
 Asia-Pacific in-Game Advertising Market | 2026-2036
Asia-Pacific in-Game Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific in-Game Advertising Market Analytics
India's PLI scheme for electronics manufacturing is realigning hardware availability for in-game advertising across the Asia-Pacific region. Unity Technologies leverages its engine dominance to sustain embedded ad network reach across mobile and console platforms. InMobi anchors demand through its programmatic supply-side platform specialized in emerging market inventory. Digital Turbine competes by controlling pre-installed app distribution on Android devices shipped throughout Southeast Asia.
Asia-Pacific in-game advertising encompasses dynamic and static promotional content rendered within interactive entertainment software, typically delivered via SDK integrations that support real-time ad serving, viewability tracking, and reward-based user engagement mechanics. The primary commercial purpose involves monetizing free-to-play game audiences while offering brands immersive, non-interruptive exposure formats. Video ads command premium inventory rates across casual games due to completion-based pricing models, while native ads within role-playing games capture sustained engagement through narrative-integrated placements. Mobile devices dominate volume as the fastest-growing device category, though VR headsets represent an emerging format channel with concentrated developer investment.
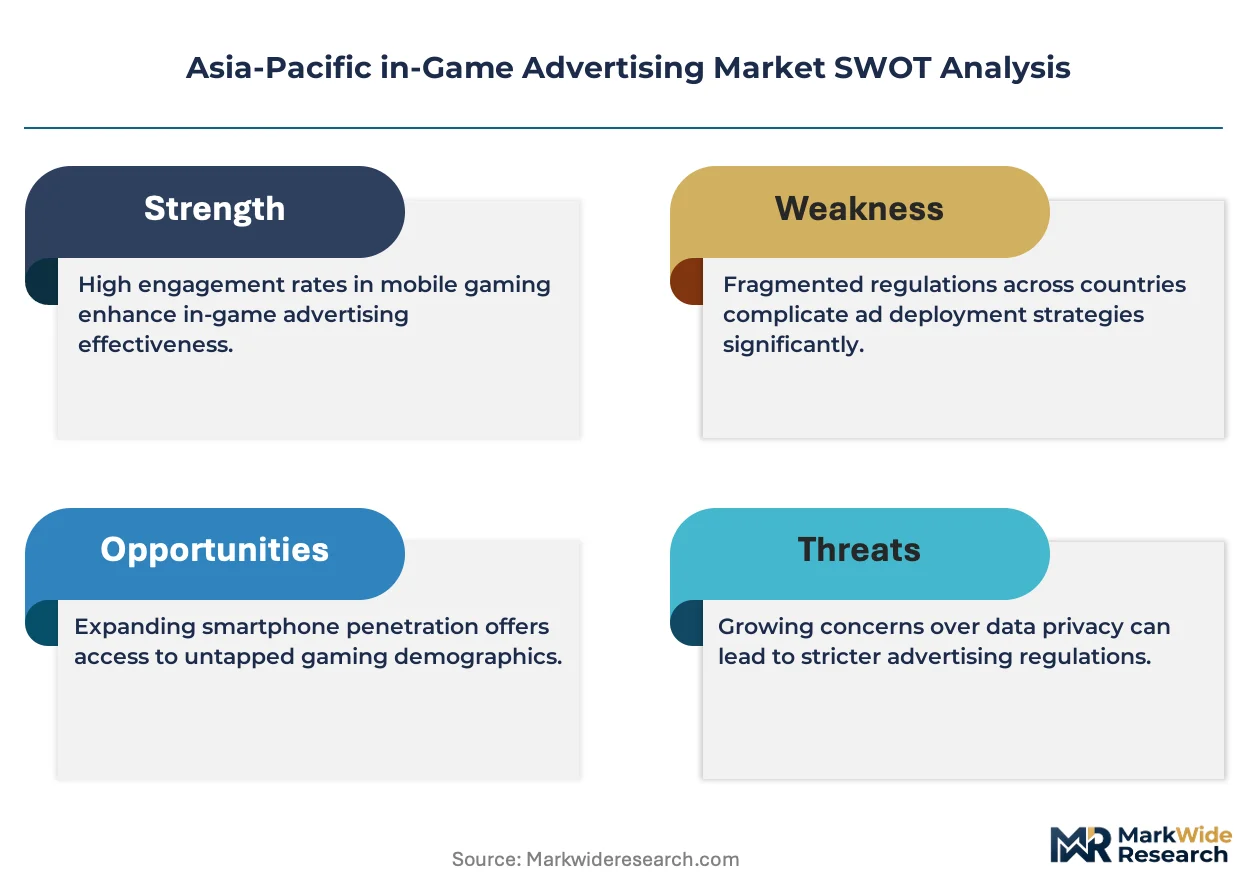
TRAI's digital advertising guidelines in India, China's SAMR oversight of internet platform algorithms, and South Korea's KCC broadcasting standards collectively shape permissible ad formats, data collection practices, and disclosure requirements across the region. These frameworks restrict certain behavioral targeting methods while mandating transparency in rewarded advertising mechanics. Stakeholders must monitor evolving interpretations of personal data protection laws as they determine SDK deployment strategies and publisher partnership terms across jurisdictions.
Market Dynamics
Programmatic real-time bidding infrastructure is compressing ad inventory transaction cycles across Southeast Asian mobile gaming ecosystems, while India's domestic smartphone manufacturing expansion under PLI schemes reshapes device accessibility for advertisers targeting tier-two urban cohorts.
Growth Catalysts
- 5G network densification:Reduced latency in South Korea and Singapore enables sub-100-millisecond ad auction completion, supporting dynamic creative optimization during live esports broadcasts.
- TRAI digital advertising guidelines:India's transparency mandates for rewarded video mechanics build advertiser trust in disclosure-compliant inventory, accelerating brand safety budget allocation.
- Esports tournament commercialization:Sponsorship integration into competitive gaming titles in South Korea creates native inventory formats with completion rates exceeding conventional interstitials.
Market Restraints
- Data localization requirements:China's SAMR oversight of cross-border data flows forces redundant SDK infrastructure deployment, elevating compliance architecture costs for multi-territory campaigns.
- Device fragmentation:India's entry-level Android ecosystem spans chipsets from MediaTek, Unisoc, and Qualcomm with divergent rendering capabilities, complicating playable ad creative standardization.
- Attention economy saturation:Casual game session lengths in Indonesia and Philippines compress below four minutes, constraining mid-roll video placement windows without disrupting retention metrics.
Strategic Opportunities
- Vietnam's underpenetrated RPG segment:Narrative-integrated native placements remain scarce in turn-based mobile titles, offering first-mover positioning for story-driven brand partnerships.
- Cloud gaming infrastructure:Convergence of 5G edge computing with subscription streaming services enables server-side rendered ad insertion immune to client-side blocking.
- Australia's TGA-aligned wellness gaming:Therapeutic game applications create compliant inventory channels for pharmaceutical advertisers navigating strict healthcare promotion codes.
Industry Challenges
- SKAdNetwork attribution complexity:Apple's privacy-preserving measurement framework fragments conversion visibility across iOS inventory, forcing probabilistic modeling investments that degrade campaign optimization precision.
- Cross-platform identity resolution:Fragmented device graphs spanning mobile, console, and emerging VR headsets complicate frequency capping and sequential messaging orchestration for unified brand narratives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific in-Game Advertising Market |
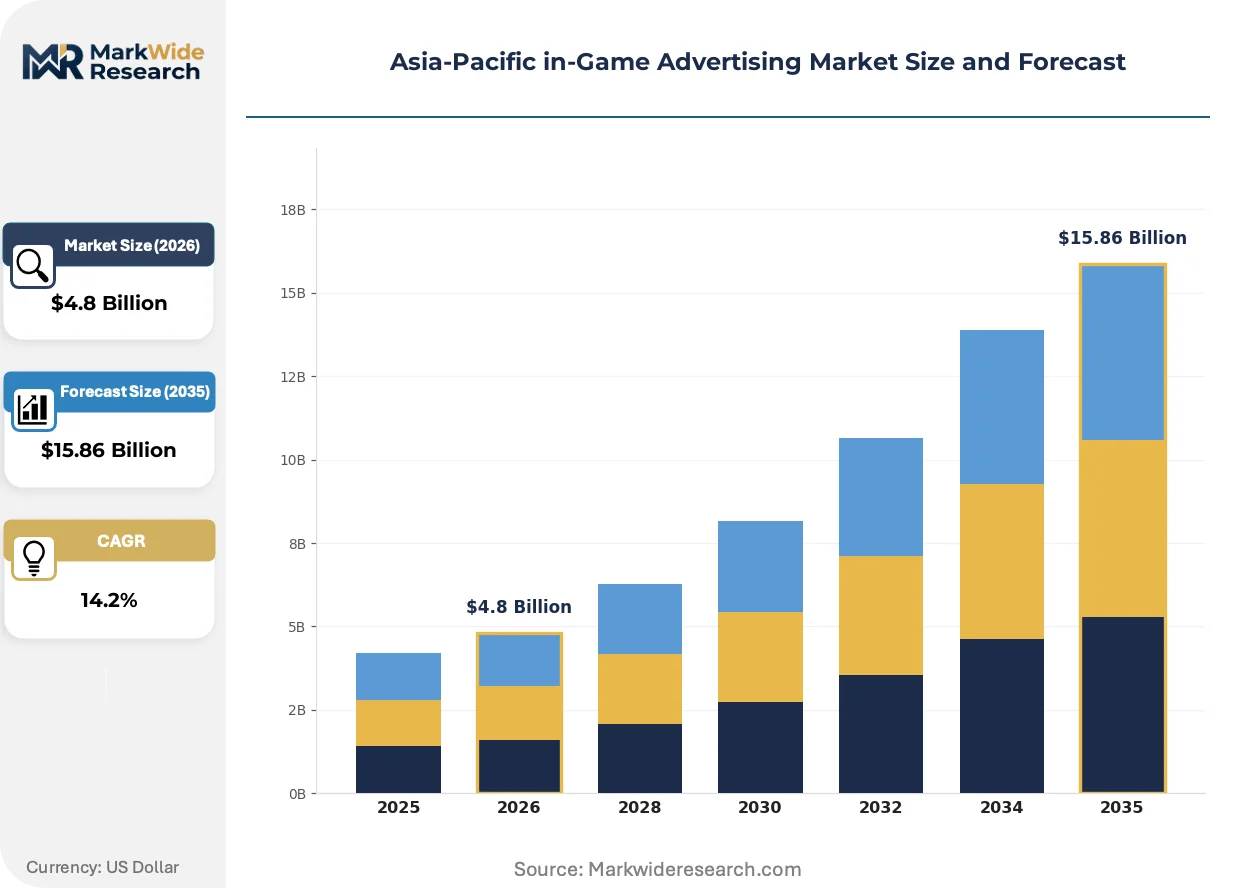
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ad Format: Video Ads, Banner Ads, Native Ads, Sponsored Content Game Type: Casual Games, Action Games, Role-Playing Games, Simulation Games Device Type: Mobile Devices, Consoles, PCs, VR Headsets Monetization Strategy: In-App Purchases, Subscription Model, Freemium Model, Ad-Supported |
| Companies Covered | InMobi, Aarki, Unity Technologies, ironSource, Chartboost, Vungle, Playwire, Digital Turbine, Motive Interactive, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific in-Game Advertising Market Evolving Landscape
Artificial intelligence is restructuring creative production pipelines and measurement methodologies across Asia-Pacific in-game advertising, compressing the gap between impression delivery and performance verification while enabling dynamic personalization at scale.
Generative AI for playable ad creation is converging with automated quality assurance testing, reducing prototype development from weeks to hours. Mid-size studios in Thailand and Malaysia adopt these tools to compete with established creative agencies. The structural consequence is flattening production cost curves that previously favored publishers with captive design resources.
South Korea's KCC broadcasting standards for algorithmic transparency now extend to in-game promotional content, mandating disclosure when recommendation engines prioritize sponsored placements. Publishers operating competitive titles must architect separate ranking logic for organic versus commercial content. Esports platforms with integrated marketplaces face the steepest compliance reconfiguration timelines.
Rewarded advertising mechanics are displacing forced interstitial formats as the dominant monetization layer in Southeast Asian hyper-casual games. Publishers in Vietnam and Indonesia now structure entire session economies around opt-in video consumption rather than interruptive displays. This behavioral pivot concentrates inventory value in completion-verified metrics rather than impression-based pricing.
Asia-Pacific in-Game Advertising Market Segmentation
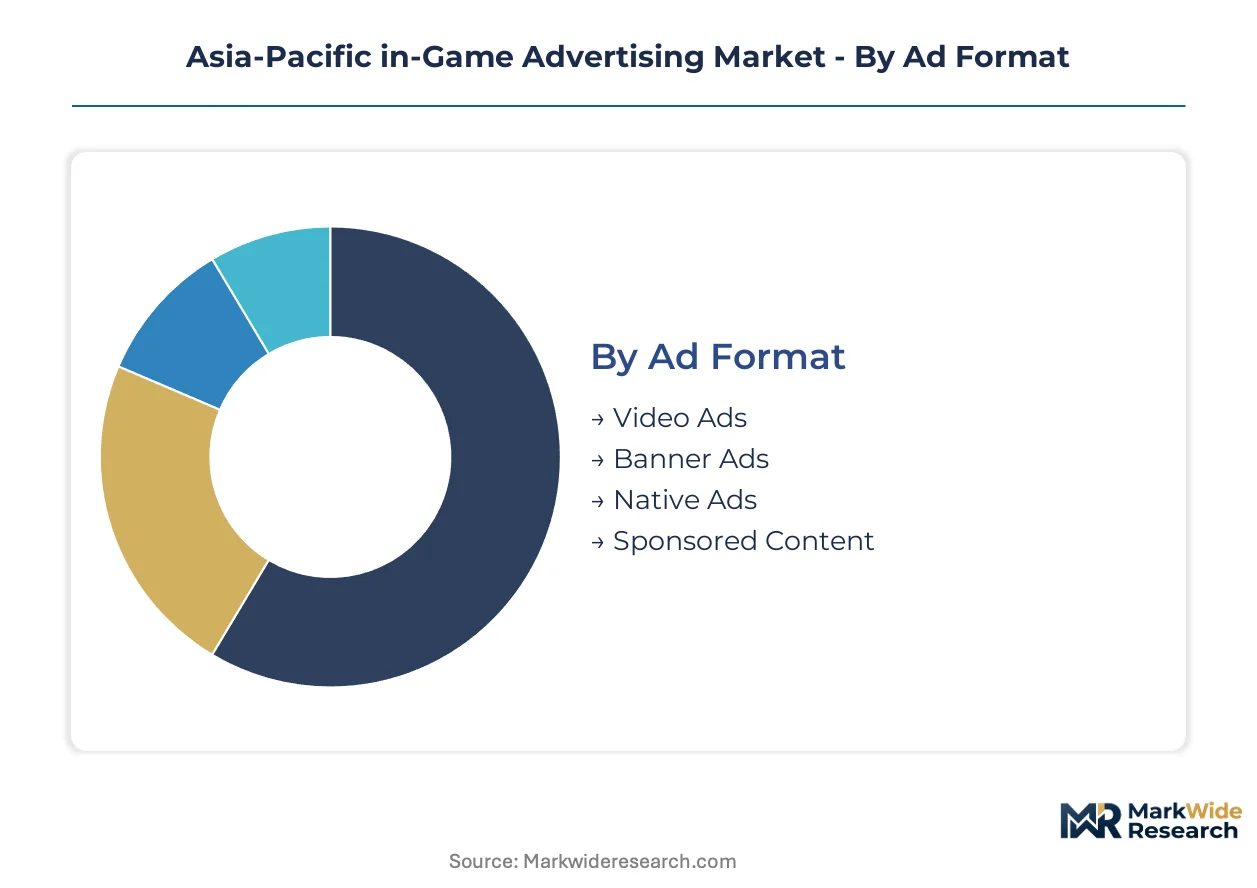
Advertisers in the Asia-Pacific in-game advertising market prioritize format compatibility with device rendering capabilities and session duration patterns. Segmentation reveals how inventory value concentrates in completion-verified video placements across mobile ecosystems while emerging formats reshape competitive positioning.
Ad Format:
Brand safety budgets flow toward formats offering viewability verification and user opt-in mechanics.
- Video Ads:Completion-based pricing models dominate premium inventory allocation. South Korean esports broadcasts and Southeast Asian casual game sessions drive demand for skippable and rewarded video units with sub-100-millisecond auction completion.
- Native Ads:Narrative-integrated placements within role-playing game environments capture sustained engagement. Vietnam's underpenetrated turn-based mobile titles present first-mover positioning for story-driven brand partnerships.
- Banner Ads:Static display units retain utility in entry-level Android devices across India's tier-two urban cohorts where rendering constraints limit rich media execution.
- Sponsored Content:Deep integration into game economies and character customization systems commands premium rates from lifestyle and automotive advertisers targeting completionist player segments.
Video ads lead on scale; native ads lead on momentum.
Game Type:
Session length variability determines placement window viability and creative format selection.
- Casual Games:Hyper-casual titles in Indonesia and Philippines compress session lengths below four minutes, constraining mid-roll video placement without retention disruption. Rewarded advertising mechanics now structure entire session economies around opt-in video consumption.
- Role-Playing Games:Extended engagement cycles enable sequential messaging and narrative-integrated brand partnerships. South Korean mobile RPGs demonstrate highest average revenue per user for sponsored content integration.
- Action Games:Competitive multiplayer environments in India and Australia support esports sponsorship overlays and dynamic branded asset insertion during live tournament broadcasts.
- Simulation Games:Life-simulation and vehicle-simulation genres in Japan and Australia attract automotive and consumer goods advertisers seeking contextual relevance through virtual product placement.
Casual games dominate volume throughput; role-playing games dominate monetization depth.
Device Type:
5G network densification and domestic manufacturing expansion reshape addressable device bases.
- Mobile Devices:India's PLI scheme for electronics manufacturing accelerates domestic smartphone production, expanding inventory access for advertisers targeting price-sensitive cohorts. Programmatic supply-side platforms specialize in emerging market mobile inventory.
- VR Headsets:Concentrated developer investment in South Korea and Japan positions immersive advertising as an emerging format channel with server-side rendered insertion capabilities.
- Consoles:Premium household penetration in Australia and Japan supports high-definition video advertising with deterministic attribution through platform-native measurement frameworks.
- PCs:Browser-based and client-based gaming in Southeast Asian internet cafes sustains display and video inventory for mass-market brand awareness campaigns.
Mobile devices anchor volume expansion; VR headsets climb the fastest.
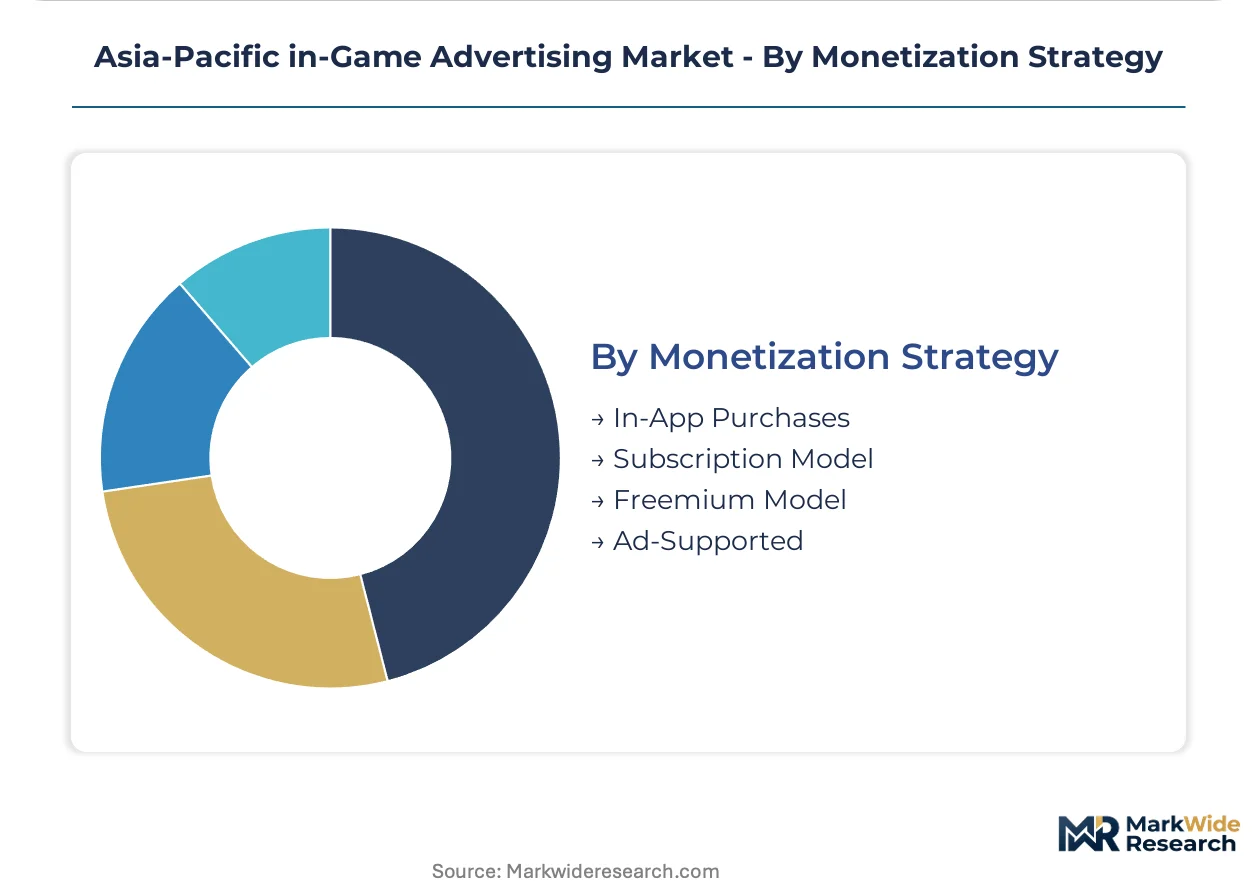
Monetization Strategy:
Publisher revenue model selection determines ad load tolerance and user segment accessibility.
- Freemium Model:Hybrid revenue streams combining in-app purchases with opt-in advertising dominate Southeast Asian market structure. Publishers balance conversion funnel optimization with rewarded video placement density.
- Ad-Supported:Pure advertising dependency in hyper-casual games concentrates inventory value in completion-verified metrics rather than impression-based pricing across Vietnam and Indonesia.
- In-App Purchases:Whales and dolphins in South Korean and Japanese RPGs subsidize ad-free experiences for non-paying users, creating segmented inventory access.
- Subscription Model:Cloud gaming services in Singapore and Australia explore server-side ad insertion immune to client-side blocking as a supplementary revenue layer.
Freemium models lead on publisher adoption; ad-supported strategies gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Developer talent clusters in Seoul, Bangalore, and Ho Chi Minh City anchor regional production capacity for ad-tech middleware and playable creative tooling. These workforce concentrations attract venture deployment for SDK engineering and programmatic infrastructure buildout.
South Korea
Esports tournament viewership exceeding conventional sports broadcasts drives brand sponsorship integrations into competitive gaming titles. The Korea Communications Commission mandates algorithmic transparency for recommendation engines prioritizing sponsored placements. Seoul-based publishers operating competitive titles architect separate ranking logic for organic versus commercial content.
India
Domestic smartphone manufacturing expansion under the Production-Linked Incentive scheme reshapes device accessibility for advertisers targeting tier-two urban cohorts. TRAI's digital advertising guidelines enforce transparency mandates for rewarded video mechanics. Bangalore's developer ecosystem concentrates SDK engineering talent for programmatic supply-side platforms.
China
Cloud gaming infrastructure convergence with 5G edge computing enables server-side rendered ad insertion immune to client-side blocking. The State Administration for Market Regulation oversees cross-border data flows, forcing redundant SDK infrastructure deployment. Shenzhen's hardware manufacturing corridor supplies chipsets and rendering components for entry-level Android devices.
Vietnam
Narrative-integrated native placements remain scarce in turn-based mobile RPGs, offering first-mover positioning for story-driven brand partnerships. The Ministry of Information and Communications regulates digital content distribution and advertising disclosure standards. Ho Chi Minh City's game development studios adopt generative AI tooling for playable ad creation, compressing prototype development cycles.
Australia
Therapeutic game applications create compliant inventory channels for pharmaceutical advertisers navigating strict healthcare promotion codes aligned with the Therapeutic Goods Administration. Privacy-preserving measurement frameworks fragment conversion visibility, forcing probabilistic modeling investments. Sydney and Melbourne concentrate cloud gaming service operations exploring subscription-supported ad insertion models.
Asia-Pacific in-Game Advertising Market Competitive Landscape
Capital-heavy producers with captive ad networks compete with asset-light middleware providers licensing SDK access across publisher portfolios. The market structure concentrates around three to five vertically integrated platforms controlling demand-side and supply-side infrastructure simultaneously. Two strategic archetypes dominate: engine-embedded networks leveraging rendering pipeline access, and programmatic specialists aggregating fragmented emerging-market inventory. Competitive moves center on pre-installed app distribution partnerships and server-side ad insertion technology licensing.
Among Asia-Pacific-based programmatic platforms, InMobi occupies a position exemplifying supply-side specialization in emerging market mobile inventory. Unity Technologies represents the engine-embedded archetype, leveraging rendering pipeline dominance to sustain network reach across mobile and console deployments. Digital Turbine sits within the distribution-control tier, anchoring pre-installed app monetization on Android devices shipped throughout Southeast Asia.
| Leading Market Players |
|---|
| InMobi |
| Aarki |
| Unity Technologies |
| ironSource |
| Chartboost |
| Vungle |
| Playwire |
| Digital Turbine |
| Motive Interactive |
| Others |
Value Network & Pricing Analysis
Server-side ad insertion technology is compressing cost economics for cloud gaming infrastructure while concentrating rendering pipeline control among engine-embedded networks with captive SDK access across Southeast Asian publisher portfolios.
Pricing Analysis
Completion-verified pricing models for rewarded video inventory dominate premium allocation across South Korean esports broadcasts and Southeast Asian casual gaming sessions. Price differentiation hinges on viewability certification tiers and real-time bidding latency guarantees under 100 milliseconds. Pricing pressure stems from programmatic infrastructure commoditization compressing intermediary margins. Hyper-casual publishers in Indonesia and Vietnam exhibit highest price sensitivity due to pure ad-supported revenue dependency, while South Korean RPG studios command premium rates for narrative-integrated sponsorships.
Supply Chain Analysis
Single-source vulnerability sits with Unity Technologies' rendering pipeline dominance across mobile and console SDK deployments. Supply concentrates in South Korea for esports tournament infrastructure, India for PLI-accelerated smartphone manufacturing, and China for cloud gaming edge computing hardware. Raw material dependencies span 5G chipset components from MediaTek and Qualcomm, ad-serving server capacity, and generative AI compute resources. Tariff exposure on cross-border data flows under China's SAMR oversight elevates redundant infrastructure costs. Distribution runs through programmatic supply-side platforms aggregating fragmented publisher inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where advertiser budgets pivot toward premium inventory with deterministic attribution and brand safety certification.
For Market Incumbents: Cement network effects by deepening SDK integration into Unity's rendering pipeline and acquiring generative AI creative tooling startups in Thailand and Malaysia. Engine-embedded positioning defends against programmatic commoditization. Vertical integration into server-side ad insertion technology preserves margin structure as client-side blocking proliferates. For New Entrants and Emerging Players: Enter via Vietnam's underpenetrated turn-based RPG segment where narrative-integrated native placements remain scarce. Ho Chi Minh City developer clusters offer accessible talent pools for playable ad creation. Cloud gaming infrastructure partnerships in Singapore and Australia provide white-space distribution channels immune to established mobile ad network saturation. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier programmatic platforms because SKAdNetwork attribution complexity fragments conversion visibility and rewards scale-based probabilistic modeling investments. Target supply-side specialists with emerging market mobile inventory concentration. Watch Apple's privacy framework evolution as the signal for iOS inventory valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Server-Side Ad Insertion Licensing | Cloud gaming services in Singapore deploy immune-to-blocking revenue layers. |
| Generative AI Creative Acquisition | Thai and Malaysian studios compress playable ad prototyping from weeks to hours. |
| Esports Tournament Sponsorship Integration | South Korean KCC mandates separate ranking logic for commercial content. |
| Pre-Installed App Distribution Partnership | Android OEMs in Southeast Asia anchor monetization before user acquisition. |
| 5G Edge Computing Infrastructure Buildout | Reduced latency enables sub-100-millisecond programmatic auction completion. |
Research Methodology
Multiple input streams — primary interviews with mobile game publishers, programmatic platform executives, and brand media buyers, plus secondary validation through TRAI regulatory filings, SAMR algorithmic transparency notices, and KCC broadcasting standards — were reconciled using bottom-up inventory sizing and top-down advertiser spend analysis. Stakeholder consultations spanned SDK engineering leads in Bangalore, esports tournament operators in Seoul, and cloud gaming infrastructure architects in Sydney. Secondary sources included App Annie mobile game revenue data, hyperscaler capex disclosures for edge computing deployment, and venture funding databases tracking ad-tech middleware investments.
Historical growth patterns were cross-referenced against panel inputs from demand-side and supply-side platform executives to derive trajectory assumptions across the analysis window. Segmentation modeling incorporated ad format type, game genre session characteristics, device rendering capabilities, and monetization strategy hybridity. CAGRs were computed from reconciled value estimates incorporating 5G penetration curves, PLI scheme smartphone production forecasts, and esports viewership projections without year-specific anchoring.
Inputs from primary fieldwork and disclosed regulatory frameworks were available through the study window; gaps in real-time bidding transaction-level data and SKAdNetwork conversion pathway visibility introduce uncertainty bands around iOS inventory valuation. Forecasts reflect documented assumptions regarding privacy framework evolution and cloud gaming subscriber conversion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
GCC Gaming Headsets Market
Gaming
United Kingdom Online Gambling Market
Gaming
South Korea Gaming Peripherals Market
Gaming
VR Melee Games Market
Gaming
Global Esports Market
Gaming
North America Gaming Market
Gaming
Playstation Network (PSN) Market
Gaming
India Gaming Market
Gaming
RPG Games Market
Gaming
Europe Video Game Software Market
Gaming
Germany Gaming Headset Market
Gaming
Online Casual Games Market
Gaming
Console Games Market
Gaming
Serious Games Market
Gaming
Social Gaming Market
Gaming
Connected Game Console Market