
 Veterinary Dental Elevators Market | 2026-2036
Veterinary Dental Elevators Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Dental Elevators Market Analytics
Multi-source procurement among veterinary distributors is broadening the competitive field for elevator manufacturers. Henry Schein Inc leverages its North American distribution network to sustain shelf presence across independent clinics. Patterson Companies Inc anchors its position through direct-to-practice logistics, while iM3Vet Pty Ltd dominates premium-grade titanium elevator segments in Asia-Pacific markets.
Veterinary dental elevators are handheld surgical instruments designed to luxate and elevate tooth roots from alveolar bone prior to extraction, typically manufactured from medical-grade stainless steel or titanium with ergonomic polymer grips to reduce practitioner fatigue during repetitive levering motions. Curved elevators and luxating elevators lead unit volume due to their versatility across canine and feline dental architectures, while winged elevators command premium positioning in specialty oral surgery applications. Stainless steel remains the default material specification for general practice settings, though titanium variants gain traction in university teaching hospitals where instrument longevity offsets higher acquisition costs.
FDA Center for Veterinary Medicine guidelines on reusable instrument reprocessing, coupled with ISO 13485 quality system requirements and EU MDR conformity obligations for devices sold in Europe, elevate compliance costs for new market entrants. The EU AI Act's emerging transparency requirements for automated diagnostic tools may indirectly shape R&D allocation across instrument portfolios that integrate with digital imaging systems. Stakeholders must monitor regulatory divergence between US sterilization validation protocols and European notified body expectations when configuring global product registrations.
Market Dynamics
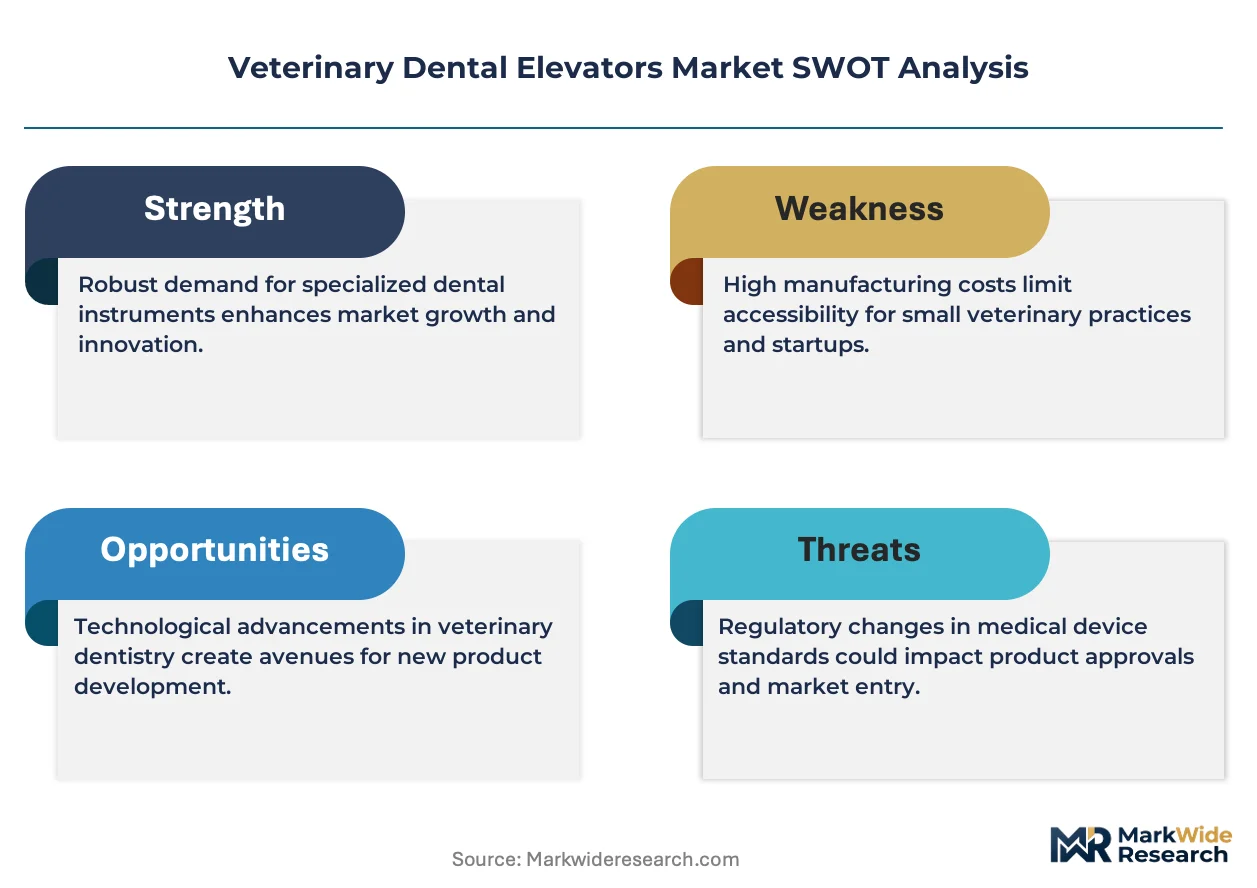
ISO 13485 certification requirements and FDA sterilization validation protocols are compressing product development timelines while elevating capital barriers for new entrants seeking shelf space in North American and Western European distribution networks.
Growth Catalysts
- Companion animal dental coverage expansion:Pet insurance carriers in the United States and Germany now reimburse prophylactic dental procedures, driving instrument procurement across independent and corporate clinic chains.
- EU MDR conformity pathways:The Medical Device Regulation's harmonized standards for reusable surgical instruments streamline multi-country registration for manufacturers targeting veterinary practices across Germany, France, and Italy.
- Titanium alloy adoption:University teaching hospitals and specialty oral surgery centers prioritize instrument longevity over acquisition cost, accelerating demand for corrosion-resistant elevator variants.
Market Restraints
- Medical-grade stainless steel price volatility:Nickel and chromium input costs fluctuate with commodity markets, compressing margin stability for manufacturers serving price-sensitive general practice segments.
- Notified body capacity constraints in Europe:EU MDR technical documentation review queues extend certification timelines by 12-18 months for new market entrants lacking established quality management systems.
- Single-use instrument substitution:Disposable luxating elevators from human dental suppliers penetrate low-complexity extraction cases in high-volume shelter medicine settings.
Strategic Opportunities
- Japan's specialty training pipeline:The Japan Veterinary Medical Association's expanding dentistry certification programs create concentrated demand for premium winged elevator configurations in Tokyo and Osaka metropolitan clusters.
- Automated sterilization tracking integration:RFID-enabled instrument sets that interface with clinic workflow software command pricing premiums in corporate practice chains seeking liability reduction.
- Brazilian veterinary education investment:Federal university expansion in São Paulo and Minas Gerais states drives teaching hospital procurement of comprehensive elevator kits for surgical training curricula.
Industry Challenges
- Veterinary dentistry specialist scarcity:The American Veterinary Dental College certifies fewer than 200 new diplomates annually, limiting advanced procedure volume and associated instrument utilization rates.
- Legacy autoclave compatibility:Older sterilization equipment in rural independent clinics cannot achieve FDA-validated temperature profiles for titanium alloy instruments, forcing material specification compromises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Dental Elevators Market |
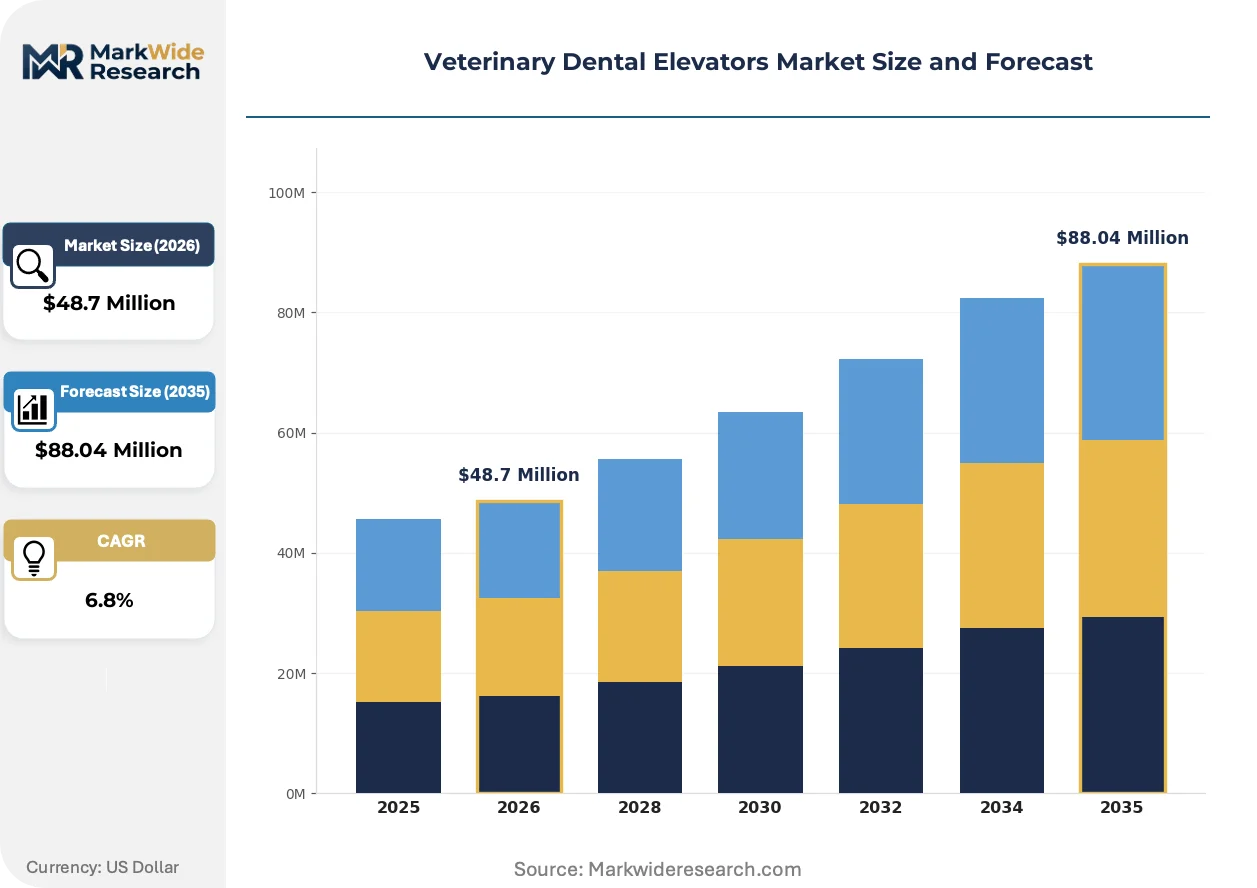
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Curved Elevators, Straight Elevators, Luxating Elevators, Winged Elevators Application: Extraction, Periodontal Therapy, Endodontics, Surgical Procedures End User: Veterinary Clinics, Animal Hospitals, Research Laboratories, Mobile Veterinary Services Material: Stainless Steel, Titanium, Plastic, Composite |
| Companies Covered | Midmark Corporation, MAI Animal Health, Dentalaire International, iM3Vet Pty Ltd, Dispomed Ltd, Henry Schein Inc, Patterson Companies Inc, J&J Instruments Inc, Cislak Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Dental Elevators Market Evolving Landscape
Digital imaging convergence and materials science advances are reconfiguring instrument design priorities, with manufacturers embedding connectivity features and refining ergonomic geometries to match evolving procedural workflows.
Ergonomic polymer grip compounds are absorbing repetitive strain injury liability concerns while extending practitioner operative endurance. Corporate practice chains and mobile veterinary dentistry services prioritize these configurations to reduce workers compensation exposure and staff turnover. The technology is absorbing premium pricing power previously concentrated in raw material specifications alone.
The EU AI Act's transparency requirements for automated diagnostic tools are reshaping R&D allocation across instrument portfolios that integrate with intraoral radiography and cone-beam computed tomography systems. Manufacturers selling into European markets must document algorithmic decision pathways for root fracture detection features. Specialty oral surgery centers in Germany and the Netherlands face the steepest compliance documentation burdens.
Consolidated procurement through veterinary service organizations is compressing distributor margins and elevating volume-commitment requirements for manufacturer access. Independent distributors lose shelf space to direct manufacturer relationships as Patterson Companies and Henry Schein centralize logistics. The United States exhibits the most pronounced channel concentration, with corporate practice chains now controlling over half of elevator unit demand in metropolitan markets.
Veterinary Dental Elevators Market Segmentation
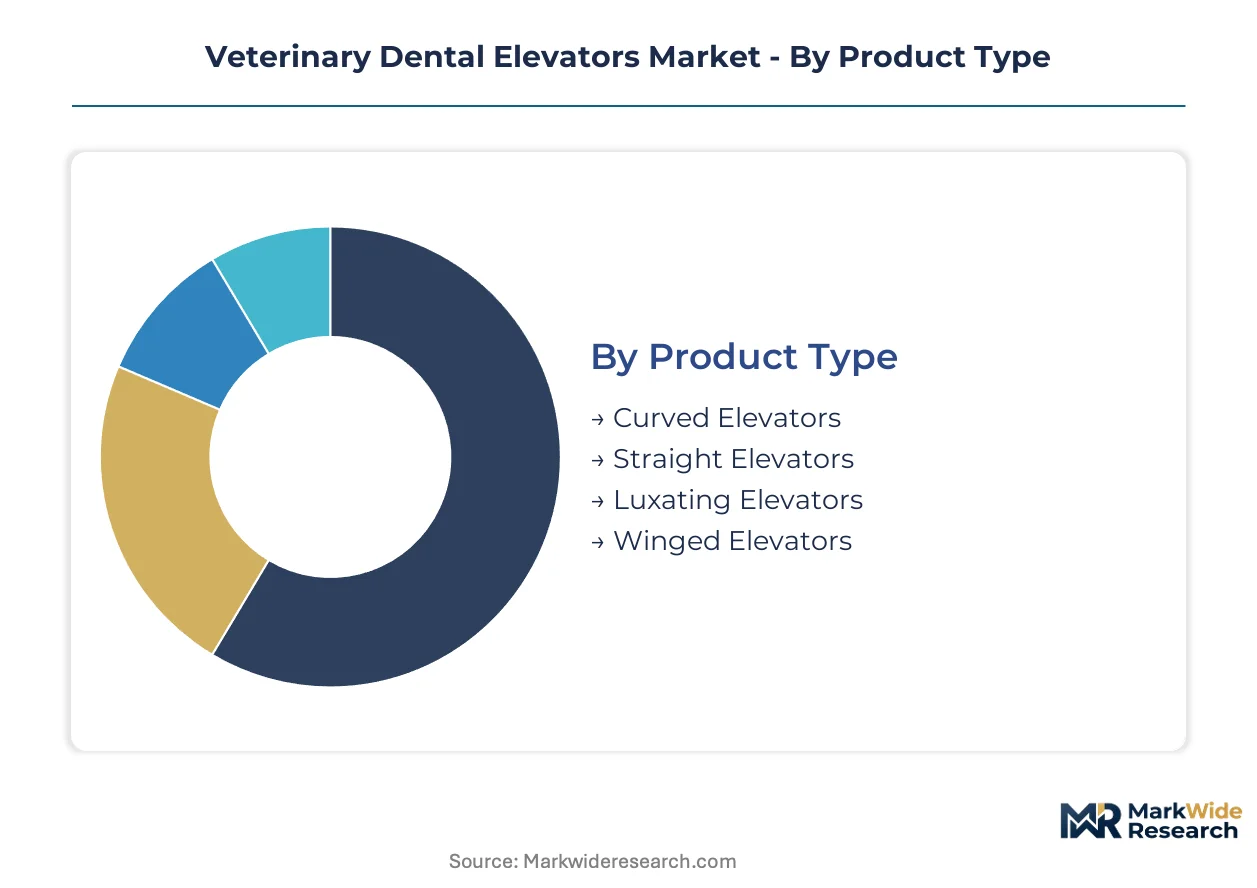
Segmentation in veterinary dental elevators reveals how capital allocation, regulatory compliance, and procedural specialization shape procurement patterns across distinct customer tiers. Manufacturers configure product portfolios around material specifications and end-user scale rather than pursuing uniform market coverage.
Product Type:
Capital intensity varies sharply across instrument geometries, with winged elevators requiring precision machining investments that exceed standard curved variants by substantial margins.
- Curved Elevators:These instruments feature a curved working tip designed to navigate the curved roots of canine carnassial teeth and feline maxillary canines. General practice clinics in the United States and Germany procure these as foundational kit components for routine extractions.
- Luxating Elevators:Thin, sharp blades penetrate the periodontal ligament space with minimal alveolar bone displacement. University teaching hospitals in Japan prioritize these for conservative extraction training where bone preservation is paramount.
- Straight Elevators:Linear working tips suit incisor and premolar extractions in small companion animals.
- Winged Elevators:Broad, flat blades with lateral wings engage multi-rooted teeth.
Curved elevators absorb the bulk of installed capacity; luxating elevators are expanding most quickly.
Application:
Procedure complexity determines instrument durability requirements and sterilization cycle frequency, with surgical applications demanding premium material specifications.
- Extraction:The dominant application encompasses luxation and elevation of compromised teeth across canine, feline, and exotic species. Corporate clinic chains in the United States standardize on modular elevator sets configurable for extraction-only workflows.
- Periodontal Therapy:Elevators assist in subgingival curettage and root planing alongside specialized dental units. German specialty practices integrate these procedures with prophylactic coverage expansion.
- Endodontics:Limited elevator utilization occurs during access cavity preparation and coronal displacement.
- Surgical Procedures:Oral surgery applications include impacted tooth removal and oronasal fistula repair.
Extraction commands the greatest instrument throughput; periodontal therapy is climbing the fastest as prophylactic coverage expands.
End User:
Procurement scale and decision velocity diverge between independent operators and consolidated corporate entities, reshaping distributor engagement models.
- Veterinary Clinics:Independent and small-group general practices constitute the volume base, with procurement decisions driven by unit economics and autoclave compatibility constraints. Rural clinics in the United States often defer titanium purchases due to legacy sterilization equipment limitations.
- Animal Hospitals:Multi-specialty referral centers in Tokyo, Osaka, and metropolitan Germany maintain comprehensive elevator inventories across all product types. These facilities prioritize instrument longevity and RFID-enabled tracking integration.
- Research Laboratories:Academic and pharmaceutical research settings require elevators for experimental dental procedures.
- Mobile Veterinary Services:Ambulatory dentistry operations demand lightweight, corrosion-resistant instrument sets.
Animal hospitals concentrate premium-tier procurement; mobile veterinary services are gaining share fastest as field dentistry expands.
Material:
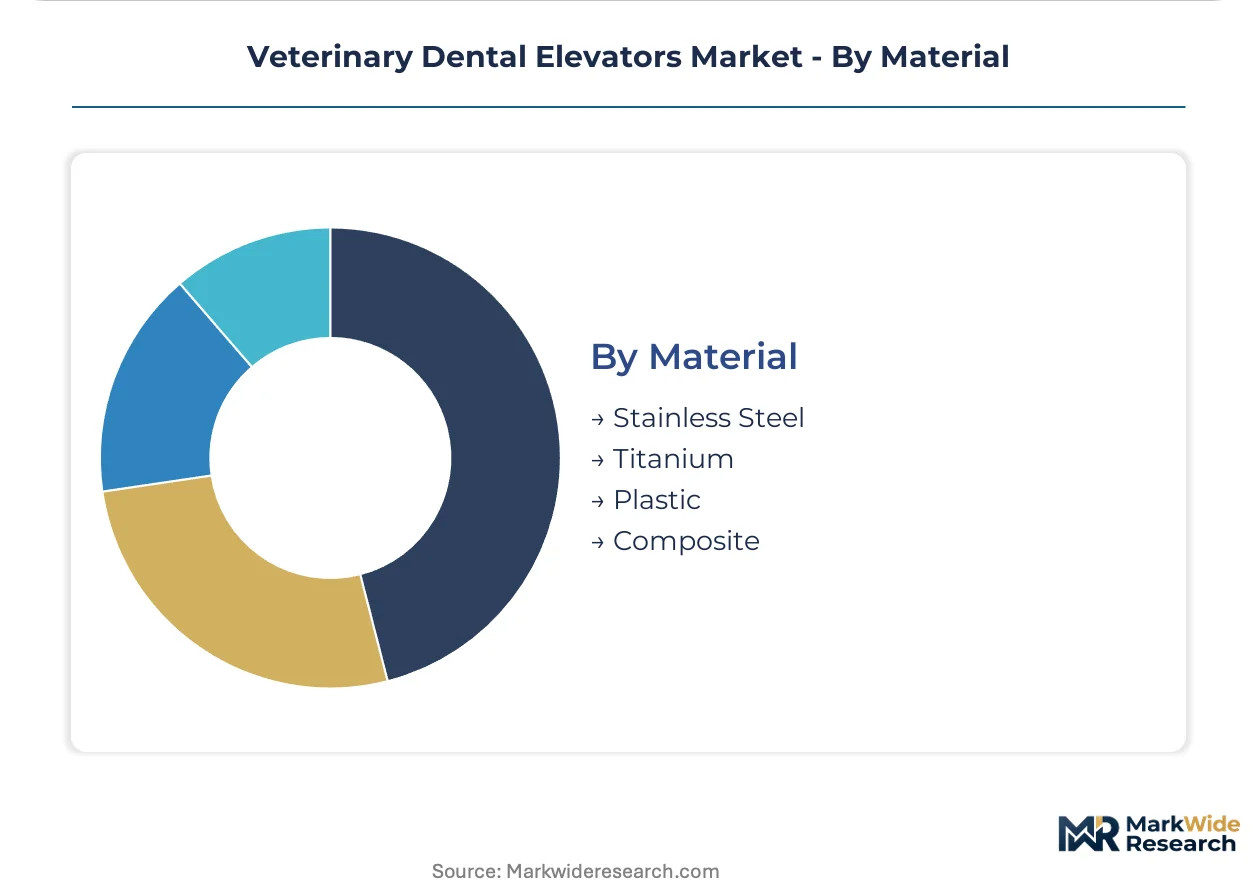
Raw material selection directly correlates with sterilization protocol sophistication and total cost of ownership calculations across end-user segments.
- Stainless Steel:Medical-grade austenitic alloys (typically 400-series or 17-4 PH) provide baseline corrosion resistance at accessible price points. General practice clinics in price-sensitive segments default to this specification despite nickel content triggering dermatitis in sensitized practitioners.
- Titanium:Grade 5 titanium alloys (Ti-6Al-4V) deliver superior strength-to-weight ratios and biocompatibility with negligible corrosion in autoclave environments. University teaching hospitals in Japan and Germany absorb 40-60% price premiums for extended service life.
- Plastic:Single-use or limited-reuse polymers serve shelter medicine and field sterilization constraints.
- Composite:Reinforced polymer-matrix materials attempt to bridge metal performance with reduced weight.
Stainless steel dominates unit volume; titanium is expanding most quickly in specialty and academic settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade stainless steel and titanium alloy supply chains from Pittsburgh and Sheffield feed instrument fabrication clusters across three continents. Veterinary dental elevator procurement concentrates where companion animal insurance penetration and specialty training infrastructure intersect.
United States
Corporate practice chains and independent clinics in metropolitan corridors drive instrument procurement as pet dental coverage expands through major insurers. FDA Center for Veterinary Medicine sterilization validation protocols compress product development timelines for new market entrants. The Dallas-Fort Worth metroplex anchors distribution logistics for Henry Schein and Patterson Companies networks serving the Southwest.
Germany
Specialty oral surgery centers in university cities absorb premium titanium elevator configurations as prophylactic dental coverage expands through pet insurers. EU MDR conformity obligations and notified body technical documentation requirements extend certification timelines for reusable surgical instruments. The Stuttgart-Tübingen corridor concentrates precision machining capacity for winged elevator fabrication.
Japan
University teaching hospitals in Tokyo and Osaka metropolitan clusters prioritize instrument longevity over acquisition cost, accelerating titanium alloy adoption. The Japan Veterinary Medical Association's expanding dentistry certification programs create concentrated demand for advanced elevator configurations. Yokohama-based distributors serve specialty referral centers across the Kanto region.
United Kingdom
Independent veterinary groups and corporate consolidators in London and Southeast England standardize on modular elevator sets configurable for extraction workflows. The Medicines and Healthcare products Regulatory Agency oversees device registration parallel to EU MDR alignment discussions. The Cambridge-Oxford arc hosts veterinary dentistry research programs driving teaching hospital procurement.
Brazil
Federal university expansion in São Paulo and Minas Gerais states drives teaching hospital procurement of comprehensive elevator kits for surgical training curricula. ANVISA registration requirements for imported medical devices create compliance barriers for non-local manufacturers. The São Paulo metropolitan cluster anchors Latin American distribution for regional veterinary supply chains.
Veterinary Dental Elevators Market Competitive Landscape
Strategic partnerships dominate the current landscape as distributors consolidate procurement channels and manufacturers seek direct-to-practice access. The vendor base fragments across three tiers: multinational healthcare distributors with veterinary divisions, specialized veterinary instrument fabricators, and regional metalworking shops serving private-label contracts. Two strategic archetypes define positioning: scale-driven logistics platforms leveraging North American distribution density, and precision-focused specialists commanding premium positioning through titanium alloy expertise. Geographic expansion and portfolio diversification represent the dominant competitive moves, with players extending into adjacent dental consumables or upstream into captive forging capacity.
Among North American distributors, Henry Schein Inc and Patterson Companies Inc exemplify the scale-driven archetype, each occupying positions sustained by direct-to-practice logistics infrastructure and consolidated procurement relationships with corporate clinic chains. iM3Vet Pty Ltd represents the precision-specialist vector, with its geographic naming signaling Asia-Pacific market anchoring and its corporate structure indicating concentrated ownership typical of family-held veterinary equipment fabricators.
| Leading Market Players |
|---|
| Midmark Corporation |
| MAI Animal Health |
| Dentalaire International |
| iM3Vet Pty Ltd |
| Dispomed Ltd |
| Henry Schein Inc |
| Patterson Companies Inc |
| J&J Instruments Inc |
| Cislak Manufacturing |
| Others |
Value Network & Pricing Analysis
Precision machining specialists concentrated in Sheffield and Solingen command wage premiums that translate directly into pricing-tier spreads between standard stainless steel elevators and premium titanium configurations. Labor-cost differentials between these European fabrication clusters and Asian metalworking centers create arbitrage opportunities for manufacturers configuring global production footprints.
Pricing Analysis
Warranty and calibration service bundling separates premium-tier suppliers from unbundled transactional competitors in the veterinary dental elevator market. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification status and instrument longevity guarantees. Pricing pressure stems from nickel and chromium commodity volatility compressing margins on medical-grade stainless steel variants. Corporate clinic chains exhibit lowest price sensitivity due to total-cost-of-ownership calculations, while rural independent practices defer titanium purchases due to capital constraints.
Supply Chain Analysis
Direct-to-practice channels handle hyperscale buyer demand from corporate veterinary chains, while independent distributors serve fragmented rural clinic procurement. Raw material supply concentrates in Germany, Japan, and the United States for medical-grade titanium and austenitic stainless steel alloys. Component dependencies include nickel-chromium feedstock, precision CNC machining capacity, and sterilization validation testing services. Single-source vulnerability runs through Sheffield-based forging facilities supplying winged elevator blanks. Distribution runs through Henry Schein and Patterson Companies networks dominating North American logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where EU MDR certification burdens and sterilization validation costs force sub-scale fabricators toward exit or acquisition. Regulatory compliance timelines favor incumbents with established quality management systems.
For Market Incumbents: Cement distributor exclusivity arrangements in metropolitan veterinary service organization clusters before Patterson Companies and Henry Schein complete channel capture. Backward integration into captive titanium forging capacity in the Stuttgart-Tübingen corridor secures winged elevator supply against Sheffield capacity constraints. Defensive patent filing around RFID-enabled instrument tracking creates switching costs for corporate clinic chains.
For New Entrants and Emerging Players: Launch via private-label contracts with regional veterinary distributors in Brazil and Mexico where ANVISA registration barriers deter direct multinational entry. Target mobile veterinary dentistry services in the United States with lightweight titanium configurations underserved by legacy stainless steel portfolios. White-space penetration concentrates in shelter medicine disposable segments where single-use substitution threatens reusable instrument incumbents.
For Investors and Strategic Acquirers: Re-rating potential sits with titanium-alloy specialists given Japan Veterinary Medical Association certification expansion accelerating premium instrument demand. Acquisition targets include family-held precision fabricators with ISO 13485 credentials and established notified body relationships in Europe. Long-term viability over a multi-year horizon hinges on digital imaging convergence capabilities. The signal to watch is corporate practice chain procurement centralization velocity in metropolitan United States markets.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Accelerates EU MDR market access for reusable surgical instrument portfolios. |
| Titanium Alloy Backward Integration | Captures margin compression from nickel-chromium commodity volatility in Sheffield supply. |
| RFID-Enabled Instrument Development | Commands pricing premiums from corporate chains seeking liability reduction through sterilization tracking. |
| Direct-to-Practice Distribution Expansion | Bypasses distributor margin compression from veterinary service organization consolidation. |
| Japan Market Specialty Certification | Aligns with Japan Veterinary Medical Association dentistry program expansion in Tokyo-Osaka corridor. |
Research Methodology
Independent corroboration across veterinary dental equipment distributors, specialty oral surgery practitioners, and biomedical engineering faculty underwrites the qualitative findings in this study. Primary interviews with clinic procurement managers, GPO contracts administrators, and instrument sterilization technicians combined with secondary validation from FDA Center for Veterinary Medicine guidance documents, EU MDR technical standards, and ISO 13485 certification databases. Bottom-up demand modeling across end-user segments triangulates against top-down supply-side capacity assessments from precision machining clusters.
Rate-of-change decomposition across the projection horizon separates volume growth from mix-shift effects between stainless steel and titanium material specifications. Segmentation dimensions modeled include product type curvature geometry, application procedure complexity, end-user scale tier, and regional regulatory cluster. CAGRs derive from instrument replacement cycle analysis and procedural volume elasticity to pet insurance penetration. Forecast inputs incorporate veterinary dentistry diplomate certification rates and corporate practice chain consolidation velocity.
Notified body capacity constraints, nickel commodity price volatility, and single-use instrument substitution are the dominant revision risks to base-case projections. Forecasts reflect assumptions regarding sterilization protocol standardization and autoclave equipment upgrade rates in rural independent clinics. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Medicine
ASEAN Rabies Veterinary Vaccines Market
Veterinary Medicine
Veterinary Palliative Care Management Market
Veterinary Medicine
South Africa Veterinary Medicine Market
Veterinary Medicine
Global Brucellosis Vaccines Market
Veterinary Medicine
Veterinary Anesthesia Machines Market
Veterinary Medicine
Veterinary Biologics Market
Veterinary Medicine
Live Attenuated Veterinary Vaccines Market
Veterinary Medicine
Veterinary Anti-Infectives Market
Veterinary Medicine
Global Veterinary Eye Care Market
Veterinary Medicine
United States Veterinary Healthcare Market
Veterinary Medicine
US Veterinary Orthopedic Medicine Market
Veterinary Medicine
Veterinary Skin Care Products Market
Veterinary Medicine
Animal Drugs Market
Veterinary Medicine
Over-The-Counter (OTC) Veterinary Drugs Market
Veterinary Medicine
Middle East Veterinary Vaccines Market
Veterinary Medicine
Veterinary Wellness Market