
 US Veterinary Orthopedic Medicine Market | 2026-2036
US Veterinary Orthopedic Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
US Veterinary Orthopedic Medicine Market Insights
The US veterinary orthopedic medicine market is consolidating around a widening gap between premium implant systems and commodity surgical consumables. Zoetis Services LLC leverages its animal health distribution network to dominate biologic adjuncts alongside hardware. DePuy Synthes (Johnson & Johnson) anchors its position through human orthopedic technology transfer into veterinary applications. Arthrex Vet Systems differentiates via specialized arthroscopy portfolios designed for companion animal anatomy.
Veterinary orthopedic medicine encompasses surgical and non-surgical interventions for musculoskeletal disorders in animals, including titanium alloy bone plates with locking screw interfaces, cobalt-chromium implants, and arthroscopic visualization systems operating at 4mm sheath diameters for joint access. Its primary purpose is restoring mobility and eliminating pain in companion animals, working animals, and exotic species. Implants command the largest revenue share due to revision surgery economics and material certification requirements, while stem cell therapy represents the fastest-expanding technology segment as regenerative protocols gain veterinary college endorsement. Animal hospitals capture disproportionate margin pools relative to clinics because they consolidate imaging, surgery, and rehabilitation under single-roof referral models.
FDA Center for Veterinary Medicine regulates veterinary medical devices under enforcement discretion frameworks that shape manufacturer submission strategies, while USDA APHIS oversees biologic products including stem cell and platelet-rich plasma therapies. State veterinary medical boards enforce practice act provisions that determine whether rehabilitation services require direct veterinary supervision, creating uneven market access for equipment vendors. Stakeholders must monitor evolving FDA guidance on 3D-printed custom implants and state-level scope-of-practice expansions for veterinary technicians as these will reshape channel economics and service delivery models.
Market Dynamics
Specialty veterinary clinics are consolidating orthopedic service lines as pet owners demand advanced surgical interventions, compressing the traditional referral pathway between general practitioners and university hospitals. This structural shift is redrawing margin capture across the value chain.
Growth Catalysts
- FDA Center for Veterinary Medicine enforcement discretion frameworks:Manufacturers navigate streamlined submission pathways for implantable devices, accelerating product commercialization timelines relative to human medical device pathways.
- Stem cell therapy protocols:Veterinary colleges across California, Texas, and Florida are endorsing regenerative medicine curricula, expanding trained practitioner pools and normalizing biologic adjuncts alongside hardware.
- Companion animal population density:Metropolitan clusters in California, Texas, and Florida concentrate specialist referral networks, creating efficient demand aggregation for high-complexity procedures.
Market Restraints
- Titanium alloy supply concentration:Aerospace and human medical device manufacturers dominate qualified alloy sourcing, creating input competition that elevates veterinary implant material costs.
- USDA APHIS biologic product oversight:Stem cell and platelet-rich plasma therapies face dual jurisdiction complexity between FDA and USDA, creating submission uncertainty that delays commercialization.
- State veterinary practice act fragmentation:Rehabilitation service supervision requirements vary by state, forcing equipment vendors to maintain multiple compliance configurations and constraining uniform market access.
Strategic Opportunities
- Veterinary technician scope-of-practice expansion:State-level legislative activity in Florida and Texas is broadening technician autonomy in rehabilitation delivery, opening channel economics for equipment vendors.
- 3D-printed custom implant fabrication:FDA guidance evolution on patient-specific device manufacturing is creating regulatory tailwinds for bespoke orthopedic solutions in complex fracture reconstruction.
- Telemedicine-integrated postoperative monitoring:Remote rehabilitation oversight is converging with wearable motion sensors, enabling rural and secondary market penetration without physical specialist presence.
Industry Challenges
- Board-certified surgeon scarcity:The American College of Veterinary Surgeons fellowship pipeline produces limited annual diplomates, constraining service expansion capacity for high-volume orthopedic centers.
- Capital equipment amortization pressure:Arthroscopy towers and advanced imaging suites require substantial upfront investment, squeezing clinic cash flows during extended payback periods in competitive metropolitan markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Veterinary Orthopedic Medicine Market |
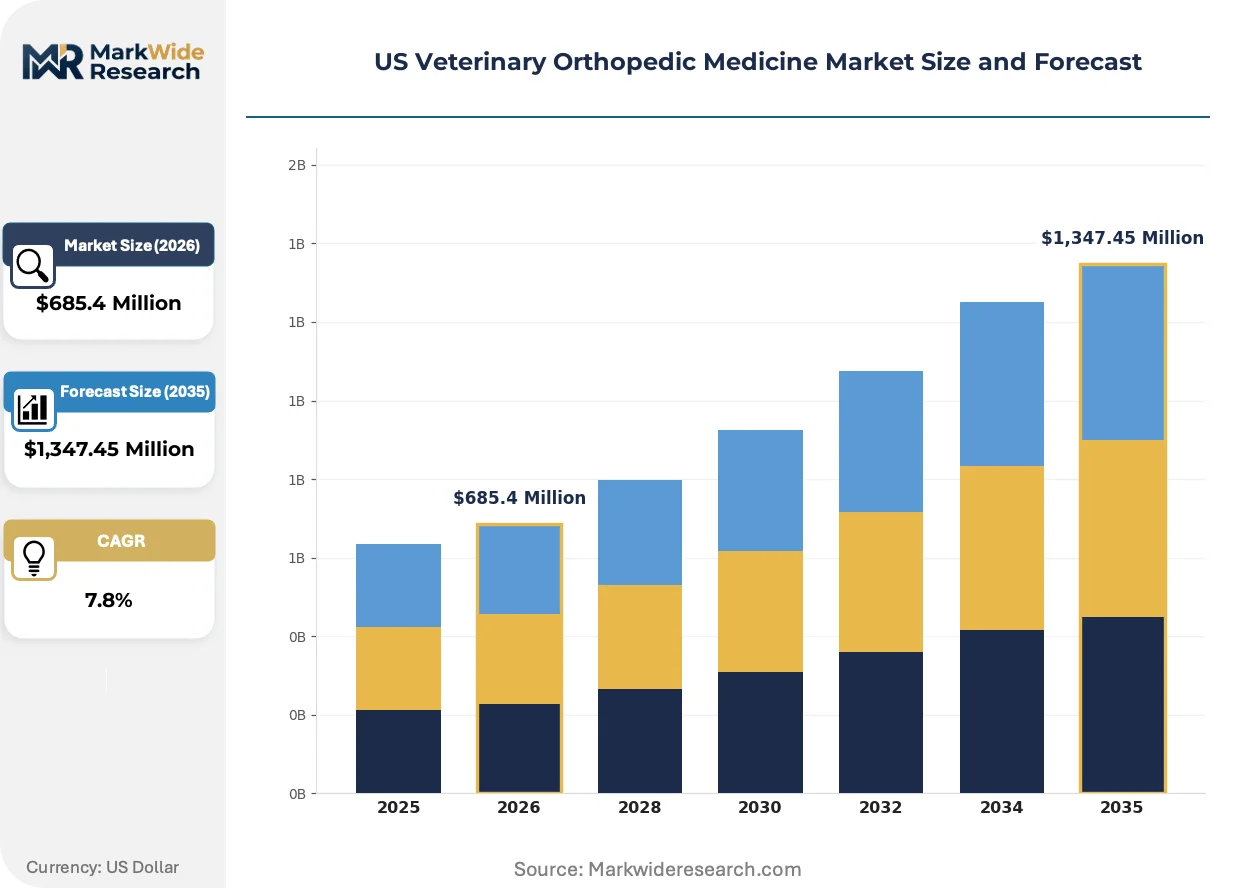
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,347.45 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Surgical Instruments, Imaging Systems, Rehabilitation Equipment Technology: Arthroscopy, Laser Therapy, Shockwave Therapy, Stem Cell Therapy End User: Veterinary Clinics, Animal Hospitals, Rehabilitation Centers, Research Institutions Application: Fractures, Ligament Injuries, Joint Surgery, Pain Management |
| Companies Covered | Zoetis Services LLC, DePuy Synthes (Johnson & Johnson), Boehringer Ingelheim International GmbH, Arthrex Vet Systems, Movora (Vimian Group), B. Braun VetCare, Elanco Animal Health, Merck Animal Health, Integra LifeSciences, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Veterinary Orthopedic Medicine Market Trends and Innovations
Point-of-care manufacturing capabilities and regenerative protocol standardization are compressing traditional supply hierarchies while elevating outcome transparency expectations among pet owners.
Patient-specific 3D-printed titanium implants are decentralizing production geography by enabling veterinary teaching hospitals to fabricate custom bone plates and joint prosthetics on-site. Academic medical centers in California and Texas are deploying in-house additive manufacturing cells, collapsing the traditional 6-8 week custom implant procurement cycle to 72-hour turnaround. This capability is decentralizing surgical planning authority from original equipment manufacturers toward institutional veterinary programs with capital deployment capacity.
FDA Center for Veterinary Medicine draft guidance on additive-manufactured medical devices is reshaping quality system requirements for custom implant producers. The framework mandates process validation documentation that mirrors human device standards, elevating compliance costs for veterinary-specific manufacturers. Smaller implant suppliers are responding by partnering with ISO 13485-certified contract manufacturers rather than building captive production facilities.
Pet owner financing platforms are displacing traditional out-of-pocket payment for orthopedic procedures, restructuring how specialty clinics package surgical and rehabilitation services. Third-party veterinary lending services are capturing referral flow by pre-qualifying owners before specialist consultation, concentrating case volume at affiliated hospital networks. This behavioral shift is most pronounced in Florida and Texas metropolitan markets where household pet expenditure exceeds national averages.
US Veterinary Orthopedic Medicine Market Segmentation
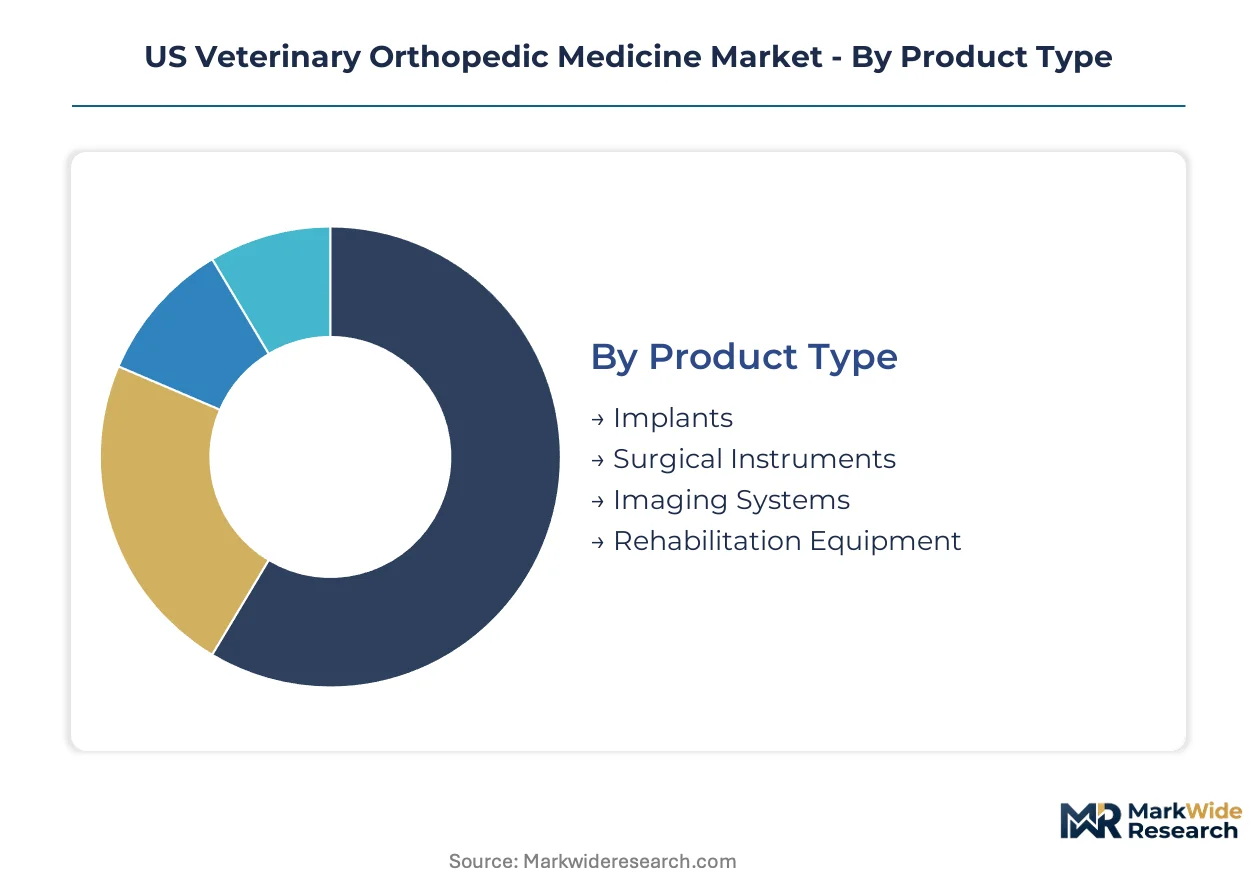
Capital allocation across product categories determines competitive positioning in US veterinary orthopedic medicine. Segment boundaries reflect distinct regulatory pathways, reimbursement structures, and technical competency requirements that shape vendor go-to-market strategies.
Product Type:
Implant systems demand the heaviest upfront capital deployment due to material certification and sterilization infrastructure requirements.
- Implants:Titanium alloy bone plates with locking screw interfaces and cobalt-chromium joint prosthetics require ISO 13485-certified manufacturing cells and FDA Center for Veterinary Medicine submission dossiers. California and Texas teaching hospitals absorb the highest volumes of premium implant systems driven by fellowship-trained surgical caseloads.
- Surgical Instruments:Precision-machined retractors, bone saws, and drill systems fabricated from surgical-grade stainless steel carry lower regulatory burdens than implants but require instrument sterilization partnerships. Demand clusters in Florida metropolitan markets where specialty clinic consolidation is compressing procurement timelines.
- Imaging Systems:Digital radiography suites and portable C-arms with veterinary-specific software configurations.
- Rehabilitation Equipment:Underwater treadmills, therapeutic laser units, and continuous passive motion devices for postoperative recovery protocols.
Most installed capacity flows through Implants. Expansion is steepest in Rehabilitation Equipment.
Technology:
Technology selection correlates directly with practitioner training depth and service pricing power across metropolitan referral networks.
- Arthroscopy:Minimally invasive joint visualization systems operating at 4mm sheath diameters enable diagnostic and therapeutic procedures through small incisions. Florida specialty clinics are deploying arthroscopy towers fastest as pet owner demand for reduced postoperative recovery times intensifies.
- Stem Cell Therapy:Autologous and allogeneic regenerative protocols require biologic processing laboratories and USDA APHIS compliance frameworks. Veterinary colleges in California and Texas are normalizing stem cell curricula, expanding trained practitioner pools beyond early-adopter academic centers.
- Laser Therapy:Class IV therapeutic lasers for tissue healing and pain modulation in outpatient settings.
- Shockwave Therapy:Extracorporeal shock wave systems for tendon and ligament pathology in performance animals.
Arthroscopy captures the dominant share of capital equipment budgets. Stem Cell Therapy is climbing the fastest as biologic adjuncts displace hardware-only protocols.
End User:
End-user channel structure determines margin retention and service bundling flexibility for orthopedic vendors.
- Animal Hospitals:Multi-specialty referral institutions consolidating imaging, surgery, and rehabilitation under single-roof models command premium pricing through case complexity. Texas and California animal hospitals are capturing disproportionate margin pools by integrating telemedicine follow-up with physical rehabilitation.
- Veterinary Clinics:General practice settings with limited orthopedic caseloads represent high-volume, low-margin consumable demand concentrated in fracture stabilization hardware.
- Rehabilitation Centers:Standalone physical therapy facilities operating under variable state supervision requirements.
- Research Institutions:Veterinary teaching hospitals driving protocol innovation and 3D-printed custom implant fabrication.
Animal Hospitals concentrate the highest-value procedures. Rehabilitation Centers are expanding most quickly where state practice acts permit veterinary technician autonomy.
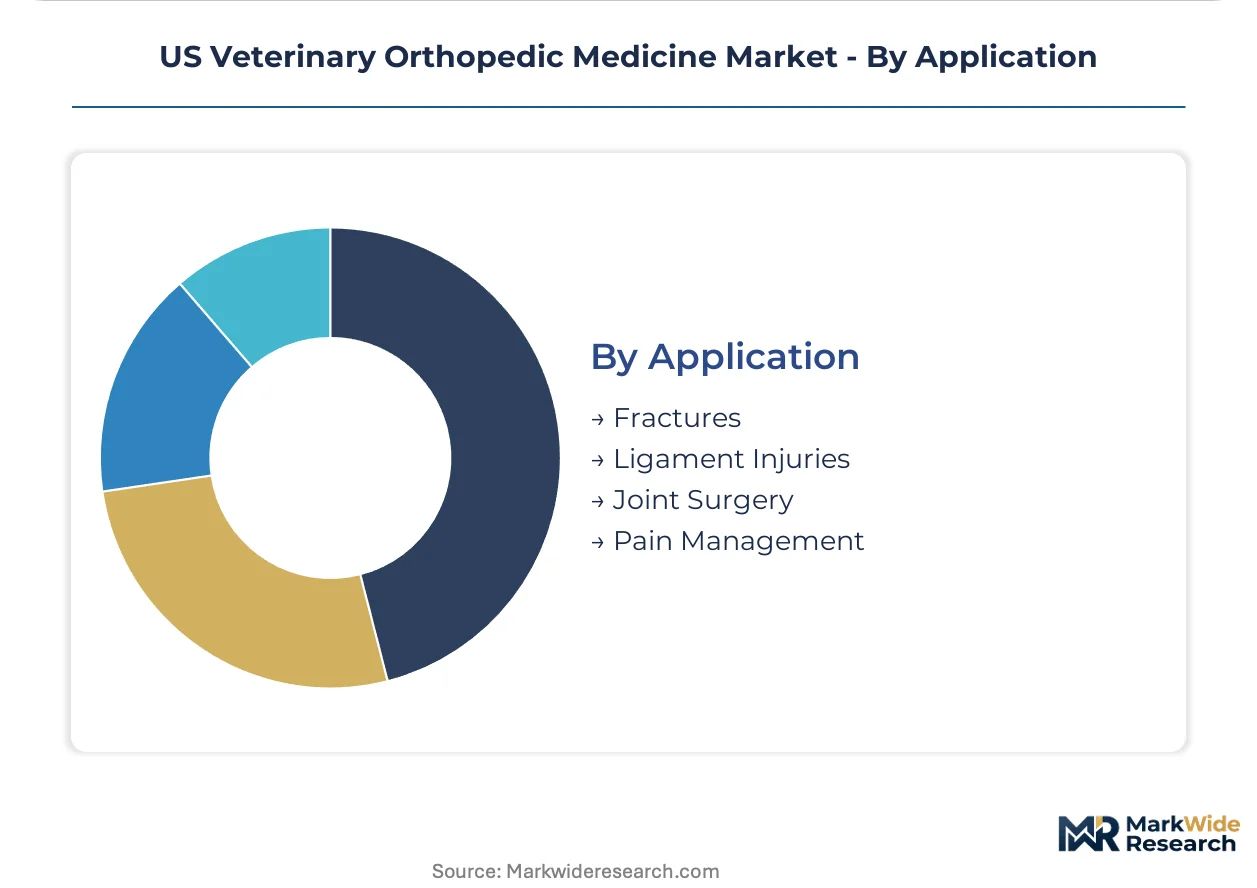
Application:
Application segmentation tracks injury etiology and procedural reimbursement patterns across companion animal populations.
- Joint Surgery:Total hip replacements, stifle stabilization procedures, and elbow arthroplasty address degenerative and traumatic conditions in large-breed dogs. California specialty networks are performing joint surgeries at the highest per-capita rates correlated with pet insurance penetration.
- Fractures:Internal fixation and external skeletal stabilization for traumatic injuries require immediate surgical intervention with revision economics driving implant selection toward premium locking plate systems.
- Ligament Injuries:Cranial cruciate ligament repair and collateral ligament reconstruction procedures.
- Pain Management:Multimodal pharmaceutical and interventional approaches for chronic orthopedic conditions.
Joint Surgery commands the highest average procedure value. Pain Management is gaining share fastest as chronic condition protocols extend patient lifespans.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Board-certified veterinary surgeons concentrate in coastal and Sun Belt metropolitan clusters, with fellowship training programs anchoring demand density in three dominant state markets.
California
Companion animal insurance penetration exceeds national averages in the San Francisco Bay Area and Los Angeles Basin, driving per-capita joint replacement volumes. FDA Center for Veterinary Medicine maintains active oversight of stem cell therapy protocols advanced by UC Davis Veterinary Medical Teaching Hospital. The San Diego-Tijuana corridor supports specialized orthopedic referral networks serving high-value performance animals.
Texas
Metropolitan Dallas-Fort Worth and Houston host the densest concentration of multi-specialty animal hospitals outside California. State veterinary practice act amendments in 2023 expanded veterinary technician autonomy in rehabilitation delivery, compressing service costs. Texas A&M University College of Veterinary Medicine drives 3D-printed custom implant fabrication through additive manufacturing partnerships with Austin-based medical device fabricators.
Florida
Household pet expenditure in Miami-Dade and Tampa Bay metropolitan areas surpasses national benchmarks by substantial margins. Third-party veterinary lending platforms pre-qualify owners before specialist consultation, restructuring case flow toward affiliated hospital networks. University of Florida College of Veterinary Medicine anchors regenerative medicine curriculum development, expanding trained practitioner pools for stem cell and platelet-rich plasma protocols.
Southeast Atlantic
Georgia and North Carolina veterinary teaching hospitals attract referral volume from underserved Appalachian and Deep South markets. State veterinary medical boards enforce variable rehabilitation supervision requirements, creating compliance complexity for equipment vendors. Atlanta and Charlotte metropolitan clusters concentrate specialty clinic investment as private equity consolidates general practice networks.
US Veterinary Orthopedic Medicine Market Competitive Landscape
Top-tier vendors anchor premium implant and biologic segments, while mid-scale specialists occupy arthroscopy and rehabilitation equipment niches. The vendor base stratifies across human orthopedic technology transfer players, dedicated animal health conglomerates, and specialized veterinary device fabricators. Three archetypes dominate: diversified animal health conglomerates leveraging distribution scale, human medical device divisions applying cross-species technology platforms, and focused veterinary specialists engineering species-specific anatomical solutions. Competitive positioning hardens through strategic partnerships with veterinary teaching hospitals and selective acquisitions of regenerative medicine laboratories.
Within the animal health conglomerate tier, Zoetis Services LLC and Elanco Animal Health exemplify scale-driven positioning through integrated biologic and pharmaceutical portfolios. Among human orthopedic technology transfer specialists, DePuy Synthes occupies a position bridging human device standards into veterinary applications. The specialized veterinary device segment includes Arthrex Vet Systems, which anchors its competitive stance through arthroscopy portfolios engineered specifically for companion animal joint anatomy.
| Leading Market Players |
|---|
| Zoetis Services LLC |
| DePuy Synthes (Johnson & Johnson) |
| Boehringer Ingelheim International GmbH |
| Arthrex Vet Systems |
| Movora (Vimian Group) |
| B. Braun VetCare |
| Elanco Animal Health |
| Merck Animal Health |
| Integra LifeSciences |
| Others |
Pricing and Supply Chain Analysis
ISO 13485 certification gates both qualified titanium alloy supply and premium-tier pricing access for implant manufacturers, compressing margins for uncertified competitors while elevating procurement costs for veterinary teaching hospitals seeking custom fabrication partnerships.
Pricing Analysis
Bundled service packaging dominates the US veterinary orthopedic medicine market, with animal hospitals consolidating surgical, imaging, and rehabilitation fees into single-procedure quotes while unbundled component pricing persists for general veterinary clinics. Premium-mid-economy pricing differentiation rests on FDA submission tier and ISO certification depth, with stem cell therapy protocols commanding substantial premiums over hardware-only interventions. Cost compression in standard implant tiers is intensifying because aerospace and human medical device manufacturers compete for qualified titanium alloy sourcing. General veterinary clinics exhibit the highest price sensitivity, constrained by limited orthopedic caseloads and pet owner out-of-pocket payment expectations.
Supply Chain Analysis
Single-source vulnerability sits with aerospace-qualified titanium alloy foundries concentrated in the US and Germany, where veterinary implant manufacturers face input competition from larger medical device and defense contractors. Raw material dependencies center on titanium alloy feedstock, cobalt-chromium casting ingots, and surgical-grade stainless steel bar stock. Tariff exposure on precision-machined components from European contract manufacturers elevates landed costs for arthroscopy instrumentation. Distribution runs through Zoetis Services LLC and Elanco Animal Health integrated networks, compressing independent vendor channel economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US veterinary orthopedic medicine market reads as a late-cycle quality story, justified by pet owner demand shifts toward biologic adjuncts and regenerative protocols that require premium certification tiers and fellowship-trained surgical delivery.
For Market Incumbents: Anticipate margin compression from 3D-printed custom implant decentralization at Texas A&M and UC Davis teaching hospitals by deepening captive biologic processing capabilities and securing exclusive stem cell therapy distribution partnerships with university veterinary medical centers. For New Entrants and Emerging Players: The price-point gap between premium locking-plate systems and economy external fixation hardware opens white-space targeting of Florida metropolitan specialty clinics consolidating arthroscopy service lines, with entry through telemedicine-integrated postoperative monitoring platforms for rural market penetration. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale rehabilitation equipment fabricators lacking USDA APHIS biologic product compliance infrastructure. Long-term viability over the next decade hinges on state-level veterinary technician scope-of-practice expansion enabling service cost compression. The signal to watch is FDA draft guidance finalization on additive-manufactured veterinary devices, which would accelerate custom implant commercialization timelines and reshape capital equipment amortization economics.| Strategic Initiative | Industry Significance |
|---|---|
| Biologic Processing Laboratory Acquisition | Captures stem cell and PRP therapy margins previously flowing to third-party reference laboratories. |
| Veterinary Teaching Hospital Partnership | Secures protocol endorsement and fellow-training pipeline access for implant system standardization. |
| Telemedicine Platform Integration | Enables rural specialist service extension without board-certified surgeon geographic expansion. |
| ISO 13485 Certification Investment | Unlocks FDA submission pathways for 3D-printed custom implants and elevates contract manufacturing access. |
| State Legislative Advocacy Coalition | Accelerates veterinary technician rehabilitation autonomy in Florida and Texas, compressing service delivery costs. |
Research Methodology
Direct dialogue with veterinary orthopedic surgeons, animal hospital procurement directors, biomedical engineers at implant manufacturers, and state veterinary medical board administrators combined with secondary validation against FDA Center for Veterinary Medicine submission databases, USDA APHIS biologic product registrations, and university veterinary teaching hospital annual reports. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue allocations across product categories.
Segment-level value outputs reflect modeled projections across the analysis window, with implant systems, surgical instruments, imaging equipment, and rehabilitation devices tracked separately alongside arthroscopy, stem cell therapy, laser therapy, and shockwave technology categories. CAGRs derived from historical procedure growth rates, pet population demographic shifts, and specialist fellowship pipeline expansion. Forecast inputs incorporated state-level practice act amendments, FDA guidance evolution timelines, and pet insurance penetration differentials by metropolitan statistical area.
The model assumes a particular technology adoption path; alternative pathways for 3D-printed custom implants would alter the outlook if FDA enforcement discretion tightens or teaching hospital capital deployment slows. Forecasts reflect documented assumptions about biologic product regulatory jurisdiction clarification and state rehabilitation supervision harmonization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Medicine
ASEAN Rabies Veterinary Vaccines Market
Veterinary Medicine
Global Companion Animal Pharmaceuticals Market
Veterinary Medicine
South Africa Veterinary Medicine Market
Veterinary Medicine
Veterinary Skin Care Products Market
Veterinary Medicine
US Veterinary Diagnostics Market
Veterinary Medicine
Veterinary Biologics Market
Veterinary Medicine
Veterinary Palliative Care Management Market
Veterinary Medicine
Global Veterinary Autogenous Vaccines Market
Veterinary Medicine
Veterinary Pain Management Market
Veterinary Medicine
Veterinary Orthopedic Medicine Market
Veterinary Medicine
Live Attenuated Veterinary Vaccines Market
Veterinary Medicine
Veterinary Anti-Infectives Market
Veterinary Medicine
Veterinary Dental Elevators Market
Veterinary Medicine
Global Veterinary/Animal Vaccines Market
Veterinary Medicine
Veterinary Anesthesia Market
Veterinary Medicine
Veterinary Medicine Market