
 Soy-Based Chemical Market | 2026-2036
Soy-Based Chemical Market Size, Share, and Industry Trends Forecast 2026-2036
Soy-Based Chemical Market Analysis
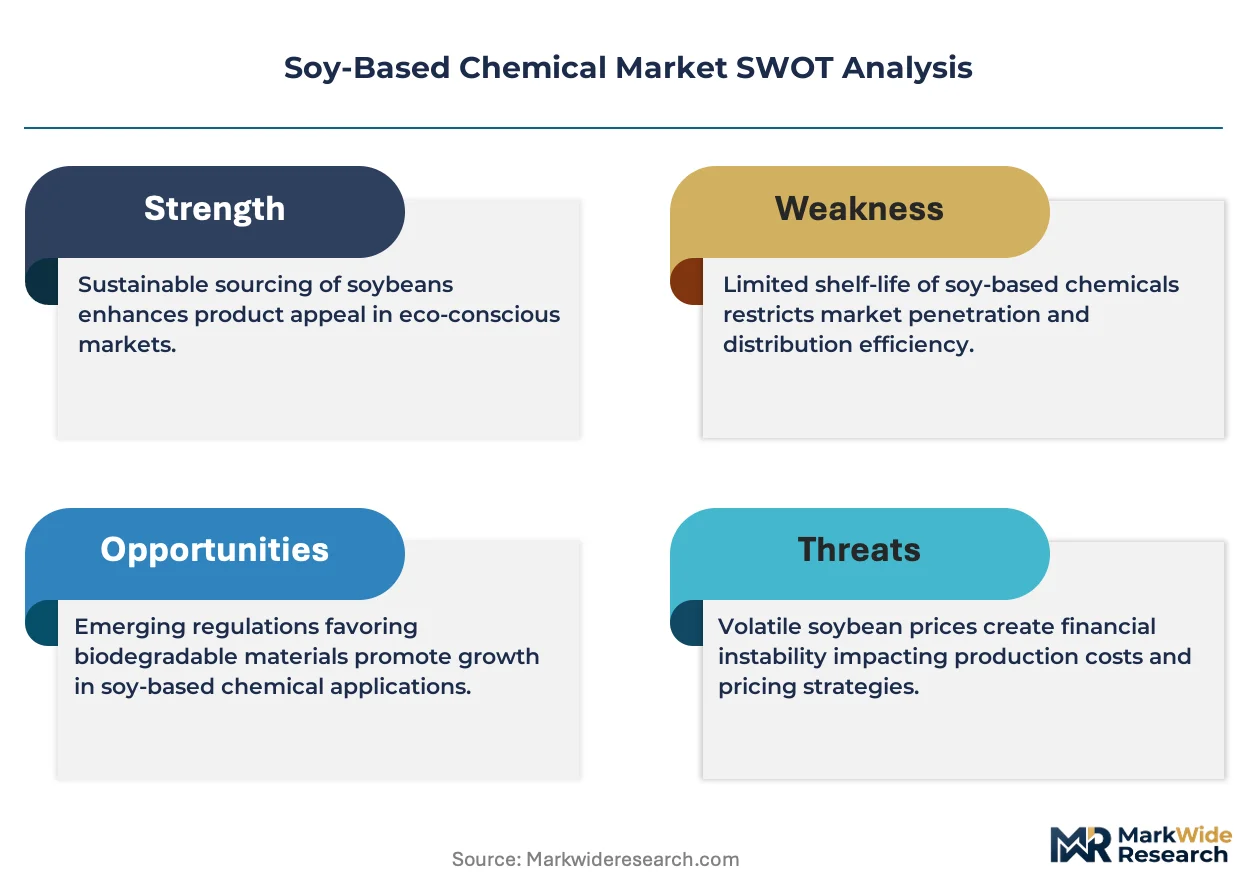
ASTM D6866 certification for biobased content is rotating from a voluntary label to a procurement gate across European and North American industrial buyers. Cargill leverages its crushing network to anchor feedstock cost positions in North American oleochemical supply. BASF competes through specialized catalyst systems that convert soybean oil into higher-value ester intermediates. Evonik Industries differentiates via pharmaceutical-grade lecithin purification capabilities that command premium positioning in personal care channels.
Soy-based chemicals comprise oleochemical derivatives, protein isolates, and phospholipid extracts refined from Glycine max through solvent extraction, mechanical pressing, or enzymatic hydrolysis, with specifications typically requiring minimum 95% purity for industrial-grade applications and strict residual hexane limits for food-grade streams. These materials serve as functional replacements for petroleum-derived surfactants, binders, and plasticizers across formulated product industries. Soybean oil dominates current value flows due to its direct substitution potential in alkyd resins and polyurethane foams, while soy lecithin captures concentrated margin pools in pharmaceutical and nutraceutical emulsification where supply tightness persists. Bioplastics applications are expanding fastest among the application categories, though food additives still absorb the largest absolute volume given entrenched soy protein demand in processed meat analogs and bakery systems.
The EPA administers Renewable Fuel Standard credits that indirectly bolster soy methyl ester economics for chemical applications, while REACH registration requirements in Europe impose toxicological documentation burdens that favor established suppliers with dedicated regulatory affairs capacity. FDA food-contact substance notifications govern lecithin and protein deployment in packaging applications, creating compliance moats around GRAS-affirmed supply chains. Stakeholders must monitor how the EU F-Gas Regulation and parallel state-level climate mandates in the United States reshape relative economics between soy-derived and synthetic chemical pathways.
Market Dynamics
The EU Green Deal's petrochemical phase-out timelines are compressing substitution economics for soy-derived polyols, while ASTM D6866 certification hardens from voluntary label to procurement gate across industrial buyer bases.
Growth Catalysts
- REACH Registration Requirements:European toxicological documentation burdens favor established suppliers with dedicated regulatory affairs capacity, consolidating demand around compliant oleochemical networks.
- Bioplastics Manufacturing:German polyurethane foam producers are scaling soy-polyol purchases as alkyd resin substitution accelerates in coatings applications.
- Midwest Crushing Corridors:United States soybean processing clusters now share logistics infrastructure with renewable chemical pilot plants, collapsing feedstock-to-reactor transport costs.
Market Restraints
- Residual Solvent Limits:Food-grade lecithin streams face strict hexane contamination ceilings that constrain processing throughput and elevate purification capex.
- Petrochemical Price Volatility:Crude oil swings distort relative economics for soy methyl ester against synthetic surfactants, freezing long-term supply contracts.
- Protein Isolate Substitution:Pea and fava protein isolates are capturing share in meat analog formulations, pressuring soy protein volume absorption.
Strategic Opportunities
- Pharmaceutical-Grade Lecithin:Supply tightness in high-purity phospholipid channels commands premium positioning in personal care and drug delivery emulsification.
- EPA Renewable Fuel Standard Credits:Indirect bolstering of soy methyl ester economics creates arbitrage windows for chemical applications versus fuel markets.
- Enzymatic Hydrolysis Convergence:Combining solvent-free extraction with precision fermentation is opening pharmaceutical-grade protein isolate pathways.
Industry Challenges
- ASTM D6866 Certification Timelines:Biobased content verification delays average 4-6 months, freezing supplier qualification for urgent procurement cycles.
- GRAS Affirmation Complexity:FDA food-contact substance notifications for lecithin deployment in packaging require extensive toxicological dossiers that smaller crushers cannot assemble.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy-Based Chemical Market |
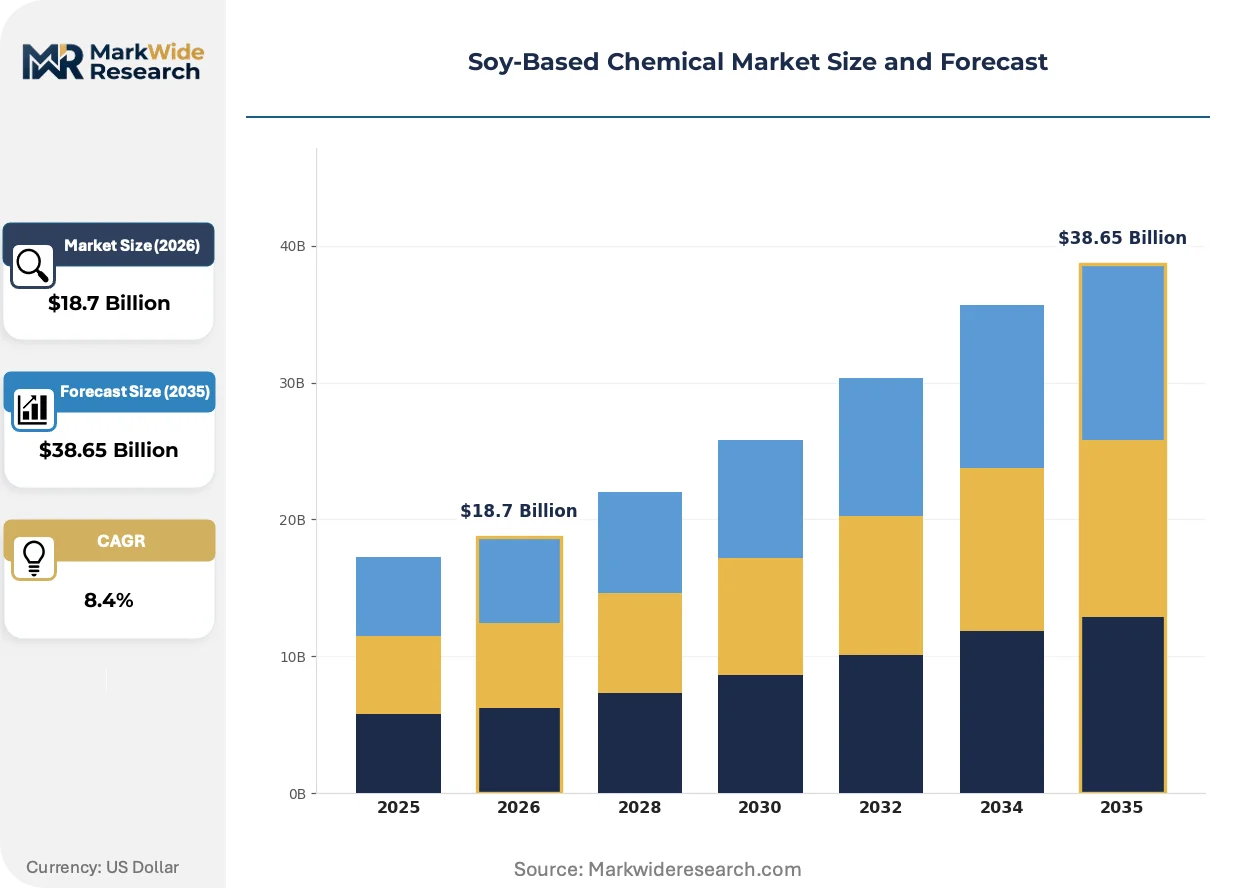
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soybean Oil, Soy Protein, Soy Lecithin, Soy Flour Application: Food Additives, Bioplastics, Cosmetics, Textiles End User: Food Industry, Personal Care, Agriculture, Automotive Grade: Food Grade, Industrial Grade, Pharmaceutical Grade, Technical Grade |
| Companies Covered | Dow, DuPont de Nemours, Cargill, NatureWorks, Evonik Industries, Archer Daniels Midland Company, Bunge Limited, Elevance Renewable Sciences, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy-Based Chemical Market Emerging Trajectories
Enzymatic processing routes are displacing hexane-based extraction in high-margin pharmaceutical channels, while regulatory certification hardens into competitive moats rather than marketing claims.
Enzyme-catalyzed oil modification is displacing traditional alkali refining in lecithin purification workflows. European nutraceutical contract manufacturers are adopting these systems to meet EFSA residual solvent limits. The technology is displacing incumbent solvent extraction capacity in Rotterdam and Hamburg port clusters, forcing legacy processors into feedstock trading rather than finished goods.
The EU F-Gas Regulation is accelerating fluorinated blowing agent phase-outs in polyurethane foam production. This compresses substitution timelines for soy-derived polyols in rigid insulation applications. German appliance manufacturers are reformulating cold-chain equipment specifications to exclude synthetic alternatives, locking in biopolyol procurement through 2030.
Industrial buyers are consolidating supplier rosters around ASTM D6866-certified networks with verified mass-balance documentation. Food packaging converters are replacing spot purchasing with multi-year offtake agreements tied to certified crushing origin. This concentration is most visible in United States Midwest logistics corridors, where Cargill and Bunge terminal assets now anchor qualification requirements.
Soy-Based Chemical Market Segmentation
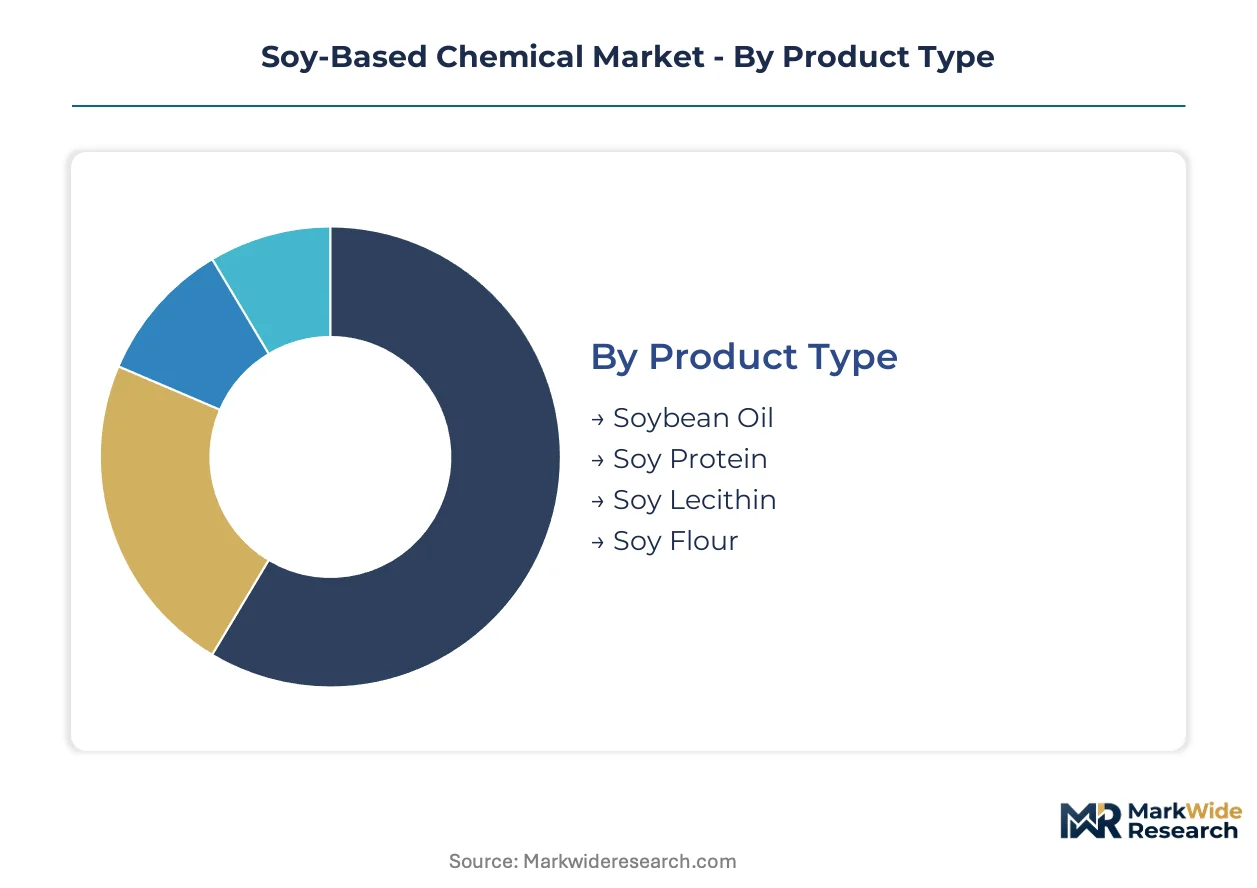
Soy-based chemical value pools fragment across radically different margin architectures. Product type determines feedstock conversion economics, while grade certification erects pricing tiers that separate commodity crushers from specialized refiners.
Product Type:
Margin concentration sits with phospholipid and protein fractions that command purification premiums over commodity oil streams.
- Soybean Oil:Triglyceride base refined through alkali neutralization and bleaching for alkyd resin and polyurethane polyol feedstocks. Demand clusters in United States Midwest crushing corridors where Cargill and Bunge terminal infrastructure collapses logistics costs for bioplastics manufacturers.
- Soy Lecithin:Phospholipid concentrate separated through degumming and solvent precipitation, with pharmaceutical-grade specifications requiring residual hexane below 25 ppm. Supply tightness in high-purity channels commands premium positioning in nutraceutical emulsification and drug delivery systems.
- Soy Protein:Isolate and concentrate fractions produced via aqueous extraction and isoelectric precipitation for meat analog and bakery applications. Pea protein substitution is pressuring volume absorption in European formulated foods.
- Soy Flour:Full-fat or defatted meal milled to particle specifications for industrial adhesive and paper coating binders. Technical-grade absorption concentrates in particleboard and plywood manufacturing.
Soybean oil holds installed capacity across North American and European crushing networks. Soy lecithin is rotating up the share rankings as pharmaceutical-grade purification investments compound.
Application:
Volume leadership diverges from value growth, with food additives absorbing absolute tonnage while bioplastics climbs the fastest.
- Food Additives:Emulsifiers, texturizers, and protein fortifiers deployed in processed meat analogs, bakery systems, and beverage stabilization. Entrenched demand in United States and German food manufacturing absorbs the largest absolute volume despite protein isolate substitution pressures.
- Bioplastics:Polyol intermediates for polyurethane foams and thermoplastic starch blends for packaging films. German appliance manufacturers are locking in biopolyol procurement through 2030 as EU F-Gas Regulation accelerates fluorinated blowing agent phase-outs.
- Cosmetics:Lecithin-derived emollients and phospholipid liposomes for personal care formulations. EFSA residual solvent limits are compressing qualification timelines for European contract manufacturers.
- Textiles:Soy protein fiber spinning and oil-based softening agents for natural fiber processing. Technical-grade specifications dominate current absorption in Asian spinning mills.
Food additives anchor current volume baselines. Bioplastics represents the steepest expansion trajectory as petrochemical substitution timelines compress.
End User:
Procurement sophistication varies sharply, with pharmaceutical and automotive buyers imposing certification regimes that commodity food processors bypass.
- Food Industry:Processed meat, dairy alternative, and bakery manufacturers purchasing protein isolates and lecithin emulsifiers under GRAS-affirmed supply chains. FDA food-contact substance notifications govern packaging deployment, creating compliance moats around established suppliers.
- Personal Care:Cosmetics and nutraceutical formulators demanding pharmaceutical-grade lecithin with documented mass-balance certification. ASTM D6866 verification is hardening from voluntary label to procurement gate across European and North American industrial buyers.
- Agriculture:Biopesticide carriers and soil amendment formulations utilizing soy flour and protein hydrolysates. Technical-grade specifications dominate current procurement with limited purity premiums.
- Automotive:Polyurethane foam suppliers for seating and insulation applications sourcing soy-derived polyols under OEM sustainability mandates. EPA Renewable Fuel Standard credits indirectly bolster soy methyl ester economics for chemical pathway arbitrage.
The food industry commands current volume leadership. Personal care is gaining share fastest as pharmaceutical-grade purification investments compound premium positioning.
Grade:
Certification tier determines accessible end-use markets and pricing power, with pharmaceutical and food grades capturing margin premiums over technical specifications.
- Food Grade:Complies with FDA and EFSA residual solvent limits, heavy metal ceilings, and microbial specifications for direct human consumption. Strict hexane contamination constraints elevate purification capex and constrain processing throughput for lecithin streams.
- Industrial Grade:Minimum 95% purity specifications for surfactant, binder, and plasticizer applications without food-contact requirements. Alkyd resin and polyurethane polyol manufacturers absorb the largest industrial-grade volumes.
- Pharmaceutical Grade:USP and EP monograph compliance with documented batch traceability and endotoxin testing for injectable and topical drug delivery. Evonik Industries and specialized European refiners command concentrated margin pools in this channel.
- Technical Grade:Basic purity specifications for adhesive, coating, and agricultural applications with minimal regulatory documentation. Soy flour and crude lecithin fractions dominate technical-grade supply.
Industrial grade holds installed capacity across commodity crushing networks. Pharmaceutical grade is rotating up the share rankings as personalized medicine and targeted drug delivery expand phospholipid demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Illinois River waterway and Chicago rail hub anchor North American soy-based chemical flows, connecting Midwest crushing clusters to Atlantic and Gulf export terminals.
United States
Midwest soybean processing corridors in Iowa and Illinois now share logistics infrastructure with renewable chemical pilot plants, collapsing feedstock-to-reactor transport costs. EPA Renewable Fuel Standard credits indirectly bolster soy methyl ester economics for chemical pathway arbitrage. Cargill and Bunge terminal assets in Decatur and Cedar Rapids anchor supplier qualification requirements for bioplastics manufacturers.
Germany
Polyurethane foam producers in North Rhine-Westphalia are scaling soy-polyol purchases as the EU F-Gas Regulation accelerates fluorinated blowing agent phase-outs. REACH registration requirements favor established suppliers with dedicated regulatory affairs capacity, consolidating demand around compliant oleochemical networks. Hamburg port clusters are displacing legacy solvent extraction capacity with enzyme-catalyzed lecithin purification systems.
China
Dual carbon goals are compressing substitution timelines for soy-derived polyols in rigid insulation applications across Yangtze River Delta manufacturing zones. The country's national chemical regulator is tightening residual solvent limits for food-grade lecithin imports. Shanghai and Ningbo port infrastructure is expanding dedicated storage for pharmaceutical-grade phospholipid concentrates.
Brazil
Soybean crushing expansion in Mato Grosso and Paraná is creating surplus oil streams for oleochemical conversion. ANVISA pharmaceutical-grade certification requirements are elevating purification standards for lecithin exports to North American and European nutraceutical markets. Santos port terminal investments are reducing time-to-market for high-purity phospholipid shipments.
India
FSSAI food-grade specifications are converging with EFSA residual solvent limits for lecithin imports used in processed food manufacturing. The PLI scheme for specialty chemicals is attracting investment in enzymatic hydrolysis capacity for pharmaceutical-grade protein isolates. Gujarat and Maharashtra industrial corridors are developing shared solvent-free extraction infrastructure for personal care ingredient supply.
Soy-Based Chemical Market Vendor Landscape
Listed leaders compete with private specialists across feedstock control and purification technology dimensions. The vendor base organizes around three strategic archetypes: agricultural conglomerates with captive crushing assets, diversified chemical majors with catalyst and process licensing capabilities, and specialized refiners focused on pharmaceutical-grade phospholipid fractions. Dominant competitive moves include backward integration into seed crushing and multi-year offtake agreements tied to certified origin documentation.
Within the agricultural conglomerate tier, Cargill and Bunge Limited exemplify feedstock-anchored positioning through Midwest terminal network control. Among diversified chemical majors, BASF and Evonik Industries occupy positions defined by catalyst systems and pharmaceutical-grade purification capabilities respectively. Dow and DuPont de Nemours represent the materials science archetype with polymer formulation expertise that bridges petrochemical and bio-based product lines.
| Leading Market Players |
|---|
| Dow |
| DuPont de Nemours |
| Cargill |
| NatureWorks |
| Evonik Industries |
| Archer Daniels Midland Company |
| Bunge Limited |
| Elevance Renewable Sciences |
| BASF |
| Others |
Supply Flow & Price Mechanics
ASTM D6866 biobased certification gates both supplier qualification and price differentiation, compressing procurement timelines while amplifying premiums for verified mass-balance documentation across European and North American industrial buyer networks.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade lecithin and technical-grade soy flour, with residual hexane thresholds below 25 ppm commanding substantial purification premiums. Contract-based long-term offtake agreements dominate bioplastics procurement, while spot purchasing persists in technical-grade adhesive applications. Pricing pressure stems from pea protein substitution in European meat analog formulations, eroding volume absorption in standard-grade isolates. Food processors exhibit highest price sensitivity due to entrenched commodity purchasing patterns, whereas personal care formulators absorb premiums for documented endotoxin compliance.
Supply Chain Analysis
The United States Midwest and Germany anchor soy-based chemical production, with Iowa and Illinois crushing corridors sharing logistics infrastructure with renewable chemical pilot plants while North Rhine-Westphalia polyurethane producers scale biopolyol procurement. Feedstock draws from Mato Grosso and Paraná expansion in Brazil, creating surplus oil streams for oleochemical conversion. Single-source vulnerability concentrates in pharmaceutical-grade lecithin purification, where Rotterdam and Hamburg enzyme-catalyzed capacity remains limited. Distribution runs through Cargill and Bunge terminal assets in Decatur and Cedar Rapids, anchoring qualification requirements for downstream bioplastics manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Soy-based chemicals occupy early-cycle expansion positioning, with EU F-Gas Regulation acceleration of fluorinated blowing agent phase-outs compressing substitution timelines for biopolyol adoption in rigid insulation applications.
For Market Incumbents: Shield installed margin positions by deepening backward integration into seed crushing networks in Mato Grosso and Paraná, securing captive feedstock supply against Brazilian export competition. Accelerate pharmaceutical-grade lecithin purification investments to defend against enzyme-catalyzed displacement in Rotterdam and Hamburg port clusters.
For New Entrants and Emerging Players: FDA food-contact substance notification fast-tracks offer regulatory arbitrage against GRAS-affirmed incumbent supply chains, enabling white-space penetration in sustainable packaging films. Target United States Midwest logistics corridors where shared infrastructure collapses feedstock-to-reactor transport costs. Pursue enzymatic hydrolysis specialization to bypass hexane-based extraction capex barriers.
For Investors and Strategic Acquirers: EU Green Deal petrochemical phase-out timelines reshape the acquisition landscape toward compliant oleochemical networks with dedicated REACH registration capacity. Five-to-ten year viability favors diversified chemical majors with catalyst licensing capabilities over pure-play crushers exposed to protein isolate substitution. Monitor EPA Renewable Fuel Standard credit arbitrage windows as inflection signals for soy methyl ester chemical pathway economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Crushing | Cargill and Bunge terminal control in Decatur collapses feedstock cost positions for bioplastics manufacturers. |
| Pharmaceutical-Grade Purification Investment | Evonik Industries commands concentrated margin pools in USP-compliant lecithin channels for drug delivery systems. |
| Enzymatic Hydrolysis Capacity Buildout | Enzyme-catalyzed systems in Hamburg displace legacy solvent extraction, meeting EFSA residual solvent limits. |
| Long-Term Biopolyol Offtake Agreements | German appliance manufacturers lock in procurement through 2030 under EU F-Gas Regulation compliance mandates. |
| REACH Registration Consolidation | Established suppliers with dedicated regulatory affairs capacity capture demand from smaller crushers unable to assemble toxicological dossiers. |
Methodological Framework
Desk research of customs and trade data, SEC filings from listed agricultural conglomerates, and ECHA REACH registration databases preceded structured interviews with plant managers at Midwest crushing facilities, procurement leads at German polyurethane foam producers, distribution channel partners in Rotterdam and Hamburg port clusters, and technical R&D directors specializing in enzymatic hydrolysis pathways. Bottom-up volume modeling triangulated against top-down value estimates from oleochemical network disclosures.
Variance decomposition across the projection horizon isolates feedstock cost volatility, regulatory compliance burden shifts, and substitution elasticity between soy and pea protein isolates. Segmentation dimensions modeled include grade tier, end-use industry, regional production hub, and certification status. CAGRs derived from historical crushing capacity expansion rates and announced pilot plant investments, with bioplastics application growth calibrated against EU F-Gas Regulation implementation schedules.
Underlying assumptions cover sustained EPA Renewable Fuel Standard credit economics, REACH registration timeline stability, and EFSA residual solvent limit enforcement, with deviation risk concentrated in crude oil price volatility distorting relative economics for soy methyl ester against synthetic surfactants. Recalibration cycles align with material shifts in EU Green Deal petrochemical phase-out timelines and ASTM D6866 certification adoption rates across industrial buyer bases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
US Potassium Methylate Market
Functional Chemicals
Potassium Methylate Market
Functional Chemicals
Europe Fumaric Acid Market
Functional Chemicals
Asparagine Market
Functional Chemicals
Lauric Arginate Market
Functional Chemicals
Chlorobutanol Market
Functional Chemicals
Amino Acids Market
Functional Chemicals
Glutaraldehyde Market
Functional Chemicals
L-Citrulline Market
Functional Chemicals
Paraformaldehyde Market
Functional Chemicals
Tartrazine Market
Functional Chemicals
Global Potassium Citrate Market
Functional Chemicals
Propylparaben Market
Functional Chemicals
Ortho Phthalic Aldehyde Market
Functional Chemicals
Calcium Citrate Malate Market
Functional Chemicals
Global Peptide Synthesis Market