
 Solar Paper Market | 2026-2036
Solar Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Paper Market Insights
Direct-to-consumer online channels for portable solar accessories is fragmenting as specialty electronics retailers and outdoor gear platforms compete for wallet share. Anker leverages its established power electronics brand to cross-sell solar-integrated charging products through Amazon and direct storefronts. Hanergy sustains thin-film technology leadership through captive R&D pipelines focused on flexible substrate efficiency. Solio specializes in compact foldable designs that anchor premium positioning within backpacking and expedition segments.
Solar paper denotes ultra-thin photovoltaic cells printed or deposited on flexible substrates such as PET or polyimide, typically achieving thicknesses below one millimeter and bend radii under thirty millimeters for integration into portable devices, wearables, and temporary ground coverings. The primary commercial purpose centers on harvesting ambient light in mobile or off-grid contexts where rigid silicon panels prove impractical. Flexible solar sheets lead product type revenue due to their compatibility with consumer electronics form factors, while solar fabrics represent the fastest-growing category as textile-integrated photovoltaics gain traction in military and emergency response applications. Thin-film technology dominates manufacturing volume, though nanotechnology-enhanced layers command premium margins through improved low-light conversion efficiency.
MIIT efficiency mandates in China and REACH substrate compliance requirements in Europe shape material selection and cross-border market access for solar paper manufacturers. FDA electrical safety standards influence portable charging product classifications for US consumer channels, while ISO certification requirements affect OEM qualification with electronics brands. Stakeholders must monitor evolving thin-film efficiency thresholds and substrate recyclability mandates as these regulatory vectors increasingly determine which product architectures secure commercial traction.
Market Dynamics
Thin-film photovoltaic manufacturing advances are compressing unit economics while MIIT efficiency mandates in China accelerate flexible substrate deployment across consumer electronics supply chains.
Growth Catalysts
- MIIT Efficiency Mandates:China's Ministry of Industry and Information Technology enforces minimum conversion efficiency thresholds for flexible solar cells, forcing domestic manufacturers to upgrade deposition equipment and driving technology spillover effects.
- Outdoor Recreation Demand:Backpacking and expedition segments in North America and Europe prioritize weight reduction, creating pull-through for sub-200 gram solar charging solutions integrated with power banks.
- Perovskite-Silicon Tandem Deposition:Laboratory-scale roll-to-roll coating processes are achieving higher power conversion efficiency on PET substrates, narrowing the performance gap with rigid crystalline alternatives.
Market Restraints
- Indium Tin Oxide Supply Concentration:Transparent conductive oxide layers depend on indium refining capacity concentrated in Chinese smelters, exposing manufacturers to price volatility and export restriction risk.
- REACH Substrate Compliance:European Chemicals Agency restrictions on certain phthalate plasticizers in polyimide films force reformulation cycles that extend product qualification timelines by 12-18 months.
- Rigid Silicon Cost Compression:Conventional monocrystalline panel prices have fallen below twenty cents per watt in utility-scale procurement, narrowing the practical premium acceptable for flexible form factors.
Strategic Opportunities
- Emergency Response Textiles:Solar fabric integration into military and disaster relief shelters offers volume potential where bend radius and rapid deployment outweigh absolute efficiency metrics.
- India PLI Scheme Extension:Production-linked incentive schemes for solar module manufacturing now explicitly include thin-film and flexible substrate categories, attracting capital toward domestic cell printing capacity.
- Direct-to-Consumer Outdoor Platforms:Specialty retailers like REI and Backcountry are building dedicated solar accessory categories with educational content, reducing customer acquisition costs versus generalist electronics channels.
Industry Challenges
- Roll-to-Roll Deposition Talent Scarcity:Process engineers with experience in continuous thin-film coating at micron-scale precision command premium compensation and migrate toward semiconductor display manufacturing.
- ISO 9001 and IEC 61215 Dual Certification:Flexible solar products targeting both consumer electronics OEMs and outdoor equipment brands must satisfy divergent quality management and photovoltaic safety standards simultaneously.
- Substrate-Cell Delamination Field Failures:Thermal cycling in desert environments exposes weaknesses in adhesive layer selection, triggering warranty claims that erode margin structures in premium product tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Paper Market |
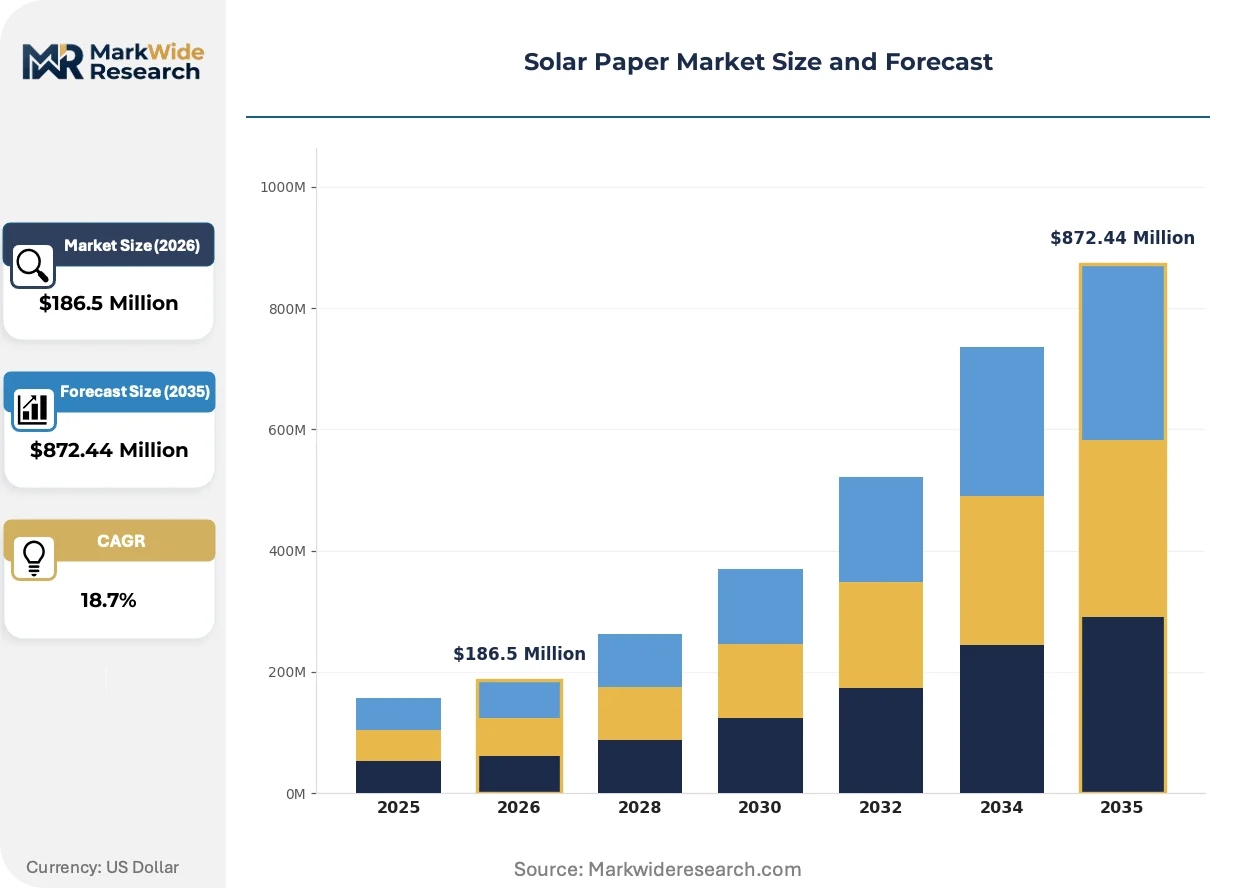
| Market Size in 2026 | $186.5 Million |
| Market Size in 2035 | $872.44 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Solar Sheets, Rigid Solar Panels, Solar Film, Solar Fabrics End User: Consumers, Commercial Applications, Utility Providers, Educational Institutions Application: Portable Charging, Solar-Powered Gadgets, Ground-Cover Solutions, Off-Grid Systems Technology: Thin-Film, Monocrystalline, Polycrystalline, Nanotechnology |
| Companies Covered | Anker, Yolk, Ningbo Evergreen Technology Co., Harbin Shinenovo Technology, Suntactics, Solio, Hanergy, Xtorm, Letsolar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Paper Market Trends and Innovations
Digital printing of photovoltaic active layers is collapsing prototyping cycles while regulatory pressure on substrate chemistry reshapes material selection across manufacturing footprints.
Copper indium gallium selenide deposition on ultra-thin stainless steel foils is virtualizing the traditional glass-encapsulated panel architecture. Military procurement offices in the United States and Germany are qualifying these substrates for tent-integrated power systems where shatter resistance matters more than absolute efficiency. The technology is virtualizing supply chain assumptions that rigid silicon dominance would persist across all portable applications.
REACH authorization requirements for diisocyanates in polyurethane encapsulants are forcing European manufacturers toward water-based acrylic alternatives. Industrial consequence includes reformulated lamination processes that sacrifice some moisture barrier performance for regulatory compliance. Flexible solar sheet suppliers serving EU consumer electronics brands are absorbing qualification costs and passing through price adjustments.
Expedition outfitters are unbundling solar charging from integrated power banks, creating preference for modular systems where panels and storage upgrade independently. Specialty outdoor retailers are responding with comparison tools that emphasize watts-per-gram metrics over brand loyalty. This pattern concentrates in Germany and Switzerland where alpine climbing culture prioritizes equipment weight optimization.
Solar Paper Market Segmentation
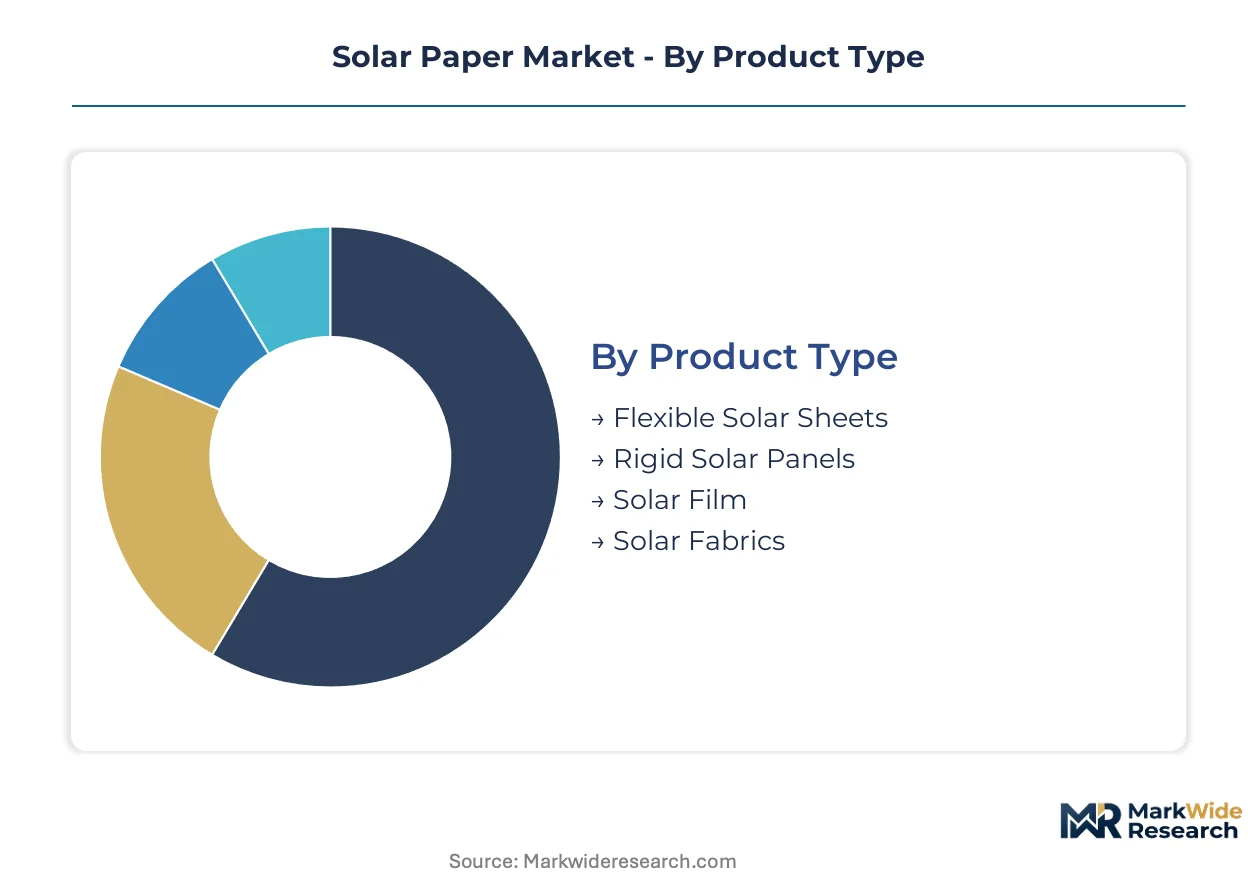
Solar paper manufacturers configure product architectures around substrate flexibility, end-use mobility requirements, and deposition technology economics. Segment boundaries shift as thin-film efficiency gains erode traditional distinctions between portable and fixed-installation applications.
Product Type:
Cost tier separation between premium flexible substrates and economy rigid alternatives determines margin capture across consumer and industrial channels.
- Flexible Solar Sheets:PET or polyimide substrates below one millimeter thickness achieve bend radii under thirty millimeters. Backpacking and expedition segments in Germany and Switzerland prioritize sub-200 gram configurations for alpine equipment integration.
- Solar Fabrics:Textile-embedded photovoltaic threads weave into tent canopies and emergency shelter materials. Military procurement offices in the United States and Germany are qualifying these substrates for rapid-deployment field power where shatter resistance outweighs absolute efficiency metrics.
- Rigid Solar Panels:Glass-encapsulated crystalline architectures persist in semi-permanent installations where weight constraints relax.
- Solar Film:Ultra-thin deposition layers on stainless steel foils target building-integrated photovoltaics and curved surface applications.
Flexible Solar Sheets hold installed capacity. Solar Fabrics is rotating up the share rankings.
End User:
Application context varies sharply between mobility-dependent consumers and infrastructure-scale utility procurement with divergent performance specifications.
- Consumers:Outdoor recreation participants and remote workers drive demand for modular charging systems. Specialty retailers like REI and Backcountry are building dedicated solar accessory categories with educational content, reducing customer acquisition costs versus generalist electronics channels.
- Commercial Applications:Construction sites and agricultural operations deploy temporary ground-cover solutions where grid connection proves uneconomical.
- Utility Providers:Distributed generation pilots test flexible substrate durability in non-standard mounting configurations.
- Educational Institutions:Research laboratories and sustainability demonstration projects constitute a fragmented, price-sensitive procurement channel.
Consumers command volume concentration. Commercial Applications is climbing the fastest as temporary power rental models proliferate.
Application:
Customer type determines whether bend radius, absolute wattage, or deployment speed receives priority in product specification.
- Portable Charging:Power bank integration and standalone panel configurations target weight-optimized mobility. Expedition outfitters are unbundling solar charging from integrated storage, creating preference for modular systems where panels and batteries upgrade independently.
- Off-Grid Systems:Remote telecommunications and monitoring stations require multi-year durability in temperature-extreme environments.
- Solar-Powered Gadgets:Wearable electronics and IoT sensors embed micro-scale photovoltaic harvesters for battery extension.
- Ground-Cover Solutions:Agricultural weed suppression films with dual-purpose energy generation face qualification delays for soil contact safety.
Portable Charging anchors current revenue. Off-Grid Systems is gaining share fastest as rural electrification programs expand.
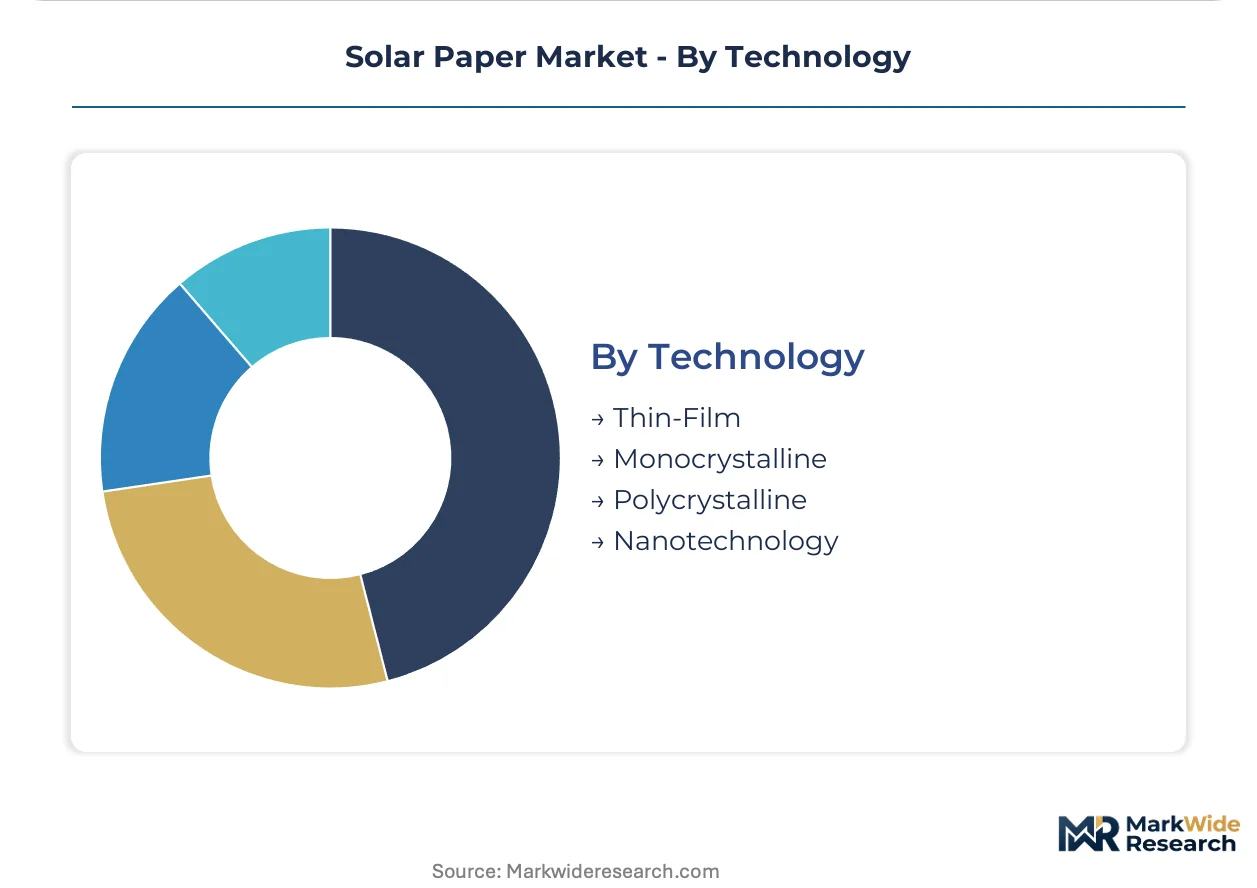
Technology:
Deposition method and active layer composition create performance tiering that spans efficiency, low-light response, and manufacturing scalability.
- Thin-Film:Copper indium gallium selenide and cadmium telluride deposition on flexible substrates dominates manufacturing volume. MIIT efficiency mandates in China force domestic manufacturers to upgrade roll-to-roll coating equipment, driving technology spillover effects across consumer electronics supply chains.
- Nanotechnology:Quantum dot and plasmonic enhancement layers command premium margins through improved spectral conversion efficiency in diffuse light conditions.
- Monocrystalline:High-purity silicon wafers maintain efficiency leadership in rigid substrate applications where flexibility requirements are absent.
- Polycrystalline:Lower-cost silicon casting processes retain share in price-sensitive educational and developing market installations.
Thin-Film holds installed capacity. Nanotechnology is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT efficiency mandates and production-linked incentive schemes across Asia-Pacific economies are redistributing solar paper manufacturing capacity toward integrated supply chain clusters.
China
Domestic solar component ecosystems in Jiangsu and Zhejiang provinces absorb the majority of flexible substrate output for consumer electronics integration. MIIT enforces minimum conversion efficiency thresholds that force deposition equipment upgrades across roll-to-roll coating facilities. Shenzhen and Dongguan manufacturing clusters specialize in sub-millimeter PET substrate production for portable charging accessories.
United States
Outdoor recreation demand in Colorado and California drives specialty retailer procurement of sub-200 gram solar charging solutions. FDA electrical safety standards influence portable charging product classifications for direct-to-consumer channels. Denver-Boulder corridor hosts expedition outfitter headquarters that unbundle solar panels from integrated power banks.
Germany
REACH substrate compliance requirements force reformulation of polyimide films containing restricted phthalate plasticizers. Alpine climbing culture in Bavaria and Baden-Württemberg prioritizes watts-per-gram metrics in equipment selection. Munich-based specialty retailers build dedicated solar accessory categories with educational content for backpacking segments.
India
PLI scheme extensions for solar module manufacturing now explicitly include thin-film and flexible substrate categories. Telangana and Karnataka states attract capital toward domestic cell printing capacity for rural electrification programs. Hyderabad industrial corridors develop roll-to-roll deposition talent pipelines for export-oriented production.
Japan
METI supports perovskite-silicon tandem research through national laboratory partnerships with PET substrate developers. Kansai region manufacturing clusters refine low-light conversion efficiency for wearable electronics integration. Osaka-based material suppliers qualify water-based acrylic encapsulants for REACH-aligned export compliance.
Solar Paper Market Competitive Landscape
On the supply side, the industry is bifurcated between power electronics brands with established consumer distribution and thin-film specialists with captive deposition technology. The vendor base spans three strategic archetypes: integrated consumer electronics brands, flexible substrate technology developers, and compact design specialists focused on expedition segments. Competitive moves concentrate on cross-selling solar-integrated products through Amazon and direct storefronts, plus qualification of textile-embedded formats for military procurement.
Within the power electronics tier, Anker leverages its established brand to anchor cross-selling strategies for solar-integrated charging products. Hanergy occupies a position exemplifying thin-film technology leadership through flexible substrate efficiency focus. Solio represents the compact design archetype with foldable configurations targeting premium backpacking positioning.
| Leading Market Players |
|---|
| Anker |
| Yolk |
| Ningbo Evergreen Technology Co. |
| Harbin Shinenovo Technology |
| Suntactics |
| Solio |
| Hanergy |
| Xtorm |
| Letsolar |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Los Angeles maritime corridor carries flexible solar substrate shipments whose freight cost volatility feeds directly into downstream price spreads between certified and uncertified product tiers. Container rate swings amplify the advantage of integrated manufacturers with captive deposition capacity in Jiangsu and Zhejiang provinces, compressing margins for buyers dependent on spot-market substrate procurement.
Pricing Analysis
Certification level (ISO 9001/IEC 61215 dual-grade) creates the primary spread between premium flexible solar sheets and economy alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects divergent qualification timelines for consumer electronics OEMs versus outdoor equipment brands. Cost compression in the economy tier is intensifying because rigid silicon panels have fallen below twenty cents per watt in utility-scale procurement, narrowing the acceptable premium for bendable form factors. Educational institutions and developing-market installations exhibit the highest price sensitivity, while military procurement offices in the United States and Germany tolerate substantial premiums for shatter-resistant CIGS-on-steel substrates.
Supply Chain Analysis
Export control restrictions on advanced roll-to-roll deposition equipment limit technology transfer to emerging cell printing facilities in India and Southeast Asia. Manufacturing gravity centers on China, South Korea, and Japan for thin-film active layer deposition, with Jiangsu and Zhejiang provinces hosting the majority of flexible PET substrate production. Supply chains draw from concentrated indium refining capacity in Chinese smelters for transparent conductive oxide layers, alongside copper and gallium feedstocks. Single-source vulnerability in indium tin oxide supply exposes manufacturers to price volatility and export restriction risk. Distribution runs through direct-to-consumer Amazon storefronts, specialty outdoor retailers like REI and Backcountry, and OEM qualification channels with consumer electronics brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar paper market fragmentation creates entry niches as expedition outfitters unbundle solar charging from integrated power banks, splintering demand across modular component suppliers. Specialty retailers building educational content categories reduce customer acquisition costs for players with authentic outdoor credibility.
For Market Incumbents: Insulate margin structures by deepening backward integration into polyimide film formulation and captive indium refining partnerships that buffer transparent conductive oxide cost spikes. Pursue dual ISO 9001 and IEC 61215 certification investments to defend qualification status against emerging thin-film specialists targeting consumer electronics OEMs. Counter the threat of perovskite-silicon tandem deposition advances by locking in multi-year supply agreements with PET substrate developers in Shenzhen and Dongguan manufacturing clusters. For New Entrants and Emerging Players: Establish a beachhead in emergency response textiles where military and disaster relief procurement prioritizes rapid deployment over absolute efficiency metrics. Solar fabric integration into tent canopies offers the most penetrable white-space, with textile-embedded photovoltaic threads qualifying for United States and German military procurement offices. Pursue a go-to-market angle through direct engagement with alpine climbing outfitters in Germany and Switzerland who prioritize watts-per-gram metrics and modular system architectures. For Investors and Strategic Acquirers: Roll-to-roll deposition specialists with process engineering talent pipelines in Hyderabad and Kansai region manufacturing clusters represent the most defensible acquisition archetype. Long-term viability across the analysis window hinges on qualification for MIIT efficiency mandates in China and REACH substrate compliance in Europe. Watch perovskite-silicon tandem laboratory achievements transitioning to roll-to-roll coating scale as the inflection signal for technology displacement risk in CIGS-dominated flexible substrates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Production | Captive PET and polyimide supply secures margin protection against REACH reformulation cycles in Europe. |
| Military Procurement Qualification | United States and German defense contracts validate shatter-resistant CIGS-on-steel for tent-integrated power systems. |
| Direct-to-Consumer Platform Launch | Amazon and specialty outdoor storefronts reduce customer acquisition costs versus generalist electronics channels. |
| Perovskite-Silicon Tandem R&D Partnership | METI-supported national laboratory collaborations in Japan advance low-light conversion efficiency for wearable integration. |
| India PLI Scheme Participation | Production-linked incentives for thin-film categories attract capital toward domestic cell printing capacity in Telangana. |
Research Methodology
A spread of perspectives from thin-film deposition engineers, specialty outdoor retailer category buyers, military procurement officers, consumer electronics OEM qualification managers, and roll-to-roll equipment suppliers converged on the working assumptions shaping this analysis. Primary interview insights were cross-validated against secondary sources including MIIT efficiency mandate documentation, ECHA REACH authorization records, FDA electrical safety guidance, SEC filings from power electronics brands, and customs trade data for indium and gallium feedstock flows. Bottom-up segment sizing was reconciled with top-down market triangulation to anchor volume and value estimates.
Demand-supply balance modeling across the projection horizon incorporated flexible solar sheet, solar fabric, and rigid panel product types alongside thin-film, nanotechnology, and crystalline silicon technology tiers. End-user segmentation captured consumers, commercial applications, utility providers, and educational institutions with application splits across portable charging, off-grid systems, solar-powered gadgets, and ground-cover solutions. CAGRs were derived from installed capacity buildout trajectories, efficiency improvement curves, and substitution elasticity estimates between flexible and rigid photovoltaic architectures. Perovskite-silicon tandem deposition scale-up timelines and MIIT mandate compliance costs were integrated as scenario variables.
Stress conditions across indium price volatility, REACH substrate reformulation delays, and rigid silicon cost compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding roll-to-roll coating equipment upgrade cycles and military procurement qualification timelines. Material shifts in perovskite stability validation or indium export restriction enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Wood-Based Panel Market
Paper Products
Metallized Paper Market
Paper Products
Global Wood Pulp Market
Paper Products
White Top Testliner Market
Paper Products
Pulp and Paper Chemicals Market
Paper Products
Paper and Board Technologies Market
Paper Products
White Line Chipboard Market
Paper Products
BPA Free Thermal Paper Market
Paper Products
Loose Leaf Paper Market
Paper Products
Europe Paper Market
Paper Products
Europe Decor Paper Market
Paper Products
Uncoated White Top Testliner Market
Paper Products
Sanitary Paper Products Market
Paper Products
Liquid Paperboard Market
Paper Products
Super Calendered Glassine Paper Market
Paper Products
Paper Making Machine Market