
 Emergency Vehicle Lights Market | 2026-2036
Emergency Vehicle Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Emergency Vehicle Lights Market Analytics
Buyer concentration among municipal fleet operators is shifting as regional cooperative purchasing agreements consolidate procurement volumes across multiple jurisdictions. Whelen Engineering leverages extensive domestic manufacturing capacity to anchor supply relationships with large public safety departments. Sound Off Signal competes through specialized configurations for law enforcement vehicles. Feniex differentiates via direct-to-agency digital channels that reduce distributor markup.
Emergency vehicle lights are electroluminescent warning devices engineered to output specific candela intensities, flash patterns, and chromaticity coordinates compliant with jurisdictional standards. LED modules now dominate new installations due to superior energy efficiency, extended operational lifespans exceeding 50,000 hours, and programmable flash sequences. Light bars command the largest revenue share among product types, reflecting integrated siren and communication mounting platforms. LED technology leads growth velocity across all application categories, displacing halogen and xenon in retrofit cycles.
NFPA 1901 governs fire apparatus lighting in the United States, while ECE R65 and ECE R10 regulate warning device approval across European member states. SAE Class 1 specifications define minimum intensity thresholds that shape product development priorities for manufacturers targeting North American sales. Stakeholders must monitor pending amendments to photometric testing protocols and emerging state-level mandates for amber rear warning on tow and recovery vehicles.
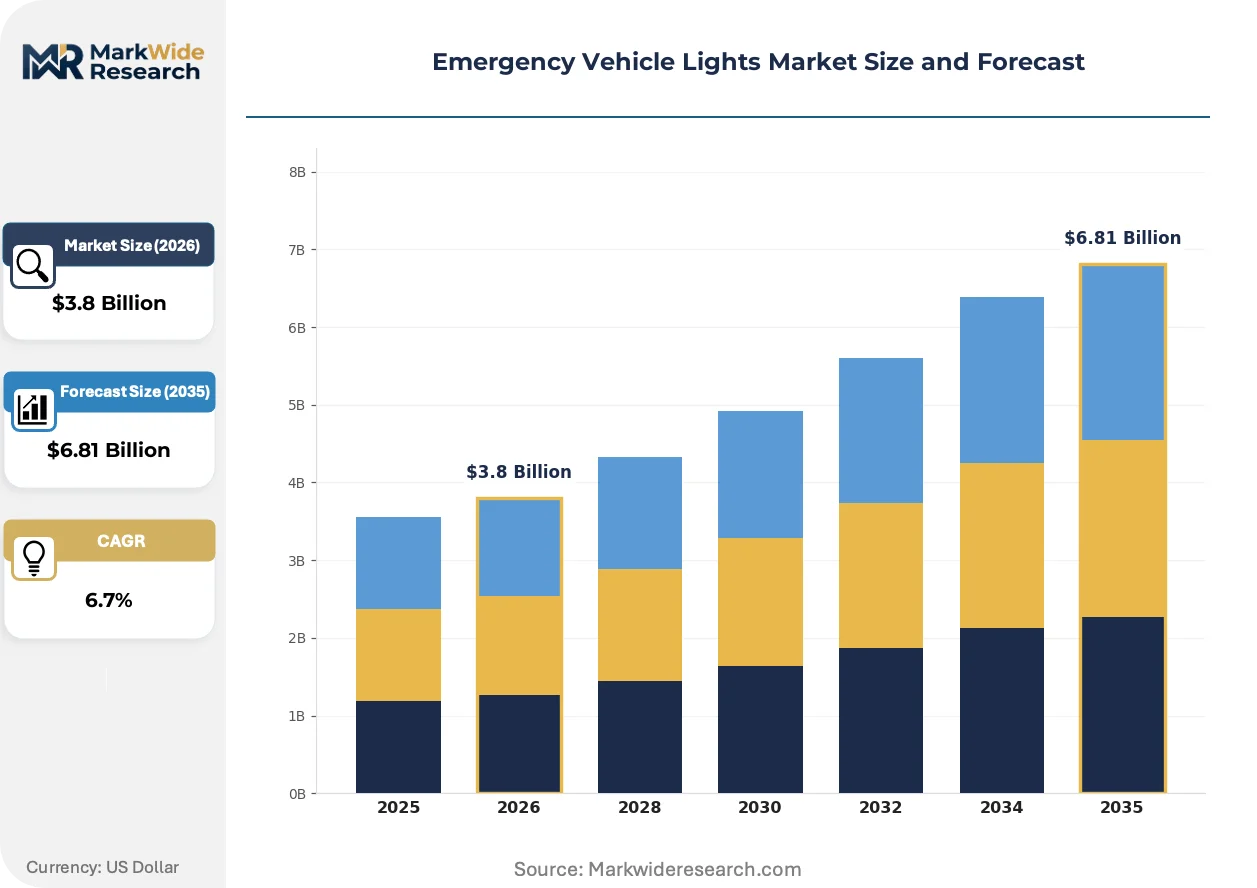
Market Dynamics
LED photometric standardization is compressing supplier margins while accelerating retrofit cycles across municipal fleets. NFPA 1901 and ECE R65 amendments are forcing simultaneous hardware upgrades and testing protocol investments.
Growth Catalysts
- SAE Class 1 intensity mandates:North American law enforcement agencies must replace legacy halogen systems to meet revised candela thresholds, triggering fleet-wide procurement waves.
- Energy efficiency targets:LED modules cut electrical draw by 70% versus xenon alternatives, enabling auxiliary equipment integration without alternator upgrades.
- Cooperative purchasing agreements:Multi-jurisdictional consortiums in Texas, California, and Florida aggregate volumes that justify dedicated manufacturing lines.
Market Restraints
- Aluminum and copper price volatility:Heat sink and conductor materials constitute 35% of LED module bill-of-materials, exposing margins to commodity swings.
- Photometric testing concentration:Only three certified laboratories in Germany, the United States, and Japan can validate ECE R65 compliance, creating certification bottlenecks.
- Strobe-based alternatives:Some European emergency services retain xenon strobe systems for extreme-weather visibility, slowing LED penetration in Nordic markets.
Strategic Opportunities
- Connected vehicle integration:V2X communication modules enable lights to auto-trigger based on dispatch system inputs, opening software-recurring revenue streams.
- Tow and recovery mandates:Pending state-level amber rear-warning requirements in the United States create a 400,000-vehicle retrofit addressable market.
- Direct-to-agency digital channels:Manufacturers bypassing distributor networks capture 15-20 point margin improvements while accelerating specification cycles.
Industry Challenges
- Photometric engineering talent scarcity:Fewer than 200 specialists globally possess combined optical design and regulatory compliance expertise.
- Legacy vehicle electrical incompatibility:Pre-2010 fleet architectures lack CAN bus infrastructure, requiring expensive harness retrofits.
- Multi-standard certification timelines:Simultaneous NFPA 1901, ECE R65, and SAE validation extends product launch windows by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emergency Vehicle Lights Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Bars, Spotlights, Hideaway Lights, Beacons Technology: LED, Strobe, Halogen, Xenon Application: Fire Services, Law Enforcement, Emergency Medical Services, Towing Services End User: Government Agencies, Private Contractors, Fire Departments, Ambulance Services |
| Companies Covered | Ultra Bright Lightz, HiViz Lighting, Whelen Engineering, LED Autolamps, TecNiq, Feniex, Sound Off Signal, SirenWorld, SpeedTech Lights, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emergency Vehicle Lights Market Evolving Landscape
Programmable flash patterns and spectral tuning are transforming emergency lighting from static hardware into configurable safety systems. Manufacturers now compete on software-defined photometric outputs rather than fixture geometry alone.
Multi-die LED arrays with independent channel control are consolidating market share among premium system integrators. Fire apparatus builders specify these modules to achieve zone-specific intensity zoning without mechanical shutters. The technology is consolidating supplier tiers by collapsing discrete optical, thermal, and driver subsystems into single-source platforms.
Pending amendments to ECE R65 testing protocols will mandate horizontal plane uniformity measurements that current reflector designs fail. German technical inspection associations are piloting automated goniometer systems that reduce certification cycles from 90 to 21 days. Fire apparatus OEMs in Scandinavia are pre-qualifying suppliers against draft standards to secure 2027 model year placements.
Fleet operators are unbundling installation and maintenance from equipment procurement, treating warning systems as capital assets with 10-year service life planning. Cooperative purchasing agreements in the United States now specify lifecycle cost metrics that favor LED longevity claims. Municipal procurement officers in California and Texas require documented lumen maintenance curves at 25,000-hour intervals.
Emergency Vehicle Lights Market Segmentation
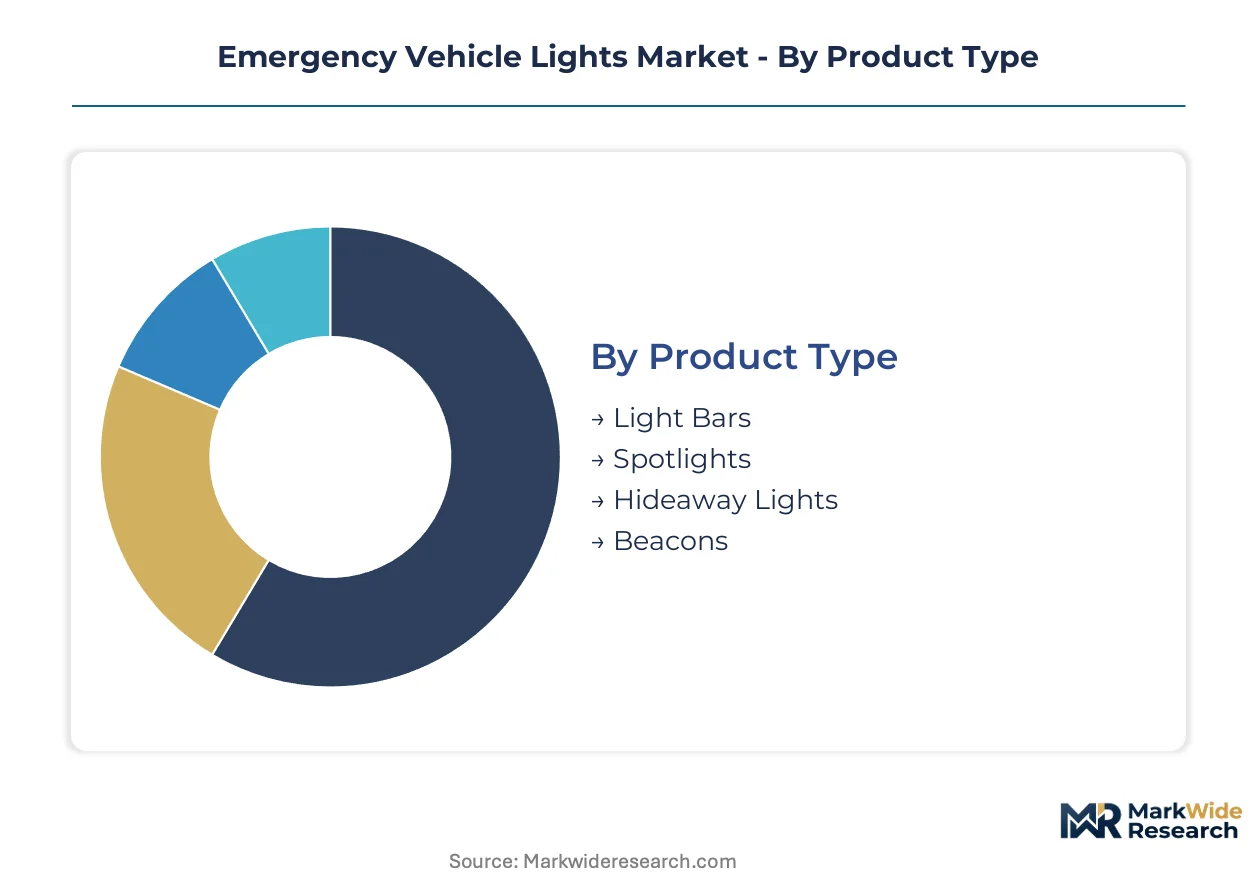
Segmentation in emergency vehicle lighting reflects divergent procurement priorities across public safety verticals. Municipal fleet managers prioritize lifecycle cost metrics, while federal grant programs shape technology adoption timelines. Understanding these segment boundaries clarifies where specification power concentrates and where margin compression threatens.
Product Type:
Fixture geometry determines mounting integration complexity and peripheral equipment compatibility, making physical form factor the primary filter in fleet specification processes.
- Light Bars:Roof-mounted linear assemblies integrate siren housings, speaker enclosures, and antenna mounting platforms into unified aerodynamic profiles. Fire apparatus builders in the United States specify these for NFPA 1901 compliance on pumper and aerial platforms. Demand concentrates among municipal departments consolidating procurement through cooperative agreements in Texas and California.
- Spotlights:Directional high-intensity modules deliver focused candela output for perimeter illumination and suspect apprehension scenarios. Law enforcement agencies prioritize these for traffic stop safety and rural search operations. Specifications from the California Highway Patrol influence adoption patterns across western states.
- Hideaway Lights:Concealed grille and surface-mount strobes enable rapid deployment without permanent roof penetration. Private security contractors favor these for unmarked vehicle flexibility.
- Beacons:Rotating or fixed-mount omnidirectional warning devices serve auxiliary and secondary vehicle applications. Towing operators specify amber variants pending state mandate expansions.
Light bars lead on scale; hideaway lights lead on momentum.
Technology:
Energy efficiency mandates and extended service life requirements are compressing the viable technology set, with electrical architecture compatibility now governing retrofit versus new-build decisions.
- LED:Solid-state semiconductor emitters deliver programmable spectral output, 50,000-hour operational lifespans, and 70% electrical draw reduction versus legacy alternatives. Multi-die arrays with independent channel control enable zone-specific intensity zoning without mechanical shutters. Municipal procurement officers in Texas and California now require documented lumen maintenance curves at 25,000-hour intervals.
- Strobe:Xenon gas-discharge systems retain installed base in extreme-weather visibility applications. Nordic emergency services specify these for ice fog penetration where LED spectral output scatters.
- Halogen:Tungsten-filament incandescent technology persists only in pre-2010 fleet retrofits where CAN bus infrastructure is absent.
- Xenon:High-intensity discharge arc lamps face accelerating displacement except in specialized high-candela niche applications.
LED dominates installed value; strobe defends regional pockets.
Application:
Jurisdictional regulatory frameworks create non-overlapping specification territories, with color chromaticity and flash pattern mandates varying by emergency service category.
- Fire Services:Red-dominant warning systems with specific horizontal plane intensity distributions governed by NFPA 1901. Apparatus builders pre-qualify suppliers against draft ECE R65 amendments to secure future model year placements.
- Law Enforcement:Blue and red combination systems with programmable pursuit and traffic control sequences. SAE Class 1 intensity mandates trigger fleet-wide procurement waves as agencies replace legacy halogen installations.
- Emergency Medical Services:White and amber augmentation for scene illumination alongside primary warning functions. Specifications emphasize electrical compatibility with life support equipment loads.
- Towing Services:Amber-dominant rear and side warning systems. Pending state-level mandates in the United States create retrofit addressable market expansion.
Fire services anchor procurement volume; towing services present steepest expansion trajectory.
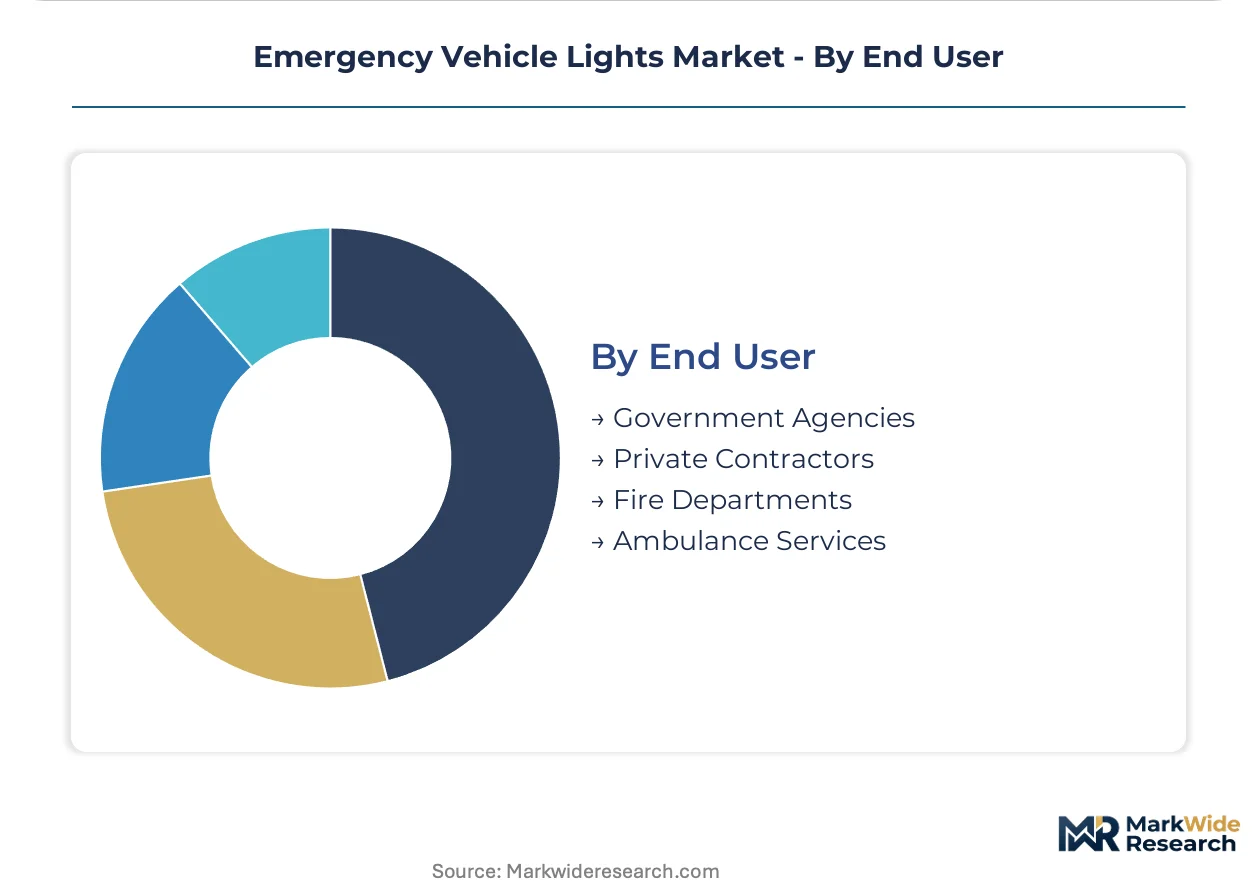
End User:
Funding mechanism and specification authority fragmentation creates distinct sales cycle dynamics, with grant-funded federal programs operating on different timelines than municipal capital budgets.
- Government Agencies:Federal, state, and municipal fleet operators with cooperative purchasing agreement access. Procurement concentrates through aggregated volume contracts in Texas, California, and Florida consortiums.
- Private Contractors:Commercial towing, security, and industrial emergency response operators with price-sensitive specification criteria. Direct-to-agency digital channels capture margin improvements in this segment.
- Fire Departments:Specialized apparatus OEM relationships with 10-year service life planning and lifecycle cost evaluation frameworks.
- Ambulance Services:Hospital-based and municipal third-service operators with electrical integration priorities for patient care equipment.
Government agencies command procurement scale; private contractors drive channel innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany enforces ECE R65 amendments with automated goniometer testing, while the United States channels federal grants toward municipal LED retrofits. Regulatory divergence is compressing certification timelines in Europe and accelerating procurement waves across North American fleets.
United States
Federal grant programs fund municipal fleet modernization across Texas, California, and Florida cooperative purchasing consortiums. NFPA 1901 standards tighten photometric requirements for fire apparatus lighting nationwide. Detroit-area automotive electronics clusters supply integrated warning system platforms to major apparatus builders.
Germany
KBA-validated ECE R65 testing bottlenecks concentrate supplier qualification efforts among three certified laboratories. Draft amendments mandate horizontal plane uniformity measurements that reshape reflector engineering priorities. Stuttgart technical inspection associations pilot automated certification cycles reducing validation from 90 to 21 days.
United Kingdom
SAE Class 1 intensity thresholds influence specification patterns for law enforcement vehicle imports from North American suppliers. ECE R10 electromagnetic compatibility regulations govern warning device approval alongside R65 photometric standards. West Midlands emergency vehicle conversion specialists integrate multi-die LED arrays for zone-specific intensity zoning.
Japan
METI energy efficiency targets drive LED displacement of xenon strobe systems in metropolitan police and fire departments. JIS standards for emergency vehicle equipment create parallel certification pathways distinct from ECE protocols. Nagoya automotive lighting clusters develop thermal management solutions for high-candela multi-die arrays.
Canada
Health Canada electromagnetic emissions guidelines intersect with provincial fleet procurement standards for emergency services vehicles. Ontario municipal cooperative purchasing agreements aggregate volumes comparable to mid-sized US states. Toronto-area vehicle upfitters specialize in cold-weather LED reliability engineering for Arctic territory deployments.
Emergency Vehicle Lights Market Competitive Landscape
United States producers anchor one tier; European specialists hold certification-intensive positions. The supplier base stratifies across domestic manufacturing scale, direct-to-agency digital channels, and photometric engineering depth. Three archetypes dominate: vertically integrated domestic manufacturers, digitally native direct sellers, and specialized law enforcement configurators. Capacity expansion and cooperative purchasing alignment represent the dominant competitive moves.
Within the integrated manufacturing tier, Whelen Engineering occupies a position exemplifying domestic production scale. Sound Off Signal represents specialized configurators targeting law enforcement-specific requirements. Feniex anchors the digitally native archetype with direct-to-agency channel structures that bypass traditional distributor networks.
| Leading Market Players |
|---|
| Ultra Bright Lightz |
| HiViz Lighting |
| Whelen Engineering |
| LED Autolamps |
| TecNiq |
| Feniex |
| Sound Off Signal |
| SirenWorld |
| SpeedTech Lights |
| Others |
Value Network & Pricing Analysis
Aluminum and copper price volatility cascades through LED module manufacturing, compressing margins on heat sink and conductor components that constitute over one-third of bill-of-materials costs. Municipal cooperative purchasing agreements in Texas and California aggregate volumes sufficient to command contract-based pricing, while smaller private contractors absorb spot-market commodity swings.
Pricing Analysis
Capacity additions in domestic United States manufacturing are reshaping price floors for NFPA 1901-compliant fire apparatus lighting systems. Three-tier pricing structure across premium multi-die arrays, standard integrated light bars, and economy hideaway modules stratifies by certification grade and photometric testing depth. Pricing pressure stems from LED photometric standardization commoditizing base specifications. Government agencies with cooperative purchasing access exhibit lowest price sensitivity; private security contractors demonstrate highest elasticity.
Supply Chain Analysis
Photometric engineering talent scarcity in Germany, Japan, and the United States constrains certified manufacturing expansion. Supply draws from aluminum extrusion facilities in Michigan, semiconductor packaging operations in Nagoya, and optical lens foundries in Stuttgart. Single-source vulnerability concentrates in ECE R65 testing laboratories, where only three certified facilities validate European market entry. Distribution runs through municipal procurement consortiums and direct-to-agency digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as fleet operators unbundle installation from equipment procurement and mandate documented lumen maintenance curves at 25,000-hour intervals. Specification power is shifting toward lifecycle cost evaluation frameworks that favor premium LED longevity claims.
For Market Incumbents: Extend certification investment pipelines to capture pending ECE R65 amendment cycles and secure 2027 model year placements with Scandinavian fire apparatus OEMs. Defensive consolidation around automated goniometer testing partnerships reduces validation bottlenecks from 90 to 21 days. Backward integration into aluminum heat sink manufacturing mitigates commodity exposure. For New Entrants and Emerging Players: Private towing contractors with pending state-level amber rear-warning mandates represent the most penetrable buyer archetype. Direct-to-agency digital channels bypass 15-20 point distributor markups while accelerating specification cycles. White-space exists in connected vehicle integration software for V2X communication modules. For Investors and Strategic Acquirers: Roll-up economics work for specialized law enforcement configurators because photometric engineering talent scarcity limits organic replication of regulatory compliance expertise. Five-to-ten year viability hinges on cooperative purchasing alignment with Texas, California, and Florida consortiums. Watch for automated certification cycle compression as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Standard Certification Investment | Simultaneous NFPA 1901, ECE R65, and SAE validation secures cross-jurisdictional market access. |
| Automated Goniometer Testing Partnership | German technical inspection association pilots reduce ECE R65 validation cycles from 90 to 21 days. |
| Direct-to-Agency Digital Channel Buildout | Manufacturer bypass of distributor networks captures 15-20 point margin improvements. |
| Connected Vehicle Software Development | V2X communication modules enable auto-triggered lights based on dispatch system inputs. |
| Cooperative Purchasing Agreement Alignment | Texas, California, and Florida consortiums aggregate volumes justifying dedicated manufacturing lines. |
Research Methodology
Direct dialogue with municipal fleet procurement officers, fire apparatus OEM specification engineers, photometric testing laboratory directors, and cooperative purchasing consortium administrators grounded qualitative findings. Secondary validation drew from NFPA 1901 amendment dockets, ECE R65 regulatory filings, KBA certification databases, and SAE technical standards documentation. Bottom-up installation volume estimates triangulated against top-down municipal capital expenditure budgets.
Segment-level value outputs across the projection horizon reflect product type, technology, application, and end user dimensions with regional regulatory cluster overlays. CAGRs were derived from installed base replacement cycles and cooperative purchasing volume trajectories. Forecast inputs incorporated LED lumen maintenance curves, aluminum commodity price bands, and photometric engineering labor availability constraints.
Underlying measurement precision varies by segment; government agency procurement with cooperative purchasing agreement access carries tighter precision than fragmented private contractor demand. Forecasts reflect assumptions on NFPA 1901 amendment adoption timelines and ECE R65 horizontal plane uniformity mandate implementation. Material deviation in federal grant program funding levels or ECE R65 testing laboratory capacity expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Global Automotive Electronic Stability Control Systems Market
Automotive Safety and Security Systems
Driver Drowsiness Monitoring System Market
Automotive Safety and Security Systems
Active Spoiler Market
Automotive Safety and Security Systems
Advanced Suspension Control System Market
Automotive Safety and Security Systems
Automotive Seat Belt Pretensioner Market
Automotive Safety and Security Systems
Airbag Control Unit Sensor Market
Automotive Safety and Security Systems
Pedestrian Protection System Market
Automotive Safety and Security Systems
Two Wheeler Anti-Lock Braking System Market
Automotive Safety and Security Systems
Global Emergency Locking Retractor Seatbelt Market
Automotive Safety and Security Systems
United States Automotive Collision Avoidance Systems Market
Automotive Safety and Security Systems
Automotive Driver State Monitoring Systems Market
Automotive Safety and Security Systems
Automotive Radar Market
Automotive Safety and Security Systems
Automotive Seat Belt System Market
Automotive Safety and Security Systems
Automotive Shielding Market
Automotive Safety and Security Systems
Global Automotive Hill Descent Control Market
Automotive Safety and Security Systems
Automotive Intelligent Headlight System Market