
 Canada Automotive Adaptive Lighting System Market | 2026-2036
Canada Automotive Adaptive Lighting System Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Automotive Adaptive Lighting System Market Outlook
Luxury SUV and electric vehicle lineups are repositioning adaptive lighting from option packages to standard equipment tiers. HELLA KGaA Hueck & Co. leverages its Windsor engineering center to sustain prototype-to-production cycles for Detroit Three programs. Valeo Group anchors its Canadian aftermarket presence through Quebec distribution hubs serving collision repair networks. Osram Licht AG competes on LED module specialization for tier-one headlamp integrators.
Automotive adaptive lighting systems modulate beam patterns through sensor fusion, camera input, and mechatronic actuators to optimize road illumination without glare to oncoming traffic. Matrix LED arrays partition light sources into individually addressable segments operating at PWM frequencies above 200 Hz to prevent perceptible flicker while enabling selective dimming zones. Factory-installed LED configurations dominate unit economics due to wiring harness integration complexity and calibration requirements at vehicle assembly. Intelligent high beam technology captures expanding margin pools as camera resolution and neural classification algorithms reduce false-positive glare triggering.
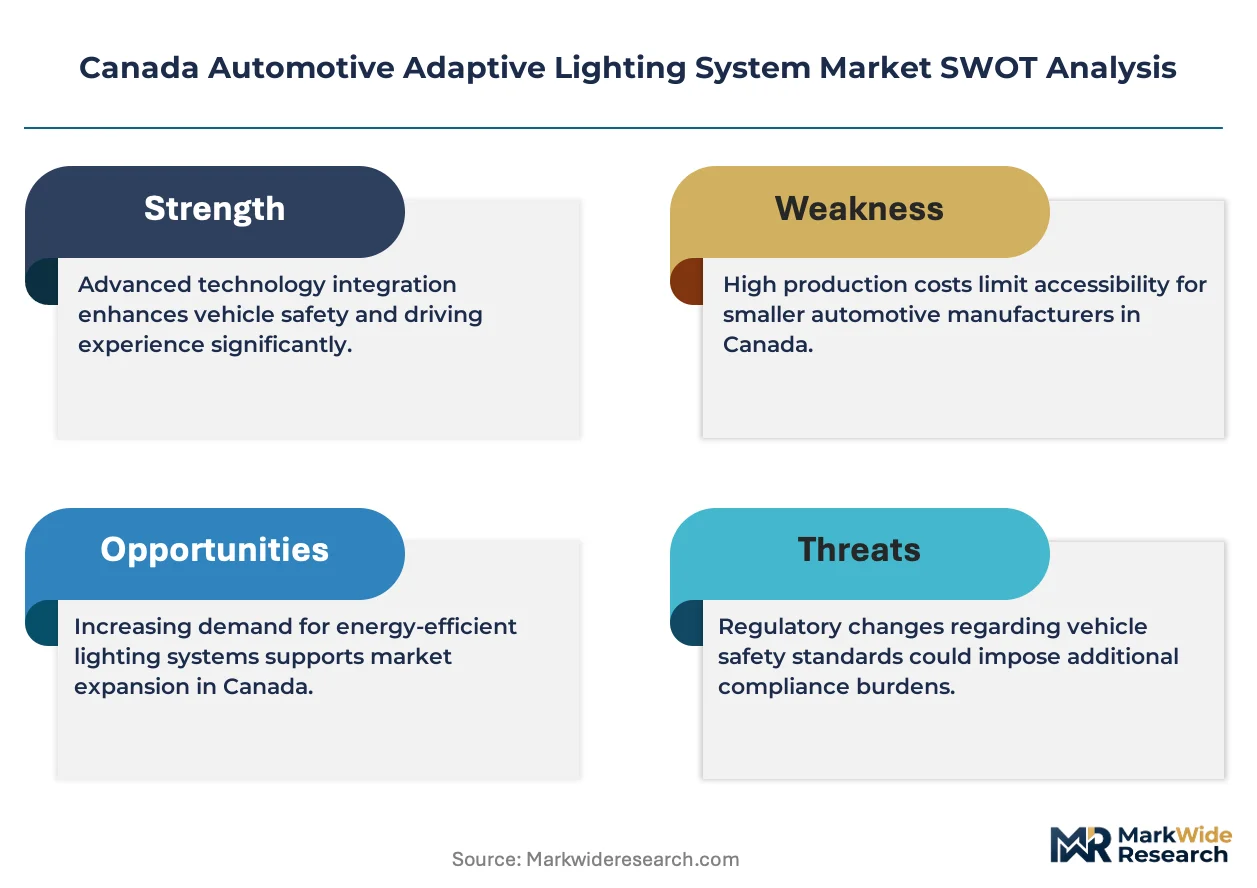
Transport Canada administers CMVSS 108 compliance verification for headlamp photometric performance, while provincial ministries of transportation enforce periodic safety inspection standards affecting retrofit market access. Health Canada and PMRA coordinate on rare earth phosphor material handling guidelines embedded in LED supply chain audits. Stakeholders must monitor proposed amendments to CMVSS 108 addressing adaptive driving beam equivalence with UNECE R48 provisions.
Market Dynamics
Transport Canada's CMVSS 108 compliance pathways for matrix beam equivalence are compressing certification timelines while Ontario's automotive corridor concentrates prototype-to-production cycles for Detroit Three electrification programs.
Growth Catalysts
- Matrix LED standardization:PWM frequencies above 200 Hz eliminate perceptible flicker while enabling selective dimming zones, accelerating OEM platform adoption across luxury and mid-tier vehicle lineups.
- Health Canada phosphor guidelines:Rare earth material handling audits embedded in LED supply chains are driving vertical quality integration among tier-one headlamp assemblers.
- Detroit-Windsor assembly networks:Proximity engineering centers sustain same-day prototype iteration cycles for adaptive driving beam calibration at vehicle assembly.
Market Restraints
- Wiring harness integration complexity:Factory-installed LED configurations require dedicated calibration infrastructure that locks out independent retrofit channels.
- Provincial inspection standard fragmentation:Ministry of transportation safety inspection variations across Quebec, Ontario, and British Columbia create aftermarket access friction.
- UNECE R48 compliance gaps:Pending CMVSS 108 amendments addressing adaptive driving beam equivalence extend product certification timelines for non-harmonized designs.
Strategic Opportunities
- Collision repair network penetration:Quebec distribution hubs serving aftermarket channels capture margin pools from insurance-totalled luxury vehicle recovery.
- Neural classification algorithm advancement:Camera resolution improvements reduce false-positive glare triggering, expanding intelligent high beam technology addressability.
- Electric vehicle platform integration:Dedicated 48V electrical architectures in battery-electric lineups eliminate alternator-driven voltage fluctuation constraints on adaptive actuator performance.
Industry Challenges
- Mechatronic actuator calibration:Sensor fusion integration with legacy vehicle CAN bus architectures requires specialized firmware engineering capacity concentrated in Windsor and Detroit engineering centers.
- Photometric performance verification:CMVSS 108 headlamp testing protocol updates demand capital-intensive darkroom facility investment for tier-two suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Automotive Adaptive Lighting System Market |
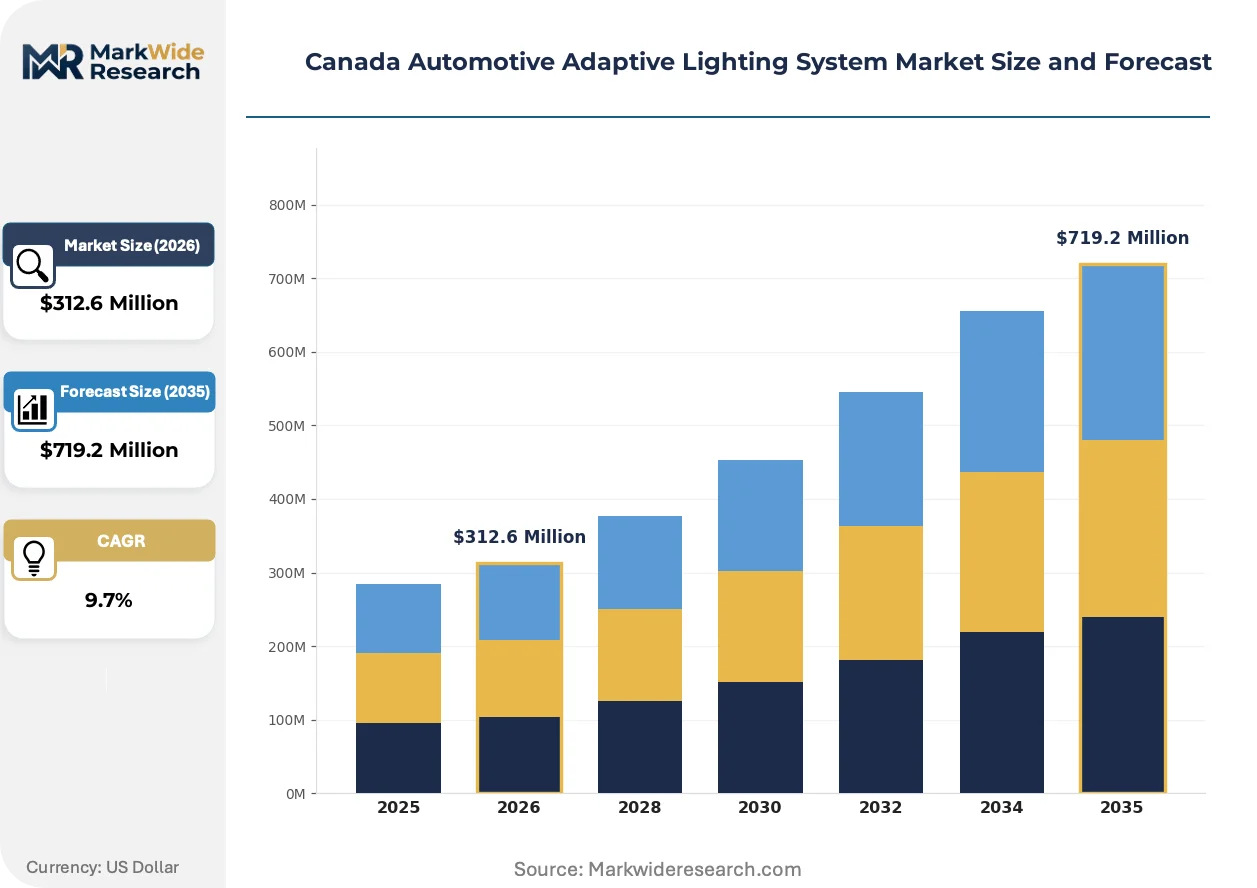
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $719.2 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, HID, Halogen, Laser Technology: Dynamic Bending, Intelligent High Beam, Automatic Leveling, Matrix Lighting End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Dealerships Installation: Factory Installed, Retrofitted, Modular, Integrated |
| Companies Covered | HELLA KGaA Hueck & Co., Valeo Group, Koninklijke Philips N.V., Stanley Electric Co. Ltd, Osram Licht AG, Koito Manufacturing Co. Ltd, Hyundai Mobis, Magneti Marelli SpA, ZKW Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Automotive Adaptive Lighting System Market Strategic Shifts
Adaptive lighting technology trajectories are compressing development cycles through sensor fusion convergence while regulatory harmonization pressures reshape certification strategies across provincial jurisdictions.
Digital micromirror device technology is overtaking traditional mechanical shutter systems for selective beam masking. Premium SUV and electric vehicle lineups adopt solid-state actuation for sub-100-millisecond response times. This shift is overtaking electromechanical relay architectures in next-generation headlamp control modules.
Transport Canada's proposed CMVSS 108 amendments addressing adaptive driving beam equivalence with UNECE R48 provisions are forcing dual-homologation strategies for cross-border vehicle programs. Tier-one integrators must maintain parallel certification documentation for US and Canadian regulatory submissions. Ontario-based engineering centers are absorbing additional compliance personnel to manage submission timeline compression.
Fleet procurement for rental and corporate vehicle pools is consolidating specification authority at national headquarters, displacing dealer-level option package discretion. Standard-fit adaptive lighting suites are replacing à la carte configuration in three-year lease structures. This concentration is most visible in Toronto and Vancouver corporate fleet management contracts where total cost of ownership calculations now embed lighting technology residual value premiums.
Canada Automotive Adaptive Lighting System Market Segmentation
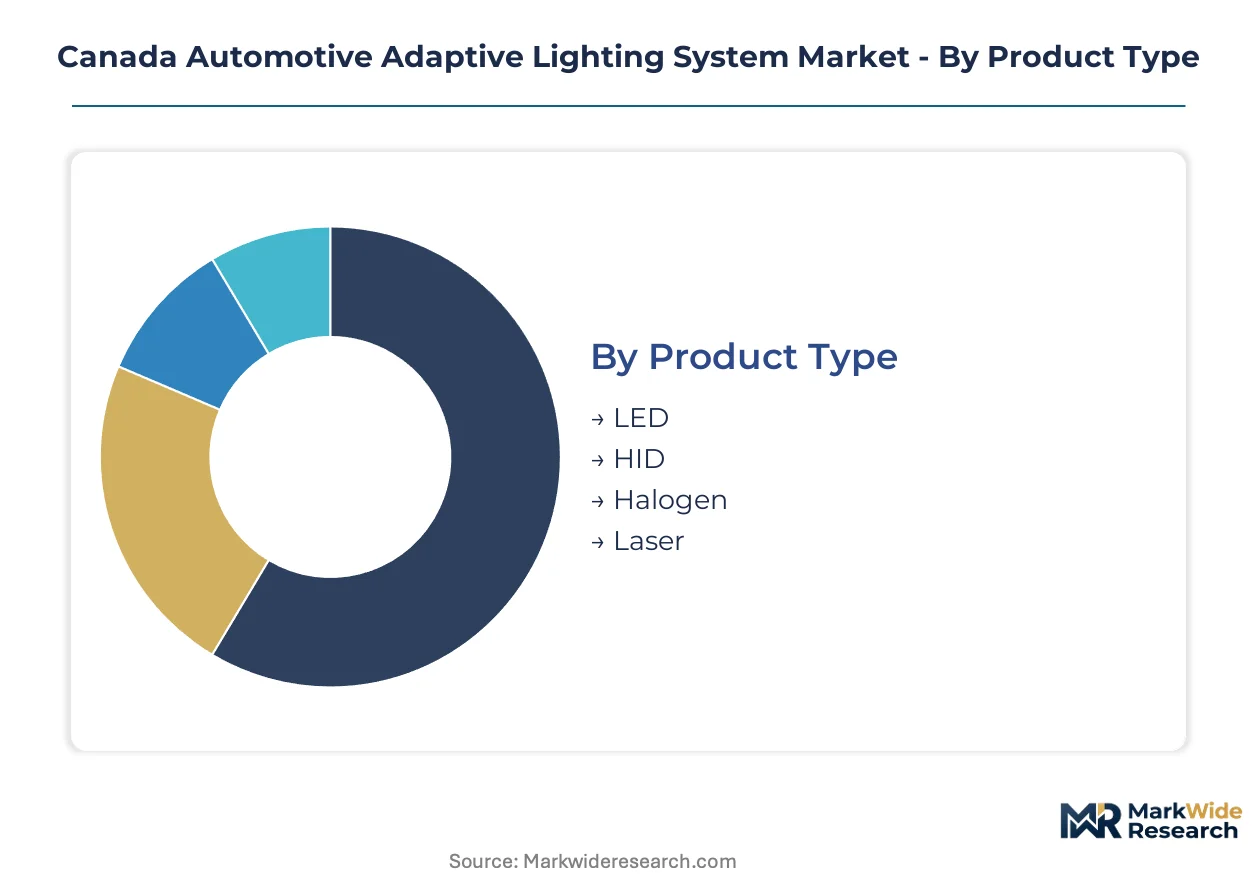
Adaptive lighting segmentation in Canada reflects divergent certification burdens across factory and retrofit channels. CMVSS 108 compliance pathways vary sharply by product architecture and installation method, reshaping margin structures and competitive positioning.
Product Type:
LED and laser configurations trigger Transport Canada photometric verification under CMVSS 108 matrix beam equivalence proposals, while HID and halogen variants operate under legacy certification frameworks with compressed documentation requirements.
- LED:Matrix LED arrays partition illumination into individually addressable segments operating at PWM frequencies above 200 Hz. Ontario's Detroit-Windsor assembly corridor concentrates demand as luxury and electric vehicle lineups standardize LED configurations for 48V electrical architectures.
- HID:High-intensity discharge systems maintain aftermarket relevance through Quebec collision repair networks serving insurance-totalled vehicle recovery. Provincial inspection standard fragmentation across Ontario, Quebec, and British Columbia constrains retrofit channel expansion for non-factory HID installations.
- Halogen:Legacy incumbent in economy vehicle segments with minimal adaptive functionality.
- Laser:Premium tier technology requiring specialized Health Canada phosphor material handling audits.
Leading the category by volume: LED. Growing fastest: Laser.
Technology:
Cost tier stratification separates premium matrix and intelligent high beam systems from standard dynamic bending and automatic leveling offerings, with neural classification algorithms driving price differentiation at the top end.
- Matrix Lighting:Digital micromirror devices enable sub-100-millisecond selective beam masking without mechanical shutters. Toronto and Vancouver corporate fleet procurement contracts now specify matrix lighting as standard-fit equipment in three-year lease structures, displacing dealer-level option discretion.
- Intelligent High Beam:Camera fusion with neural classification reduces false-positive glare triggering. Windsor engineering centers sustain same-day prototype iteration cycles for Detroit Three electrification programs integrating intelligent high beam calibration.
- Dynamic Bending:Entry-level adaptive functionality with mechatronic actuator control.
- Automatic Leveling:Load-compensation technology standard in mid-tier SUV platforms.
Commanding premium pricing: Matrix Lighting. Expanding most quickly: Intelligent High Beam.
End User:
Application concentration varies sharply between vehicle assembly integration requiring dedicated calibration infrastructure and aftermarket channels constrained by provincial safety inspection fragmentation.
- OEMs:Factory-installed configurations dominate unit economics through wiring harness integration complexity and vehicle assembly calibration requirements. OEM specification authority is consolidating at national headquarters for rental and corporate fleet procurement.
- Vehicle Assemblers:Detroit-Windsor networks anchor prototype-to-production cycles with proximity engineering centers enabling adaptive driving beam calibration at line speed.
- Aftermarket Providers:Quebec distribution hubs serve collision repair networks with regulatory access friction from provincial inspection variations.
- Dealerships:Dealer-level option package discretion is contracting as fleet procurement centralizes.
Capturing dominant volume: OEMs. Gaining share fastest: Vehicle Assemblers.
Installation:
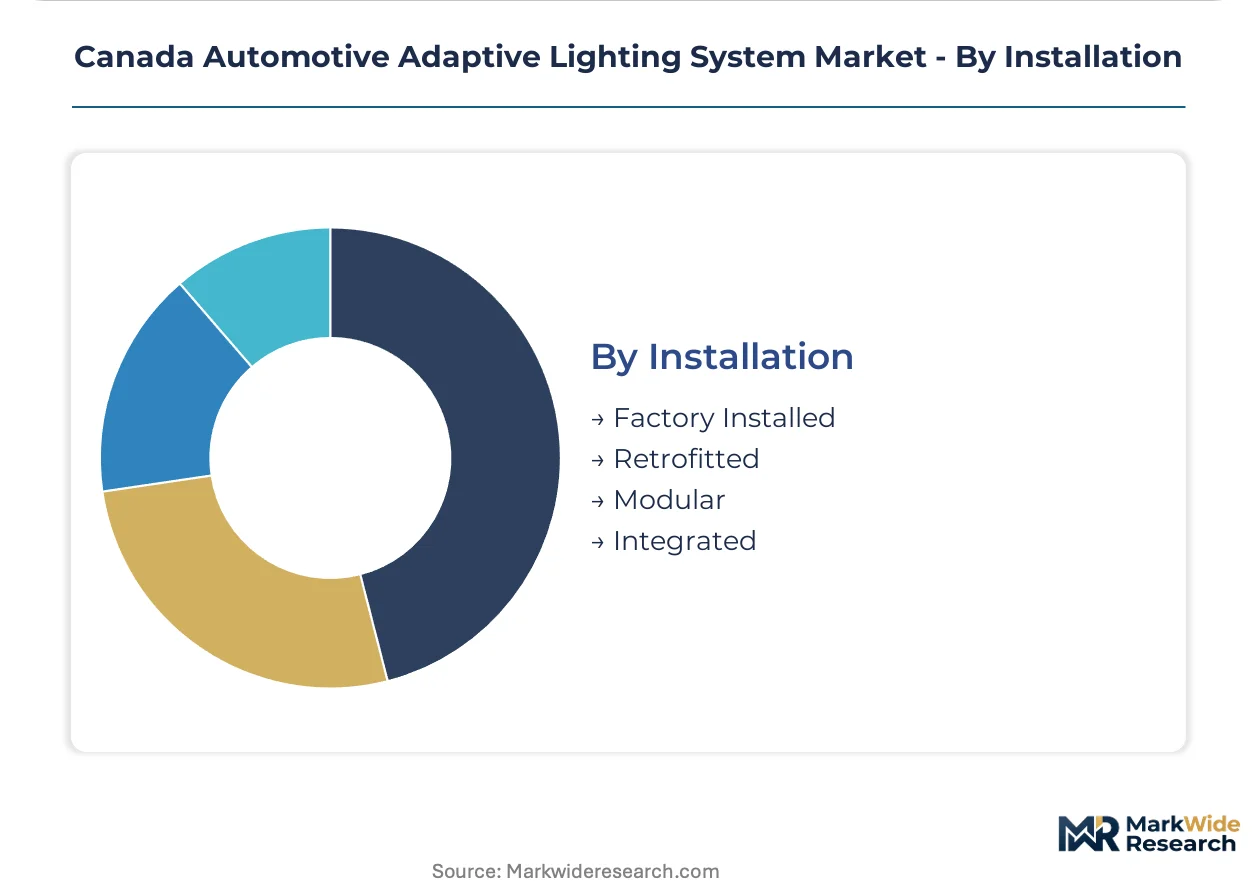
Supply concentration in Ontario's automotive corridor favors factory and integrated methods, while modular and retrofitted approaches face aftermarket access barriers from CMVSS 108 compliance complexity.
- Factory Installed:Dedicated calibration infrastructure at vehicle assembly locks in revenue concentration. UNECE R48 compliance gaps in pending CMVSS 108 amendments extend certification timelines for cross-border programs, forcing dual-homologation strategies.
- Integrated:Solid-state actuation architectures eliminate electromechanical relay systems in next-generation headlamp control modules.
- Modular:Reduced channel presence due to wiring harness integration barriers.
- Retrofitted:Minimal market penetration constrained by provincial inspection standard fragmentation and CMVSS 108 photometric performance verification requirements.
Holding volume leadership: Factory Installed. Steepest expansion trajectory: Integrated.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian production concentrates in Ontario's automotive corridor while consumption distributes across provincial fleet procurement centers. Transport Canada's CMVSS 108 standards create regulatory differentiation from US NHTSA pathways. Health Canada phosphor guidelines impose additional compliance layers on LED supply chains.
Ontario
Detroit-Windsor assembly networks anchor prototype-to-production cycles for Detroit Three electrification programs. Transport Canada administers CMVSS 108 compliance verification through Toronto-area testing facilities. Windsor engineering centers sustain same-day adaptive driving beam calibration iterations for cross-border vehicle programs.
Quebec
Montreal distribution hubs serve collision repair networks recovering insurance-totalled luxury vehicles. Provincial ministry of transportation safety inspection standards diverge from Ontario protocols, creating aftermarket access friction. Valeo Group anchors aftermarket presence through Quebec logistics infrastructure serving eastern Canadian repair channels.
British Columbia
Vancouver corporate fleet procurement contracts specify standard-fit adaptive lighting in three-year lease structures. Provincial inspection variations compress retrofit channel economics compared to factory-installed configurations. Pacific port access supports LED module import logistics for tier-one headlamp integrators serving western Canadian vehicle assembly.
Alberta
Calgary energy sector fleet operators prioritize lighting technology residual value calculations in total cost of ownership models. Provincial safety inspection protocols align more closely with federal CMVSS 108 than Quebec or British Columbia variations. Edmonton distribution nodes serve prairie aftermarket channels with reduced regulatory friction compared to coastal provinces.
Canada Automotive Adaptive Lighting System Market Competitive Environment
Top-tier vendors anchor factory-installed LED configurations, while mid-tier specialists occupy collision repair and aftermarket retrofit channels. The vendor base stratifies across tier-one headlamp integrators, LED module specialists, and mechatronic actuator suppliers. German and Japanese automotive lighting conglomerates represent the consolidated archetype, while European component specialists exemplify the technology-licensing tier. Dominant competitive moves include dual-homologation strategies for cross-border certification and vertical integration into rare earth phosphor supply chains.
Among Germany-based lighting conglomerates, HELLA KGaA Hueck & Co. and Osram Licht AG occupy positions within the tier-one integration tier, while Valeo Group exemplifies the European component specialist archetype with Quebec distribution infrastructure. These three entities represent the competitive core serving Detroit-Windsor assembly networks and Canadian aftermarket channels through differentiated regulatory compliance capabilities.
| Leading Market Players |
|---|
| HELLA KGaA Hueck & Co. |
| Valeo Group |
| Koninklijke Philips N.V. |
| Stanley Electric Co. Ltd |
| Osram Licht AG |
| Koito Manufacturing Co. Ltd |
| Hyundai Mobis |
| Magneti Marelli SpA |
| ZKW Group |
| Others |
Value Chain & Pricing Dynamics
Detroit Three procurement consolidation at platform-engineering centers anchors contract-based long-term offtake pricing for factory-installed LED configurations, compressing margin negotiation leverage for tier-two module suppliers.
Pricing Analysis
Margin tightening in aftermarket retrofit channels traces to provincial inspection standard fragmentation across Ontario, Quebec, and British Columbia, which elevates compliance documentation costs for non-factory installations. Three-tier pricing structure across premium matrix systems, standard dynamic bending offerings, and economy halogen tiers separates OEM specification grades. Pricing pressure intensifies in collision repair segments as insurance-totalled vehicle recovery volumes fluctuate. Tier-one headlamp integrators exhibit lowest price sensitivity due to captive supply relationships with Detroit-Windsor assemblers.
Supply Chain Analysis
Rare earth phosphor supply rests on Chinese and Malaysian specialty chemical producers subject to Health Canada material handling audit requirements. LED die sourcing concentrates in Taiwan, South Korea, and Japan, while mechatronic actuator production centers on Germany and Mexico. Single-source vulnerability in digital micromirror device fabrication creates chokepoint exposure for matrix beam suppliers. Distribution runs through Ontario-based tier-one integrators feeding Detroit-Windsor assembly networks with same-day calibration capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transport Canada's CMVSS 108 matrix beam equivalence pathways construct a cost-of-compliance moat that rewards pre-certified incumbents while filtering speculative entrants lacking darkroom photometric verification infrastructure.
For Market Incumbents: Anticipate neural classification algorithm commoditization by locking firmware engineering capacity at Windsor and Detroit engineering centers. Backward integration into rare earth phosphor supply chains defends margin position against Health Canada audit cost inflation. Dual-homologation documentation investments for cross-border vehicle programs preempt UNECE R48 compliance gap exposure. For New Entrants and Emerging Players: Enter via Quebec collision repair network penetration where provincial inspection friction has suppressed incumbent aftermarket investment. Insurance-totalled luxury vehicle recovery represents the most penetrable white-space, with Valeo Group's distribution infrastructure leaving service gaps in Atlantic Canada. Go-to-market execution should anchor on rapid CMVSS 108 certification for HID retrofit configurations under legacy documentation frameworks. For Investors and Strategic Acquirers: Distressed-cycle entries favor tier-two LED module specialists with dormant Health Canada phosphor handling certifications in Ontario. Long-term viability hinges on 48V electrical architecture adoption in battery-electric platforms eliminating voltage fluctuation constraints. Watch Detroit Three electrification program cadence as inflection signal for adaptive driving beam content-per-vehicle expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Matrix Beam Certification Investment | Darkroom facility capital deployment satisfies CMVSS 108 photometric verification requirements for OEM qualification. |
| Quebec Distribution Hub Expansion | Montreal logistics infrastructure captures collision repair margin pools from insurance-totalled luxury vehicle recovery. |
| Neural Classification Algorithm Licensing | Camera fusion IP partnerships reduce false-positive glare triggering for intelligent high beam calibration. |
| 48V Electrical Architecture Integration | Battery-electric platform wiring harness design eliminates alternator-driven voltage constraints on actuator performance. |
| Dual-Homologation Documentation Systems | Parallel CMVSS 108 and UNECE R48 submission management compresses cross-border program certification timelines. |
Study Parameters
Multi-period observation of Detroit Three electrification program cadence, CMVSS 108 amendment trajectories, and LED content-per-vehicle trends anchored the trend analysis, supplemented by interviews with tier-one headlamp integrator procurement directors, OEM platform engineers, Windsor engineering center technical leads, Quebec collision repair network operators, and Transport Canada compliance verification officers. Secondary validation drew from vehicle production databases, IHS Markit registration data, Health Canada phosphor handling audit disclosures, and provincial ministry of transportation inspection standard filings. Bottom-up segment sizing triangulated against top-down automotive lighting expenditure estimates.
Segment-weighting across product type, technology tier, end-user channel, and installation method dimensions structured the analytical framework across the projection horizon. CAGRs derived from fitted growth curves applied to baseline penetration rates, with electric vehicle platform integration and fleet procurement centralization serving as primary demand-side inputs. Supply-side constraints incorporated rare earth phosphor supply chain audit capacity and mechatronic actuator firmware engineering scarcity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under CMVSS 108 amendment timing uncertainty and Detroit Three production schedule volatility. Forecasts reflect documented assumptions regarding regulatory harmonization progress and OEM specification authority consolidation. A small set of triggers—matrix beam standardization mandates, phosphor supply disruptions, and provincial inspection standard alignment—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Remote Vehicle Shutdown System Market
Automotive Safety and Security Systems
Two Wheeler Crash Guard Market
Automotive Safety and Security Systems
Automatic Emergency Braking Market
Automotive Safety and Security Systems
Electronic Stability Control System Market
Automotive Safety and Security Systems
Airbag Control Unit Sensor Market
Automotive Safety and Security Systems
Latin America Airbag Systems Market
Automotive Safety and Security Systems
Lane Change Assist Systems Market
Automotive Safety and Security Systems
Automotive Fusion Sensors Market
Automotive Safety and Security Systems
Automotive Seat Belt Sensor Market
Automotive Safety and Security Systems
Smart Motorcycle Helmet Market
Automotive Safety and Security Systems
Driver Monitoring System (DMS) Market
Automotive Safety and Security Systems
Ignition Interlock Devices Market
Automotive Safety and Security Systems
Global Automotive Radar Sensors Market
Automotive Safety and Security Systems
Driver Assistance System Market
Automotive Safety and Security Systems
United States Automotive Airbag Systems Market
Automotive Safety and Security Systems
Automotive Speed Alert System Market