
 Remote Vehicle Shutdown System Market | 2026-2036
Remote Vehicle Shutdown System Market Size, Share, and Industry Trends Forecast 2026-2036
Remote Vehicle Shutdown System Market Analytics
The capital-intensity divergence between hardware-heavy incumbents and software-native entrants is rotating competitive dynamics in remote vehicle shutdown systems. CalAmp leverages its telematics heritage to sustain integrated device-and-cloud offerings for fleet operators. Geotab competes through open-platform architecture that anchors third-party shutdown module compatibility. Samsara differentiates via real-time diagnostics layered with immobilization triggers for commercial vehicle managers.
Remote vehicle shutdown systems combine GPS tracking, cellular or satellite transceivers, and relay-controlled engine immobilizers to enable authorized parties to disable vehicle ignition remotely, typically operating on 12V automotive power with CAN bus integration for modern fleets. The primary commercial purpose centers on theft recovery, delinquent payment enforcement, and emergency fleet safety intervention. Software Platforms command margin pools through recurring subscription revenue, while IoT Solutions capture fastest expansion as edge-computing modules embed predictive disable logic at the device level. OEM Integration remains structurally constrained by automaker certification cycles, leaving Aftermarket channels to dominate near-term volume.
NHTSA mandates on vehicle safety communications, FCC regulations governing cellular spectrum for automotive telemetry, and state-level repossession compliance statutes collectively shape product certification and market access for shutdown system vendors. The EU AI Act and GDPR frameworks impose additional constraints on autonomous decision-to-disable algorithms in European deployments. Stakeholders must monitor evolving insurer data-sharing agreements and law enforcement warrant protocols that determine permissible activation authority across jurisdictions.
Market Dynamics
Cellular-enabled shutdown modules are consolidating fleet procurement decisions around integrated telematics platforms rather than standalone immobilization hardware, compressing vendor margins while elevating software subscription attach rates.
Growth Catalysts
- NHTSA vehicle-to-everything mandates:The agency's safety communication protocols require remote intervention capabilities in connected commercial vehicles, forcing fleet-wide upgrade cycles.
- Cellular IoT module cost compression:Mass production of LTE-M and NB-IoT chipsets has reduced hardware deployment thresholds for small fleet operators.
- Commercial fleet electrification:Electric vehicle architectures integrate shutdown logic natively through battery management systems, simplifying retrofit adoption.
Market Restraints
- Semiconductor supply concentration:Cellular modem and GPS receiver fabrication concentrates in Taiwanese and South Korean foundries, exposing hardware vendors to allocation volatility.
- GDPR algorithmic decision constraints:The EU AI Act restricts autonomous disable triggers without human authorization, complicating European rollout of predictive immobilization.
- CAN bus protocol fragmentation:Proprietary vehicle communication standards across automakers force costly per-model certification for aftermarket installers.
Strategic Opportunities
- Usage-based insurance integration:Insurer data-sharing partnerships in the United States enable premium discounts for fleets deploying verified shutdown systems.
- Edge-computing convergence:Predictive disable logic embedding at the device level reduces latency and cellular data costs for remote operations.
- Latin American stolen vehicle recovery:Brazil and Mexico lack mature repossession infrastructure, creating first-mover advantage for cellular-GPS hybrid platforms.
Industry Challenges
- Automotive cybersecurity certification:ISO/SAE 21434 compliance timelines extend 18-24 months for new shutdown module designs.
- Legacy fleet integration complexity:Pre-CAN bus vehicles require analog relay retrofitting, fragmenting installation protocols and technician training requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remote Vehicle Shutdown System Market |
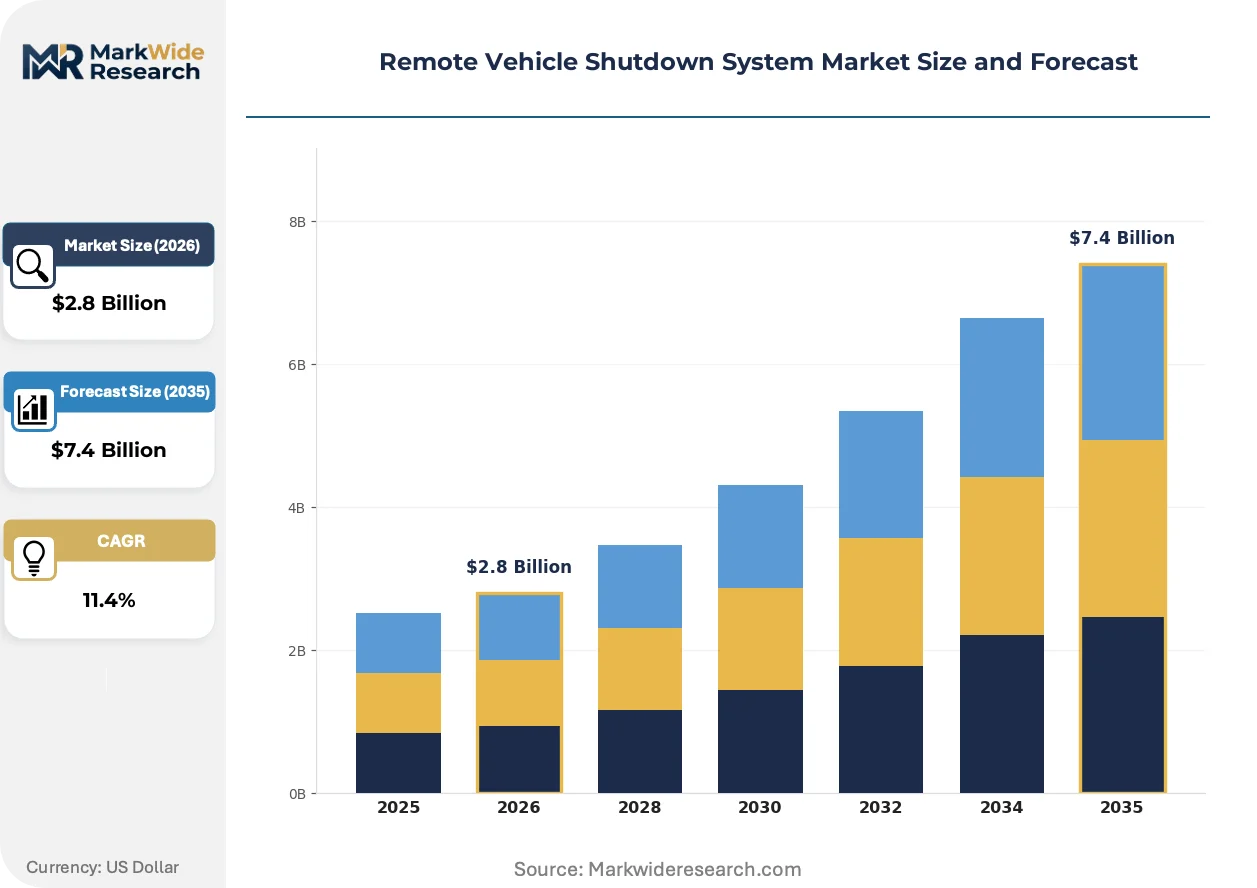
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPS Systems, IoT Solutions, Software Platforms, Security Modules End User: Fleet Operators, Law Enforcement, Insurance Companies, Ride-Sharing Services Technology: RFID, Cellular Network, Satellite Communication, Bluetooth Installation Type: Aftermarket, OEM Integration, Self-Installation, Professional Installation |
| Companies Covered | CalAmp, Verizon Connect, Teletrac Navman, Geotab, LoJack, Spireon, Guidepoint Systems, Samsara, PassTime, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remote Vehicle Shutdown System Market Evolving Landscape
Remote vehicle shutdown architectures are pivoting from reactive immobilization toward predictive intervention systems, embedding machine learning at the network edge while regulatory pressure hardens data governance requirements.
Edge-computing modules with localized inference engines are bifurcating the hardware market between basic relay-controlled units and intelligent platforms capable of pattern-based disable decisions. Large commercial fleets with centralized dispatch operations are adopting the advanced tier fastest. The technology split is compressing margins for commodity hardware vendors while expanding recurring software revenue pools.
The EU AI Act's risk classification framework for autonomous decision systems is forcing European deployments to maintain human-in-the-loop authorization protocols. Vendors must rearchitect cloud platforms to accommodate regional consent workflows. Aftermarket channels in Germany and France are absorbing the compliance costs through extended certification cycles.
Fleet procurement departments are consolidating vendor relationships around full-stack telematics providers rather than sourcing shutdown hardware separately. Small and mid-size fleet operators in the United States are abandoning point solutions for bundled subscription contracts. This concentration is visible most acutely in last-mile delivery and construction equipment verticals where total cost of ownership visibility dominates capital allocation decisions.
Remote Vehicle Shutdown System Market Segmentation
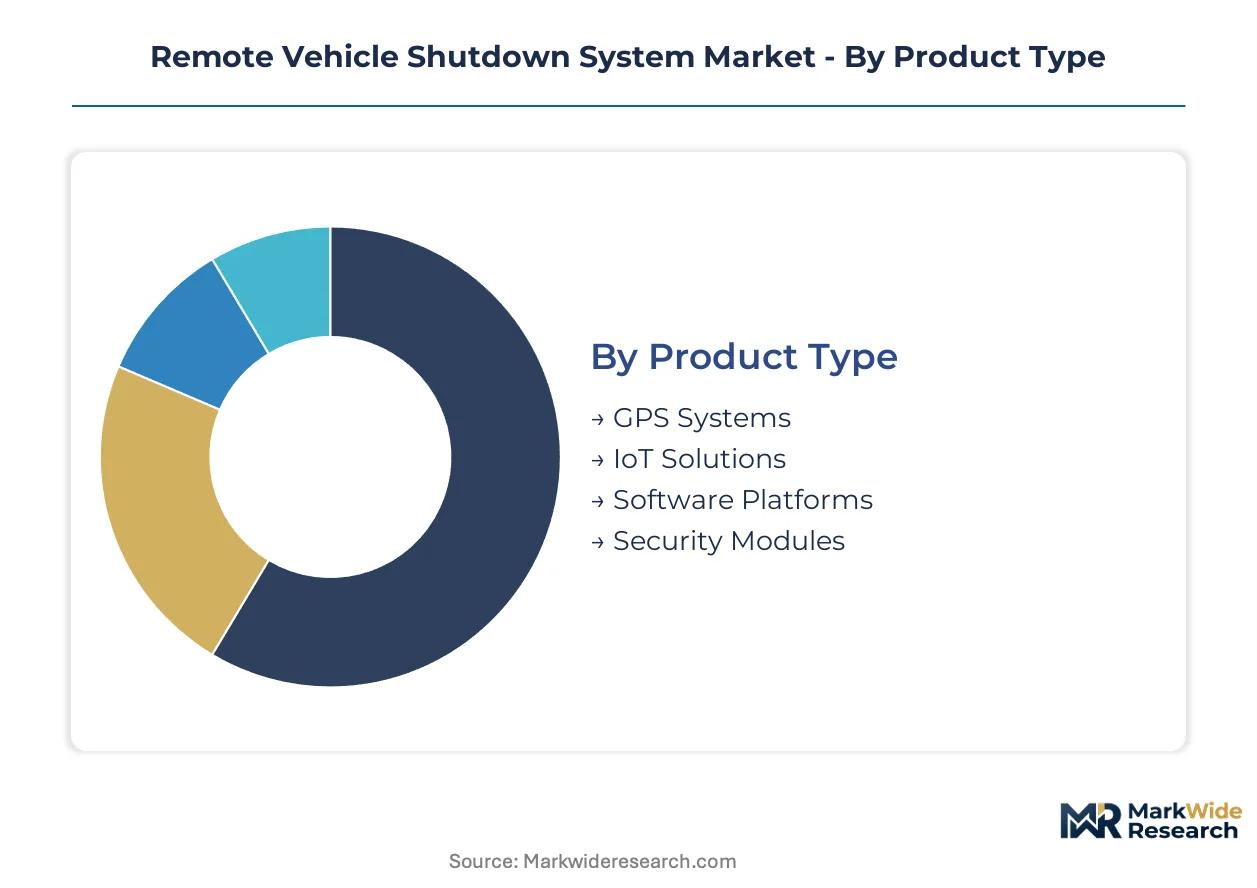
Remote vehicle shutdown systems fragment across four critical dimensions that determine procurement patterns and margin capture. Each segmentation axis reveals distinct channel preferences, from fleet telematics bundling to law enforcement direct contracting, shaping how vendors allocate R&D and sales resources.
Product Type:
Aftermarket channels favor hardware-heavy segments with minimal integration overhead, while fleet procurement concentrates around subscription-anchored platforms that bundle immobilization with broader telematics services.
- GPS Systems:Satellite positioning hardware with relay-controlled ignition cutoff circuits operates on 12V automotive power and integrates via OBD-II or hardwired CAN bus connections. Fleet operators in the United States dominate procurement, driven by stolen vehicle recovery mandates in high-theft metropolitan corridors and insurance premium reduction programs.
- IoT Solutions:Edge-computing modules embed cellular transceivers with localized predictive disable logic, reducing latency and data transmission costs. Demand clusters among mid-size commercial fleets adopting LTE-M and NB-IoT chipsets as hardware cost compression accelerates deployment.
- Software Platforms:Cloud-based command interfaces with API architectures enable third-party shutdown module orchestration and recurring subscription revenue capture.
- Security Modules:Hardened relay assemblies with tamper-detection circuitry serve law enforcement and high-value asset protection verticals requiring physical security guarantees.
GPS Systems dominate installed base. IoT Solutions is where expansion concentrates.
End User:
Customer type determines pricing tolerance and contract structure, with enterprise fleets accepting multi-year subscriptions while public sector buyers prioritize capital expenditure visibility and certification compliance.
- Fleet Operators:Commercial vehicle managers across last-mile delivery, construction equipment, and logistics verticals procure shutdown capabilities as embedded telematics features rather than standalone hardware. United States electrification mandates and total cost of ownership visibility drive consolidation around bundled platform contracts.
- Law Enforcement:Police departments and federal agencies require warrant-compliant activation protocols with audit trails and chain-of-custody documentation for evidentiary admissibility.
- Insurance Companies:Usage-based insurers deploy verified shutdown systems for premium discount eligibility and delinquent payment enforcement on financed vehicles.
- Ride-Sharing Services:Mobility platforms integrate driver safety interventions and asset recovery capabilities for gig-economy vehicle pools.
Fleet Operators anchor volume procurement. Insurance Companies represent the steepest expansion trajectory as data-sharing partnerships proliferate.
Technology:
Transmission protocol selection trades off coverage reliability against infrastructure dependency and recurring connectivity costs, with cellular architectures displacing satellite in cost-sensitive fleet applications.
- Cellular Network:LTE-M and NB-IoT transceivers leverage existing mobile infrastructure for continental coverage with minimal hardware overhead. Small fleet operators in the United States accelerate adoption as module pricing compresses through mass production economies.
- Satellite Communication:Iridium and Globalstar-based systems enable disable commands beyond cellular range for remote asset recovery and cross-border operations.
- RFID:Proximity-based authorization systems with short-range immobilization triggers serve controlled-access fleet yards and high-security facilities.
- Bluetooth:Smartphone-tethered architectures with limited range support consumer-grade vehicle recovery and peer-to-peer asset tracking applications.
Cellular Network captures mainstream fleet deployment. Satellite Communication retains premium positioning for geography-agnostic coverage requirements.
Installation Type:
Channel structure bifurcates between certified installer networks required for OEM warranty preservation and self-service options targeting cost-constrained small operators.
- Aftermarket:Third-party hardware deployment through authorized dealer networks and direct-to-fleet sales dominates near-term volume, bypassing automaker certification cycles that extend 18-24 months. United States commercial fleets prioritize rapid deployment over factory integration.
- OEM Integration:Factory-installed shutdown logic embedded in vehicle electronics during manufacturing ensures warranty compliance and native CAN bus integration.
- Self-Installation:Plug-and-play OBD-II dongles with relay bypass capabilities serve owner-operators and small fleet managers with limited technical support access.
- Professional Installation:Certified technician deployment with hardwired ignition interlock and tamper-evident mounting satisfies insurance and regulatory compliance requirements.
Aftermarket channels command current volume. OEM Integration is gaining share fastest as electric vehicle architectures natively embed shutdown capabilities through battery management systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Brazil and Mexico exhibit acute price sensitivity to hardware module costs, while fleet operators in the United States and Germany absorb premium pricing for integrated telematics platforms with embedded shutdown capabilities.
United States
Commercial fleet electrification mandates in California and New York accelerate OEM-integrated shutdown adoption through battery management systems. NHTSA vehicle-to-everything safety protocols require remote intervention capabilities in connected commercial vehicles. Dallas-Fort Worth and Atlanta logistics corridors concentrate procurement decisions for last-mile delivery operators bundling immobilization with fleet telematics.
Germany
Automotive OEMs in Stuttgart and Munich embed shutdown logic natively in electric vehicle architectures, streamlining factory integration. The EU AI Act restricts autonomous disable triggers without human authorization, forcing rearchitecture of cloud platforms. Bavaria's industrial automation clusters absorb compliance costs through extended certification cycles for aftermarket installers.
Brazil
Stolen vehicle recovery demand in São Paulo and Rio de Janeiro outpaces mature repossession infrastructure, creating first-mover opportunity for cellular-GPS hybrid platforms. ANVISA automotive telemetry guidelines intersect with state-level vehicle tracking mandates. São Paulo state's commercial fleet operators prioritize cost-compressed LTE-M modules over satellite-based alternatives.
Mexico
Cross-border logistics operators in Nuevo León and Mexico City deploy shutdown systems for asset recovery along US-Mexico trade corridors. The country's federal telecommunications regulator governs cellular spectrum allocation for automotive IoT deployments. Bajío Region automotive manufacturing clusters integrate shutdown capabilities for export-bound commercial vehicles.
China
Domestic electric vehicle manufacturers in Shenzhen and Shanghai embed remote immobilization through battery management systems at factory level. MIIT connected vehicle standards mandate cybersecurity certification for telematics modules. Yangtze River Delta telematics vendors compress hardware margins while capturing recurring software subscription revenue from fleet operators.
Remote Vehicle Shutdown System Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in remote vehicle shutdown systems, with full-stack telematics providers commanding premium positioning against hardware-centric point solution vendors. The integrated tier captures multi-year subscription contracts from enterprise fleets, while specialists compete on rapid deployment and price compression for small operator segments. Three archetypes dominate: legacy telematics incumbents with device-and-cloud integration, open-platform orchestrators enabling third-party module compatibility, and edge-computing natives embedding predictive logic at the device level. Competitive dynamics center on strategic partnerships with insurers for usage-based premium programs and geographic expansion into Latin American stolen vehicle recovery markets.
Within the integrated telematics tier, CalAmp and Samsara exemplify contrasting approaches to fleet market capture, while Geotab occupies a position as the open-platform orchestrator anchoring third-party shutdown module ecosystems. CalAmp represents the legacy heritage archetype with sustained device-and-cloud bundling for North American fleet operators. Samsara exemplifies the real-time diagnostics layering model that embeds immobilization triggers within broader vehicle health monitoring. Geotab sits within the architecture-agnostic tier, enabling interoperability across heterogeneous hardware deployments rather than captive device ecosystems.
| Leading Market Players |
|---|
| CalAmp |
| Verizon Connect |
| Teletrac Navman |
| Geotab |
| LoJack |
| Spireon |
| Guidepoint Systems |
| Samsara |
| PassTime |
| Others |
Value Network & Pricing Analysis
NHTSA ISO/SAE 21434 cybersecurity certification gates both supplier qualification and price differentiation simultaneously, forcing vendors into extended 18-24 month validation cycles that stratify hardware margins by compliance tier while compressing commodity relay-controller pricing.
Pricing Analysis
Recurring subscription revenue from cloud-based command interfaces drives lifetime value across customer relationships. Pricing stratifies across premium certified-installer tiers, standard bundled telematics packages, and economy self-install OBD-II dongles, with ISO 21434 compliance level as the primary differentiation driver. Cost compression in LTE-M cellular modules is intensifying because mass production economies from Taiwanese and South Korean foundries flood mid-market segments. Small fleet operators exhibit acute price sensitivity, while enterprise commercial vehicle managers absorb premium positioning for integrated platform contracts with real-time diagnostics layering.
Supply Chain Analysis
Just-in-time inventory preferences dominate cellular modem procurement, though strategic stockpiling of GPS receiver chipsets persists among security module vendors serving law enforcement verticals. Hardware fabrication concentrates in Taiwan, South Korea, and China, with relay assemblies and tamper-detection circuitry drawing from Mexican and German automotive component networks. Supply chain risk centers on single-source vulnerability for NB-IoT baseband processors from concentrated foundry capacity. Distribution runs through authorized dealer networks and direct-to-fleet sales channels, bypassing OEM certification bottlenecks that extend factory integration timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified cybersecurity engineering talent represents the critical scarcity constraining vendor expansion, as ISO 21434 compliance timelines exceed typical product development cycles and fragment competitive positioning between qualified and unqualified suppliers.
For Market Incumbents: Consolidate around full-stack telematics bundling to defend against open-platform orchestrators enabling third-party shutdown module compatibility. Deepen backward integration into edge-computing chip design to capture predictive disable logic revenue pools. Prioritize certification investment in EU AI Act human-in-the-loop authorization protocols to preserve European market access against algorithmic decision constraints. For New Entrants and Emerging Players: Lead with cellular-GPS hybrid platforms targeting Brazilian and Mexican stolen vehicle recovery markets where repossession infrastructure remains underdeveloped. Penetrate Latin American cross-border logistics corridors through cost-compressed LTE-M modules with localized Portuguese and Spanish language cloud interfaces. Pursue insurer data-sharing partnerships as the primary go-to-market angle for usage-based premium discount eligibility. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-native platform tiers as recurring subscription revenue displaces hardware-heavy transactional models. Long-term viability favors vendors with captive cloud architectures and API ecosystem lock-in rather than point-solution hardware specialists. Target acquisition profiles center on edge-computing natives with embedded predictive logic capabilities. Watch for inflection when FCC spectrum allocation rulings for automotive telemetry cross thresholds that advantage cellular over satellite transmission protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Module Development | Embedding predictive disable logic at the device level reduces latency for fleet operators in Dallas-Fort Worth logistics corridors. |
| Insurer Data-Sharing Partnership | Usage-based premium discount programs in California and New York accelerate fleet procurement decisions for verified shutdown systems. |
| EU AI Act Compliance Certification | Human-in-the-loop authorization protocols preserve market access for cloud platforms serving Bavarian industrial automation clusters. |
| Latin American Geographic Expansion | First-mover positioning in São Paulo and Rio de Janeiro stolen vehicle recovery markets captures price-sensitive fleet demand. |
| OEM Integration Partnership | Factory-installed shutdown logic through battery management systems streamlines adoption for commercial fleet electrification mandates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, NHTSA safety communication protocols, FCC spectrum allocation records, and EU AI Act implementation guidance. Fleet telematics procurement officers, automotive cybersecurity engineers, commercial vehicle fleet managers, and insurance underwriting specialists contributed structured interviews. Customs and trade data from United States, German, and Brazilian automotive component flows supplemented bottom-up vendor revenue triangulation against top-down market sizing from vehicle production databases.
Segmentation dimensions modeled span product type, end user archetype, transmission technology, and installation channel across the analysis window. CAGRs derive from regression analysis of historical fleet telematics adoption curves, cellular IoT module cost compression trajectories, and regulatory mandate implementation schedules. Industry-specific forecast inputs incorporate NHTSA vehicle-to-everything protocol rollout timing and commercial fleet electrification penetration rates by vehicle class.
Underlying assumptions cover continued LTE-M and NB-IoT chipset cost compression, stable FCC automotive telemetry spectrum allocation, and sustained NHTSA safety communication enforcement, with deviation risk concentrated in Taiwanese foundry capacity constraints and EU AI Act algorithmic decision interpretation variance. Revision becomes warranted when semiconductor allocation volatility crosses thresholds that disrupt hardware vendor margin structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Keyless Entry Access Systems Market
Automotive Safety and Security Systems
Engine Braking System Market
Automotive Safety and Security Systems
Global Automotive Braking System Market
Automotive Safety and Security Systems
Lane Departure Warning System Market
Automotive Safety and Security Systems
Active Spoiler Market
Automotive Safety and Security Systems
Automotive Active Safety System Market
Automotive Safety and Security Systems
Automotive Active Health Monitoring System Market
Automotive Safety and Security Systems
Automotive Blind Spot Detection (BSD) System Market
Automotive Safety and Security Systems
Automotive Anti Lock Braking System and Electronic Stability Control Market
Automotive Safety and Security Systems
Automotive Keyless Entry System Market
Automotive Safety and Security Systems
Automatic Brake Pad Inspection System Market
Automotive Safety and Security Systems
Occupant Classification System Market
Automotive Safety and Security Systems
Global Automotive Safety System Market
Automotive Safety and Security Systems
Automotive Anti-Pinch Power Window System Market
Automotive Safety and Security Systems
United States Automotive Airbag Systems Market
Automotive Safety and Security Systems
Forward Collision Warning System for Automotive Market