
 Automotive TPMS Market | 2026-2036
Automotive TPMS Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive TPMS Market Analysis
Aftermarket distribution channels is reshaping how replacement sensors reach independent garages and fleet service depots. Continental AG leverages its tier-1 supplier relationships to sustain OEM channel dominance across European and North American vehicle programs. Sensata Technologies anchors its position through specialized MEMS pressure sensing architectures that occupy the premium direct TPMS tier.
Automotive tire pressure monitoring systems are electronic safety devices that measure tire inflation levels through radio-frequency transmitting sensors or wheel-speed differential algorithms, typically operating at 433 MHz in Europe and 315 MHz in North America, with the primary purpose of preventing blowouts, improving fuel efficiency, and extending tire service life. Direct TPMS commands the largest installed base due to regulatory precision requirements, while Smart TPMS represents the fastest-expanding category as embedded software integration enables predictive maintenance analytics for fleet operators. Electric Vehicles application segment concentrates disproportionate R&D investment because battery weight distribution and range sensitivity amplify the value of optimized tire pressure management.
The US NHTSA Federal Motor Vehicle Safety Standard 138 mandates TPMS functionality on all light vehicles, compelling sustained replacement demand as sensor batteries deplete after five to seven years of service. European type-approval frameworks under UN ECE Regulation 64 and the EU's General Safety Regulation tighten performance thresholds for commercial vehicle TPMS accuracy. Stakeholders must monitor how cybersecurity standards for vehicle-to-everything communication protocols reshape sensor authentication requirements and supplier qualification timelines.
Market Dynamics
The transition from direct to Smart TPMS architectures is compressing hardware margins while expanding software revenue pools, forcing suppliers to restructure R&D allocation toward embedded analytics and cloud-connectivity stacks.
Growth Catalysts
- Fleet telematics integration:Commercial logistics operators in North America and Europe are mandating real-time tire pressure data feeds into centralized fleet management platforms, creating pull-through demand for sensor hardware with enhanced transmission range.
- UN ECE Regulation 64:European type-approval frameworks now require TPMS functionality on commercial vehicles above 3.5 tonnes, expanding the addressable installed base beyond passenger car segments.
- Lithium-ion battery cost curves:Extended sensor battery life is enabling 10-year maintenance-free operation, reducing total cost of ownership calculations for fleet procurement committees.
Market Restraints
- MEMS wafer supply concentration:Pressure-sensing die fabrication clusters in Taiwan and South Korea create vulnerability to foundry allocation constraints during semiconductor demand cycles.
- Indirect TPMS algorithm maturity:Wheel-speed differential systems still fail to meet NHTSA precision thresholds for temperature-compensated pressure readings, limiting their deployment scope.
- Radio frequency spectrum fragmentation:Divergent operating frequencies between European 433 MHz and North American 315 MHz standards force dual-SKU inventory strategies that inflate working capital requirements.
Strategic Opportunities
- Predictive maintenance platforms:Cloud-based tire wear modeling that integrates TPMS data with vehicle dynamics sensors is creating recurring revenue streams for suppliers with software development capabilities.
- Electric vehicle weight optimization:Battery pack mass distribution sensitivity in EV platforms is elevating tire pressure management to a range-critical function, commanding premium sensor specifications.
- Aftermarket channel digitization:Direct-to-installer e-commerce platforms are disintermediating traditional distribution layers, enabling sensor manufacturers to capture margin previously allocated to regional distributors.
Industry Challenges
- RF calibration technician scarcity:Proper installation of direct TPMS requires torque-limited valve stem mounting and receiver pairing procedures that many independent garages lack training to execute correctly.
- Cybersecurity certification timelines:UNECE R155 vehicle-type approval requirements for sensor authentication protocols are extending product validation cycles by 8-14 months for suppliers without established security engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive TPMS Market |
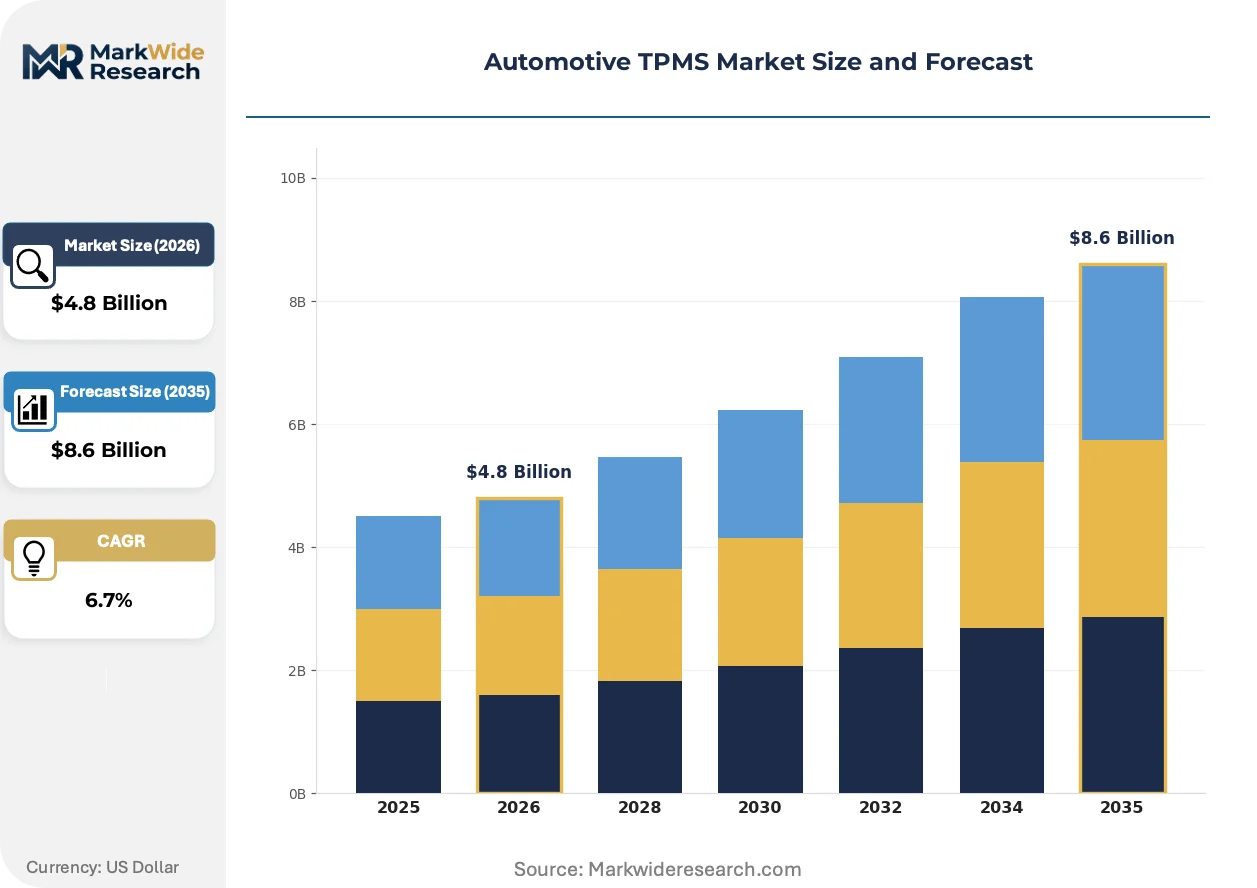
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct TPMS, Indirect TPMS, Hybrid TPMS, Smart TPMS End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Dealerships Technology: Wireless Technology, Sensor Technology, Communication Protocols, Software Integration Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Electric Vehicles |
| Companies Covered | DENSO Corporation, Continental AG, Sensata Technologies, Huf Hülsbeck & Fürst, Pacific Industrial Co., Ltd., ZF Friedrichshafen AG, VALEO, Robert Bosch GmbH, HELLA GmbH & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive TPMS Market Emerging Trajectories
Software-defined functionality is displacing fixed-parameter hardware designs across the TPMS value chain, with suppliers racing to embed sufficient compute capacity for over-the-air algorithm updates.
Smart TPMS is hybridizing pressure sensing with temperature-compensated load estimation and tread-wear prediction algorithms. Heavy-duty fleet operators in Germany and the Netherlands are piloting these systems at scale. This convergence is collapsing the historical separation between tire monitoring and chassis dynamics control modules.
The EU General Safety Regulation is mandating advanced driver-assistance system interoperability that includes TPMS data feeds to emergency braking and stability control computers. Vehicle manufacturers must redesign electrical architectures to accommodate these data pathways. Passenger car platforms launching after 2024 face the steepest compliance engineering costs.
Service bundling is reshaping how fleet managers procure tire pressure monitoring. Large logistics operators in the United States are negotiating tire-as-a-service contracts that embed sensor hardware costs into per-mile pricing. This shift transfers capital expenditure risk to suppliers while demanding lifetime performance guarantees that favor established tier-1 vendors with balance sheet depth.
Automotive TPMS Market Segmentation
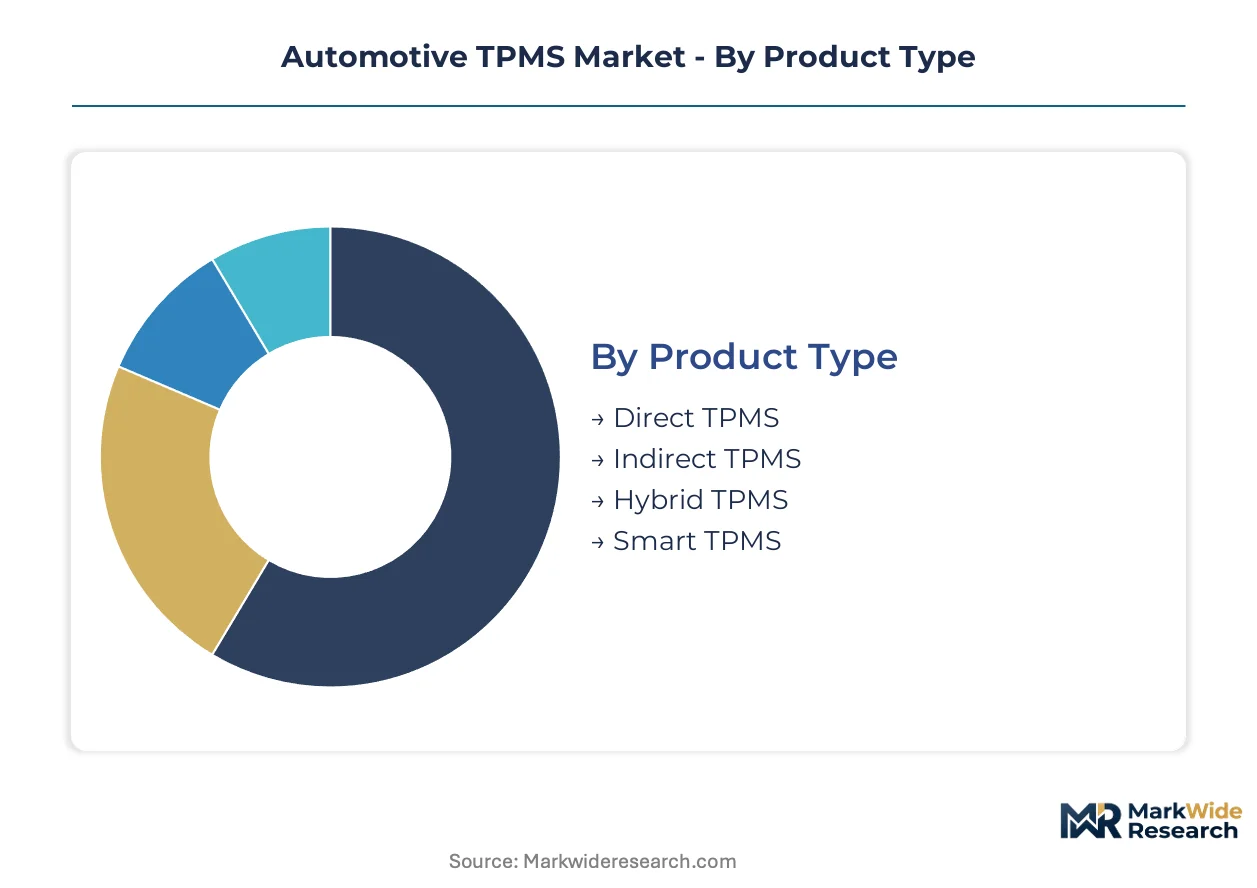
TPMS market segmentation reveals how hardware specifications, distribution channels, and vehicle electrification reshape supplier priorities. Each dimension carries distinct margin profiles and regulatory exposure that determine competitive positioning.
Product Type:
Use-case spectrum spans from basic pressure alerts to predictive tire analytics, with hardware complexity and software content determining value capture.
- Direct TPMS:Individual valve-stem sensors transmit pressure and temperature data via radio frequency to a central receiver. NHTSA precision mandates in the United States sustain replacement demand as battery depletion cycles drive aftermarket volume.
- Smart TPMS:Embedded processors execute tread-wear prediction and load-estimation algorithms, enabling cloud-connected fleet analytics. German heavy-duty logistics operators pilot these systems at scale, compressing the historical separation between tire monitoring and chassis control modules.
- Indirect TPMS:Wheel-speed differential algorithms estimate pressure without dedicated hardware, constrained by temperature-compensation limitations that exclude NHTSA compliance.
- Hybrid TPMS:Combines direct sensing with indirect validation layers, deployed where cost-sensitive platforms require redundancy without full Smart TPMS compute overhead.
The dominant share belongs to Direct TPMS, while Smart TPMS is closing the gap fastest.
End User:
Channel economics diverge sharply between captive OEM supply and fragmented aftermarket service networks.
- OEMs:Tier-1 suppliers negotiate multi-year vehicle program contracts with embedded sensor specifications, leveraging Federal Motor Vehicle Safety Standard 138 compliance as a baseline qualification.
- Aftermarket Providers:Independent distributors and e-commerce platforms disintermediate traditional regional wholesalers, capturing margin previously allocated to layered distribution.
- Vehicle Assemblers:Contract manufacturers integrate TPMS modules during final assembly, with procurement committees prioritizing 10-year battery life specifications enabled by lithium-ion cost curves.
- Dealerships:Authorized service centers execute sensor replacement and receiver pairing procedures, though technician training gaps persist for torque-limited valve stem mounting protocols.
OEMs command volume concentration, though aftermarket channels are expanding most quickly through direct-to-installer digitization.
Technology:
Technology layers stack from physical sensing elements through connectivity protocols to cloud analytics infrastructure.
- Sensor Technology:MEMS pressure-sensing die fabrication concentrates in Taiwan and South Korea, creating foundry allocation vulnerability during semiconductor demand cycles.
- Software Integration:Embedded analytics platforms enable over-the-air algorithm updates and predictive maintenance revenue streams for suppliers with development capabilities.
- Wireless Technology:Radio-frequency transmission at 433 MHz in Europe and 315 MHz in North America forces dual-SKU inventory strategies that inflate working capital requirements.
- Communication Protocols:Vehicle-to-everything cybersecurity standards under UNECE R155 extend validation cycles for authentication-compliant sensor designs.
Sensor Technology anchors hardware value, while Software Integration delivers the steepest expansion trajectory as functionality migrates from fixed-parameter to programmable architectures.
Application:
Vehicle platform characteristics dictate sensor specification intensity and replacement frequency.
- Electric Vehicles:Battery pack mass distribution sensitivity elevates tire pressure management to range-critical status, commanding premium specifications and disproportionate R&D investment.
- Commercial Vehicles:UN ECE Regulation 64 mandates TPMS functionality above 3.5 tonnes, with fleet telematics integration pulling real-time data feeds into centralized management platforms.
- Passenger Vehicles:Light vehicle segments drive replacement sensor volume through NHTSA-mandated installed base expansion and five-to-seven-year battery depletion cycles.
- Two-Wheelers:Cost-constrained platforms favor indirect or hybrid architectures where regulatory thresholds permit, limiting addressable premium sensor share.
Passenger Vehicles maintain installed base dominance, yet Electric Vehicles are gaining share fastest as platform electrification accelerates tire pressure optimization requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal mandates and commercial fleet digitization are reshaping TPMS deployment patterns across major automotive manufacturing clusters. Battery-electric platform proliferation and logistics operator telematics integration are accelerating sensor hardware refresh cycles in specific national markets.
United States
NHTSA Federal Motor Vehicle Safety Standard 138 sustains replacement sensor volume as five-to-seven-year battery depletion cycles drive aftermarket demand. The regulation mandates direct TPMS precision thresholds that indirect systems cannot satisfy. Detroit-area tier-1 suppliers coordinate multi-year vehicle program contracts with embedded sensor specifications.
Germany
UN ECE Regulation 64 mandates TPMS functionality on commercial vehicles above 3.5 tonnes, expanding the addressable installed base beyond passenger segments. KBA type-approval frameworks tighten performance thresholds for temperature-compensated pressure readings. Stuttgart and Munich host heavy-duty fleet pilot programs integrating Smart TPMS with chassis dynamics control modules.
China
Domestic suppliers capture growing share of the indirect TPMS segment as cost-sensitive platforms proliferate. MIIT vehicle certification requirements align with evolving international standards. Yangtze River Delta manufacturing clusters dominate MEMS pressure-sensing die fabrication volume.
Japan
METI industrial policy supports sensor miniaturization R&D for electric vehicle weight optimization applications. JIS standards provide technical baselines for radio-frequency transmission protocols. Nagoya-area automotive electronics corridors concentrate OEM supplier engineering capabilities.
South Korea
Domestic battery-electric vehicle manufacturers prioritize tire pressure management for range-critical platform specifications. MFDS regulatory coordination ensures alignment with UNECE cybersecurity frameworks for vehicle-to-everything communication. Seoul Capital Area foundry clusters face allocation constraints during semiconductor demand cycles.
Automotive TPMS Market Vendor Landscape
On the supply side, the industry is consolidating around tier-1 automotive suppliers with established OEM channel relationships and specialized MEMS sensing specialists with captive fabrication capabilities. Three strategic archetypes dominate: integrated tier-1s leveraging vehicle program scale, MEMS-focused technology specialists commanding premium direct TPMS tiers, and diversified automotive electronics conglomerates with sensor portfolio breadth. Competitive moves center on strategic partnerships for fleet telematics integration and backward integration into pressure-sensing die fabrication.
Among German-based tier-1 suppliers, Continental AG and ZF Friedrichshafen AG exemplify the integrated archetype with multi-decade vehicle program relationships. Sensata Technologies occupies a position within the MEMS specialist tier, while DENSO Corporation represents the diversified Japanese automotive electronics conglomerate structure. Bosch GmbH and VALEO sit within the European diversified supplier category with broad sensor portfolio coverage.
| Leading Market Players |
|---|
| DENSO Corporation |
| Continental AG |
| Sensata Technologies |
| Huf Hülsbeck & Fürst |
| Pacific Industrial Co., Ltd. |
| ZF Friedrichshafen AG |
| VALEO |
| Robert Bosch GmbH |
| HELLA GmbH & Co. KGaA |
| Others |
Supply Flow & Price Mechanics
MEMS wafer foundry allocation constraints in Taiwan and South Korea determine both tiered sensor pricing spreads and supply chain resilience investments, forcing tier-1 suppliers to dual-source pressure-sensing die while absorbing margin compression in standard-grade direct TPMS modules.
Pricing Analysis
Certification level under UN ECE R155 and NHTSA FMVSS 138 creates the primary spread between premium authenticated sensors and economy-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects software integration depth and battery chemistry specifications. Cost compression in the standard tier is intensifying because Chinese indirect TPMS suppliers capture share in cost-sensitive platforms. Fleet procurement committees exhibit lowest price sensitivity due to total cost of ownership calculations, while independent garages face acute margin pressure on replacement sensor installations.
Supply Chain Analysis
Extended payment terms from OEM vehicle program contracts now stretch 90-120 days, forcing sensor manufacturers to utilize supply-chain finance facilities against receivables. MEMS pressure-sensing die fabrication concentrates in Taiwan, South Korea, and the Yangtze River Delta region of China. Raw material dependencies span lithium-ion battery cells, RF transmission components, and automotive-grade epoxy packaging compounds. Single-source vulnerability clusters in Taiwan Semiconductor Manufacturing capacity allocation for pressure-sensing wafers. Distribution runs through tier-1 supplier direct fulfillment to OEM assembly plants, with aftermarket channels digitizing toward direct-to-installer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as fleet telematics integration splinters demand between basic replacement sensors and cloud-connected Smart TPMS analytics, creating distinct procurement committees with divergent technical specifications.
For Market Incumbents: Insulate OEM channel position by securing multi-year vehicle program contracts with embedded cybersecurity authentication protocols, while backward integration into MEMS fabrication capacity hedges foundry allocation risk from Taiwan and South Korean suppliers. For New Entrants and Emerging Players: Pursue aftermarket digitization white-space through direct-to-installer e-commerce platforms targeting independent garages in North America and Europe, where RF calibration technician scarcity creates service bundling opportunities alongside sensor hardware sales. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors MEMS technology specialists with captive fabrication capabilities and established UNECE R155 certification timelines, suggesting acquisition targets with security engineering teams and 10-year battery life specifications will command premium valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Smart TPMS Platform Integration | Embedded analytics enable recurring revenue streams through cloud-connected fleet maintenance contracts. |
| MEMS Fabrication Backward Integration | Captive wafer production insulates margin pressure from Taiwan and South Korean foundry allocation cycles. |
| Cybersecurity Certification Investment | UNECE R155 compliance extends product validation timelines but locks out unqualified competitors from OEM programs. |
| Aftermarket Channel Digitization | Direct-to-installer platforms disintermediate regional distributors and capture margin previously allocated to layered wholesale networks. |
| Electric Vehicle Platform Standardization | Battery weight distribution sensitivity in EV architectures elevates tire pressure management to range-critical status. |
Methodological Framework
Operator-level perspectives from tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributor operations managers, and fleet telematics integration specialists anchored the qualitative base. These primary insights combined with secondary validation from NHTSA regulatory filings, UN ECE type-approval databases, vehicle production registries, and customs trade data for MEMS component flows. Bottom-up sensor shipment modeling and top-down automotive electronics market sizing provided triangulation checks across estimation approaches.
Scenario-bracketing around fleet electrification penetration and cybersecurity certification timeline variations framed the analytical approach across the projection horizon. Segmentation dimensions modeled encompass product type, vehicle propulsion architecture, end-user channel, and regional regulatory cluster. CAGRs derived from logistic curve fitting to technology adoption patterns and replacement cycle analysis. Industry-specific forecast inputs included lithium-ion battery cost curve trajectories and commercial vehicle telematics integration rates.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles, automotive production volumes, or logistics freight rates would shift the trajectory. Forecasts reflect documented assumptions about regulatory compliance deadlines and technology substitution elasticities. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Pedestrian Protection System Market
Automotive Safety and Security Systems
Car Camera Cleaning Systems Market
Automotive Safety and Security Systems
Motorcycle Stability Control Market
Automotive Safety and Security Systems
Seat Belt Pretensioner and Load Limiter Market
Automotive Safety and Security Systems
Avalanche Airbags Market
Automotive Safety and Security Systems
Occupant Classification System Market
Automotive Safety and Security Systems
Automotive Brake System Market
Automotive Safety and Security Systems
Brake System Market
Automotive Safety and Security Systems
ABS Sensors Market
Automotive Safety and Security Systems
Automotive Active Safety System Market
Automotive Safety and Security Systems
Adaptive Front Lighting Market
Automotive Safety and Security Systems
Automotive Seat Belt Pretensioner Market
Automotive Safety and Security Systems
Europe Airbag Systems Market
Automotive Safety and Security Systems
Automotive Surge Absorber Market
Automotive Safety and Security Systems
Automotive Laser Headlight Market
Automotive Safety and Security Systems
In-Cabin Monitoring System (ICMS) Market