
 Wheel Spacers and Adapters Market | 2026-2036
Wheel Spacers and Adapters Market Size, Share, and Industry Trends Forecast 2026-2036
Wheel Spacers and Adapters Market Analytics
Hub-centric specification upgrades is unwinding across the wheel spacers and adapters landscape as enthusiasts prioritize vibration-free fitment over budget alternatives. Spidertrax leverages its deep specialization in off-road hub-centric systems to command premium positioning in the 4x4 channel. ECCPP competes through aggressive online distribution and broad SKU coverage across import and domestic fitments. Rugged Ridge sustains brand loyalty among Jeep owners through OE-quality validation and trail-tested product lines.
Wheel spacers and adapters are precision-machined cylindrical components, typically forged from 6061-T6 aluminum or billet steel, that mount between a vehicle's hub and wheel to alter offset, increase track width, or convert bolt patterns for fitment compatibility. Hub-centric designs maintain center bore alignment to eliminate vibration, while bolt-on configurations require direct lug engagement for load transfer. The material dimension shows aluminum dominating volume due to its strength-to-weight ratio, though steel variants anchor the commercial truck segment where load ratings exceed passenger vehicle thresholds. Vehicle type segmentation reveals SUVs and trucks generating the fastest growth as lift kit installations drive companion spacer purchases for proper wheel clearance.
NHTSA maintains oversight of aftermarket wheel component safety through Federal Motor Vehicle Safety Standards compliance expectations, while SAE J2530 provides wheel performance test protocols that spacer manufacturers reference for structural validation. ISO 9001 quality management certification has become a baseline market access requirement for suppliers serving North American distributors. Stakeholders must monitor evolving state-level vehicle modification enforcement patterns and insurer liability positions on aftermarket fitment to anticipate demand shifts in key regional markets.
Market Dynamics
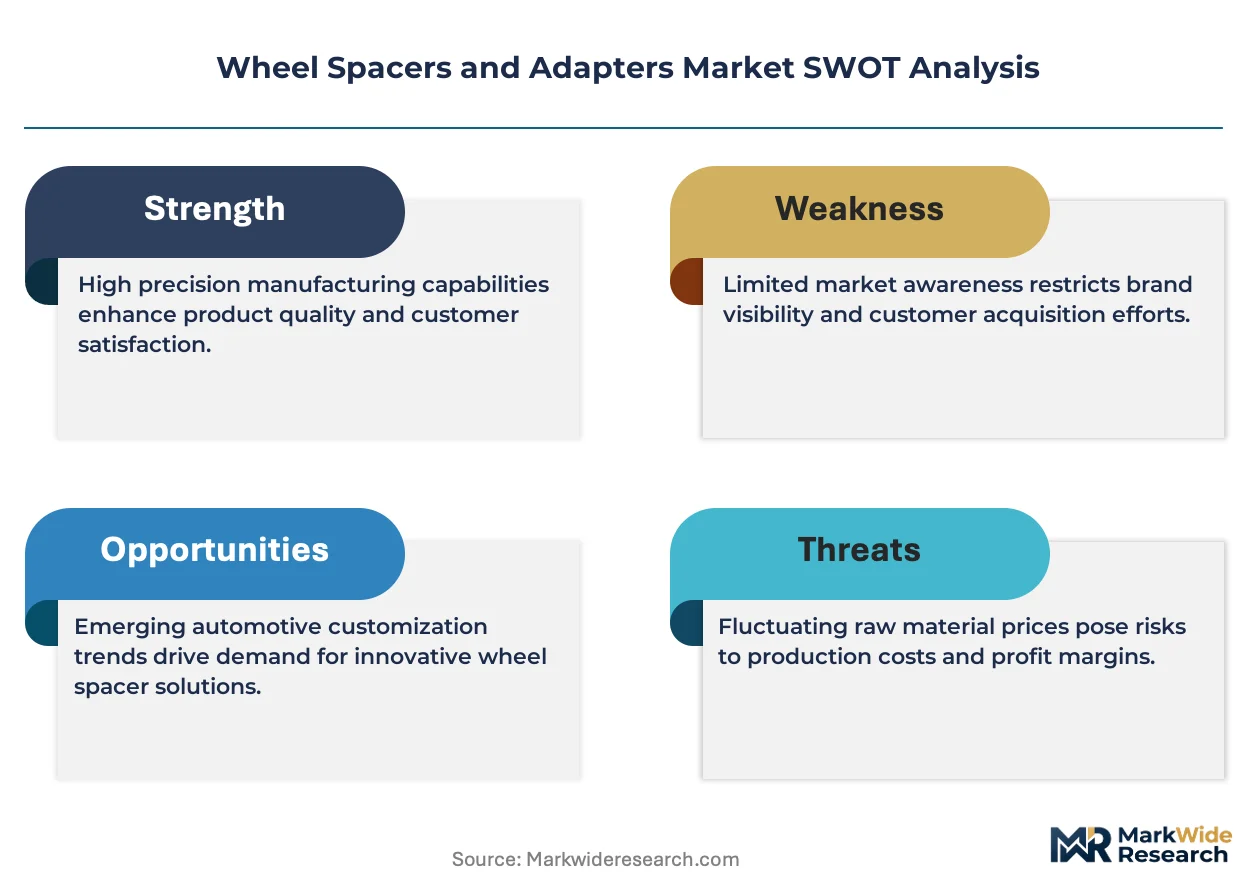
The wheel spacers and adapters market is being reshaped by the tension between hub-centric precision engineering and price-driven commoditization, as enthusiasts demand vibration-free fitment while budget buyers accept lug-centric alternatives that transfer load through wheel studs rather than hub contact.
Growth Catalysts
- Lifted truck aftermarket expansion:Suspension lift kit installations in the United States generate companion spacer purchases for proper wheel clearance and steering geometry correction.
- SAE J2530 structural validation protocols:Wheel performance testing standards provide manufacturers with credible safety benchmarks that differentiate premium products in distributor channels.
- Off-road recreation participation:Rock crawling and desert racing communities in the American Southwest sustain replacement demand for trail-damaged components.
Market Restraints
- Aluminum 6061-T6 price volatility:Aerospace and industrial demand for high-strength aluminum alloys creates input cost pressure that squeezes margin on standard-thickness spacers.
- Insurance liability uncertainty:US auto insurers maintain inconsistent positions on aftermarket wheel modifications, creating purchase hesitation among daily-driver owners.
- Steel forging capacity concentration:Heavy-duty commercial truck spacer production depends on domestic foundry capacity that has consolidated to three major suppliers.
Strategic Opportunities
- Electric vehicle wheel offset correction:Battery pack packaging constraints on EV platforms create fitment incompatibilities that hub-centric spacers resolve for aftermarket wheel upgrades.
- Direct-to-consumer CNC customization:Online configurators enabling bolt pattern and thickness specification capture margin previously retained by distribution intermediaries.
- ISO 9001 certification arbitrage:Quality management credentialing opens access to fleet maintenance contracts with municipal and commercial vehicle operators.
Industry Challenges
- CNC machining talent scarcity:Precision aluminum milling for tight-tolerance hub bores requires skilled operators that aftermarket manufacturers struggle to recruit.
- Hub bore measurement standardization:Vehicle manufacturers publish inconsistent center bore specifications, forcing spacer producers to maintain extensive vehicle-specific databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheel Spacers and Adapters Market |
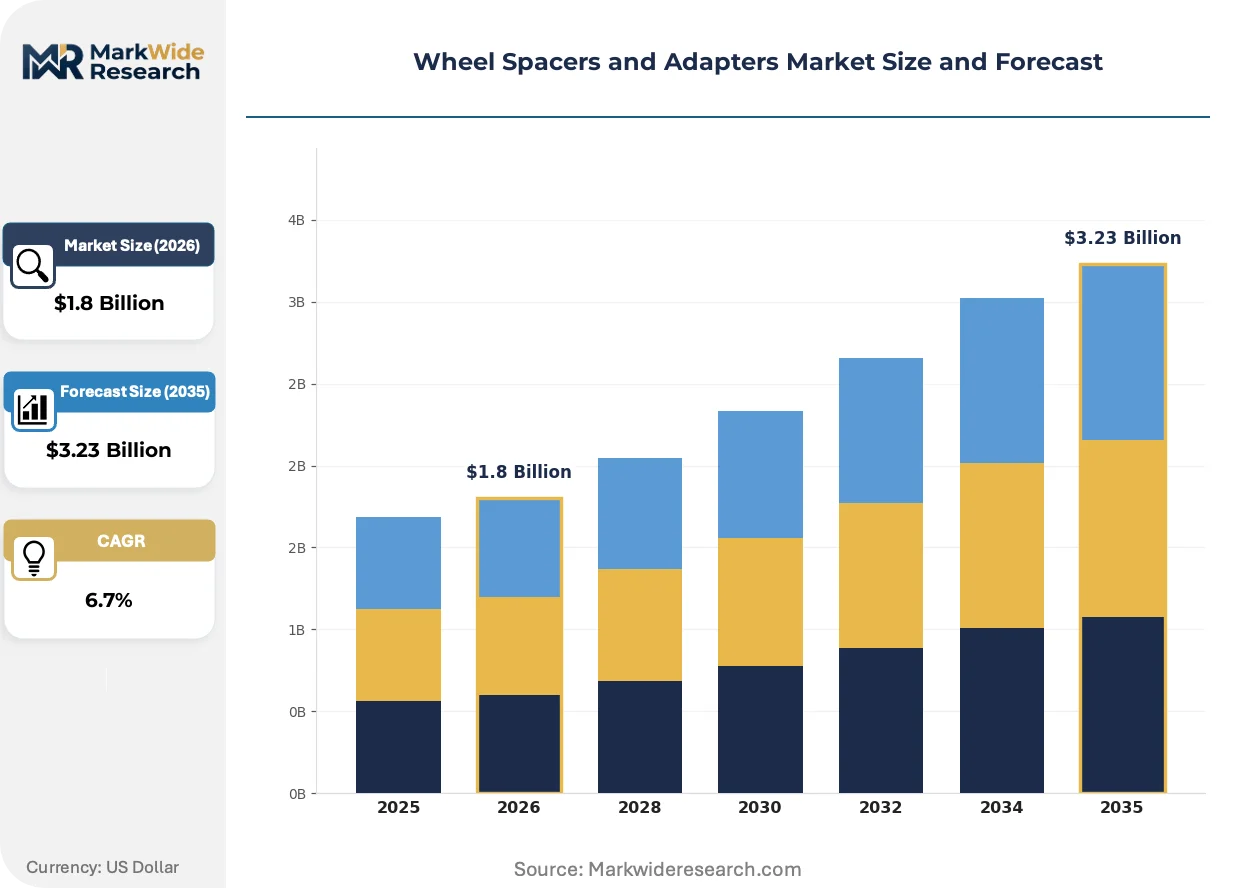
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spacers, Adapters, Hub Centric, Bolt On Vehicle Type: Passenger Cars, SUVs, Trucks, Commercial Vehicles Material: Aluminum, Steel, Composite, Magnesium Size: 5mm, 10mm, 25mm, 50mm |
| Companies Covered | Spidertrax, Rugged Ridge, ECCPP, Titan Wheel Accessories, Precision European Motorwerks, Supreme Suspensions, OrionMotorTech, RockTrix, BONOSS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheel Spacers and Adapters Market Evolving Landscape
Active innovation in the wheel spacers and adapters market centers on material science advancement, regulatory validation rigor, and the disintermediation of traditional distribution channels through digital fitment tools.
Multi-piece modular spacer systems are bifurcating the premium segment from commodity offerings. These configurations separate the hub-centric ring from the main spacer body, allowing enthusiasts to swap center bores across multiple vehicles. High-end off-road builders in the Rocky Mountain states adopt these systems for garage-based wheel fitment experimentation. The technology is bifurcating price tiers by enabling single-SKU inventory to cover dozens of vehicle applications.
NHTSA has intensified scrutiny of aftermarket wheel component documentation through informal guidance on Federal Motor Vehicle Safety Standards compliance expectations. Manufacturers now invest in third-party structural testing beyond SAE J2530 minimums to defend product liability positions. The regulatory pressure concentrates most acutely on billet steel producers serving commercial truck fleets where failure consequences carry severe liability exposure.
Specialty retailers now unbundle after-sales support from product transactions through video-based installation verification. Buyers upload torque sequence footage for technician review rather than relying on printed instructions. This service model shift appears strongest in the southeastern United States where independent shops lack factory-trained wheel specialists. The behavioral change reduces warranty claim rates while building recurring engagement with enthusiast communities.
Wheel Spacers and Adapters Market Segmentation
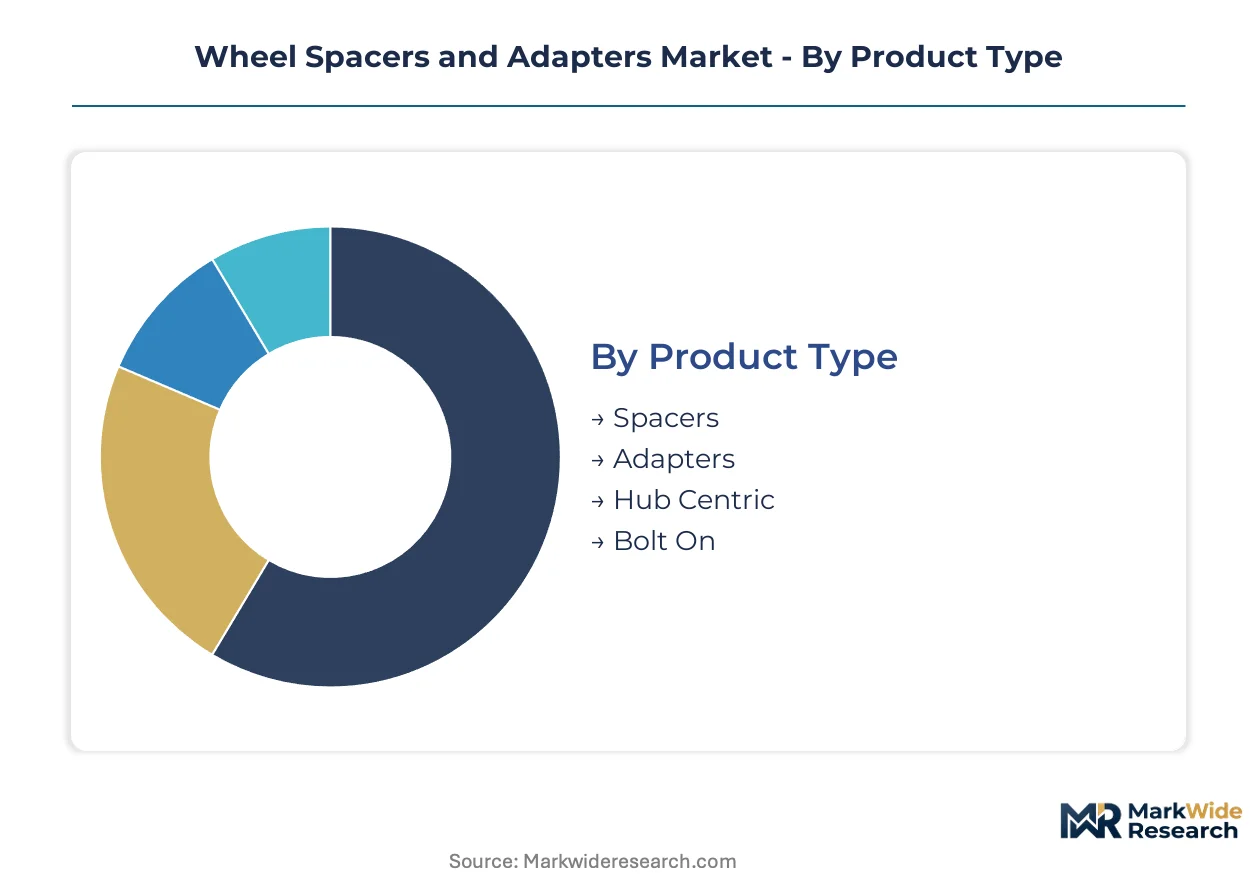
Wheel spacers and adapters demand fragments across four distinct dimensions, each channeling through different procurement pathways. Product type and vehicle application determine whether components flow through specialty off-road retailers, general automotive distributors, or direct-to-consumer CNC configurators.
Product Type:
Channel mix varies sharply by product complexity, with hub-centric precision components commanding distributor relationships while bolt-on alternatives dominate Amazon and eBay marketplaces.
- Spacers:Cylindrical aluminum or steel discs that increase track width without altering bolt patterns. Demand concentrates in Texas and California lifted truck markets where suspension modifications require steering geometry correction. NHTSA safety documentation requirements favor established suppliers with third-party structural testing capabilities.
- Adapters:Dual-bolt-pattern components enabling wheel fitment across incompatible vehicle specifications. The Rocky Mountain off-road community sustains replacement demand for trail-damaged units, with Spidertrax commanding premium positioning through hub-centric engineering specialization.
- Hub Centric:Center-bore-aligned designs eliminating vibration through direct hub contact. These precision-machined components flow through specialty 4x4 retailers and installer networks rather than mass-market channels.
- Bolt On:Lug-centric configurations transferring load through wheel studs rather than hub contact. Price-driven commoditization pushes these units through online marketplaces with minimal technical support.
By volume, Spacers leads. By growth pace, Hub Centric is expanding most quickly as enthusiasts prioritize vibration-free fitment over budget alternatives.
Vehicle Type:
Application context determines margin structure, with commercial fleet contracts demanding ISO 9001 certification while consumer segments tolerate broader quality variance.
- Passenger Cars:Fitment corrections for aftermarket wheel upgrades on sedans and coupes. Daily-driver owners in urban California markets show purchase hesitation due to insurer liability uncertainty.
- SUVs:Battery pack packaging constraints on electric SUV platforms create offset incompatibilities that hub-centric spacers resolve. This segment climbs the fastest as EV aftermarket wheel upgrades accelerate.
- Trucks:Lift kit installations generate companion spacer purchases for proper wheel clearance. The American Southwest desert racing and rock crawling communities sustain steady component turnover.
- Commercial Vehicles:Heavy-duty steel spacers serving fleet maintenance contracts with municipal and commercial operators. SAE J2530 structural validation and ISO 9001 certification serve as baseline market access requirements.
Trucks dominates current revenue. SUVs gain share fastest as electric vehicle wheel offset correction needs multiply.
Material:
Cost tier separation runs through raw material sourcing, with aerospace aluminum demand creating input pressure on standard-thickness production.
- Aluminum:6061-T6 forged alloy dominating volume through strength-to-weight ratio optimization. Price volatility from competing aerospace and industrial demand squeezes margin on commodity spacers.
- Steel:Billet steel anchoring commercial truck applications where load ratings exceed passenger vehicle thresholds. Domestic foundry capacity consolidation to three major suppliers creates supply concentration risk.
- Composite:Emerging polymer-matrix alternatives targeting weight reduction in motorsport applications.
- Magnesium:Premium racing components where mass reduction justifies material cost premium.
Aluminum leads by unit volume. Steel maintains revenue concentration through commercial fleet pricing power.
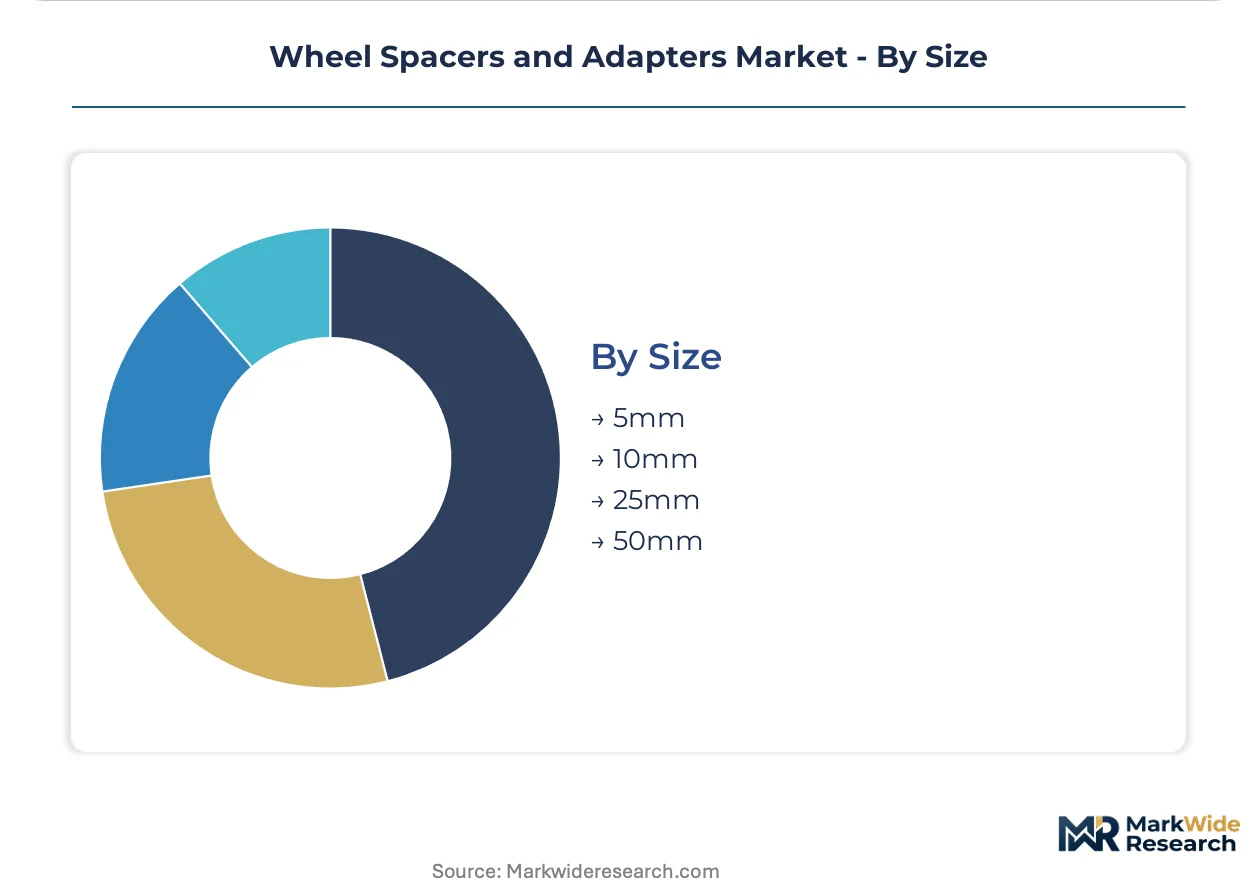
Size:
Thickness specification correlates directly with application severity, with thicker units requiring proportionally greater structural validation investment.
- 5mm:Minimal offset correction for subtle stance adjustment on lowered passenger vehicles.
- 10mm:Moderate track width expansion clearing brake caliper interference on performance upgrades.
- 25mm:Standard lifted truck clearance spacing, generating the steepest expansion trajectory as suspension lift installations multiply.
- 50mm:Maximum thickness requiring hub-centric precision engineering for load distribution integrity.
25mm thickness commands the highest absolute demand. 50mm specifications achieve the fastest growth rate among premium off-road builders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of precision-machined aluminum spacers from Chinese manufacturing clusters dominate international supply, while import demand concentrates in markets with active off-road recreation cultures and stringent vehicle modification enforcement protocols.
United States
Lifted truck aftermarket expansion in Texas and California generates companion spacer purchases for steering geometry correction. NHTSA guidelines on Federal Motor Vehicle Safety Standards compliance shape product safety testing protocols for hub-centric designs. The American Southwest desert racing communities around Moab, Utah and Johnson Valley, California sustain replacement demand for trail-damaged components.
Germany
Performance tuning culture around the Nürburgring and Stuttgart drives demand for track-width expansion on European performance vehicles. KBA type-approval requirements for aftermarket wheel components influence structural validation investments by exporters targeting the market. The Baden-Württemberg automotive cluster anchors precision machining capabilities serving both domestic fitment and re-export programs.
Australia
Remote-area four-wheel-drive touring and mining fleet applications create dual demand for both recreational and commercial-grade spacers. The country's national automotive safety regulator maintains strict enforcement of wheel modification standards that favor certified suppliers. Perth-based fabricators serve Western Australian mining operations requiring heavy-duty steel variants for load-rated commercial applications.
Japan
JDM wheel fitment culture and stance modification trends sustain niche demand for thin-profile hub-centric spacers. METI industrial standards and JIS certification requirements filter market access for imported components. Osaka-area machining shops specialize in ultra-precise center bore work for domestic luxury vehicle applications.
United Arab Emirates
Desert dune bashing and luxury vehicle customization in Dubai and Abu Dhabi drive premium spacer demand for high-performance SUVs. MOHAP product safety oversight applies to automotive aftermarket components entering the market. Sharjah's industrial free zones host aluminum forging operations serving Gulf Cooperation Council distribution networks.
Wheel Spacers and Adapters Market Competitive Landscape
Listed leaders compete with private specialists across certification tier and distribution channel. The vendor base stratifies between ISO 9001-certified precision manufacturers serving fleet contracts and unbranded commodity producers flooding online marketplaces. Three archetypes dominate: hub-centric engineering specialists commanding premium positioning, high-volume CNC fabricators competing on SKU breadth, and private-label assemblers sourcing billet blanks from concentrated forging capacity. Capacity expansion and direct-to-consumer digital fitment tools represent the dominant competitive moves reshaping channel economics.
Among North American off-road specialists, Spidertrax and Rugged Ridge exemplify the hub-centric precision tier, while ECCPP represents high-volume online distribution archetypes. These three entities anchor the competitive spectrum from trail-validated premium positioning to mass-market SKU coverage, with each occupying distinct price-performance coordinates that reflect their underlying manufacturing and channel strategies.
| Leading Market Players |
|---|
| Spidertrax |
| Rugged Ridge |
| ECCPP |
| Titan Wheel Accessories |
| Precision European Motorwerks |
| Supreme Suspensions |
| OrionMotorTech |
| RockTrix |
| BONOSS |
| Others |
Value Network & Pricing Analysis
Foundry utilization rates above 85 percent at domestic billet steel producers create pricing power asymmetries that propagate through commercial truck spacer tiers while aluminum forging clusters in Guangdong and Zhejiang provinces compress margin floors on consumer-grade hub-centric units through excess capacity competition.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the wheel spacers and adapters market. Price differentiation rests on ISO 9001 certification grade and SAE J2530 structural validation depth, with certified precision manufacturers commanding 40-60 point spreads over unbranded commodity producers. Cost compression in economy-tier aluminum spacers is intensifying because aerospace and industrial demand for 6061-T6 alloys elevates input costs faster than downstream absorption permits. Fleet maintenance contracts show least price sensitivity due to liability exposure, while daily-driver passenger vehicle owners exhibit highest elasticity amid insurer uncertainty on aftermarket modifications.
Supply Chain Analysis
Strategic stockpile preferences dominate commercial truck procurement, with municipal fleets maintaining 90-120 day steel spacer inventories to hedge foundry delivery volatility, while consumer aftermarket channels run lean just-in-time replenishment from Chinese aluminum forging clusters. Raw material dependencies center on 6061-T6 aluminum billet, billet steel from concentrated domestic foundries, and precision cutting tools for CNC hub bore machining. Single-source vulnerability concentrates in heavy-duty steel forging capacity, where three domestic suppliers control fleet-grade production. Distribution runs through specialty 4x4 retailers for hub-centric precision components and Amazon marketplace intermediaries for bolt-on commodity units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wheel spacers and adapters incumbents face substitution pressure from integrated lift kit manufacturers bundling companion spacers, requiring defensive positioning around certification moats and installer network captivity.
For Market Incumbents: Shield premium positioning by deepening SAE J2530 validation investments beyond baseline requirements to defend against liability exposure in commercial fleet segments. Capture installer network loyalty through video-based torque verification services that reduce warranty claims while building recurring engagement. Vertical integration into CNC machining talent pipelines addresses operator scarcity constraining hub-centric production expansion. For New Entrants and Emerging Players: Digital fitment configurators represent the most penetrable service-layer gap, with incumbents under-serving direct-to-consumer customization demand for bolt pattern and thickness specification. Target electric SUV owners seeking wheel offset correction for battery-pack-constrained platforms, where hub-centric precision requirements exceed commodity producer capabilities. Deploy online CNC configurators with VIN-specific compatibility engines to capture margin previously retained by distribution intermediaries. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among ISO 9001-certified precision manufacturers serving municipal fleet maintenance contracts with multi-year service agreements. Acquisition focus should center on mid-cap specialists with captive CNC machining capabilities and established third-party structural testing documentation. Watch NHTSA enforcement intensity on Federal Motor Vehicle Safety Standards compliance as the inflection signal separating certified premium suppliers from liability-exposed commodity producers.| Strategic Initiative | Industry Significance |
|---|---|
| SAE J2530 Validation Investment | Third-party structural testing documentation defends product liability positions against NHTSA scrutiny. |
| Direct-to-Consumer CNC Configurator Launch | Online bolt pattern and thickness specification captures margin from distribution intermediaries. |
| ISO 9001 Certification Pathway | Quality management credentialing unlocks municipal and commercial fleet maintenance contracts. |
| Installer Network Captivity Program | Video-based torque verification services build recurring engagement with 4x4 specialty retailers. |
| CNC Machining Talent Pipeline Development | In-house operator training addresses precision milling scarcity constraining hub-centric production. |
Research Methodology
Desk research of SAE technical standards documentation, NHTSA guidance memoranda, and customs trade flow data preceded structured interviews with aftermarket distributor procurement managers, CNC machining shop supervisors, fleet maintenance directors, and specialty 4x4 retailer owners. Primary fieldwork combined telephone interviews and facility observations at aluminum forging operations in Guangdong province and domestic steel foundry clusters. Secondary validation drew from SEC filings of listed automotive component suppliers, IHS Markit vehicle registration databases, and ISO certification registry extracts. Bottom-up demand modeling triangulated against top-down market sizing from production capacity estimates.
Variance decomposition across the projection horizon isolates volume drivers by product type, vehicle application, material grade, and regional regulatory enforcement intensity. Segmentation dimensions modeled include hub-centric versus bolt-on configurations, passenger vehicle versus commercial fleet end-use, and certified versus uncertified supplier tiers. CAGRs were derived from elasticity-adjusted demand curves incorporating lift kit installation correlation, EV platform fitment incompatibility resolution rates, and replacement cycle frequency for trail-damaged off-road components. Aluminum price volatility and foundry capacity utilization serve as industry-specific forecast sensitivity inputs.
Underlying assumptions cover NHTSA enforcement continuity, insurer liability position stability, and Chinese aluminum forging capacity expansion, with deviation risk concentrated in state-level vehicle modification enforcement patterns and domestic steel foundry consolidation outcomes. Forecasts reflect these documented assumptions with explicit scenario boundaries. Revision becomes warranted when NHTSA guidance crosses into formal rulemaking or when domestic steel foundry capacity drops below two viable suppliers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Automotive Intelligent Tires Market
Tires and Wheels
Tire Inflating Machine Market
Tires and Wheels
Global Ultra High Performance Tire Market
Tires and Wheels
Automotive All-Season Tire Market
Tires and Wheels
Racing Tires Market
Tires and Wheels
Elastic Polyurethane Wheels Market
Tires and Wheels
Automotive 3D Printed Tires Market
Tires and Wheels
Asia Pacific 2-Wheeler Tire Market
Tires and Wheels
North America 2-Wheeler Replacement Tire Market
Tires and Wheels
Automotive Wheel Spindle Market
Tires and Wheels
Tire Carousel Market
Tires and Wheels
Global Tire Curing Press Market
Tires and Wheels
Europe Aircraft Tires Market
Tires and Wheels
Automotive Steel Wheels Market
Tires and Wheels
Connected Tire Market
Tires and Wheels
Global Tires Market