
 Torque Testers Market | 2026-2036
Torque Testers Market Size, Share, and Industry Trends Forecast 2026-2036
Torque Testers Market Outlook
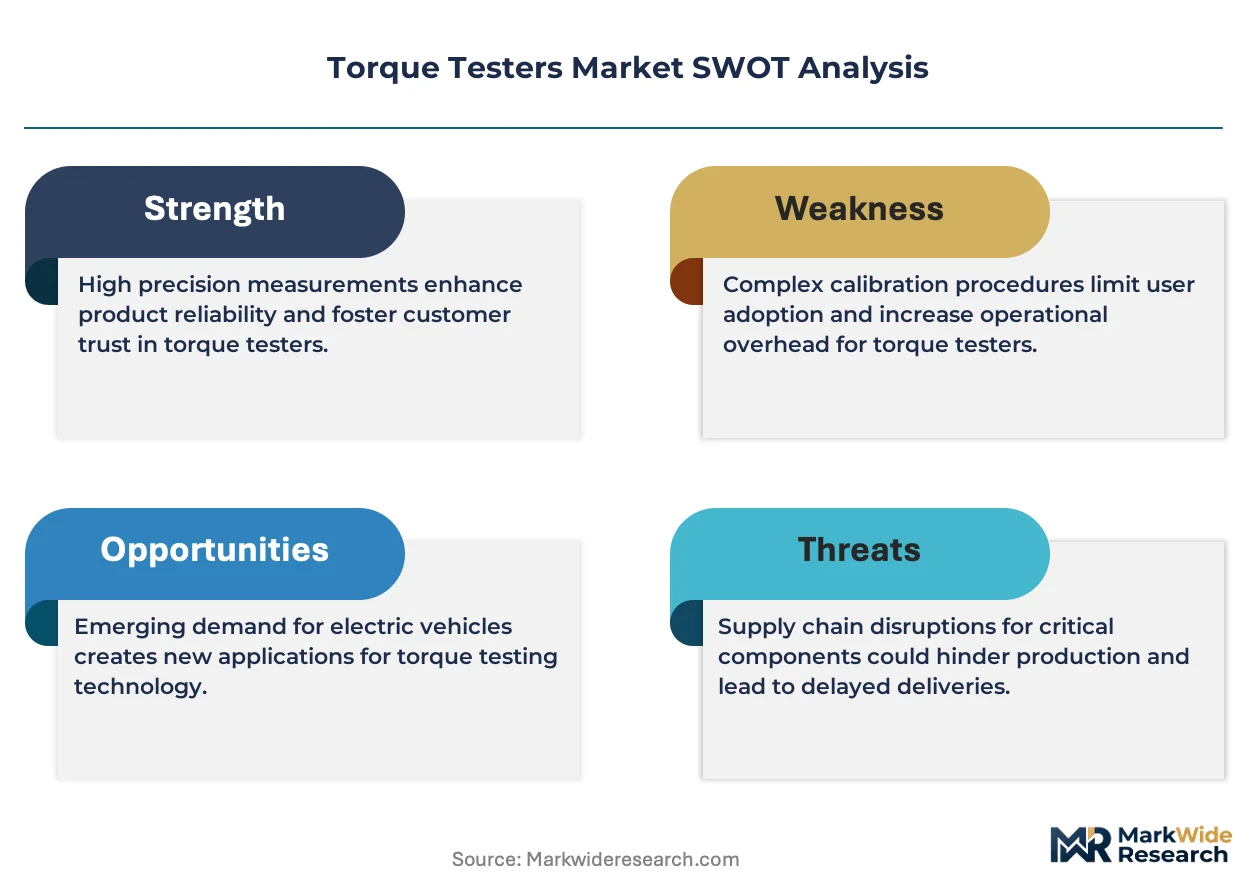
Modular sensor configurations with swappable drive heads is broadening buyer choice across mid-range torque testing platforms. Sturtevant Richmont leverages its captive calibration laboratory network to sustain premium positioning in aerospace compliance workflows. Mecmesin anchors European demand through localized service infrastructure and application-specific fixture development. Norbar competes on extended-range capacity, dominating offshore wind turbine bolt tensioning specifications where peak torque values exceed conventional instrument limits.
A torque tester measures rotational force applied to fasteners, components, or assemblies, typically quantifying values in Newton-meters or inch-pounds through strain gauge, piezoelectric, or mechanical spring mechanisms. The device ensures joint integrity, prevents material fatigue, and validates assembly specifications across production environments. Digital torque testers with electronic load cells and data logging capability lead product type demand, while mechanical units retain share in field service and budget-constrained maintenance operations. Application segmentation tilts toward automotive and aerospace where regulatory traceability mandates drive replacement cycles and upgrade investment.
FDA 21 CFR Part 11 compliance requirements shape electronic torque tester specifications in pharmaceutical packaging and medical device assembly, mandating audit trails and electronic signatures for validation records. OSHA lockout/tagout standards and ISO 9001 quality management frameworks reinforce demand for calibrated instrumentation with certificate-backed traceability chains. Stakeholders must weigh total cost of ownership against calibration interval flexibility when selecting between vendor-managed service contracts and in-house metrology laboratory investment.
Market Dynamics
ISO 6789 calibration standard adoption across European and North American manufacturing bases is compressing replacement cycles and forcing metrology infrastructure upgrades among precision assembly operations.
Growth Catalysts
- Automotive OEM quality budgets:Assembly line torque verification spending is expanding as electric vehicle powertrain manufacturing demands tighter fastener specifications.
- FDA 21 CFR Part 11:Pharmaceutical packaging and medical device assembly mandates now require audit trails and electronic signatures, driving validation-capable tester procurement.
- Offshore wind specifications:Bolt tensioning requirements for turbine installation exceed conventional instrument limits, creating specialized demand for extended-range capacity platforms.
Market Restraints
- Strain gauge input volatility:Semiconductor supply constraints for precision sensor components create lead time unpredictability for mid-range platform manufacturers.
- German calibration laboratory concentration:Premium positioning depends on captive metrology networks concentrated in single-country infrastructure, creating geographic supply risk.
- Mechanical spring substitution:Budget-constrained field service operations retain legacy mechanical units, limiting digital platform penetration in price-sensitive maintenance segments.
Strategic Opportunities
- Japanese precision manufacturing clusters:Capital equipment procurement concentration in automotive and electronics assembly creates concentrated demand for application-specific fixture development.
- OSHA lockout/tagout integration:Safety-standard alignment with calibrated instrumentation opens industrial maintenance verticals previously served by uncertified equipment.
- Wireless data logging convergence:Bluetooth-enabled torque testers paired with cloud-based asset management systems create new service revenue streams for equipment vendors.
Industry Challenges
- Metrology technician scarcity:In-house calibration laboratory investment requires certified personnel that regional labor markets cannot supply at scale.
- ISO 9001 traceability documentation:Certificate-backed chain maintenance creates administrative burden for multi-site manufacturers with decentralized quality operations.
- Legacy system integration:Digital torque testers must interface with existing manufacturing execution systems, creating protocol compatibility delays in brownfield facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Torque Testers Market |
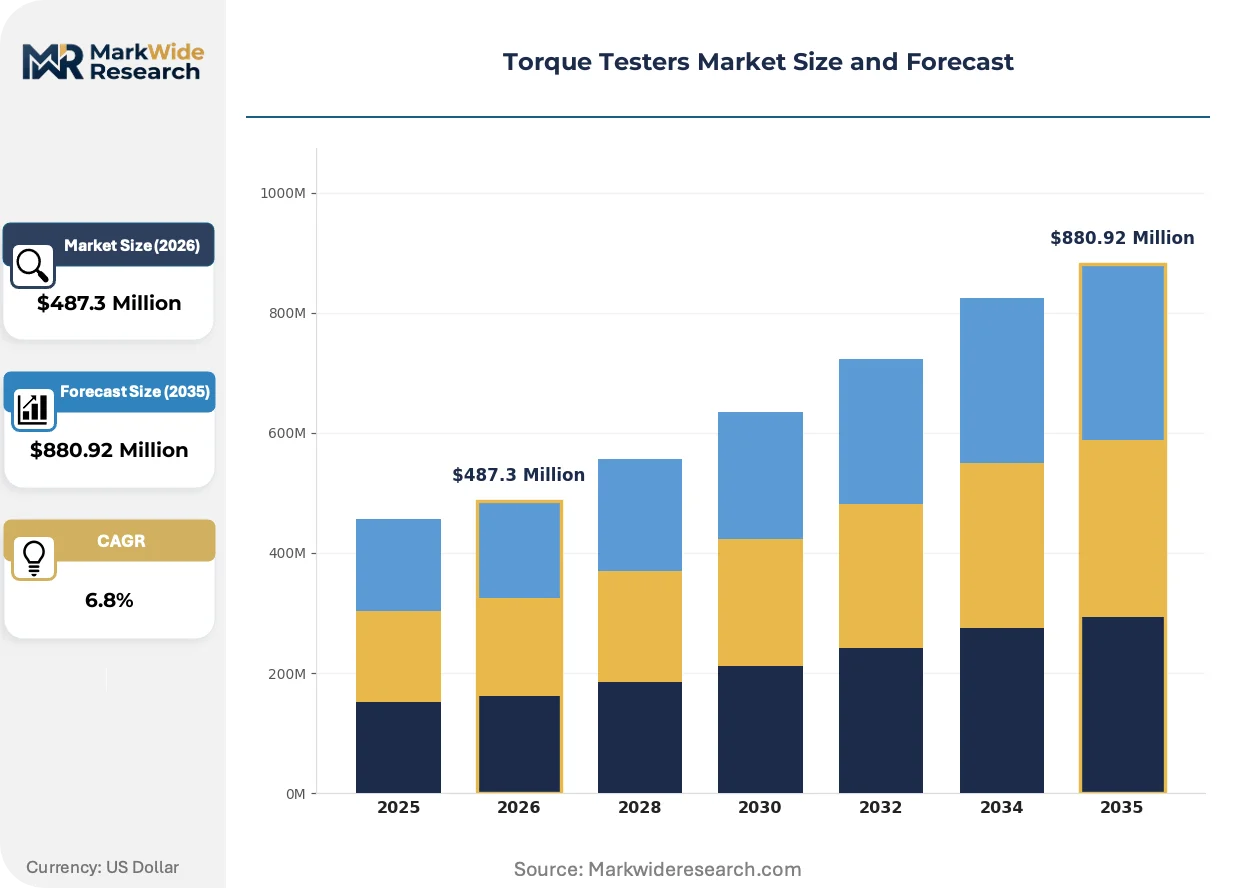
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Torque Testers, Digital Torque Testers, Mechanical Torque Testers, Static Torque Testers Technology: Electronic, Hydraulic, Pneumatic, Manual Application: Aerospace, Automotive, Manufacturing, Electronics End User: OEMs, Service Providers, Research Institutions, Quality Control Departments |
| Companies Covered | Sturtevant Richmont, Mecmesin, Imada, Norbar, Mountz, Mark-10, PCE Instruments, Yokota Industrial, Tohnichi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Torque Testers Market Strategic Shifts
Modular hardware architectures and wireless connectivity protocols are compressing product lifecycles and enabling service-model transitions among established equipment vendors.
Wireless torque measurement systems with integrated Bluetooth modules and cloud-native firmware are consolidating field service and production floor data streams into unified asset management platforms. Automotive suppliers in Germany and the United States are adopting these systems fastest, replacing tethered benchtop configurations. The technology is consolidating vendor revenue toward subscription-based calibration and software update services rather than discrete hardware transactions.
EU MDR medical device regulation and FDA 21 CFR Part 11 validation requirements are mandating electronic record integrity for assembly operations. Torque tester specifications now require embedded audit trail generation and cryptographic signature capability as standard features. Pharmaceutical packaging lines in Ireland, Switzerland, and Massachusetts are retrofitting existing stations with compliant instrumentation ahead of inspection readiness deadlines.
Buyer preference for vendor-managed service contracts over in-house metrology investment is fragmenting traditional capital equipment purchasing patterns. Tier-one aerospace contractors in Toulouse and Seattle are unbundling after-sales calibration from initial hardware procurement, selecting suppliers based on regional technician density. Japan's automotive sector exhibits the strongest resistance to this shift, maintaining captive calibration capabilities for intellectual property protection reasons.
Torque Testers Market Segmentation
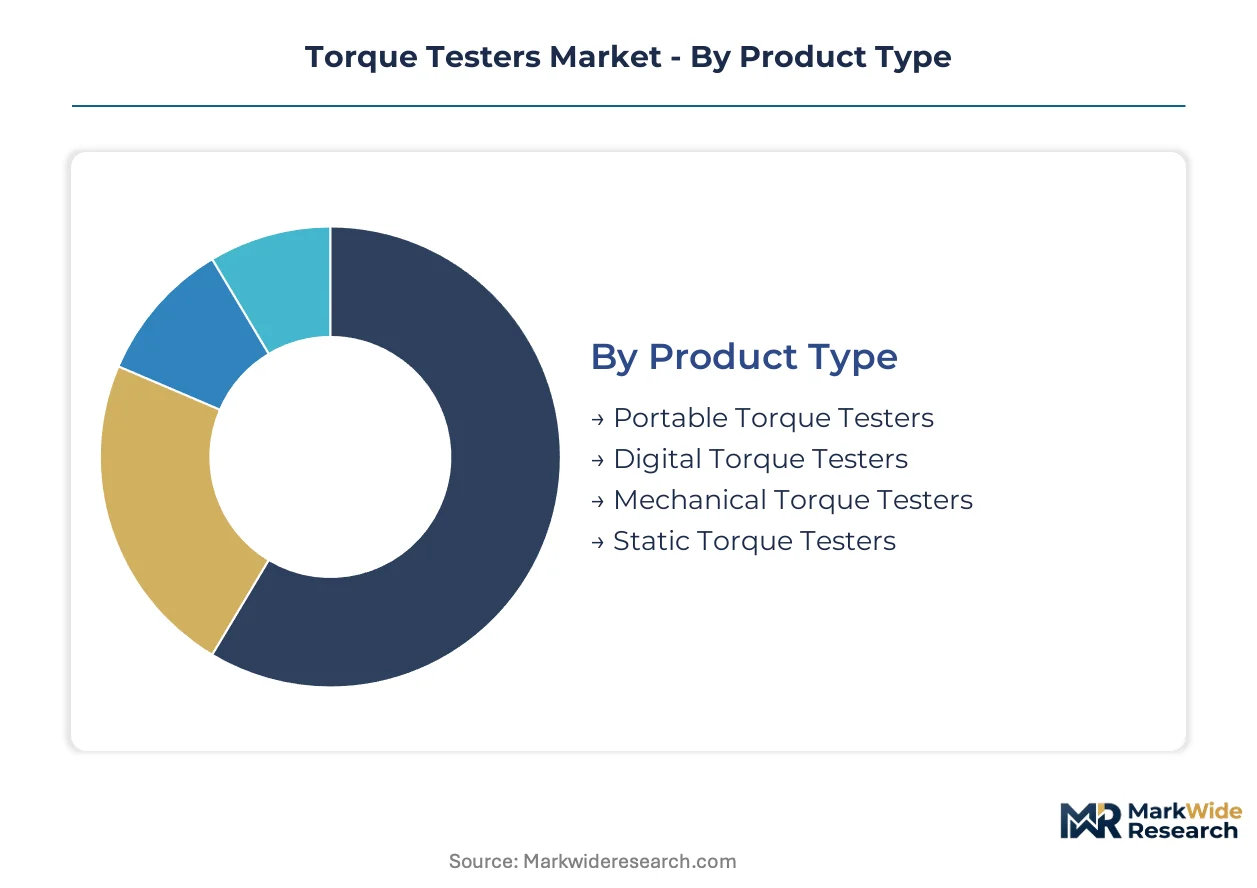
Torque tester procurement patterns diverge sharply across capital intensity tiers, with electronic platforms demanding multifold higher upfront investment than mechanical alternatives. Understanding these investment gradients helps vendors align pricing architectures with buyer budget cycles and calibration service attach rates.
Product Type:
Capital intensity stratifies most dramatically here, with electronic platforms requiring precision sensor arrays and embedded firmware development that mechanical units avoid entirely.
- Digital Torque Testers:Electronic load cells and data logging capability define these platforms, with strain gauge or piezoelectric sensors delivering traceable measurements to ISO 6789 standards. Pharmaceutical packaging lines in Massachusetts and medical device assembly in Switzerland concentrate procurement here, driven by FDA 21 CFR Part 11 validation mandates for audit trails and electronic signatures.
- Portable Torque Testers:Battery-powered units with wireless Bluetooth modules enable field calibration and production floor mobility without tethered benchtop constraints. German automotive suppliers and Japanese electronics manufacturers lead adoption, replacing fixed installations with cloud-connected asset management integration.
- Mechanical Torque Testers:Spring-based or beam-deflection mechanisms serve budget-constrained maintenance operations with minimal calibration infrastructure.
- Static Torque Testers:Benchtop configurations for laboratory and incoming inspection environments where rotational measurement occurs without dynamic load application.
Digital torque testers absorb the bulk of installed capacity; portable torque testers are expanding most quickly.
Technology:
Volume concentration favors electronic systems, though pneumatic and hydraulic alternatives retain defensible positions in high-torque industrial environments where electrical hazards or contamination risks prohibit standard electronic deployment.
- Electronic:Strain gauge and piezoelectric transducers with microprocessor-controlled signal conditioning dominate precision assembly verification. Aerospace compliance workflows in Toulouse and Seattle standardize on these platforms for certificate-backed traceability chains.
- Manual:Dial-indicating or break-over mechanisms persist in field service and small-lot production where capital budgets exclude electronic investment. Maintenance departments in price-sensitive manufacturing verticals retain these units despite limited data documentation capability.
- Hydraulic:Fluid-pressure amplification systems address bolt tensioning applications where torque multiplication exceeds direct electronic measurement ranges.
- Pneumatic:Compressed-air actuation serves explosive atmospheres and cleanroom environments where electrical spark risks or particulate generation from electronic components create compliance conflicts.
Electronic technology commands the dominant share of new procurement; hydraulic systems are gaining share fastest in offshore wind installation specifications.
Application:
Margin structures vary substantially across these verticals, with aerospace and pharmaceutical-facing automotive commanding premium pricing for validation documentation that general manufacturing will not fund.
- Automotive:Assembly line torque verification spans powertrain, chassis, and interior fastener validation, with electric vehicle manufacturing tightening specifications for battery enclosure and motor mounting hardware. OEM quality budget expansion in Germany, Japan, and the United States drives replacement cycle compression.
- Aerospace:Regulatory traceability mandates from FAA and EASA enforce calibrated instrumentation with unbroken certificate chains for flight-critical joint verification. Tier-one contractors in Toulouse and Seattle unbundle after-sales calibration from hardware procurement, selecting suppliers by regional technician density.
- Manufacturing:General industrial assembly across machinery, appliance, and consumer goods production, with ISO 9001 quality management frameworks reinforcing demand for traceable measurement.
- Electronics:Miniaturized fastener and component torque validation for semiconductor equipment, consumer devices, and precision instrumentation assembly.
Automotive applications deploy the largest installed base; aerospace specifications are climbing the fastest as regulatory deadlines compress upgrade timelines.
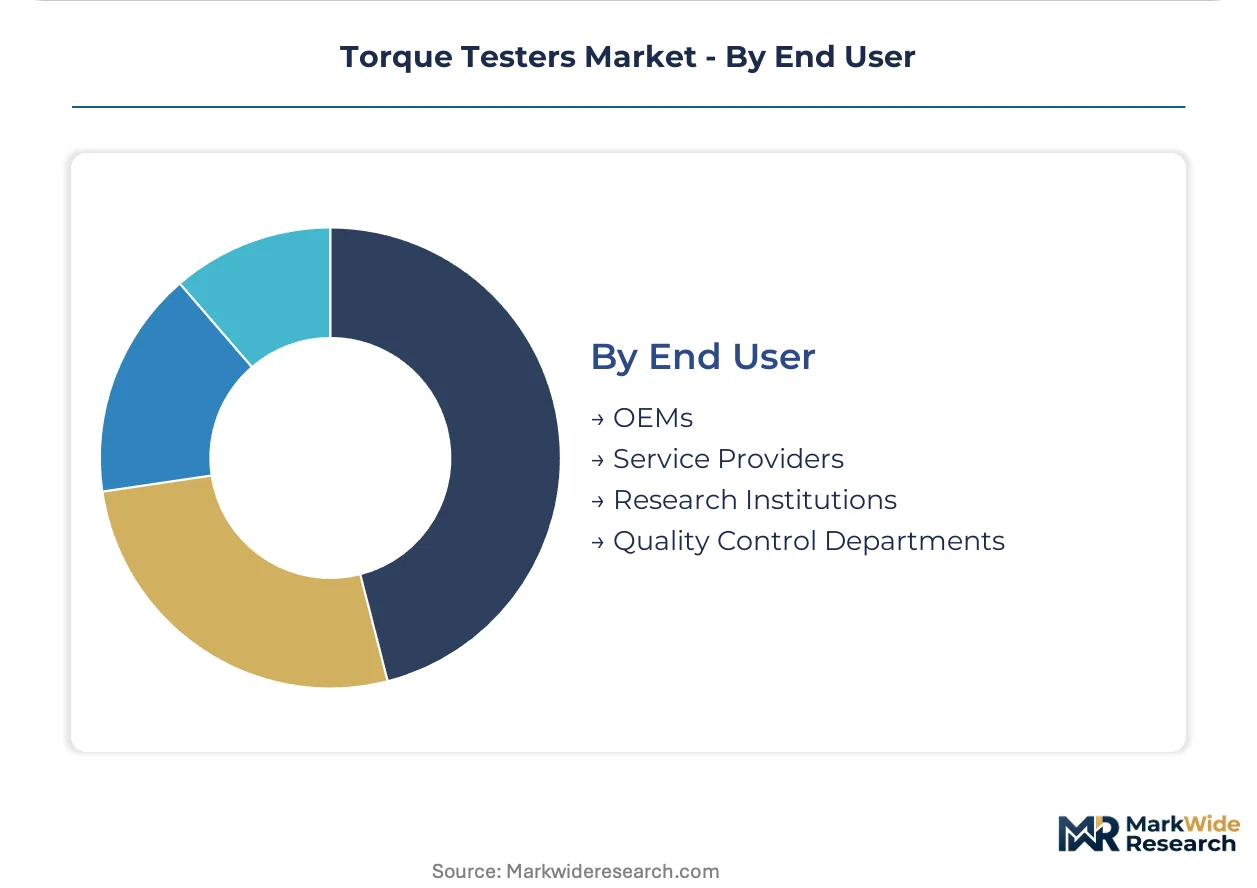
End User:
Customer type determines service contract penetration, with OEMs accepting vendor-managed calibration while research institutions insist on captive metrology capabilities for intellectual property protection.
- OEMs:Original equipment manufacturers integrate torque testers directly into production lines, with procurement decisions centralized under quality engineering and manufacturing engineering functions. Capital equipment budgets in German and Japanese automotive clusters concentrate demand for application-specific fixture development.
- Quality Control Departments:Incoming inspection and final audit functions within multi-site manufacturers face administrative burden from ISO 9001 traceability documentation across decentralized operations.
- Service Providers:Independent calibration laboratories and field service contractors prioritize portable platforms with rapid turnaround and transport durability.
- Research Institutions:Universities and national metrology laboratories maintain captive calibration capabilities, resisting vendor-managed service models for intellectual property protection and experimental flexibility.
OEMs represent the largest addressable spend; quality control departments are expanding procurement fastest as ISO 6789 adoption forces metrology infrastructure upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany and Japan where precision manufacturing clusters demand calibrated instrumentation, while consumption spreads across automotive and aerospace hubs in the United States, France, and Switzerland requiring traceable torque verification systems.
United States
Electric vehicle powertrain manufacturing tightens fastener specifications for battery enclosures and motor mounting hardware. FDA 21 CFR Part 11 mandates audit trails and electronic signatures for pharmaceutical packaging lines. Massachusetts medical device assembly clusters and Detroit automotive corridors drive replacement cycle compression for validation-capable testers.
Germany
Automotive OEM quality budgets expand for assembly line torque verification as ISO 6789 calibration standards compress replacement cycles. KBA vehicle safety regulations enforce unbroken certificate chains for production floor instrumentation. Stuttgart and Munich precision manufacturing clusters concentrate capital equipment procurement for application-specific fixture development.
Japan
Automotive and electronics assembly sectors maintain captive calibration capabilities for intellectual property protection. METI industrial standards reinforce traceable measurement requirements across multi-site manufacturers. Nagoya and Osaka manufacturing belts resist vendor-managed service models while sustaining premium positioning for precision sensor platforms.
France
Aerospace tier-one contractors unbundle after-sales calibration from hardware procurement based on regional technician density. EASA regulatory traceability mandates enforce calibrated instrumentation for flight-critical joint verification. Toulouse aerospace clusters standardize on electronic platforms with certificate-backed traceability chains.
Switzerland
Pharmaceutical packaging operations retrofit existing stations with FDA 21 CFR Part 11 compliant instrumentation ahead of inspection readiness deadlines. Swissmedic medical device regulations mandate electronic record integrity for assembly operations. Basel and Zurich pharmaceutical corridors concentrate demand for embedded audit trail generation capability.
Torque Testers Market Competitive Environment
The competitive structure tilts toward specialization-driven differentiation rather than scale consolidation. Premium positioning depends on captive calibration laboratory networks and application-specific fixture development capabilities. Two strategic archetypes dominate: precision metrology specialists with regional service infrastructure, and extended-range capacity providers serving offshore industrial specifications. Geographic expansion through localized technician density and strategic partnerships for wireless data logging integration represent the dominant competitive moves.
Among European precision metrology specialists, Mecmesin and Norbar occupy positions anchored by regional service infrastructure and extended-range capacity platforms respectively. Sturtevant Richmont exemplifies the premium-tier archetype through captive calibration laboratory networks concentrated in aerospace compliance workflows. Japanese specialists including Imada and Tohnichi represent the precision manufacturing cluster focus, while Mountz and Mark-10 sit within the North American vendor tier serving automotive and industrial maintenance verticals.
| Leading Market Players |
|---|
| Sturtevant Richmont |
| Mecmesin |
| Imada |
| Norbar |
| Mountz |
| Mark-10 |
| PCE Instruments |
| Yokota Industrial |
| Tohnichi |
| Others |
Value Chain & Pricing Dynamics
Strain gauge sensor component indices cascade through torque tester manufacturing tiers, compressing margins in mid-range electronic platforms while premium calibration-backed instruments retain pricing power through captive metrology network scarcity.
Pricing Analysis
Margin tightening in mid-range digital platforms reflects semiconductor input volatility and extended lead times for piezoelectric transducers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 6789-certified laboratory units from production-floor verification tools and field-service mechanical alternatives. Cost-down pressure on standard-tier products accelerates because automotive OEMs unbundle hardware procurement from calibration service contracts. Quality control departments in multi-site manufacturers exhibit highest price sensitivity; aerospace tier-one contractors in Toulouse and Seattle show least sensitivity due to regulatory traceability mandates.
Supply Chain Analysis
Freight cost escalation from German calibration laboratory concentration creates geographic supply risk for North American and Asian buyers requiring certificate-backed traceability chains. Manufacturing concentrates in Germany, Japan, and the United States where precision sensor fabrication and captive metrology infrastructure co-locate. Component sourcing draws from Taiwanese semiconductor foundries for strain gauge signal conditioning, Japanese specialty steel for drive heads, and Swiss precision machining for calibration artifacts. Single-source vulnerability concentrates in German captive laboratory networks. Distribution runs through authorized regional service partners with technician density determining procurement decisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified metrology technician scarcity props pricing for vendor-managed calibration services, constraining supply expansion and sustaining premium positioning for established laboratory networks.
For Market Incumbents: Deploy captive calibration laboratory expansion in Japanese and North American precision manufacturing clusters to counter emerging portable platform entrants. Defensive consolidation through backward integration into strain gauge sensor supply reduces semiconductor lead time exposure. Reinforce aerospace compliance workflow positioning through EASA and FAA audit trail certification investments. For New Entrants and Emerging Players: Begin with wireless Bluetooth-enabled portable torque testers targeting German automotive supplier field service operations where tethered benchtop configurations face replacement pressure. White-space concentrates in cloud-connected asset management integration for mid-tier manufacturers resisting full vendor-managed service models. Go-to-market through regional calibration service partnerships rather than direct hardware distribution. For Investors and Strategic Acquirers: The window for entry favors precision metrology specialists with regional technician density and application-specific fixture development capabilities over extended-range industrial capacity providers. Long-term viability hinges on subscription-based calibration revenue attachment rather than discrete hardware transaction models. Watch FDA 21 CFR Part 11 enforcement intensity in pharmaceutical packaging verticals as inflection indicator for validation-capable platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Calibration Laboratory Expansion | Builds regional technician density to capture aerospace tier-one contractor procurement in Toulouse and Seattle. |
| Wireless Data Logging Platform Launch | Consolidates field service and production floor data streams into unified asset management systems for German automotive suppliers. |
| Backward Integration into Sensor Supply | Reduces semiconductor lead time volatility exposure for mid-range electronic platform manufacturers. |
| Application-Specific Fixture Development | Captures Japanese precision manufacturing cluster demand for automotive and electronics assembly verification. |
| FDA 21 CFR Part 11 Compliance Certification | Unlocks pharmaceutical packaging line retrofit demand in Massachusetts and Swiss corridors ahead of inspection deadlines. |
Study Parameters
Independent corroboration across quality engineering directors, metrology laboratory managers, OEM procurement leads, and aftermarket service heads underwrites the qualitative findings. Primary interviews with tier-one aerospace contractors in Toulouse and Seattle, German automotive suppliers in Stuttgart, and Japanese electronics manufacturers in Nagoya combined with secondary validation from ISO 6789 calibration standard documentation, FDA 21 CFR Part 11 guidance publications, and customs trade data for precision instrumentation. Bottom-up segment sizing and top-down market triangulation cross-validate volume and value estimates.
Rate-of-change decomposition across the projection horizon segments torque tester demand by product type, technology, application, and end user, with additional modeling of regulatory compliance tier and calibration service attachment. CAGRs derive from segment-level growth rate synthesis applied to base-year installed capacity estimates. Forecast inputs include electric vehicle powertrain manufacturing expansion timelines and offshore wind turbine installation specifications exceeding conventional instrument limits.
Underlying measurement precision varies by segment; aerospace and pharmaceutical-facing automotive applications carry tighter precision than general manufacturing and field service maintenance. Forecasts reflect documented assumptions regarding ISO 6789 adoption velocity and semiconductor supply normalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Electric Vehicle Edrive Test Equipment Market
Automotive Testing and Simulation
Automotive Emission Analyzer Market
Automotive Testing and Simulation
Wheel Alignment Equipment Market
Automotive Testing and Simulation
Automotive Spot Weld Inspection System Market
Automotive Testing and Simulation
Vehicle Crash Testing Services Market
Automotive Testing and Simulation
Tire Testing Machine Market
Automotive Testing and Simulation
Automotive Battery Testing Market
Automotive Testing and Simulation
Railway Maintenance Machinery Market
Automotive Testing and Simulation
Automotive Driving Simulators Market
Automotive Testing and Simulation
On-Board Data Logger and Road Test Equipment System Market
Automotive Testing and Simulation
Global Automotive Wind Tunnel Testing Equipment Market
Automotive Testing and Simulation
High-Speed Highway Pilot and Lane Change Scenario Test Platforms Market
Automotive Testing and Simulation
Chassis Dynamometers Market
Automotive Testing and Simulation
Global Automotive Wind Tunnel Market
Automotive Testing and Simulation
Automotive Exhaust Analyzer Market
Automotive Testing and Simulation
ADAS Calibration Equipment Market