
 Autonomous Valet Parking System Scenario-Based Test Equipment Market | 2026-2036
Autonomous Valet Parking System Scenario-Based Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Valet Parking System Scenario-Based Test Equipment Market Insights
OEM-direct procurement channels for validation tooling is rewriting how test equipment reaches vehicle assemblers and Tier-1 suppliers. dSPACE leverages decades of hardware-in-the-loop dominance to anchor European supply relationships for parking scenario validation. Vector Informatik competes through deep embedded software integration that sustains recurring toolchain commitments across German automotive engineering centers. Siemens Digital Industries Software extends its digital twin portfolio into autonomous parking workflows, occupying a distinct position between physics simulation and regulatory documentation.
Autonomous Valet Parking System Scenario-Based Test Equipment comprises integrated hardware-software systems that replicate structured and unstructured parking environments through real-time sensor emulation, vehicle dynamics modeling, and traffic agent scripting to verify perception, planning, and control algorithms before physical road testing. These systems typically execute thousands of edge-case scenarios—occluded pedestrians, cross-traffic cyclists, degraded GNSS signals—at speeds impossible with prototype fleets alone. Scenario Simulation Platforms lead current revenue contribution because OEMs require exhaustive virtual mileage before homologation, while Sensor Emulators for LiDAR and ultrasonic arrays capture the fastest expansion as multi-sensor fusion architectures proliferate across premium and mass-market vehicle programs. Data Analytics Modules sit at the margin pool where forensic reconstruction of failure modes commands premium pricing from insurance evaluators and liability-conscious assemblers.
NHTSA in the United States, UNECE through its WP.29 framework in Europe, and Japan's MLIT collectively mandate documented scenario coverage for automated parking functions, forcing suppliers to invest in traceable test equipment that generates auditable validation evidence. The EU AI Act and emerging product liability directives in Germany and France further tighten requirements for algorithmic transparency in autonomous decision-making systems. Stakeholders must monitor which regulatory jurisdiction first mandates specific scenario libraries as de facto standards, since that determination will reshape R&D allocation and equipment certification priorities across the supply base.
Market Dynamics
Homologation pressure from NHTSA, UNECE, and Japan's MLIT is forcing Tier-1 suppliers to abandon physical prototype validation in favor of auditable scenario simulation platforms that compress development cycles while satisfying traceability mandates.
Growth Catalysts
- UNECE WP.29 Type Approval Framework:Mandated documentation of edge-case scenario coverage for automated parking functions is driving procurement of sensor emulation hardware by German and Japanese automotive suppliers.
- Multi-sensor fusion architectures:Proliferation of LiDAR-ultrasonic-RADAR combinations across premium and mass-market vehicle programs is expanding demand for synchronized test modules.
- Insurance liability exposure:Forensic reconstruction capabilities in data analytics modules command premium pricing from liability-conscious assemblers seeking failure-mode documentation.
Market Restraints
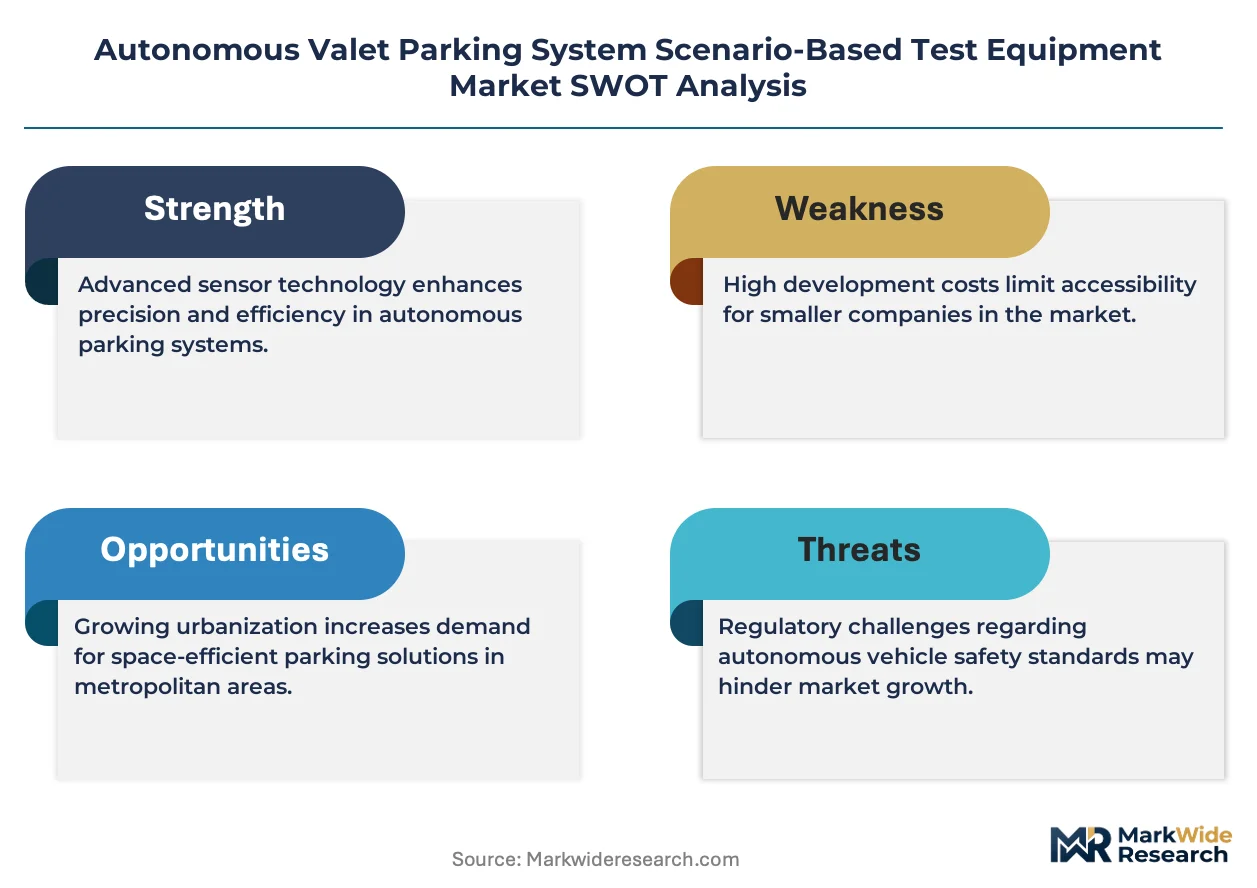
- High-fidelity sensor emulation costs:Real-time LiDAR point-cloud generation and V2X protocol simulation require specialized FPGA arrays and RF equipment that inflate capital expenditure thresholds.
- European vendor concentration:Hardware-in-the-loop platform supply clusters around German engineering centers, creating procurement risk for Asian and North American OEMs.
- Regulatory fragmentation:Divergent scenario library requirements between NHTSA guidance documents and UNECE technical specifications force redundant test equipment configurations.
Strategic Opportunities
- China's NEV certification pipeline:Domestic OEMs preparing for MIIT autonomous driving homologation lack indigenous scenario simulation capacity, creating import substitution openings for validated foreign platforms.
- Digital twin integration:Convergence of physics-based vehicle dynamics modeling with regulatory documentation workflows enables single-platform validation across engineering and compliance functions.
- Subscription-based toolchain access:Cloud-delivered scenario libraries and pay-per-mile simulation pricing are penetrating mid-tier suppliers previously priced out of perpetual-license models.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262-certified specialists capable of mapping scenario coverage to ASIL ratings command compensation premiums that strain mid-cap supplier budgets.
- Legacy HIL integration friction:Decades-old powertrain test rigs require expensive retrofitting to accommodate parking-specific vehicle dynamics and low-speed sensor fusion workloads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Valet Parking System Scenario-Based Test Equipment Market |
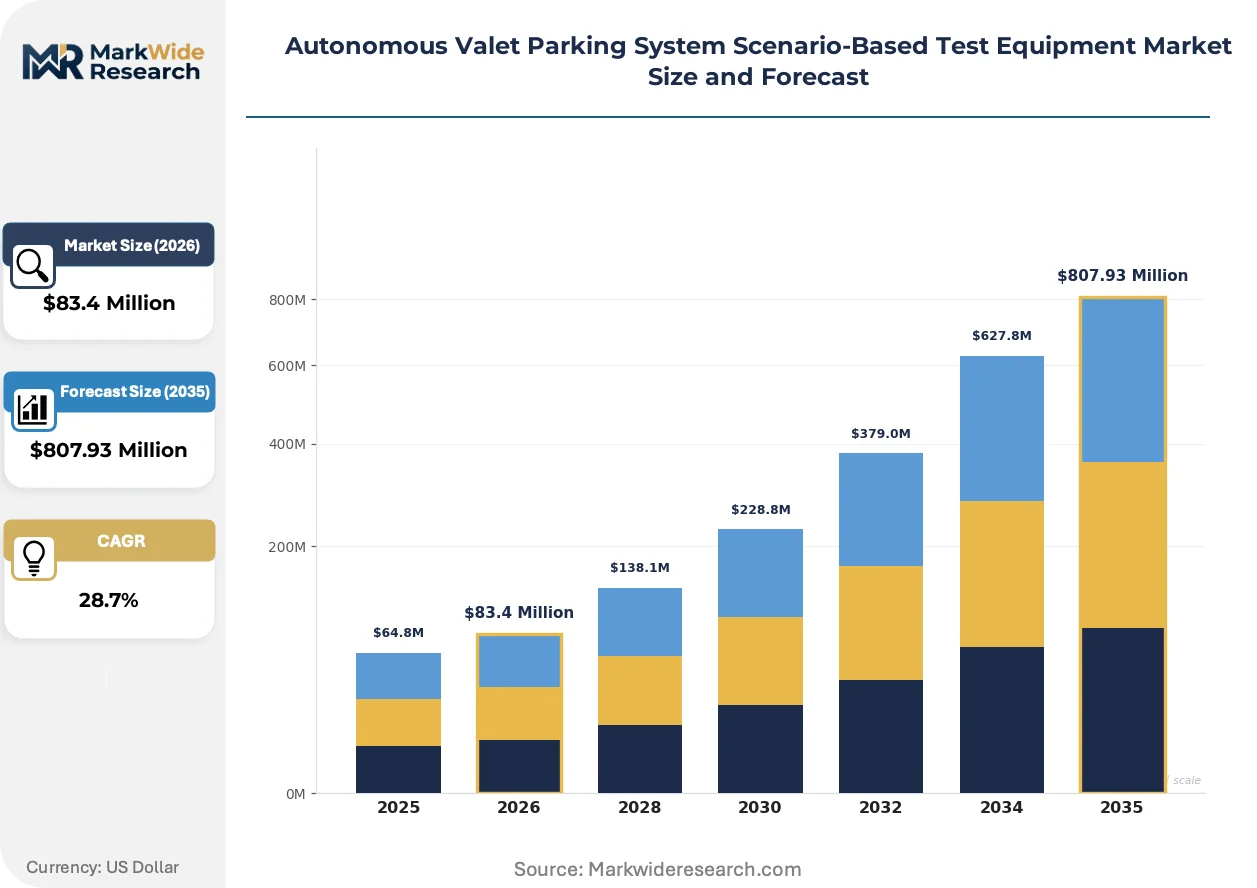
| Market Size in 2026 | $83.4 Million |
| Market Size in 2035 | $807.93 Million |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scenario Simulation Platforms, Sensor Emulators, Test Controllers, Data Analytics Modules, Communication Interfaces Technology: LiDAR, Radar, Ultrasonic Sensors, Computer Vision, V2X Communication, GNSS Application: Parking Assistance, Traffic Management, Collision Avoidance, Navigation Calibration, Safety Validation End User: Automotive Tier-1 Suppliers, Vehicle Assemblers, Research Institutes, Insurance Evaluators |
| Companies Covered | dSPACE, AVL, Vector Informatik, IPG Automotive, Foretellix, Cognata, Siemens Digital Industries Software, MathWorks, ANSYS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Valet Parking System Scenario-Based Test Equipment Market Trends and Innovations
Real-time sensor emulation is compressing the boundary between virtual validation and physical road testing, with three convergent developments reshaping how parking algorithms achieve homologation readiness.
Software-defined sensor emulation is rendering obsolete the rack-mounted hardware arrays that previously dominated validation labs. dSPACE and Vector Informatik deployments across Stuttgart and Wolfsburg engineering centers now execute ultrasonic and LiDAR point-cloud generation on GPU clusters, slashing scenario iteration latency from weeks to hours. This compression is eliminating the second prototyping cycle that historically separated simulation sign-off from fleet deployment.
The EU AI Act's algorithmic transparency requirements are extending scenario documentation obligations beyond functional safety into explainability auditing. European OEMs must now generate interpretable traces for parking trajectory decisions, forcing test equipment vendors to embed logging modules that capture intermediate planning states. German suppliers are responding by integrating regulatory documentation export functions directly into their toolchain interfaces.
Validation contracting is fragmenting from centralized OEM procurement toward distributed Tier-1 responsibility. Bosch and Continental are assuming direct scenario simulation investments previously borne by vehicle assemblers, reflecting liability transfer in automated parking system supply agreements. This reallocation concentrates equipment procurement authority within a narrower supplier tier across Bavaria and Baden-Württemberg.
Autonomous Valet Parking System Scenario-Based Test Equipment Market Segmentation
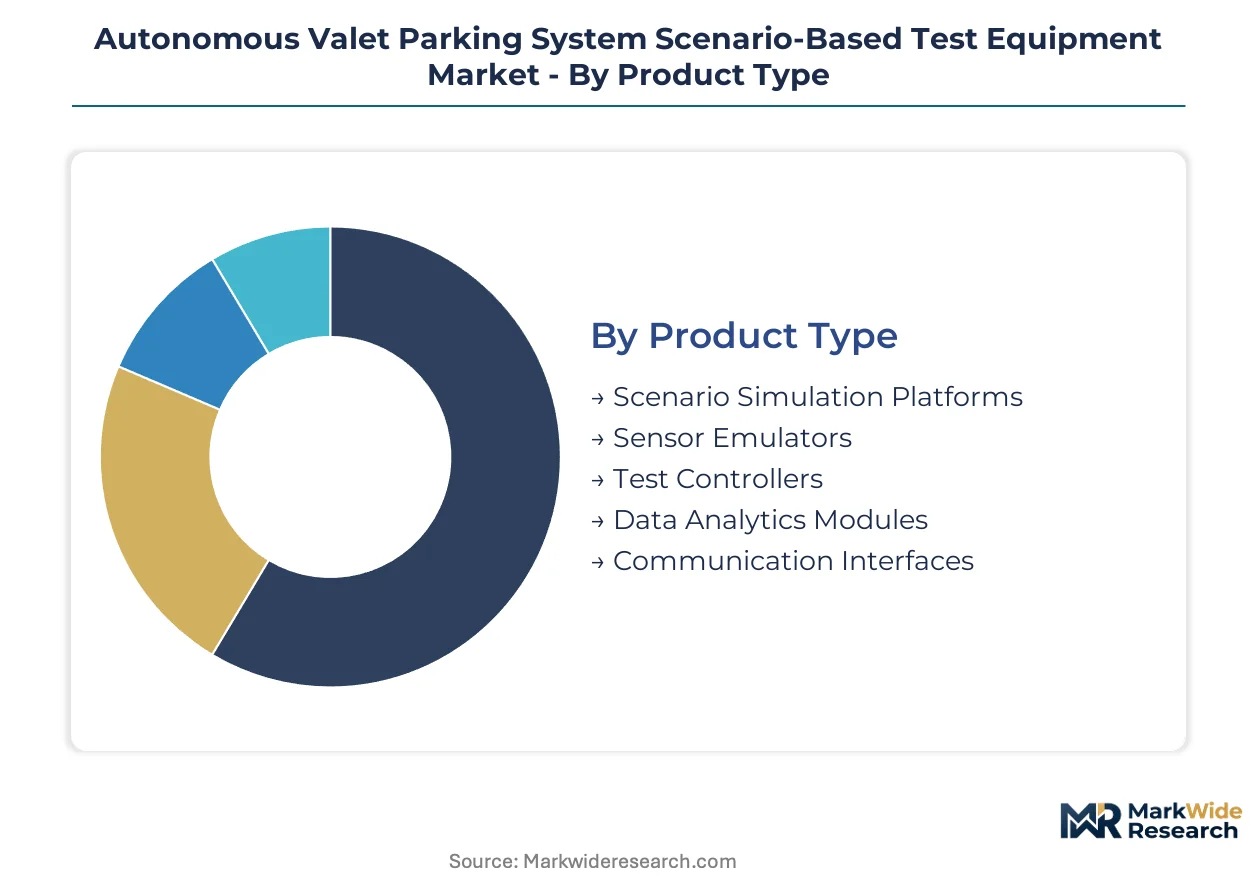
Segmentation in autonomous valet parking test equipment reflects how validation workflows fragment across sensor modalities, regulatory requirements, and liability structures. Equipment procurement decisions hinge on which stakeholder bears homologation risk.
Product Type:
Cost tier stratification separates capital-intensive hardware platforms from software modules that scale through licensing.
- Scenario Simulation Platforms:Integrated hardware-software systems executing thousands of edge-case scenarios—occluded pedestrians, cross-traffic cyclists, degraded GNSS signals—at speeds impossible with prototype fleets alone. German and Japanese Tier-1 suppliers dominate procurement as NHTSA and UNECE documentation mandates tighten. These platforms absorb the largest share of OEM validation budgets due to their position as the primary homologation gate.
- Sensor Emulators:Real-time LiDAR point-cloud generation and ultrasonic array replication on GPU clusters, slashing scenario iteration latency from weeks to hours. Multi-sensor fusion architectures proliferating across premium and mass-market vehicle programs are expanding demand most rapidly for synchronized test modules.
- Test Controllers:Hardware-in-the-loop interfaces managing real-time execution of parking dynamics and low-speed maneuver validation.
- Data Analytics Modules:Forensic reconstruction capabilities commanding premium pricing from liability-conscious assemblers and insurance evaluators seeking failure-mode documentation.
- Communication Interfaces:V2X protocol simulation modules enabling verification of vehicle-to-infrastructure coordination in structured parking environments.
Scenario Simulation Platforms command the established base. The steepest expansion runs through Sensor Emulators.
Technology:
Application requirements across perception, planning, and control algorithms determine which sensor modalities demand emulation priority.
- LiDAR:Point-cloud emulation for high-resolution spatial mapping in structured and unstructured parking environments. Premium vehicle programs in Germany and the United States are driving procurement as LiDAR costs decline and functional safety requirements harden.
- Radar:Millimeter-wave signal simulation for cross-traffic detection and obstacle classification at parking velocities. Mass-market adoption is accelerating fastest where cost constraints favor radar-dominant perception stacks.
- Ultrasonic Sensors:Short-range proximity detection emulation for parking assistance and low-speed maneuvering validation.
- Computer Vision:Camera-in-the-loop systems replicating parking line recognition, pedestrian detection, and lighting condition variation.
- V2X Communication:DSRC and C-V2X protocol testing for coordinated parking maneuvers in smart infrastructure environments.
- GNSS:Degraded signal emulation for underground and urban canyon parking scenarios where satellite positioning fails.
LiDAR emulation anchors premium validation workflows. Radar and ultrasonic combinations are gaining share fastest in cost-optimized programs.
Application:
Functional scope divides equipment procurement between active parking assistance and passive safety validation regimes.
- Parking Assistance:Automated steering, braking, and gear selection validation for valet parking execution. OEMs in Germany and Japan are concentrating investment here as UNECE WP.29 and MLIT homologation frameworks mandate documented scenario coverage.
- Safety Validation:Edge-case testing for collision avoidance, pedestrian protection, and system degradation modes. Insurance liability exposure is driving premium pricing for forensic documentation capabilities.
- Traffic Management:Multi-vehicle coordination testing for shared parking infrastructure and fleet deployment scenarios.
- Collision Avoidance:Cross-traffic cyclist and occluded pedestrian detection validation at parking facility ingress and egress points.
- Navigation Calibration:Map-matching and localization accuracy verification for automated parking trajectory planning.
Parking Assistance captures the majority of current equipment deployment. Safety Validation is expanding most quickly as liability frameworks tighten.
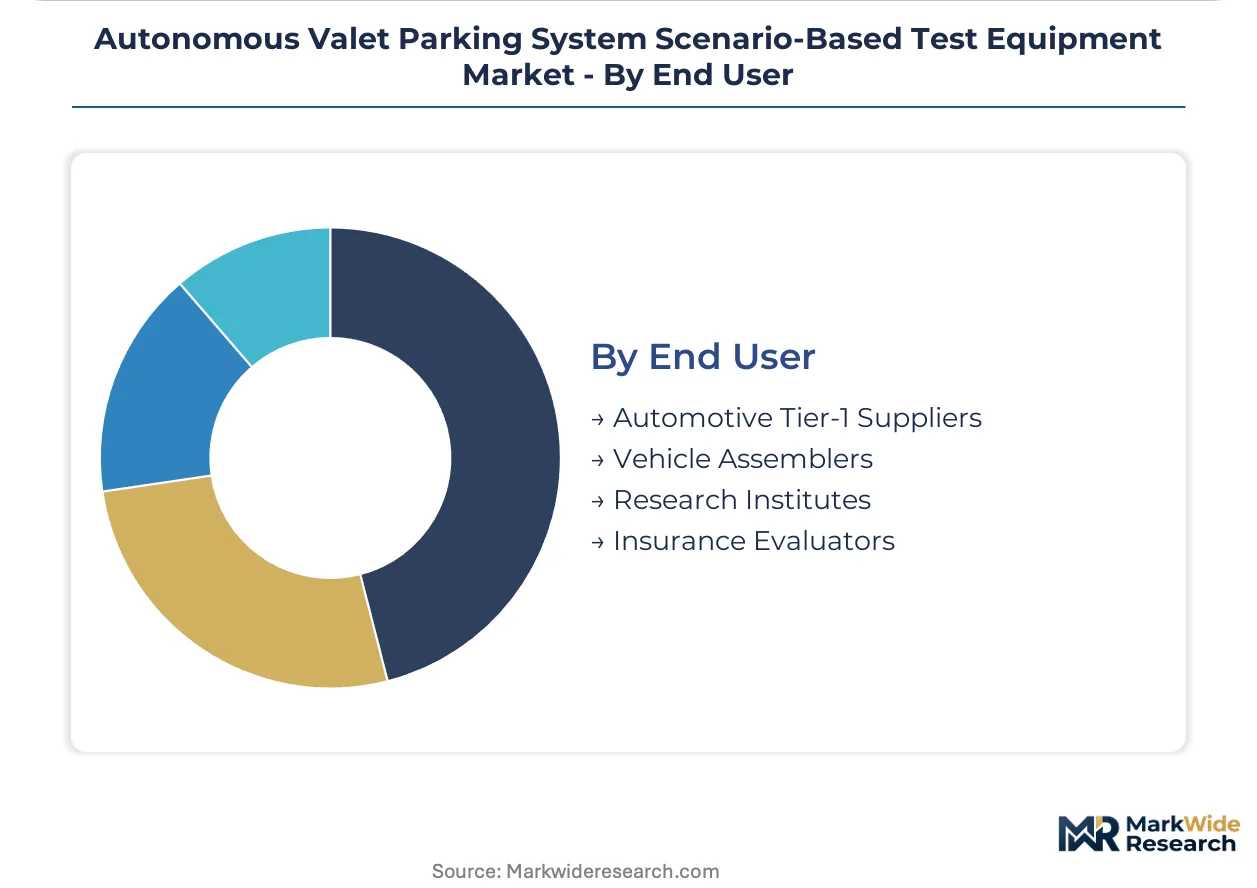
End User:
Customer type determines procurement authority and budget scale, with liability transfer reshaping who controls validation investment.
- Automotive Tier-1 Suppliers:Bosch, Continental, and comparable suppliers assuming direct scenario simulation investments previously borne by vehicle assemblers. Procurement concentrates in Bavaria and Baden-Württemberg engineering centers as liability transfer in automated parking supply agreements accelerates.
- Vehicle Assemblers:OEM-direct procurement channels for validation tooling, with premium German and Japanese manufacturers maintaining in-house simulation capacity for competitive differentiation.
- Research Institutes:Academic and government laboratory procurement for pre-competitive scenario library development and regulatory influence.
- Insurance Evaluators:Forensic reconstruction module purchasers seeking auditable failure-mode documentation for liability assessment.
Tier-1 Suppliers are consolidating procurement authority fastest. Vehicle Assemblers retain the largest installed base of legacy platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German Tier-1 suppliers command pricing premiums that Asian OEMs struggle to match, while United States-based validation programs absorb cost inflation through consolidated procurement budgets. Equipment vendors exploit this asymmetry by tiering platform access across geographic markets. Regional procurement patterns reflect divergent regulatory timelines and liability frameworks.
United States
NHTSA documentation mandates for automated parking systems drive Tier-1 procurement of sensor emulation platforms. The regulator's 2023 updated guidance on crashworthiness testing for low-speed maneuvers tightens scenario coverage requirements. Detroit-area engineering centers concentrate validation investment as domestic OEMs accelerate valet parking program timelines.
Germany
UNECE WP.29 Type Approval frameworks and the EU AI Act's algorithmic transparency rules create dual compliance burdens for parking system validation. KBA homologation procedures mandate auditable scenario libraries that only specialized equipment can generate. Stuttgart and Wolfsburg engineering clusters anchor European procurement authority for hardware-in-the-loop platforms.
Japan
MLIT automated parking certification protocols force domestic suppliers to upgrade legacy test rigs with real-time sensor emulation capabilities. METI-funded autonomous driving research programs subsidize mid-tier supplier access to scenario simulation capacity. Nagoya and Tokyo metropolitan engineering centers concentrate Tier-1 validation investment as liability transfers from assemblers.
China
MIIT autonomous driving homologation requirements for new energy vehicles outpace indigenous scenario simulation capacity. Domestic OEMs preparing for certification lack validated platform suppliers, creating import substitution openings. Shanghai and Shenzhen engineering hubs drive procurement of foreign-origin test equipment despite localization pressures.
South Korea
MFDS-aligned functional safety standards for automotive software extend into parking system validation workflows. Hyundai-Kia supplier networks invest in synchronized multi-sensor test modules to meet export market homologation requirements. Seoul Capital Area engineering centers concentrate procurement as Tier-1 suppliers assume direct validation responsibility.
Autonomous Valet Parking System Scenario-Based Test Equipment Market Competitive Landscape
Hardware-in-the-loop incumbents and software-native challengers split the market along legacy integration versus cloud-native flexibility lines. European vendor concentration around German engineering centers creates procurement bottlenecks for Asian and North American OEMs seeking diversified supply. Three archetypes dominate: established HIL platform vendors with decades of automotive relationships, simulation software specialists expanding into real-time sensor emulation, and automotive Tier-1 suppliers building captive validation capacity. Competitive moves center on strategic partnerships with semiconductor vendors for GPU cluster access and geographic expansion through localized support centers.
Within the established platform tier, dSPACE and Vector Informatik anchor German supply relationships through embedded toolchain integration. Siemens Digital Industries Software occupies a distinct position bridging physics simulation and regulatory documentation workflows. These three represent how European engineering heritage translates into defensive competitive positioning against cloud-native challengers.
| Leading Market Players |
|---|
| dSPACE |
| AVL |
| Vector Informatik |
| IPG Automotive |
| Foretellix |
| Cognata |
| Siemens Digital Industries Software |
| MathWorks |
| ANSYS |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on German FPGA suppliers for real-time LiDAR point-cloud generation determines both the premium-to-economy pricing spread across validation platforms and the geographic clustering of Tier-1 procurement around Stuttgart engineering centers.
Pricing Analysis
Configured-to-order pricing commands a substantial premium over standard catalog configurations in this market. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and customization depth, with ISO 26262-compliant platforms fetching substantial markups. Cost compression in mid-tier sensor emulation modules is intensifying because GPU cluster commoditization erodes hardware differentiation. Tier-1 suppliers in Germany and Japan exhibit lowest price sensitivity due to liability transfer pressures, while Chinese NEV startups face acute budget constraints.
Supply Chain Analysis
Contract manufacturing concentration rests with German EMS providers and Taiwanese semiconductor foundries holding specialized FPGA capacity. Component sourcing draws from Germany, Taiwan, and the United States for real-time processing hardware. Raw material dependencies center on advanced silicon wafers, RF substrates, and precision timing oscillators. Single-source vulnerability in German-engineered HIL interface cards creates procurement risk for Asian OEMs. Distribution runs through direct OEM procurement channels and Tier-1 supplier engineering centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from cloud-native simulation platforms that bypass traditional hardware-in-the-loop architectures entirely.
For Market Incumbents: Insulate embedded toolchain relationships through backward integration into GPU cluster supply chains and certification-grade documentation modules. Deepen ISO 26262 audit trail capabilities to defend against software-native challengers offering pay-per-mile alternatives. Vertical control over FPGA firmware development preserves pricing power in premium configurations.
For New Entrants and Emerging Players: Build out cloud-delivered scenario libraries targeting mid-tier Chinese NEV suppliers previously excluded from perpetual-license models. Penetration concentrates in Shanghai and Shenzhen engineering hubs where MIIT homologation requirements outpace indigenous platform capacity. SaaS-tiered pricing with usage-based metering offers the most viable go-to-market angle against entrenched German vendors.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors simulation software specialists with regulatory documentation capabilities. Long-term viability across the projection horizon rests on algorithmic transparency mandates tightening in Europe and Asia. Acquisition targets should demonstrate embedded automotive relationships and ASIL-rated toolchain integration. Watch for NHTSA scenario library standardization as the inflection signal that reshapes equipment certification priorities.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Convergence of physics simulation with UNECE WP.29 documentation workflows streamlines homologation for German OEMs. |
| Strategic Partnership | GPU cluster alliances with semiconductor vendors reduce scenario iteration latency from weeks to hours. |
| Acquisition of Specialist Firm | Forensic reconstruction module capabilities command premium pricing from liability-conscious insurance evaluators. |
| Geographic Expansion | Localized support centers in Shanghai and Shenzhen capture MIIT certification demand from Chinese NEV programs. |
| Product Launch | Software-defined sensor emulation on GPU clusters displaces rack-mounted hardware arrays in validation labs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, automotive production databases, and Tier-1 supplier procurement disclosures. Primary interviews engaged functional safety engineers, OEM platform validation leads, Tier-1 supplier procurement managers, and semiconductor vendor application specialists. Secondary validation drew from NHTSA guidance documents, UNECE WP.29 technical specifications, MIIT autonomous driving homologation protocols, and IHS Markit vehicle registration data. Bottom-up equipment procurement estimates triangulated against top-down market sizing from automotive R&D expenditure patterns.
Forecast inputs considered sensor modality proliferation rates, regulatory documentation mandate timelines, and liability transfer acceleration across supply agreements. Segmentation modeling spanned product type, technology modality, application scope, and end-user procurement authority. CAGRs were derived from regression analysis against homologation requirement adoption curves and validated against Tier-1 supplier capital expenditure disclosures. Scenario coverage mandates and multi-sensor fusion architecture penetration served as primary demand drivers throughout the projection horizon.
Stress conditions across FPGA supply availability, regulatory scenario library standardization timing, and cloud-native platform substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding NHTSA, UNECE, and MLIT enforcement trajectories. Quarterly review of homologation timeline acceleration and Tier-1 supplier consolidation patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Electric Vehicle Edrive Test Equipment Market
Automotive Testing and Simulation
Automotive Driving Simulators Market
Automotive Testing and Simulation
Driving Simulator Market
Automotive Testing and Simulation
Automotive TIC Market
Automotive Testing and Simulation
Wheel Alignment Equipment Market
Automotive Testing and Simulation
Automotive Simulation Market
Automotive Testing and Simulation
Motor Testing Equipment Market
Automotive Testing and Simulation
Automotive Battery Testing Market
Automotive Testing and Simulation
NDT in Automotive & Transportation Market
Automotive Testing and Simulation
Automotive Prognostics Market
Automotive Testing and Simulation
Automotive Emission Analyzer Market
Automotive Testing and Simulation
Fleet Over-the-Air Software Update Validation Test Platforms Market
Automotive Testing and Simulation
Vehicle Emission Testers Market
Automotive Testing and Simulation
ADAS Calibration and Alignment Equipment Systems Market
Automotive Testing and Simulation
Car Crash Simulator Systems and Services Market
Automotive Testing and Simulation
Automotive Durability Testing Market