
 Asia-Pacific Pea Protein Market | 2026-2036
Asia-Pacific Pea Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Pea Protein Market Outlook
China is narrowing its reliance on imported pea protein as Shandong Jianyuan Foods scales domestic isolate capacity. Roquette Frères anchors premium supply through its European-origin extraction technology adapted for Asian formulation standards. Cargill competes across the textured protein segment, leveraging its oilseed processing infrastructure to secure yellow pea supply chains.
Pea protein comprises globulin and albumin fractions extracted via wet or dry mechanical separation from yellow field peas, yielding protein concentrations from fifty-five to ninety percent depending on processing intensity. Isolates command the dominant margin pool due to superior emulsification in dairy alternative formulations, while textured variants are displacing soy in meat substitute applications across the region's food manufacturing sector. Powder form leads distribution volume, though liquid concentrates are gaining traction in ready-to-drink nutritional supplements through health food store channels.
China's SAMR enforces GB standards for plant protein labeling and contaminant limits, while Australia's FSANZ mandates novel food assessments for new pea protein entrants. India's FSSAI fortification directives are reshaping procurement criteria for nutritional supplement manufacturers. Stakeholders must monitor evolving allergen labeling requirements and carbon intensity disclosures under emerging sustainability frameworks.
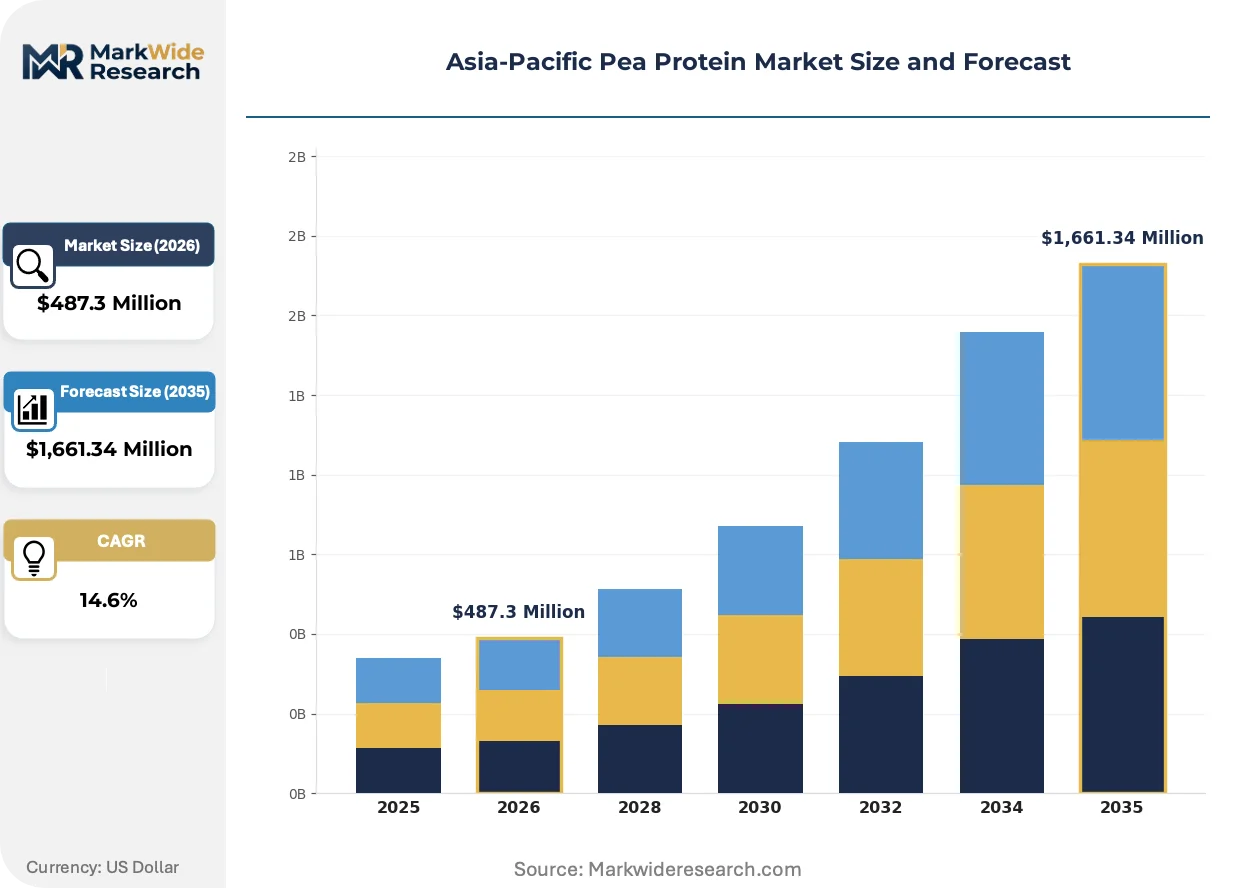
Market Dynamics
Domestic extrusion technology upgrades in eastern China are compressing import dependency for textured pea protein, while isolate procurement still flows through European-origin suppliers with adapted Asian formulation capabilities.
Growth Catalysts
- China's SAMR GB Standards:Mandatory plant protein labeling and contaminant limits are forcing domestic manufacturers to upgrade extraction purity, creating procurement demand for premium-grade isolates in dairy alternative formulations.
- Australia's FSANZ Novel Food Assessments:New entrant evaluation protocols are filtering substandard imports, elevating compliance-barrier advantages for certified suppliers serving meat substitute manufacturers.
- Shandong and Jiangsu Province Clusters:Concentrated food manufacturing infrastructure in these eastern provinces is generating localized demand spikes for both isolate and textured pea protein variants.
Market Restraints
- Yellow Pea Supply Concentration:Regional oilseed processing infrastructure remains dominated by legacy soy handlers, constraining dedicated pea protein supply chain development outside Cargill's integrated networks.
- Albumin Fraction Technical Limitation:Wet mechanical separation struggles to recover albumin proteins at commercial scale, capping functional protein yields below theoretical maximums for high-emulsification applications.
- India's FSSAI Fortification Directive Friction:Nutritional supplement procurement criteria are tightening faster than domestic testing capacity, delaying import clearances for concentrate shipments.
Strategic Opportunities
- India Nutritional Supplement White Space:Fortification mandates are expanding addressable demand for pea protein concentrates in mass-market packaged foods beyond current premium positioning.
- Liquid Concentrate Channel Innovation:Ready-to-drink nutritional supplements through health food store channels are displacing powder-dominant distribution in urban Australian and Chinese metro markets.
- Dual Carbon Goals Technology Convergence:China's MEE carbon intensity disclosure frameworks are converging with extraction energy efficiency upgrades, rewarding low-carbon process adopters with procurement preference.
Industry Challenges
- Extrusion Technician Skill Gap:Textured protein manufacturing requires specialized thermal-mechanical expertise that outpaces vocational training program output in Shandong manufacturing zones.
- FSANZ Novel Food Certification Timelines:Assessment backlogs are extending market entry lead times for new isolate suppliers, freezing competitive repositioning windows.
- Legacy Dairy Alternative Formulation Integration:Established soy and dairy protein processing lines require costly retrofit for pea protein isolate handling, slowing manufacturing pivot decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Pea Protein Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolates, Concentrates, Textured, Flours Application: Dairy Alternatives, Meat Substitutes, Nutritional Supplements, Bakery Products Form: Powder, Liquid, Granule, Flake Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores |
| Companies Covered | Roquette Frères, Shandong Jianyuan Foods, Cargill, Ingredion, Archer Daniels Midland Company, Yantai Shuangta Food, Cosucra, Puris, Axiom Foods, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Pea Protein Market Strategic Shifts
Processing technology convergence and regulatory purity escalation are compressing the viable supplier base while opening formulation white space in functional nutrition and alternative dairy segments.
Dry mechanical separation combined with precision fermentation adjuncts is virtualizing traditional wet extraction infrastructure requirements. Mid-scale manufacturers in Jiangsu province are adopting these hybrid systems to bypass capital-intensive centrifuge installations. The technology is virtualizing the historical scale advantages of European-origin mega-facilities, enabling distributed production closer to eastern China demand clusters.
FSANZ novel food standards are mandating expanded toxicological data packages for new pea protein entrants. Australian meat substitute manufacturers are responding by locking multi-year supply agreements with pre-certified European suppliers rather than onboarding Asian-origin alternatives. The regulatory burden is compressing new supplier entry while consolidating procurement power among incumbent certified players.
Health food store channel expansion is fragmenting traditional ingredient distributor control over ready-to-drink nutritional supplement formulation. Direct brand relationships between pea protein isolate suppliers and finished goods manufacturers are displacing layered procurement structures in Sydney and Shanghai metro markets. This channel compression is most visible in premium positioning segments where traceability claims command formulation influence.
Asia-Pacific Pea Protein Market Segmentation
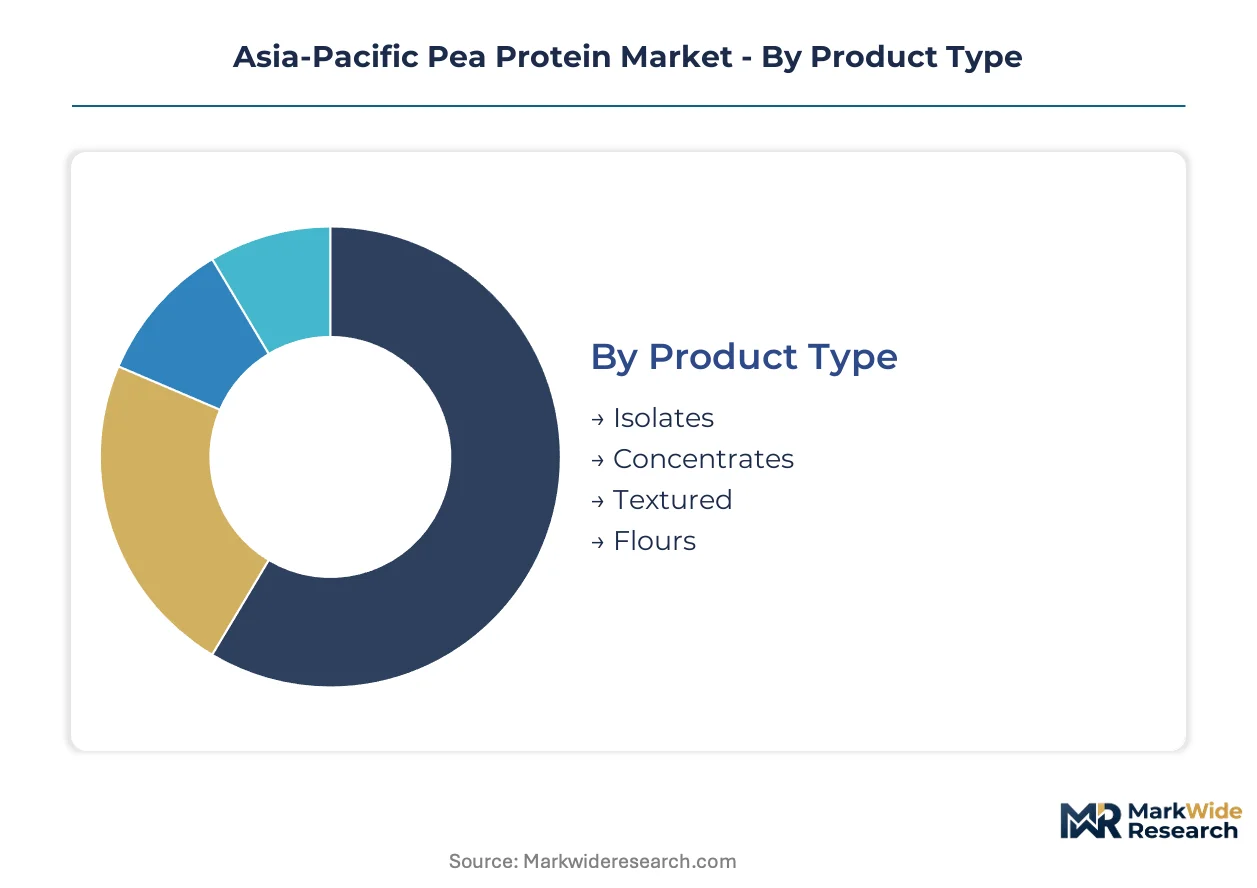
Pea protein procurement patterns diverge sharply across product purity grades, end-use formulation requirements, and channel access structures. Manufacturers in eastern China and Australia prioritize isolate specifications for dairy alternatives, while textured variants capture meat substitute volume. Distribution channel selection determines margin capture, with health food stores commanding premium positioning against supermarket commodity flows.
Product Type:
Mature isolates dominate margin pools while emerging textured formats accelerate manufacturing adoption.
- Isolates:Protein concentrations reaching eighty-five to ninety percent through wet mechanical separation deliver superior emulsification stability. Dairy alternative manufacturers in China's Shandong province specify these grades for oat milk and yogurt analogues under tightening SAMR GB contaminant limits.
- Textured:Extruded fibrous structures from dry mechanical processing replicate meat mouthfeel in plant-based substitutes. Australian meat alternative producers under FSANZ novel food assessments are locking multi-year supply agreements for pre-certified textured variants.
- Concentrates:Fifty-five to eighty percent protein fractions serve cost-sensitive bakery fortification applications across India's FSSAI-directed nutritional programs.
- Flours:Whole-milled pea powders with protein levels below fifty-five percent anchor gluten-free bakery formulations in Southeast Asian export processing zones.
Isolates handle the majority of throughput; textured formats are expanding most quickly on share.
Application:
Cost tiers separate premium positioning in dairy alternatives from volume-driven meat substitute manufacturing.
- Dairy Alternatives:High-emulsification isolates enable creamy texture replication in oat, almond, and coconut milk blends. Jiangsu province beverage manufacturers are retrofitting legacy soy processing lines for pea protein isolate handling.
- Meat Substitutes:Textured and flavored concentrates form the protein backbone of burger patties, sausages, and ground meat analogues. Australian plant-based meat startups are displacing soy with pea-derived formulations under clean-label positioning.
- Nutritional Supplements:Concentrate and isolate powders fortify protein bars and ready-to-mix beverages for India's expanding FSSAI-mandated fortification market.
- Bakery Products:Pea flour and lower-grade concentrates provide structure and protein enrichment in gluten-free bread and cookie applications.
Dairy alternatives command premium formulation spend; meat substitutes are gaining share fastest through manufacturing scale.
Form:
Volume concentration favors powder logistics while liquid concentrates penetrate premium ready-to-drink channels.
- Powder:Shelf-stable, bulk-shipped concentrates and isolates dominate ingredient procurement for food manufacturers. Powdered isolates from Roquette Frères' European-origin extraction technology anchor premium supply through adapted Asian formulation standards.
- Liquid:Pre-solubilized concentrates reduce manufacturing steps for ready-to-drink nutritional supplements. Health food store channels in Sydney and Shanghai metro markets are displacing powder-dominant distribution for liquid concentrate convenience.
- Granule:Intermediate particle sizes suit specific extrusion feed requirements in textured protein manufacturing.
- Flake:Thin-sheet dried formats accelerate rehydration in instant soup and sauce applications.
Powder handles the majority of throughput; liquid concentrates are climbing the fastest on share.
Distribution Channel:
Customer type stratification separates bulk ingredient procurement from branded finished goods access.
- Health Food Stores:Premium positioning with traceability claims and direct supplier relationships dominates ready-to-drink supplement sales. Cargill competes across this channel leveraging oilseed processing infrastructure for yellow pea supply security.
- Supermarkets:Mass-market powder and liquid concentrate placement serves home cooking and casual fitness consumers. India's urban metro retail expansion is opening shelf space for fortified packaged foods under FSSAI directives.
- Online Retail:Direct-to-consumer isolate and concentrate sales bypass traditional ingredient distributor markups for small-scale manufacturers.
- Specialty Stores:Niche positioning for organic-certified and allergen-free pea protein variants serves restricted-diet consumer segments.
Health food stores capture premium margin; online retail is expanding most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's GB standards for plant protein labeling and contaminant limits anchor China's regulatory framework, with eastern province clusters driving procurement demand for premium-grade isolates across the Asia-Pacific region.
China
Shandong and Jiangsu provinces concentrate dairy alternative manufacturing demand for high-emulsification isolates. SAMR enforces mandatory GB standards for protein labeling and contaminant limits, forcing domestic manufacturers to upgrade extraction purity. Shandong Jianyuan Foods scales domestic isolate capacity, narrowing reliance on imported supply.
Australia
Meat substitute manufacturers accelerate procurement of pre-certified textured variants under clean-label positioning. FSANZ mandates novel food assessments for new pea protein entrants, filtering substandard imports and elevating compliance-barrier advantages. Sydney metro health food stores displace powder-dominant distribution with liquid concentrate convenience.
India
FSSAI fortification directives expand addressable demand for pea protein concentrates in mass-market packaged foods. Nutritional supplement procurement criteria tighten faster than domestic testing capacity, delaying import clearances. Urban metro retail expansion opens shelf space for fortified packaged foods.
Japan
PMDA oversight shapes novel food ingredient approval pathways for pea protein entrants. Functional nutrition applications drive isolate demand for senior-targeted protein fortification. Tokyo-Osaka manufacturing corridors integrate pea-derived formulations into traditional food processing lines.
South Korea
MFDS regulates protein supplement labeling and health claim substantiation for ready-to-drink nutritional products. Seoul Capital Area health food channels fragment traditional ingredient distributor control. Daegu-Gyeongbuk food manufacturing zones trial hybrid dry mechanical separation systems.
Asia-Pacific Pea Protein Market Competitive Environment
Capability concentration sits with European-origin extraction technology specialists; scale advantage sits with integrated oilseed processors and domestic Chinese manufacturers. The supplier base stratifies across three tiers: premium-grade isolate specialists with adapted Asian formulation capabilities, mid-scale textured protein fabricators leveraging regional extrusion upgrades, and commodity concentrate handlers serving cost-sensitive fortification markets. Dominant competitive moves include capacity expansion in eastern China manufacturing zones and strategic partnerships locking multi-year supply agreements with pre-certified isolate suppliers.
Within the premium-tier vector, Roquette Frères represents European-origin extraction technology adapted for Asian formulation standards. Shandong Jianyuan Foods exemplifies domestic Chinese capacity expansion narrowing import dependency. Cargill occupies a position bridging integrated oilseed processing infrastructure with textured protein segment competition, securing yellow pea supply chain control across regional networks.
| Leading Market Players |
|---|
| Roquette Frères |
| Shandong Jianyuan Foods |
| Cargill |
| Ingredion |
| Archer Daniels Midland Company |
| Yantai Shuangta Food |
| Cosucra |
| Puris |
| Axiom Foods |
| Others |
Value Chain & Pricing Dynamics
Yellow pea supply concentration in North American and European growing regions determines both pricing tier spreads and supply chain shape, as regional oilseed processing infrastructure remains dominated by legacy soy handlers constraining dedicated pea protein supply development. Tariff exposure on imported isolates widens cost differentials between European-origin premium grades and emerging Chinese domestic production.
Pricing Analysis
Price spreads between European-origin isolates and Chinese domestic equivalents span significant ranges reflecting formulation-grade certification differentials. Three-tier pricing structure across premium, standard, and economy levels separates FSANZ-pre-certified isolates from SAMR-compliant domestic grades and unfortified concentrate commodities. Cost compression in standard-tier textured variants is intensifying because Shandong extrusion technology upgrades displace premium import dependency. Bakery fortification buyers in India exhibit highest price sensitivity; dairy alternative manufacturers in Jiangsu province demonstrate lowest sensitivity due to clean-label positioning premiums.
Supply Chain Analysis
Export-control regimes on precision fermentation adjunct technologies limit hybrid dry-mechanical separation system flows into mid-scale Chinese manufacturers. Supply concentrates in France, Canada, and China, with Roquette Frères and Shandong Jianyuan Foods anchoring isolate output while Cargill's networks control yellow pea origination. Raw material flows draw from North American pulse crops, European starch industry co-products, and Australian novel food-certified stockpiles. Single-source vulnerability sits with European-origin extraction technology licensing for high-emulsification isolate grades. Distribution runs through health food store direct relationships in Sydney and Shanghai metro markets alongside traditional ingredient distributor bulk channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives against precision-fermentation-derived alternative proteins threatening isolate demand in premium dairy alternative formulations.
For Market Incumbents: Entrench FSANZ and SAMR certification moats through accelerated toxicological data package investments that extend assessment backlogs for challengers. Lock multi-year supply agreements with Australian meat substitute manufacturers before novel food assessment timelines compress competitive windows. Prioritize backward integration into yellow pea origination to secure supply security against Cargill's network dominance. For New Entrants and Emerging Players: Pursue India's FSSAI-directed nutritional supplement white space where fortification mandates outpace domestic testing capacity, creating import clearance delays that favor agile entrants with pre-positioned concentrate inventories. Target liquid concentrate ready-to-drink channels in Seoul Capital Area health food stores where traditional distributor control fragments. Lead with direct supplier-brand relationships bypassing layered procurement structures. For Investors and Strategic Acquirers: The market sits at a regulatory-escalation phase that favors pre-certified European-origin specialists with adapted Asian formulation capabilities over scale-undifferentiated commodity handlers. Long-term viability hinges on carbon intensity disclosure convergence under China's MEE frameworks rewarding low-carbon process adopters. Acquisition focus should center on hybrid dry-mechanical separation technology holders in Jiangsu province. The signal to watch is FSANZ novel food assessment backlog resolution rates as inflection indicator for competitive entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FSANZ Pre-Certification Investment | Accelerated toxicological data packages extend compliance-barrier advantages for Australian meat substitute supply agreements. |
| Hybrid Dry-Mechanical Separation Adoption | Jiangsu province manufacturers bypass capital-intensive centrifuge installations through precision fermentation adjunct virtualization. |
| Yellow Pea Origination Backward Integration | Cargill's oilseed processing infrastructure model demonstrates supply security value against legacy soy handler dominance. |
| Liquid Concentrate Channel Direct Relationships | Sydney and Shanghai metro health food stores fragment traditional ingredient distributor control over ready-to-drink formulations. |
| Carbon Intensity Process Upgrades | China's MEE disclosure frameworks reward low-carbon extraction adopters with procurement preference under dual carbon goals. |
Study Parameters
The analysis maps isolate, textured, concentrate, and flour sub-sectors, each validated through extraction technology specialists, dairy alternative formulation directors, meat substitute procurement leads, and nutritional supplement regulatory affairs managers. Primary interviews combined with secondary validation from SAMR GB standard filings, FSANZ novel food assessment registers, FSSAI fortification directive updates, and customs trade flow data. Bottom-up capacity installations and top-down demand segmentation triangulate volume estimates.
Assumptions held regulatory approval timelines and carbon intensity disclosure adoption curves fixed while varying pea protein substitution rates against soy and dairy alternatives across the projection horizon. Segmentation dimensions modeled include product purity grade, application end-use, form factor, and distribution channel access structure. CAGRs derived from installed capacity expansion schedules cross-referenced with procurement contract visibility. Industry-specific inputs encompass extrusion technology upgrade trajectories in Shandong province and FSSAI testing capacity buildout rates.
Macroeconomic conditions sit as an overlay; deviation in pulse crop commodity pricing, ocean freight rate volatility, or bilateral tariff schedules would shift the trajectory. Forecasts reflect documented assumptions on regulatory harmonization pace and domestic technology substitution rates. Material shifts in FSANZ novel food assessment staffing levels or China's MEE enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Wellness Foods Market
Plant Based Food
North America Tofu Market
Plant Based Food
Plant-Based Vegan Eggs Market
Plant Based Food
Fermented Plant Protein Market
Plant Based Food
Italy Plant Protein Market
Plant Based Food
Faba Bean Protein Market
Plant Based Food
Plant-Based Ham Market
Plant Based Food
Vegan Steak Market
Plant Based Food
Vegan Diet Market
Plant Based Food
Vegan Alternatives Market
Plant Based Food
Europe Textured Vegetable Protein Market
Plant Based Food
Fermented Plant Extracts Market
Plant Based Food
New Jersey Vegan Products Market
Plant Based Food
Rice Protein Market
Plant Based Food
Plant-Based Beef Market
Plant Based Food
Yellow Pea Protein Market