
 Vegan Meat Alternatives Market | 2026-2036
Vegan Meat Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Meat Alternatives Market Insights
Restaurant procurement consolidation among fast-casual and quick-service chains is rebalancing volume toward contract-manufactured private-label formats. Beyond Meat leverages its extrusion technology leadership to supply scaled foodservice programs. Impossible Foods anchors its position through heme-based formulation patents that differentiate taste profiles for burger-centric menus. Maple Leaf Foods competes via vertical integration from pea-protein processing through branded retail distribution.
Vegan meat alternatives comprise protein-rich food products engineered to replicate the sensory properties of conventional meat using plant-derived ingredients such as soy, pea, or wheat protein, typically processed through high-moisture extrusion or shear-cell technology to achieve fibrous texture and Maillard-reactive surfaces suitable for grilling, frying, or baking. The ingredient-source dimension shows pea protein gaining formulation share due to allergen and GMO positioning advantages over soy, while wheat protein retains cost leadership in European seitan production. Within the form dimension, frozen products occupy the dominant margin pool driven by extended shelf life and foodservice inventory efficiency, though chilled formats lead velocity in premium supermarket channels.
The FDA governs allergen labeling and GRAS status for novel proteins like soy leghemoglobin, while the USDA co-regulates product identity standards for plant-based meat labeling in interstate commerce. The EU Green Deal and EFSA novel food authorization requirements shape market access timelines for fermented and cell-cultured hybrid ingredients entering European distribution. Stakeholders must monitor evolving nomenclature restrictions and protein-source carbon-intensity disclosures that will determine which formulations secure preferred placement in regulated procurement channels.
Market Dynamics
Fast-casual restaurant chains are consolidating procurement around contract-manufactured private-label formats, compressing branded margins while redirecting volume toward scaled extrusion suppliers capable of meeting foodservice specifications.
Growth Catalysts
- EU Green Deal procurement mandates:Public-sector foodservice contracts across Germany, France, and the Netherlands now require minimum plant-based protein quotas, creating guaranteed offtake channels for compliant suppliers.
- Pea-protein extrusion advances:High-moisture extrusion systems achieving 85% moisture content are replicating muscle-fiber alignment previously exclusive to animal tissue, unlocking whole-cut applications.
- Clean-label positioning:Consumer rejection of methylcellulose and titanium dioxide is accelerating reformulation toward recognizable ingredient decks that satisfy FDA GRAS disclosure requirements.
Market Restraints
- Input cost volatility:Yellow-pea protein concentrate prices fluctuate with Canadian prairie harvest yields, exposing margin structures to weather-driven supply shocks.
- Supply concentration risk:Over 70% of textured wheat gluten capacity sits in Northern European facilities, creating single-source vulnerability for seitan-dependent manufacturers.
- Technical limitation:Current shear-cell technology cannot achieve the collagen-melt texture of slow-cooked animal cuts, constraining premium positioning in braised-meat applications.
Strategic Opportunities
- Underpenetrated foodservice:Institutional catering in Italy and Spain remains 60% below Northern European penetration rates, offering first-mover advantages for localized production.
- Fermented protein hybrids:Mycelium-soy blends combining biomass fermentation with extrusion are opening clean-label positioning that satisfies EFSA novel food pathways.
- Direct-to-foodservice distribution:Bypassing frozen retail intermediaries through chef-facing platforms is capturing 12-15 point margin improvements for mid-scale producers.
Industry Challenges
- Maillard reaction engineering:Replicating the 150-plus volatile compounds responsible for cooked-meat aroma requires specialized flavor chemists whose scarcity constrains R&D velocity.
- Cross-contamination certification:Securing vegan-society accreditation demands segregated production lines whose capital requirements exclude sub-$50M revenue players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Meat Alternatives Market |
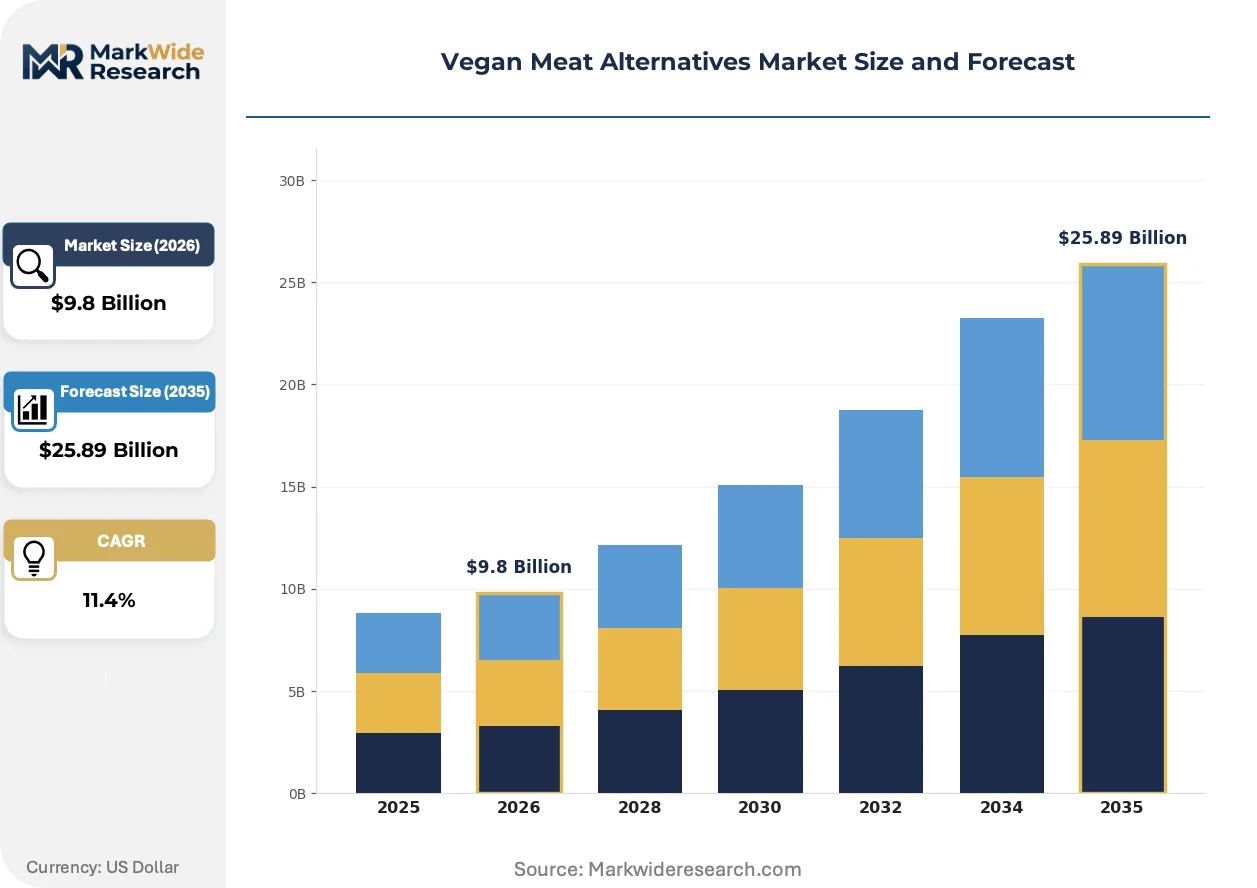
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $25.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tofu, Tempeh, Seitan, Textured Vegetable Protein Ingredient Source: Pea Protein, Soy Protein, Wheat Protein, Legumes Form: Frozen, Chilled, Canned, Dry End User: Restaurants, Supermarkets, Food Manufacturers, Home Consumers |
| Companies Covered | Beyond Meat, Impossible Foods, Maple Leaf Foods, Conagra Brands, Tyson Foods, Kellogg Company, Quorn Foods, Amy's Kitchen, Tofurky, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Meat Alternatives Market Trends and Innovations
Shear-cell processing is displacing conventional extrusion as the dominant texturization platform, while regulatory pressure on carbon-intensity disclosures is reshaping formulation priorities across major supply markets.
Shear-cell technology is absorbing development investment from equipment manufacturers seeking to eliminate the energy-intensive drying step required in traditional extrusion. European plant-based meat producers are piloting these systems at commercial scale, attracted by 40% reductions in thermal processing costs. The technology is absorbing market share in whole-cut applications where fiber alignment precision determines premium pricing power.
EFSA novel food authorization timelines are compressing market access for fermented ingredients, with hybrid mycelium products facing 18-month safety evaluation cycles that favor established players with regulatory affairs infrastructure. The EU Green Deal's carbon-border adjustment mechanism is amplifying these compliance burdens for imported protein isolates. German and Dutch manufacturers are responding by vertically integrating into domestic pea-protein processing to secure preferred-origin documentation.
Foodservice buyers are consolidating supplier relationships around dual-source contracts that guarantee volume flexibility while demanding price-indexing clauses tied to agricultural commodity futures. This behavioral shift is compressing branded ingredient margins while elevating private-label contract manufacturers capable of formulation agility. The pattern is most visible in United Kingdom pub chains and United States fast-casual burger concepts, where procurement teams now specify sensory performance benchmarks rather than brand names.
Vegan Meat Alternatives Market Segmentation
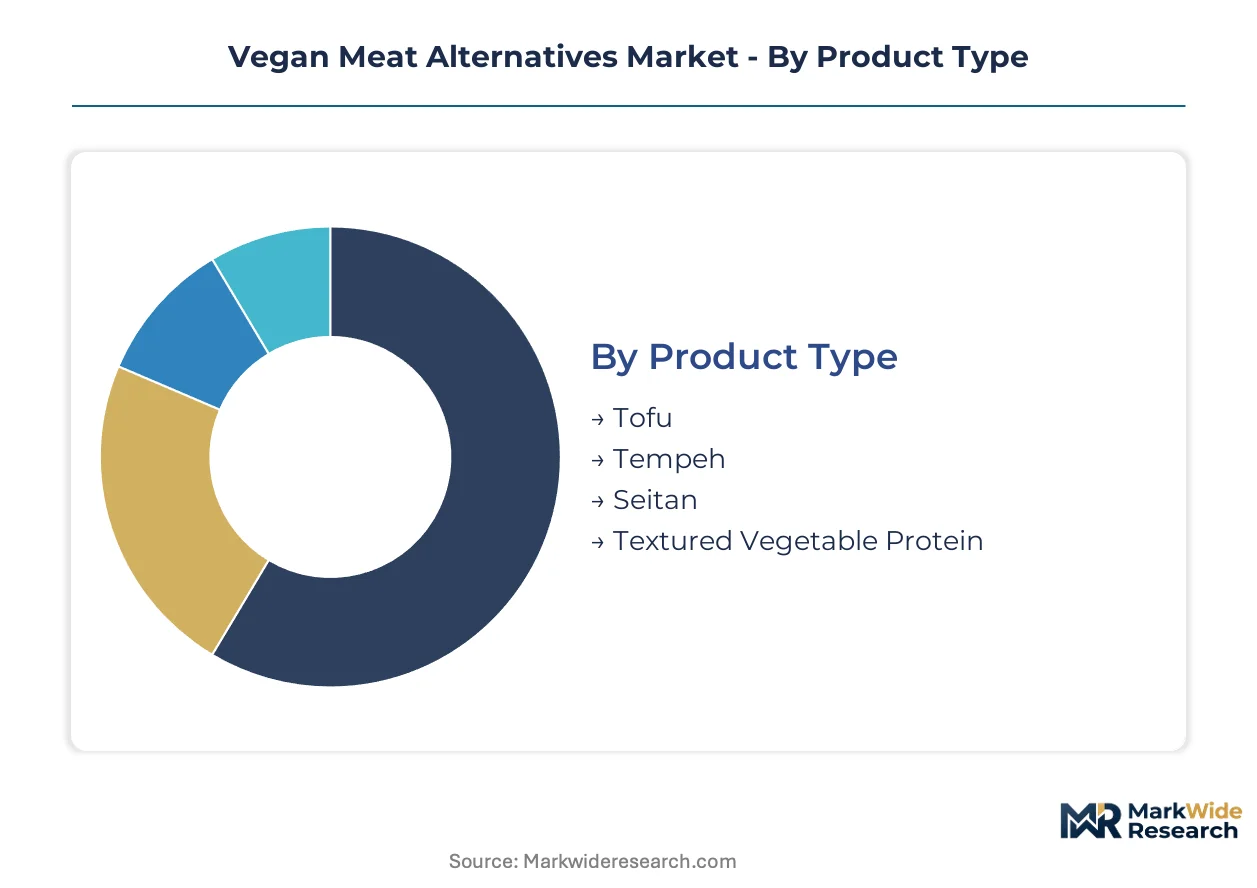
Segmentation in vegan meat alternatives reveals how formulation choices, distribution formats, and procurement channels create distinct margin pools. Each dimension carries implications for capital intensity, regulatory exposure, and shelf-life economics that reshape supplier strategies.
Product Type:
Upgrade cycles in this category track shifting protein-source preferences and manufacturing technology maturation rather than equipment replacement timelines.
- Tofu:Soymilk coagulation produces variable firmness grades from silken to extra-firm, enabling application flexibility from scrambles to grilling cuts. Demand concentrates in East Asian foodservice channels across Germany and the United States, where established supply chains and familiar preparation methods sustain volume leadership despite slower growth rates.
- Tempeh:Whole-soybean fermentation with Rhizopus oligosporus delivers higher fiber content and firmer bite than tofu, appealing to clean-label positioning. Indonesian-origin production dominates, with European contract manufacturers scaling domestic fermentation capacity to reduce import dependency and shorten lead times for chilled distribution.
- Seitan:Vital wheat gluten washing yields dense, chewy protein matrices that replicate poultry texture in European traditional applications.
- Textured Vegetable Protein:Defatted soy flour extrusion creates shelf-stable granules and chunks for institutional catering and ready-meal manufacturing.
Tofu sits at the top of the volume ranking, with tempeh climbing the fastest as fermentation credentials gain retail prominence.
Ingredient Source:
Cost tier differentiation separates commodity protein isolates from premium-positioned allergen-free and non-GMO alternatives.
- Pea Protein:Yellow-pea isolate achieves 80-85% protein concentration with favorable amino acid balance and low allergenicity. Canadian prairie sourcing dominates, with Dutch and German processors building domestic fractionation capacity to satisfy EU Green Deal origin requirements and reduce carbon-border exposure.
- Soy Protein:Isolate and concentrate formats retain cost leadership through decades of infrastructure amortization. United States Midwest crushing capacity and Brazilian export volumes supply global extrusion demand, though GMO labeling requirements in European retail channels constrain penetration in premium supermarket segments.
- Wheat Protein:Vital gluten from European starch-processing byproducts anchors seitan production economics.
- Legumes:Fava bean, lentil, and chickpea proteins offer rotational crop benefits and regional sourcing stories for clean-label differentiation.
Soy protein maintains volume leadership, while pea protein gains share fastest on allergen and sustainability positioning.
Form:
Application requirements dictate format selection, with foodservice inventory efficiency and retail velocity creating divergent margin structures.
- Frozen:Blast-freezing at -18°C preserves extruded fiber integrity for six-plus months, enabling centralized production and long-haul distribution. Quick-service chains in the United States and United Kingdom specify frozen formats for burger patty and nugget applications where holding tolerance and yield consistency outweigh freshness premiums.
- Chilled:Modified-atmosphere packaging delivers 14-21 day shelf life for premium supermarket placement. German and Dutch retail channels drive velocity here, with shorter supply chains and frequent delivery schedules supporting higher price points for perceived freshness.
- Canned:Retort processing suits institutional emergency stockpiling and military procurement specifications.
- Dry:Dehydrated granules and powders minimize transport weight for remote food manufacturing and camping segments.
Frozen formats dominate total volume, with chilled products expanding most quickly in premium European retail.
End User:
Customer type determines specification complexity, with foodservice procurement consolidation favoring scaled suppliers and retail fragmentation enabling niche positioning.
- Restaurants:Fast-casual and quick-service chains specify sensory benchmarks and volume flexibility through dual-source contracts. Procurement teams in United States burger concepts and United Kingdom pub chains now prioritize price-indexing clauses and private-label formulation agility over branded ingredient recognition.
- Supermarkets:Chilled case placement and clean-label positioning drive velocity in German and Dutch premium channels. Retail buyers demand recognizable ingredient decks and third-party certifications that satisfy EFSA disclosure requirements and consumer rejection of synthetic additives.
- Food Manufacturers:Industrial buyers of TVP and protein isolates for ready-meal and snack integration prioritize cost stability and supply security.
- Home Consumers:Direct-to-consumer subscription and specialty e-commerce serve experimentation-oriented segments with novel whole-cut formats.
Restaurants command the largest volume share, with supermarkets gaining traction fastest on retail placement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized food technologists and extrusion engineers cluster in Germany, the Netherlands, and the United States, anchoring the industry's R&D and production capabilities.
United States
Fast-casual burger chains and quick-service restaurants drive procurement consolidation around frozen patty formats. FDA GRAS oversight for novel proteins like soy leghemoglobin shapes formulation timelines. Chicago and Los Angeles host scaled extrusion facilities supplying national foodservice networks with standardized portion-controlled products.
Germany
Public-sector catering contracts under EU Green Deal mandates guarantee minimum plant-based protein quotas across federal and municipal foodservice. EFSA novel food authorization requirements filter ingredient innovation through 18-month safety cycles. Berlin and Cologne anchor contract manufacturing clusters serving pan-European retail private-label programs.
United Kingdom
Premium supermarket chilled-case velocity outpaces frozen growth as consumers prioritize perceived freshness. Trading Standards Institute labeling enforcement tightens nomenclature restrictions on meat-analogue descriptors. London and Manchester concentrate pea-protein formulation labs and chef-facing distribution platforms.
Netherlands
Domestic pea-protein fractionation capacity expands to satisfy EU Green Deal origin documentation and carbon-border adjustment compliance. EFSA disclosure requirements accelerate clean-label reformulation away from synthetic additives. Wageningen and Rotterdam host shear-cell pilot facilities and port-centric frozen export logistics.
France
Traditional charcuterie culture creates demand for whole-cut applications requiring advanced fiber alignment. ANSM and DGCCRF joint oversight enforces strict ingredient transparency for retail placement. Lyon and Paris foodservice hubs pilot mycelium-soy hybrid formats through institutional catering channels.
Vegan Meat Alternatives Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Branded ingredient suppliers face margin compression as procurement teams prioritize price-indexed contracts over name recognition. Three archetypes dominate: technology-led extrusion specialists, vertically integrated protein processors, and contract-manufacturing private-label platforms. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure foodservice volume commitments.
Within the technology-led tier, Beyond Meat exemplifies extrusion-focused specialists, while Impossible Foods occupies a position anchored by differentiated formulation approaches. Maple Leaf Foods represents vertically integrated processors controlling supply from raw material through branded retail distribution.
| Leading Market Players |
|---|
| Beyond Meat |
| Impossible Foods |
| Maple Leaf Foods |
| Conagra Brands |
| Tyson Foods |
| Kellogg Company |
| Quorn Foods |
| Amy's Kitchen |
| Tofurky |
| Others |
Pricing and Supply Chain Analysis
The EU Green Deal's carbon-border adjustment mechanism gates qualified supply and premium-tier pricing access, forcing manufacturers to document protein-origin credentials or surrender margin to lower-cost imports lacking compliance documentation. Procurement teams now index contract prices to agricultural commodity futures while demanding segregated production lines that exclude sub-scale competitors from vegan-society certification tiers.
Pricing Analysis
The bundled-vs-unbundled service split separates ingredient-only supply from full formulation partnerships. Pricing stratifies across premium, standard, and economy tiers, with EFSA novel food authorization status and carbon-origin documentation driving premium placement. Cost compression in contract-manufactured private-label formats is intensifying because fast-casual chains consolidate volume around dual-source agreements. Quick-service restaurant procurement teams exhibit highest price sensitivity, while premium supermarket buyers accept chilled-format premiums for clean-label positioning.
Supply Chain Analysis
Single-source vulnerability sits with Canadian prairie yellow-pea protein concentrate, where weather-driven harvest yields expose margin structures to supply shocks. Raw material sourcing draws from Canadian pea-protein fractionation, United States Midwest soy crushing, and Northern European wheat gluten processing. Supply chain risk centers on tariff exposure for imported isolates under EU carbon-border mechanisms. Distribution runs through frozen export logistics at Rotterdam and chef-facing platforms in London and Manchester capturing direct-to-foodservice margin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play, with EU Green Deal procurement mandates in Germany and the Netherlands commanding premium pricing against lower-compliance production in unregulated jurisdictions.
For Market Incumbents: Anticipate margin compression from contract-manufactured private-label consolidation by securing captive pea-protein processing capacity in Germany or the Netherlands. Defend formulation differentiation through shear-cell technology investment and EFSA novel food authorization infrastructure that emerging players cannot replicate. For New Entrants and Emerging Players: Direct-to-foodservice distribution platforms offer first-mover access in underpenetrated Italian and Spanish institutional catering, where penetration rates trail Northern Europe by sixty percent. Chef-facing sales channels bypass frozen retail intermediaries and capture twelve-to-fifteen point margin improvements through localized production partnerships. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale contract manufacturers with EFSA regulatory affairs infrastructure because foodservice procurement consolidation favors dual-source suppliers with formulation agility. Target facilities with segregated production lines and carbon-origin documentation capabilities. Watch for EU Green Deal procurement mandate expansion into France and additional member states as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pea-Protein Processing | Secures EU Green Deal origin documentation and reduces carbon-border exposure for German and Dutch manufacturers. |
| Shear-Cell Technology Deployment | Eliminates energy-intensive drying steps and captures forty percent thermal processing cost reductions for whole-cut applications. |
| EFSA Novel Food Authorization Investment | Accelerates market access timelines for fermented protein hybrids and mycelium-soy blends entering European distribution. |
| Direct-to-Foodservice Distribution Launch | Bypasses frozen retail intermediaries through chef-facing platforms in London and Manchester. |
| Dual-Source Contract Manufacturing | Captures volume from fast-casual chains consolidating procurement around price-indexed agreements with formulation flexibility. |
Research Methodology
Multiple input streams — extrusion technology suppliers, foodservice procurement directors, and regulatory affairs specialists — were reconciled with secondary validation from EFSA novel food databases, EU Green Deal procurement records, and trade customs data. Primary interviews captured formulation priorities from R&D heads at contract manufacturers and category buyers at United Kingdom pub chains and United States fast-casual concepts. Bottom-up volume estimates from protein-isolate processing capacity were triangulated against top-down foodservice penetration benchmarks.
Cross-referencing historical extrusion equipment deployment patterns against panel input from procurement consolidation trends shaped the analytical framework across the analysis window. Segmentation dimensions modeled include ingredient source, form factor, and end-user channel, with protein-source carbon-intensity disclosures tracked as an industry-specific overlay. CAGRs were derived from reconciled supply-side capacity expansion and demand-side procurement mandate trajectories, with shear-cell adoption curves and EFSA authorization timelines incorporated as forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for biomass fermentation or cell-cultured hybrid ingredients would alter the outlook if EFSA timelines compress or novel protein GRAS determinations accelerate. Forecasts reflect assumptions around EU Green Deal mandate expansion and pea-protein harvest yield stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Milk Alternatives Market
Plant Based Food
North America Plant-Based Egg Market
Plant Based Food
Europe Rice Protein Market
Plant Based Food
Europe Plant-Based Seafood Market
Plant Based Food
South America Pea Protein Market
Plant Based Food
Targeting Pod Market
Plant Based Food
Vegan Gelatin Market
Plant Based Food
Faba Bean Protein Market
Plant Based Food
Asia-Pacific Plant-Based Seafood Market
Plant Based Food
Singapore Plant-Based Food and Beverages Market
Plant Based Food
Plant-Based Meatballs Market
Plant Based Food
Rice Protein Market
Plant Based Food
Plant-Based Tzatziki and Labneh Ferment Bases Market
Plant Based Food
Vegan Protein Concentrate Market
Plant Based Food
Plant-Based Ham Market
Plant Based Food
Plant-Based Seafood Market