
 Soy- Based Food Market | 2026-2036
Soy- Based Food Market Size, Share, and Industry Trends Forecast 2026-2036
Soy- Based Food Market Analytics
Market Context
Plant protein processing expertise is collapsing across North American and European labor markets, constraining capacity expansion for extruded soy protein facilities. Danone S.A. leverages its fermented soy dairy alternatives portfolio to sustain European retail shelf presence amid tightening formulation standards. Vitasoy International Holdings anchors Asia-Pacific liquid soy milk distribution through decades of cold-chain infrastructure investment. Nestlé S.A. competes by extending its Garden Gourmet meat alternative line with textured soy protein formulations targeting flexitarian households.
Technical Definition and Segment Structure
Soy-based food encompasses edible products derived from Glycine max through aqueous extraction, enzymatic hydrolysis, or mechanical pressing, with protein content ranging from 3.5% in fluid soy milk to 90% in isolated protein concentrates, serving as functional nutrition sources or meat analog substrates. The food and beverage application segment dominates value generation through institutional procurement of soy milk for coffee chains and bakery formulations, while meat alternatives represent the fastest-expanding margin pool as extrusion technology improves fibrous texture replication. Online stores are displacing traditional health food stores as the primary growth channel, driven by direct-to-consumer subscription models for specialty tofu and edamame products.
Regulatory Framework
The FDA governs soy protein health claims and GRAS status determinations in the United States, while EFSA evaluates novel soy processing methods under EU novel food regulations, and China's SAMR enforces GB standards for non-GMO labeling and protein content declarations. These frameworks collectively determine market access thresholds, with non-GMO certification requirements in China and Europe diverging from U.S. tolerance for bioengineered soy feedstocks. Stakeholders must monitor evolving protein content threshold definitions and alternative dairy terminology restrictions as jurisdictions refine plant-based product categorization.
Market Dynamics
The soy-based food sector is experiencing a structural squeeze between tightening European protein sourcing standards under the EU Green Deal and the collapse of North American extrusion technician labor pools, forcing capacity decisions to outpace workforce development.
Growth Catalysts
- EU F-Gas Regulation:The regulation is accelerating facility retrofits toward low-carbon protein processing equipment, pulling investment into modernized soy extrusion infrastructure across German and Dutch manufacturing zones.
- Sports nutrition end-use:Soy protein isolate demand from athletic supplement formulators is expanding production runs for 90% concentrate grades, particularly in Chinese coastal provinces with established non-GMO certification chains.
- High-moisture extrusion:This processing technology is improving fibrous texture replication in meat alternatives, enabling foodservice channels to broaden flexitarian menu placements without sensory compromise.
Market Restraints
- Non-GMO soybean premium volatility:Input cost swings for identity-preserved soybeans constrain margin predictability for European and Chinese manufacturers dependent on certified feedstock segregation.
- Midwestern US crushing concentration:Soy protein isolate supply relies heavily on Illinois and Iowa processing clusters, creating geographic vulnerability to regional weather and logistics disruptions.
- Enzymatic hydrolysis yield ceilings:Technical limitations in breaking soy protein into functional peptides without bitterness generation restrict application expansion into pediatric and geriatric nutrition.
Strategic Opportunities
- Indonesian market penetration:Traditional tempeh consumption patterns create receptive infrastructure for expanded soy protein isolate introduction into packaged food manufacturing in Java and Sumatra.
- Direct-to-consumer subscription channels:Online stores are capturing specialty tofu and edamame demand previously served by health food retail, enabling margin capture through recurring revenue models.
- China dual carbon policy alignment:National carbon neutrality mandates are incentivizing low-energy aqueous extraction investments, positioning domestic processors for preferential procurement from state-backed foodservice distributors.
Industry Challenges
- Extrusion technician scarcity:The specialized skill set for high-shear protein texturization is disappearing from vocational pipelines in both North American and European labor markets, extending commissioning timelines for new facilities.
- GRAS determination delays:FDA review timelines for novel soy processing methods are stretching commercialization schedules for enzymatically modified protein ingredients targeting US food and beverage applications.
- Cold-chain integration complexity:Liquid soy milk distribution requires temperature-controlled infrastructure that conflicts with ambient logistics networks, forcing capital allocation decisions between dedicated fleets and third-party cold storage partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy- Based Food Market |
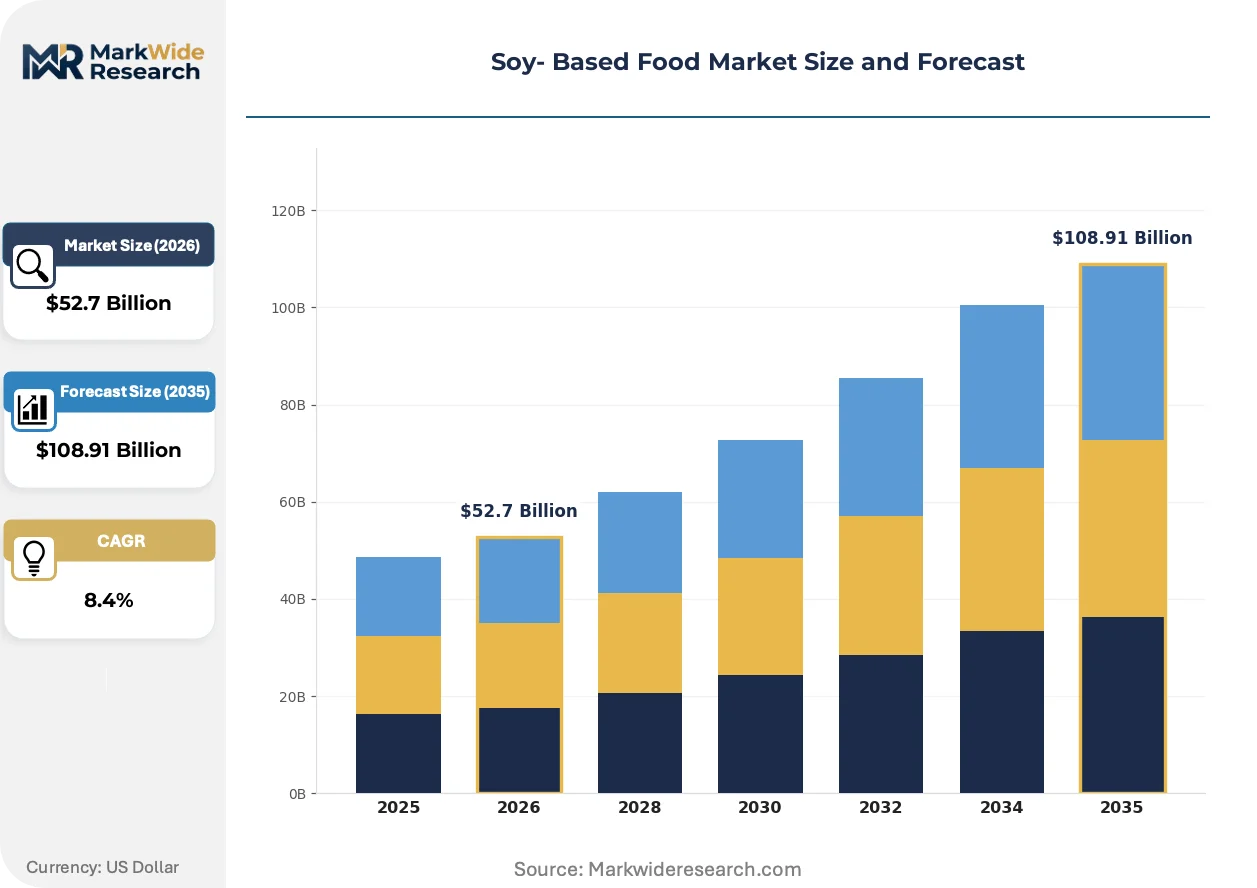
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $108.91 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Milk, Tofu, Soy Protein Isolate, Edamame End User: Health-Conscious Consumers, Vegans, Vegetarians, Fitness Enthusiasts Application: Food & Beverage, Meat Alternatives, Snacks, Dietary Supplements Distribution Channel: Online Stores, Supermarkets, Health Food Stores, Specialty Retailers |
| Companies Covered | Danone S.A., Vitasoy International Holdings, Nestlé S.A., Unilever PLC, Conagra Brands Inc., Archer Daniels Midland, Cargill, Hain Celestial, House Foods America Holding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy- Based Food Market Evolving Landscape
Processing technology and regulatory categorization are actively restructuring competitive boundaries in soy-based foods, with texture replication capabilities and terminology standards becoming decisive differentiation vectors.
High-moisture extrusion systems are bifurcating the meat alternative segment between premium fibrous whole-muscle analogs and commodity ground-format products. Foodservice operators with skilled culinary teams are adopting the former for center-plate applications, while QSR chains prioritize the latter for cost-controlled menu engineering. This technological split is compressing mid-tier positioning and forcing suppliers to commit to one equipment configuration or the other.
EFSA novel food evaluations under tightened EU protein processing standards are extending approval timelines for enzymatically hydrolyzed soy ingredients. The industrial consequence is a shift toward grandfathered aqueous extraction methods for European market entry, even where enzymatic routes offer superior functionality. Sports nutrition and clinical nutrition segments are most affected, with formulators reverting to established isolate grades rather than awaiting novel determinations.
Subscription-based procurement of specialty tofu and fermented soy dairy alternatives is displacing conventional retail replenishment among urban flexitarian households. Direct-to-consumer platforms are capturing this demand rotation, particularly in Chinese tier-one cities and North American coastal metros where cold-chain density supports fresh delivery. The channel shift is visible in Shanghai, San Francisco, and Berlin, where weekly delivery models now outpace health food store foot traffic for premium soy product categories.
Soy- Based Food Market Segmentation
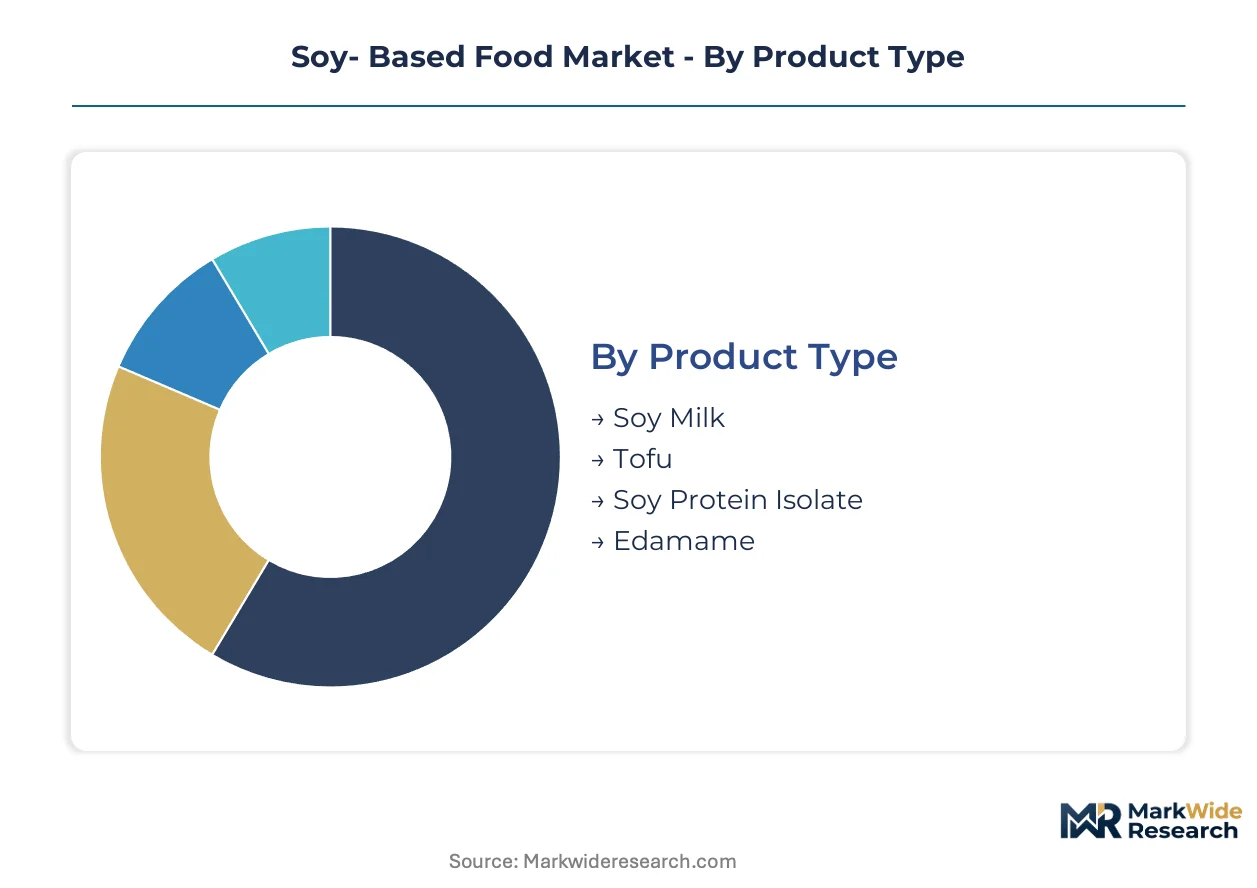
Soy-based food segmentation reveals divergent channel economics. Liquid formats demand cold-chain density, while dry isolates flow through ambient logistics. Each product category carries distinct margin profiles and regulatory exposure.
Product Type:
Channel mix varies sharply by moisture content. Fluid products anchor foodservice procurement through institutional dairy-alternative contracts, while dry concentrates supply manufacturing ingredient pipelines.
- Soy Milk:Aqueous extraction yields 3.5-4% protein beverages requiring refrigerated distribution. Coffee chains in Shanghai and Berlin drive institutional procurement through direct supplier agreements with cold-chain operators.
- Soy Protein Isolate:Spray-dried 90% protein concentrates serve sports nutrition formulators and meat analog manufacturers. Chinese coastal processors with non-GMO certification chains capture premium pricing from European supplement brands.
- Tofu:Coagulated curd products span fresh refrigerated blocks to aseptic shelf-stable formats. Specialty retailers in North American coastal metros curate artisanal varieties alongside commodity supermarket lines.
- Edamame:Immature whole soybean pods move predominantly through frozen food channels. Asian supermarket networks in Los Angeles and Vancouver sustain volume throughput for flash-frozen grades.
By volume, soy milk leads. By growth pace, soy protein isolate is expanding most quickly.
End User:
Cost tier stratification separates premium-positioned specialty buyers from mass-market flexitarian adoption. Certification requirements and formulation standards scale with price sensitivity.
- Health-Conscious Consumers:Functional nutrition seekers prioritize organic and non-GMO labeling. This segment absorbs price premiums for identity-preserved supply chains through subscription replenishment models.
- Vegans:Ethical dietary adherence drives complete dairy and meat substitution requirements. Plant-based cheese and yogurt alternatives concentrate demand among this cohort through dedicated retail shelving.
- Vegetarians:Partial animal protein exclusion creates selective soy adoption for specific meal occasions. Flexitarian positioning in European markets captures this group's intermittent purchasing patterns.
- Fitness Enthusiasts:Macronutrient tracking behavior sustains isolate and concentrate demand for post-workout applications. Chinese sports nutrition e-commerce platforms serve this segment through direct brand relationships.
Health-conscious consumers generate the highest per-capita spend. Fitness enthusiasts are gaining share fastest through digital channel migration.
Application:
Volume concentration in mature categories contrasts with margin expansion in emerging formats. Manufacturing complexity and regulatory scrutiny escalate across the spectrum.
- Food & Beverage:Institutional soy milk procurement for coffee chains and bakery formulations constitutes the largest revenue pool. German and Dutch manufacturing zones supply European foodservice distributors under EU Green Deal compliance requirements.
- Meat Alternatives:Extruded textured protein for flexitarian households climbs the steepest expansion trajectory. High-moisture extrusion technology enables whole-muscle analog placement in restaurant center-plate applications.
- Snacks:Roasted edamame and flavored tofu products occupy impulse purchase occasions. Asian supermarket networks sustain this segment through ethnic retail clustering.
- Dietary Supplements:Isolated protein powders target athletic and clinical nutrition endpoints. FDA GRAS determinations and EFSA novel food evaluations govern market access timelines.
Food and beverage dominates absolute volume. Meat alternatives show the steepest margin expansion.
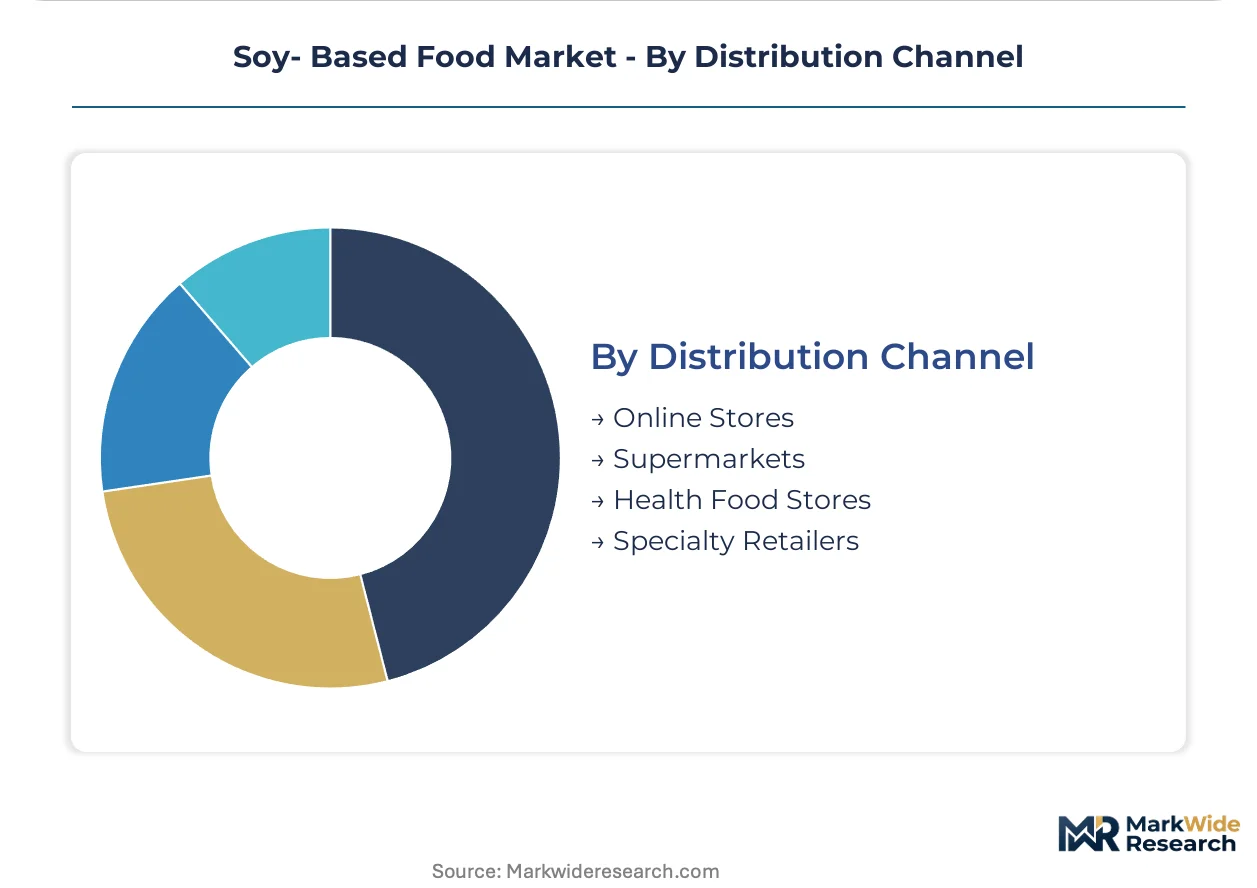
Distribution Channel:
Supply concentration in legacy retail conflicts with direct-to-consumer growth vectors. Cold-chain requirements filter channel viability by product format.
- Online Stores:Subscription models for specialty tofu and edamame displace health food retail in urban flexitarian households. Direct-to-consumer platforms in San Francisco and Shanghai capture recurring revenue through temperature-controlled last-mile partnerships.
- Supermarkets:Mass-market soy milk and refrigerated tofu blocks flow through ambient and refrigerated grocery networks. Shelf space allocation reflects retailer private label strategies and national brand trade spending.
- Health Food Stores:Curated organic and artisanal soy products serve loyalty-driven repeat purchasers. Foot traffic erosion in North American coastal metros pressures this channel's historical positioning.
- Specialty Retailers:Asian supermarket networks and natural food cooperatives maintain ethnic and premium product depth. Los Angeles and Vancouver clusters sustain volume for flash-frozen edamame and fresh tofu varieties.
Supermarkets retain volume leadership. Online stores are climbing fastest through subscription conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Chinese coastal processors with non-GMO certification chains, while European manufacturers absorb compliance premiums under the EU Green Deal. German and Dutch manufacturing zones face margin compression from facility retrofit mandates. Indonesian and Brazilian feedstock suppliers capture volume but surrender value capture to downstream processors.
China
Sports nutrition formulators in Shanghai and Shenzhen drive soy protein isolate demand for 90% concentrate grades. SAMR enforces GB standards for non-GMO labeling and protein content declarations. Jiangsu and Zhejiang coastal processors with established certification chains capture premium pricing from European supplement brands.
Germany
Foodservice distributors procure institutional soy milk under EU Green Deal compliance requirements. The EU F-Gas Regulation accelerates facility retrofits toward low-carbon protein processing equipment. North Rhine-Westphalia manufacturing zones supply extruded textured protein to flexitarian menu placements across Berlin and Hamburg.
United States
Coffee chains drive institutional procurement of fluid soy milk through direct supplier agreements with cold-chain operators. FDA governs soy protein health claims and GRAS status determinations. Illinois and Iowa crushing clusters create geographic concentration risk for soy protein isolate supply.
Indonesia
Traditional tempeh consumption patterns in Java and Sumatra create receptive infrastructure for packaged food manufacturing expansion. The country's national food safety regulator evaluates novel soy processing methods for import substitution. Jakarta and Surabaya processing hubs introduce isolate grades into instant noodle and snack formulations.
Brazil
Identity-preserved soybean premiums fluctuate with global non-GMO demand swings. ANVISA evaluates novel food applications for enzymatically modified protein ingredients. São Paulo and Paraná agricultural clusters supply segregated feedstock to European and Chinese manufacturers.
Soy- Based Food Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with multinational food conglomerates commanding formulation expertise and Asian processors dominating feedstock access. The market structures around three tiers: diversified nutrition giants with fermented soy portfolios, specialized plant-protein extractors with extrusion capabilities, and regional dairy alternatives specialists with cold-chain density. Competitive moves center on backward integration into identity-preserved soybean sourcing and strategic partnerships with foodservice distributors seeking menu-ready meat analogs.
Within the diversified nutrition tier, Danone S.A. and Nestlé S.A. exemplify archetypes combining fermented soy expertise with European retail shelf presence. Vitasoy International Holdings anchors Asia-Pacific liquid soy milk distribution through decades of cold-chain infrastructure investment. These three occupy positions reflecting different geographic and format specializations rather than direct head-to-head competition.
| Leading Market Players |
|---|
| Danone S.A. |
| Vitasoy International Holdings |
| Nestlé S.A. |
| Unilever PLC |
| Conagra Brands Inc. |
| Archer Daniels Midland |
| Cargill |
| Hain Celestial |
| House Foods America Holding |
| Others |
Value Network & Pricing Analysis
Crushing capacity utilization in Illinois and Iowa processing clusters shapes both supply concentration and price floors for soy protein isolate grades. Chinese coastal processors with established non-GMO certification chains capture premium spreads through identity-preserved feedstock segregation, while European manufacturers absorb facility retrofit premiums under EU F-Gas Regulation mandates.
Pricing Analysis
The customization-premium spread between standard commodity soy milk and formulated isolate grades widens with certification tier. Three-tier pricing structure across premium, standard, and economy levels tracks non-GMO verification depth and protein concentration purity. Cost compression in commodity fluid formats is intensifying because coffee chain procurement consolidates around direct supplier agreements. Health-conscious consumers in subscription channels show least price sensitivity, while QSR procurement teams drive hardest bargain on textured protein for flexitarian menu placements.
Supply Chain Analysis
Port congestion on Shanghai-Rotterdam trade lanes elevates inbound logistics costs for European manufacturers sourcing Chinese isolate grades. Supply concentrates in United States, China, and Brazil, with Illinois crushing clusters, Jiangsu coastal processors, and Paraná agricultural zones anchoring global feedstock flows. Raw material dependencies center on identity-preserved soybeans, extrusion equipment components, and enzymatic processing agents. Single-source vulnerability runs through Midwestern US crushing concentration for high-grade isolate supply. Distribution runs through foodservice distributor networks for institutional procurement and direct-to-consumer cold-chain partnerships for premium fresh formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The soy-based food market functions as a service-attach opportunity where subscription replenishment models for specialty tofu and fermented dairy alternatives expand faster than commodity hardware sales through retail channels.
For Market Incumbents: Fortify cold-chain infrastructure density in Chinese tier-one cities and North American coastal metros to defend against direct-to-consumer platform encroachment. Deepen backward integration into identity-preserved soybean sourcing in Brazil and Iowa to secure non-GMO feedstock segregation. Prioritize certification investment for SAMR GB standards compliance to maintain European supplement brand procurement relationships.
For New Entrants and Emerging Players: Subscription-layer gaps in Indonesian packaged food manufacturing present white-space targets where incumbents under-serve tempeh-to-isolate upgrade demand. Target Java and Sumatra processing hubs for soy protein isolate introduction into instant noodle formulations. Pursue go-to-market angles through state-backed foodservice distributor partnerships aligned with China dual carbon policy incentives.
For Investors and Strategic Acquirers: Regional dairy alternatives specialists with captive cold-chain density represent acquisition target archetypes positioned for subscription channel capture. Long-term viability frames around 5-10 year consolidation windows favor processors with aqueous extraction expertise grandfathered under tightened EFSA novel food evaluations. Watch FDA GRAS determination timelines for enzymatically modified protein ingredients as inflection indicator for sports nutrition formulation shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Identity-Preserved Feedstock | Secures non-GMO certification chains for European and Chinese premium pricing capture. |
| High-Moisture Extrusion Capacity Expansion | Enables whole-muscle analog placement in Berlin and Hamburg center-plate applications. |
| Direct-to-Consumer Subscription Launch | Captures recurring revenue from urban flexitarian households in San Francisco and Shanghai. |
| EU F-Gas Regulation Compliance Retrofit | Positions German and Dutch manufacturing zones for preferential foodservice procurement. |
| Sports Nutrition Formulator Partnership | Locks in 90% concentrate grade demand from Chinese e-commerce platform distribution. |
Research Methodology
A spread of perspectives from extrusion technology specialists, foodservice procurement directors, sports nutrition formulators, and cold-chain logistics operators converged on the working assumptions driving this analysis. Primary interviews with plant protein processing engineers, regulatory affairs leads at multinational food conglomerates, and category buyers at Asian supermarket networks combined with secondary validation from FDA GRAS filings, EFSA novel food registers, SAMR GB standard publications, and customs trade data for soybean and isolate flows. Bottom-up capacity assessments across Illinois, Jiangsu, and Paraná processing zones triangulated against top-down demand modeling from coffee chain procurement disclosures and sports nutrition e-commerce platform metrics.
Segmentation dimensions modeled span product type, end user archetype, application category, and distribution channel across the analysis window. The analytical framework projects value expansion through protein concentration tier differentiation and channel mix evolution. CAGRs derive from facility commissioning timelines, workforce development trajectories for extrusion technicians, and regulatory approval velocity for novel processing methods. Forecast inputs incorporate EU Green Deal compliance cost absorption rates and China dual carbon policy incentive capture ratios.
Forecasts assume regulatory continuity in FDA health claim determinations, EFSA novel food evaluation protocols, and SAMR GB labeling enforcement; material policy shifts would require re-modeling around alternative protein terminology restrictions or protein content threshold redefinitions. Specific risks that could revise projections include enzymatic hydrolysis yield ceiling breakthroughs, extrusion technician training pipeline restoration, or non-GMO soybean premium volatility spikes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Indoor Leafy Green Precision Nutrition Program Market
Plant Based Food
Vegan Cookies Market
Plant Based Food
New Jersey Vegan Products Market
Plant Based Food
China Rice Protein Market
Plant Based Food
South America Soy Beverages Market
Plant Based Food
Vegan Gelatin Market
Plant Based Food
Plant Based Eggs Market
Plant Based Food
United Kingdom Plant Protein Market
Plant Based Food
Organic Pea Protein Market
Plant Based Food
Rice Protein Market
Plant Based Food
Vegan Alternatives Market
Plant Based Food
United States Plant Protein Market
Plant Based Food
Rhubarb Root Extract Market
Plant Based Food
Australia Plant Protein Market
Plant Based Food
Plant-Based Margarine Market
Plant Based Food
Plant Based Food Colors Market