
 Low-Calorie Pie Market | 2026-2036
Low-Calorie Pie Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Calorie Pie Market Analytics
Almond flour is rebalancing cost structures across low-calorie pie portfolios as wheat and refined sugar face formulation pressure. Nestlé leverages its frozen dessert infrastructure to anchor distribution in European retail chains. General Mills sustains R&D intensity through its Bell Institute of Health and Nutrition, while Tate & Lyle specializes in soluble fiber and sweetener systems that reduce caloric density without textural compromise.
Low-calorie pie denotes a baked dessert product containing reduced caloric content per serving, typically achieved through substitution of refined sugars with erythritol, stevia, or allulose, and replacement of traditional shortenings with plant-based or protein-enriched alternatives; manufacturers employ modified starch systems and controlled moisture content to maintain structural integrity comparable to conventional pastry. Frozen formats dominate volume through extended shelf stability and impulse-purchase placement, while high-protein ingredient positioning captures expanding margin pools in fitness-oriented channels. Shelf-stable variants remain mature with slower velocity, though pouch packaging for individual servings is accelerating in convenience retail.
FDA Nutrition Facts regulations and EU Health Claims standards constrain permissible labeling, compelling reformulation investments that reshape competitive cost curves. The European Food Safety Authority evaluates novel sweetener submissions, creating asymmetric market access timelines across jurisdictions. Stakeholders must monitor evolving clean-label certification thresholds and caloric-claim substantiation requirements to align portfolio development with enforcement trajectories.
Market Dynamics
Reformulation pressure from FDA's updated Nutrition Facts labeling for added sugars is forcing manufacturers to rebuild entire sweetener systems and recalibrate cost structures across frozen and shelf-stable portfolios.
Growth Catalysts
- Clean-label certification thresholds:Germany's Rewe and Edeka chains now mandate protein-enriched positioning, accelerating slotting fee negotiations for reformulated SKUs.
- Millennial retail adoption:Health-conscious cohorts in the United States drive velocity in frozen dessert aisles through repeat purchase patterns tracked by loyalty programs.
- Erythritol-stevia blending:Advanced sweetener systems reduce caloric density while maintaining Maillard reaction performance in crust applications.
Market Restraints
- Almond flour cost volatility:California drought cycles and water allocation disputes compress margins on gluten-free, low-calorie formulations.
- EFSA novel food timelines:European Food Safety Authority's asynchronous evaluation schedules for allulose and rare sugars delay market entry by 18-36 months versus FDA clearance.
- Modified starch supply concentration:Three suppliers control 70% of functional starch systems for moisture retention, creating single-source vulnerability.
Strategic Opportunities
- Fitness-oriented convenience retail:Pouch packaging for individual servings captures impulse traffic in gym-adjacent locations and airport kiosks.
- EU Health Claims substantiation:Protein-enriched varieties meeting EFSA's 20% energy-from-protein threshold unlock premium shelf positioning.
- Allulose regulatory tailwind:FDA's exclusion of allulose from added sugars declaration creates 30% caloric reduction claims without reformulation trade-offs.
Industry Challenges
- Moisture control expertise gap:Formulation chemists with simultaneous pastry science and alternative sweetener experience command 40% salary premiums.
- Dual certification complexity:Simultaneous USDA Organic and EU organic compliance requires parallel audit trails and segregated production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Calorie Pie Market |
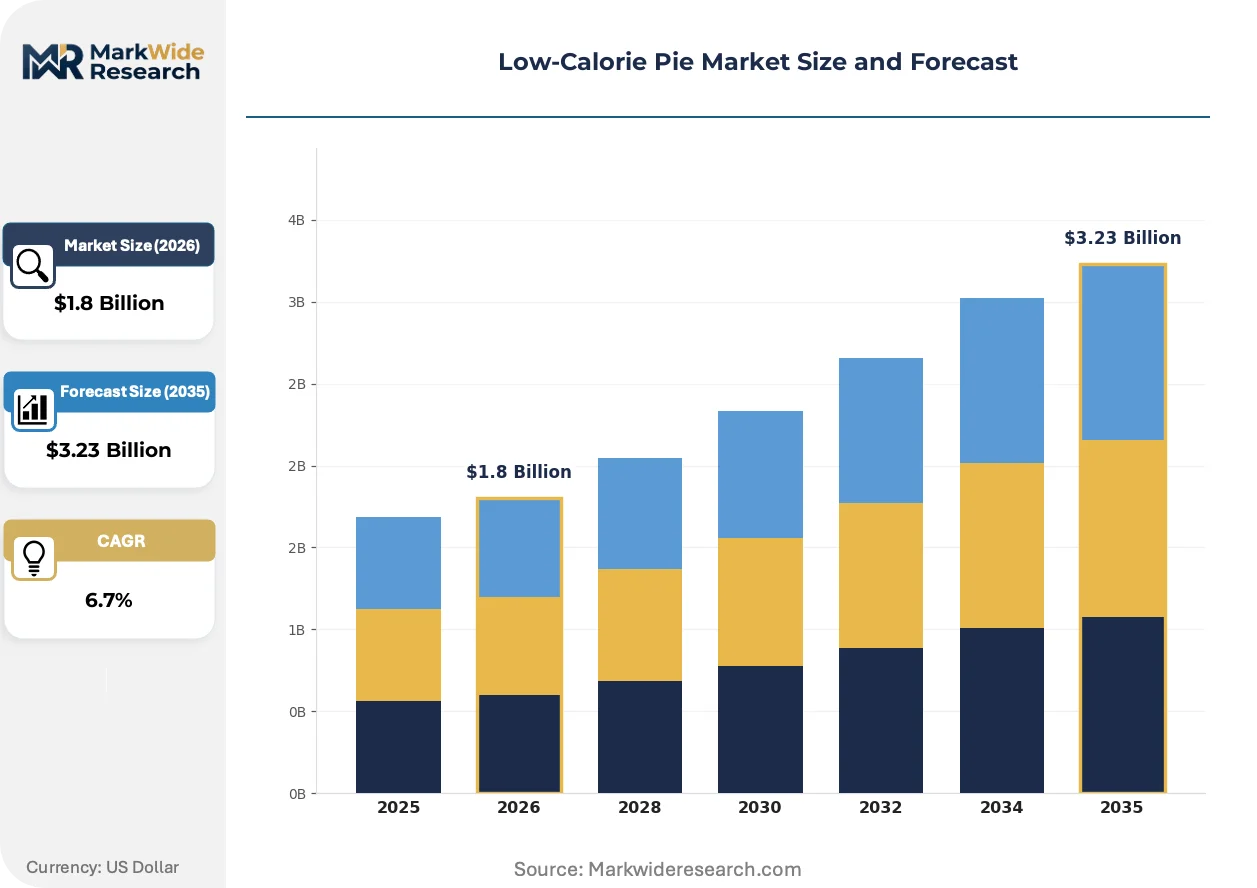
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen, Refrigerated, Shelf-Stable, Bakery Ingredient Type: Gluten-Free, Vegan, Low-Sugar, High-Protein Packaging Type: Box, Tray, Pouch, Individual Serving Distribution Channel: Supermarkets, Online Retail, Health Stores, Cafés |
| Companies Covered | Nestlé, General Mills, Mondelez International, Kellogg Company, The Kraft Heinz Company, Unilever, Conagra Brands, Tate & Lyle, PepsiCo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Calorie Pie Market Evolving Landscape
Alternative protein integration and precision fermentation are compressing traditional ingredient supply chains while opening new formulation pathways for texture-critical applications.
Precision fermentation-derived whey proteins are electrifying low-calorie pie formulations by replacing egg-based binders in vegan-positioned lines. Bakery R&D teams at mid-tier manufacturers are adopting these ingredients at pilot scale within 12-month windows. This technology is electrifying margin structures by reducing allergen labeling complexity and enabling dual vegan-high-protein claims.
EU F-Gas Regulation phase-down schedules are accelerating industrial refrigeration retrofits across frozen dessert production facilities. Compressor replacement cycles now prioritize ammonia-CO2 cascade systems with 15-year compliance horizons. Frozen format manufacturers in Poland and the Netherlands front-load capital expenditure to secure operational continuity before 2030 quota tightening.
Direct-to-fitness-channel distribution is capturing margin pools previously allocated to traditional retail slotting fees. Subscription box operators and gym partnerships displace conventional distributor networks for protein-enriched variants. This pattern concentrates in metropolitan United States clusters where boutique fitness chains maintain captive audience relationships.
Low-Calorie Pie Market Segmentation
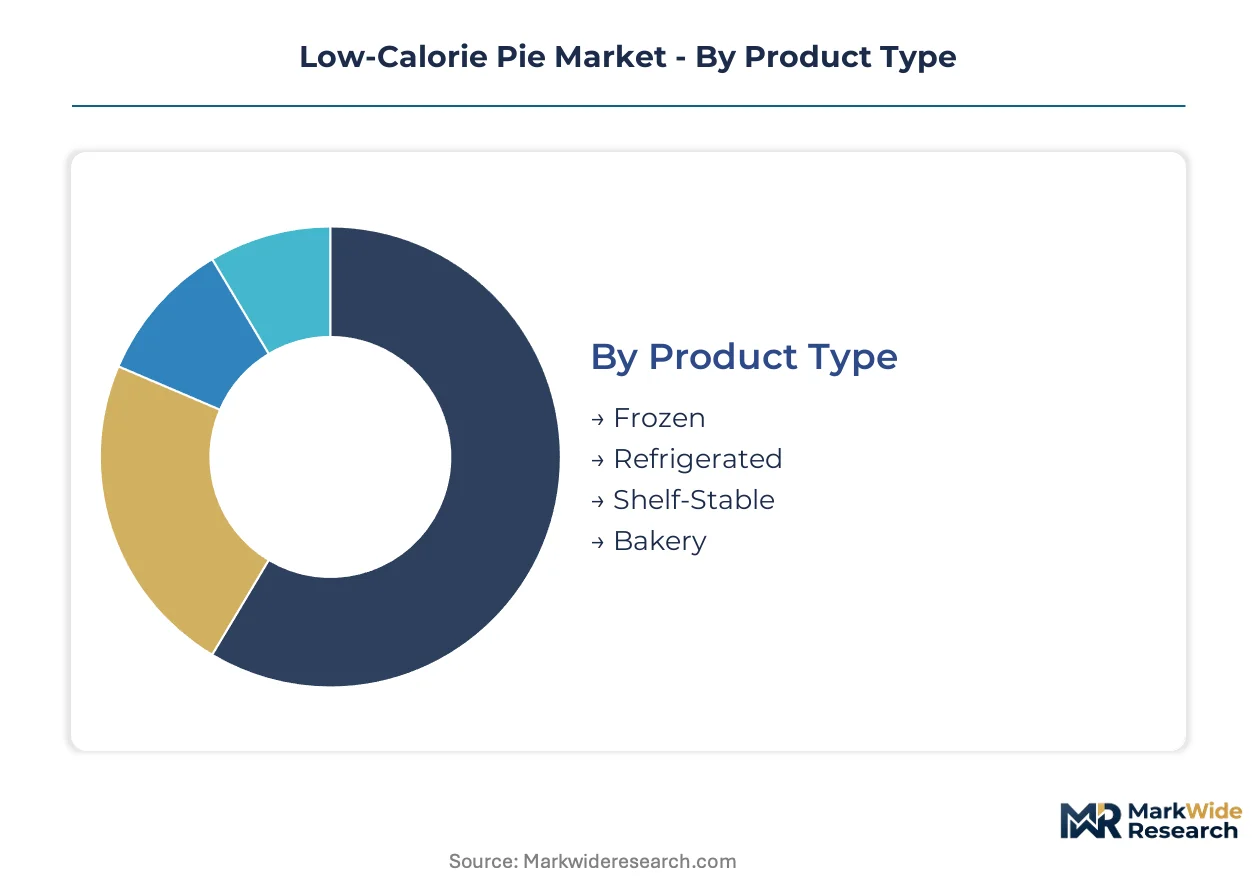
Segmentation in low-calorie pie markets determines capital allocation across refrigerated supply chains, frozen distribution infrastructure, and reformulation R&D. Manufacturers prioritize segments with the steepest velocity in health-conscious retail channels and the lowest per-unit compliance burden under evolving sweetener regulations.
Product Type:
Frozen formats demand the heaviest upfront investment in blast freezing capacity and ammonia-CO2 cascade refrigeration systems required by EU F-Gas Regulation phase-down schedules.
- Frozen:Extended shelf stability enables impulse-purchase placement in retail freezer aisles. Demand concentrates in United States metropolitan clusters where millennial loyalty programs track repeat velocity through frozen dessert sections. Reformulation investments for erythritol-stevia blending systems add 15-20% to R&D overhead.
- Refrigerated:Shorter shelf life necessitates cold-chain integrity from production through last-mile delivery. German Rewe and Edeka outlets drive slotting fee negotiations for protein-enriched refrigerated SKUs meeting clean-label certification thresholds.
- Shelf-Stable:Modified starch systems and controlled moisture content extend ambient distribution reach. United States convenience retail channels absorb individual serving pouches for on-the-go consumption.
- Bakery:Fresh-baked positioning commands premium positioning in café-adjacent locations. California and New York bakery chains pilot low-calorie formulations with almond flour bases.
Most installed capacity flows through Frozen. Expansion is steepest in Refrigerated.
Ingredient Type:
Ingredient positioning separates cost tiers through protein enrichment premiums versus commodity gluten-free alternatives, with margin capture diverging sharply across fitness-oriented versus allergen-avoidance consumer bases.
- Gluten-Free:Almond flour and alternative grain systems replace wheat-based shortenings. California drought cycles compress margins through water allocation disputes affecting nut crop yields.
- Vegan:Precision fermentation-derived whey proteins replace egg-based binders. Pilot-scale adoption accelerates in mid-tier manufacturers seeking dual vegan-high-protein claim positioning.
- Low-Sugar:Allulose, erythritol, and stevia systems reduce caloric density while maintaining Maillard reaction performance in crust applications. FDA exclusion of allulose from added sugars declaration unlocks 30% caloric reduction claims without reformulation trade-offs.
- High-Protein:Protein-enriched varieties meeting EFSA's 20% energy-from-protein threshold capture premium shelf positioning in European retail. Direct-to-fitness-channel distribution displaces conventional slotting fees through gym partnerships and subscription box operators.
Volume concentrates in Low-Sugar. Margin expansion is fastest in High-Protein.
Packaging Type:
Packaging configuration determines distribution economics, with individual serving formats requiring specialized pouch sealing equipment versus standard tray systems for multi-serve retail.
- Box:Standard corrugated protection for frozen and shelf-stable multi-serve units. United States supermarket chains dominate procurement volume.
- Tray:Rigid plastic or molded fiber platforms for refrigerated bakery display cases. German retail mandates recyclable tray materials under packaging waste directives.
- Pouch:Flexible film barriers enable individual serving portability. Gym-adjacent locations and airport kiosks in United States metropolitan clusters absorb impulse traffic.
- Individual Serving:Single-unit positioning captures convenience retail velocity. Health store channels in California and Texas prioritize grab-and-go formats.
Procurement weight sits with Box. Velocity is climbing fastest in Pouch.
Distribution Channel:
Channel selection dictates working capital intensity, with supermarkets requiring extended payment terms and slotting fees versus direct online retail with upfront inventory risk.
- Supermarkets:Frozen and refrigerated aisle placement demands trade promotion spending and loyalty program integration. United States chains track millennial repeat purchase patterns through proprietary data systems.
- Online Retail:Direct-to-consumer fulfillment requires cold-chain packaging investment for temperature-sensitive formats. Subscription box operators concentrate in fitness-oriented United States metropolitan markets.
- Health Stores:Clean-label certification thresholds gate entry for protein-enriched and vegan-positioned lines. Germany's specialized retail sector mandates EFSA-compliant health claim substantiation.
- Cafés:Foodservice placement for bakery-format low-calorie pies. New York and Los Angeles boutique chains test limited-time offerings.
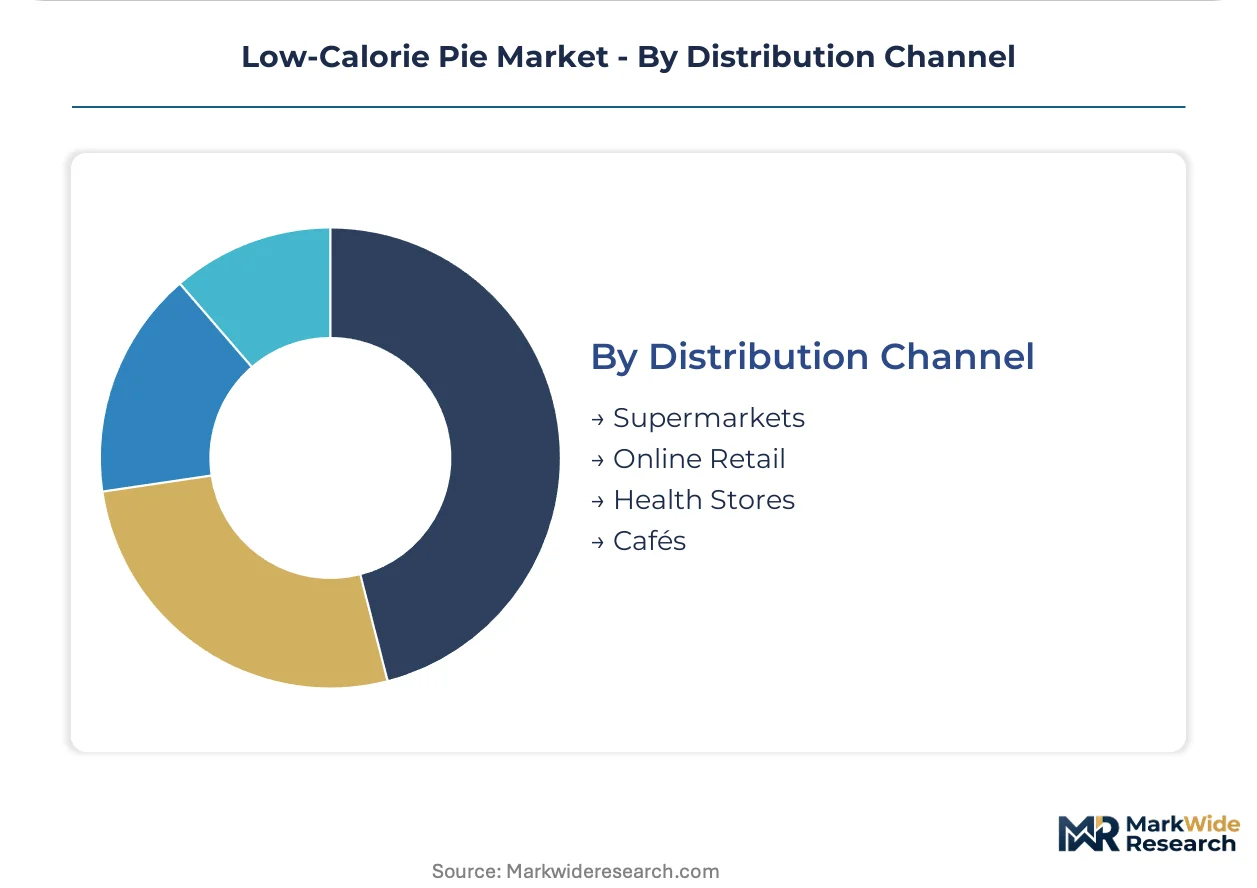
Revenue weight flows through Supermarkets. Share is gaining fastest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley almond orchards supply critical inputs for gluten-free crust formulations across North American and European manufacturing networks. Water allocation disputes and drought cycles compress raw material margins while driving reformulation toward alternative grain systems. Regulatory divergence between FDA and EFSA sweetener approval timelines creates asymmetric market access for novel ingredients.
United States
Millennial loyalty programs in metropolitan clusters track repeat velocity through frozen dessert aisles. FDA's exclusion of allulose from added sugars declarations unlocks caloric reduction claims without reformulation trade-offs. Chicago and Minneapolis frozen dessert production facilities anchor distribution networks for retail chains.
Germany
Rewe and Edeka chains mandate protein-enriched positioning, accelerating slotting fee negotiations for reformulated SKUs. EFSA's 20% energy-from-protein threshold gates premium shelf positioning under EU Health Claims standards. Bavaria and North Rhine-Westphalia host clean-label bakery R&D clusters serving Central European demand.
United Kingdom
Health store channels absorb grab-and-go individual serving formats in London and Southeast England corridors. Competition and Markets Authority scrutiny of retail pricing practices shapes promotional spending allocations. Midlands manufacturing bases supply refrigerated formats to supermarket private label programs.
Poland
Frozen format manufacturers front-load capital expenditure for ammonia-CO2 cascade refrigeration systems ahead of EU F-Gas Regulation quota tightening. Warsaw and Łódź production facilities serve as cost-competitive export hubs for Western European retail chains. Cold-chain infrastructure investments align with 2030 compliance horizons.
Netherlands
Rotterdam port logistics anchor ingredient import flows for alternative sweetener systems and modified starch inputs. Dutch food technology clusters pilot precision fermentation-derived proteins for vegan-positioned lines. Randstad metropolitan demand concentrates in convenience retail and airport kiosk channels.
Low-Calorie Pie Market Competitive Landscape
Global majors compete with regional champions across frozen dessert infrastructure and clean-label certification capabilities. Consolidated frozen food conglomerates leverage existing blast freezing capacity and retail slotting relationships against specialized bakery players with agile reformulation pipelines. Three archetypes dominate: diversified CPG conglomerates with frozen dessert portfolios, ingredient technology specialists supplying sweetener and fiber systems, and regional bakery chains with direct retail presence. Competitive moves concentrate on M&A for refrigeration assets and strategic partnerships for alternative protein sourcing.
Within the diversified conglomerate tier, Nestlé and General Mills exemplify scale-driven frozen infrastructure deployment, while Tate & Lyle occupies a specialist position supplying soluble fiber and sweetener systems to reformulating manufacturers. These anchors illustrate how competitive positioning diverges between asset-heavy frozen distribution and ingredient technology licensing models.
| Leading Market Players |
|---|
| Nestlé |
| General Mills |
| Mondelez International |
| Kellogg Company |
| The Kraft Heinz Company |
| Unilever |
| Conagra Brands |
| Tate & Lyle |
| PepsiCo |
| Others |
Value Network & Pricing Analysis
Protein-enriched certification tiers bifurcate cost structures across frozen and refrigerated formats, with EFSA-compliant 20% energy-from-protein thresholds commanding slotting fee premiums in German retail while commodity low-sugar variants face margin compression from almond flour volatility. This tier divergence manifests in supply chain configurations where premium SKUs draw from precision fermentation inputs and controlled cold-chain logistics, while economy positioning relies on modified starch systems and ambient distribution networks.
Pricing Analysis
Input-cost pass-through from California almond flour and erythritol-stevia blending systems reshapes margin structures across frozen dessert portfolios. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified protein positioning from clean-label gluten-free alternatives and commodity low-sugar formats. Cost compression in standard tiers intensifies because California drought cycles tighten nut crop yields. Health-conscious millennials in United States metropolitan clusters show lowest price sensitivity for high-protein pouch formats, while conventional frozen multi-serve buyers absorb trade promotion volatility.
Supply Chain Analysis
EU Health Claims substantiation requirements and FDA Nutrition Facts labeling mandates reshape sourcing toward domestic reformulation capabilities and segregated production runs. California almond orchards, Dutch modified starch facilities, and Polish ammonia-CO2 cascade refrigeration plants anchor geographic supply concentration. Raw material dependencies center on allulose sweetener systems, precision fermentation-derived proteins, and functional starch inputs. Single-source vulnerability concentrates in modified starch systems where three suppliers control functional moisture retention technologies. Distribution runs through frozen retail chains with loyalty program integration and direct-to-fitness subscription channels displacing conventional slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low-calorie pie market functions as a regulatory compounder where FDA's allulose exclusion from added sugars declarations and EFSA's protein threshold certifications continuously reshape formulation investment cycles and competitive cost curves.
For Market Incumbents: Deepen backward integration into precision fermentation protein sourcing to secure dual vegan-high-protein claim positioning against emerging ingredient technology specialists. Expand ammonia-CO2 cascade refrigeration capacity in Poland and Netherlands ahead of EU F-Gas Regulation quota tightening. Prioritize EFSA compliance investments to defend premium shelf positioning in German Rewe and Edeka networks.
For New Entrants and Emerging Players: Precision fermentation-derived whey proteins offer technology-first wedge into vegan-positioned lines where mid-tier manufacturers pilot adoption within compressed windows. Target direct-to-fitness-channel distribution in United States metropolitan clusters where gym partnerships and subscription box operators displace conventional slotting fees. Pursue clean-label certification thresholds as primary go-to-market angle for refrigerated format entry.
For Investors and Strategic Acquirers: Consolidation pressure builds where blast freezing infrastructure and EFSA-compliant R&D capabilities concentrate in fragmented regional bakery players. Five-to-ten year viability favors asset-heavy frozen distribution networks with established retail loyalty program integration over pure reformulation specialists. Acquisition target archetype: mid-tier manufacturers with pilot-scale precision fermentation adoption and German clean-label certification. Signal to watch: EFSA novel food timeline acceleration for allulose and rare sugars as inflection indicator for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Protein Integration | Precision fermentation-derived whey proteins reduce allergen labeling complexity and enable dual vegan-high-protein claims. |
| Ammonia-CO2 Cascade Refrigeration Retrofit | EU F-Gas Regulation phase-down schedules compel capital expenditure in Poland and Netherlands production facilities. |
| EFSA Health Claims Substantiation | Protein-enriched varieties meeting 20% energy-from-protein threshold unlock premium shelf positioning in German retail. |
| Direct-to-Fitness Distribution Buildout | Gym partnerships and subscription box operators capture margin pools previously allocated to supermarket slotting fees. |
| Allulose Reformulation Acceleration | FDA exclusion of allulose from added sugars declaration enables 30% caloric reduction claims without textural compromise. |
Research Methodology
Direct dialogue with frozen dessert R&D directors, retail category buyers at United States supermarket chains, German clean-label certification auditors, and precision fermentation ingredient suppliers grounded qualitative insights. Secondary validation drew from FDA Nutrition Facts labeling guidance documents, EFSA novel food evaluation registers, EU F-Gas Regulation compliance databases, and Nielsen retail audit data tracking frozen dessert velocity. Bottom-up and top-down triangulation reconciled manufacturer capacity disclosures with channel shipment patterns and end-user consumption estimates.
Bottom-up modeling aggregated segment-level volume and value trajectories across frozen, refrigerated, shelf-stable, and bakery formats through the projection horizon. Segmentation dimensions incorporated product type, ingredient positioning, packaging configuration, and distribution channel with regional regulatory cluster overlays. CAGRs derived from fitted growth curves calibrated to historical velocity patterns and reformulation investment cycle timing. Industry-specific forecast inputs included EFSA novel food approval timelines and EU F-Gas Regulation quota phase-down schedules.
The model holds under stable regulatory enforcement trajectories and continued clean-label certification threshold elevation; deviation in EFSA allulose evaluation acceleration or California almond crop yield collapse would shift competitive positioning and margin structures. Forecasts reflect documented assumptions about sweetener substitution rates and cold-chain infrastructure expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Waffle Market
Bakery Products
Pancakes Market
Bakery Products
Asia-Pacific Bakery Products Market
Bakery Products
Biscuit Mixes Market
Bakery Products
Vegan Baking Mix Market
Bakery Products
Frozen Bakery Market
Bakery Products
Cakes, Pastries, and Sweet Pies Market
Bakery Products
Frozen Bakery Additives Market
Bakery Products
Gluten-Free Baking Mixes Market
Bakery Products
Bakery Fats Market
Bakery Products
Pizza Dough Balls Market
Bakery Products
Organic Frozen Bakery Market
Bakery Products
Layer Cake Mixes Market
Bakery Products
Matcha Cookie Market
Bakery Products
Middle East and Africa Bakery Products Market
Bakery Products
Premixed Bread Flour Market