
 Europe Plant-Based Food and Beverage Market | 2026-2036
Europe Plant-Based Food and Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Plant-Based Food and Beverage Market Foresight
Asset-light contract manufacturing and co-packing arrangements are reshaping competitive entry in European plant-based production. Oatly Group AB leverages its proprietary enzymatic process to sustain premium positioning in oat milk across Nordic and Continental markets. Danone SA anchors its European footprint through specialized fermentation capabilities and established cold-chain distribution. Beyond Meat Inc. competes by focusing on whole-cut texture replication rather than commodity ground-meat formats.
Plant-based food and beverage encompasses formulated products derived from legumes, cereals, nuts, or oilseeds through mechanical processing, enzymatic treatment, or fermentation, designed to replicate the sensory and nutritional profiles of animal-derived foods. Protein extraction typically employs aqueous or alkaline methods followed by isoelectric precipitation to achieve functional gelling and emulsification properties for industrial food applications. Plant-based milk dominates current revenue contribution due to mature retail penetration and everyday consumption frequency across European households. Meat alternatives represent the fastest-expanding margin pool as processing scale improves and price parity with conventional proteins narrows in key markets. Distribution through supermarkets controls the majority of volume flow, though online retail channels are capturing disproportionate growth in repeat-purchase subscription models.
The EU Green Deal and Farm to Fork Strategy establish binding sustainability thresholds that reshape ingredient sourcing and carbon-labeling requirements for plant-based producers. EFSA nutrition and health claims standards determine which functional benefit statements reach packaging and advertising, directly influencing consumer trial and repeat purchase rates. REACH compliance for food-contact materials and emerging packaging regulations under the EU Packaging and Packaging Waste Directive add compliance layers for brands scaling across member states. Stakeholders must monitor evolving protein-source diversification beyond soy and pea into fava bean, lupin, and microbial fermentation inputs.
Market Dynamics
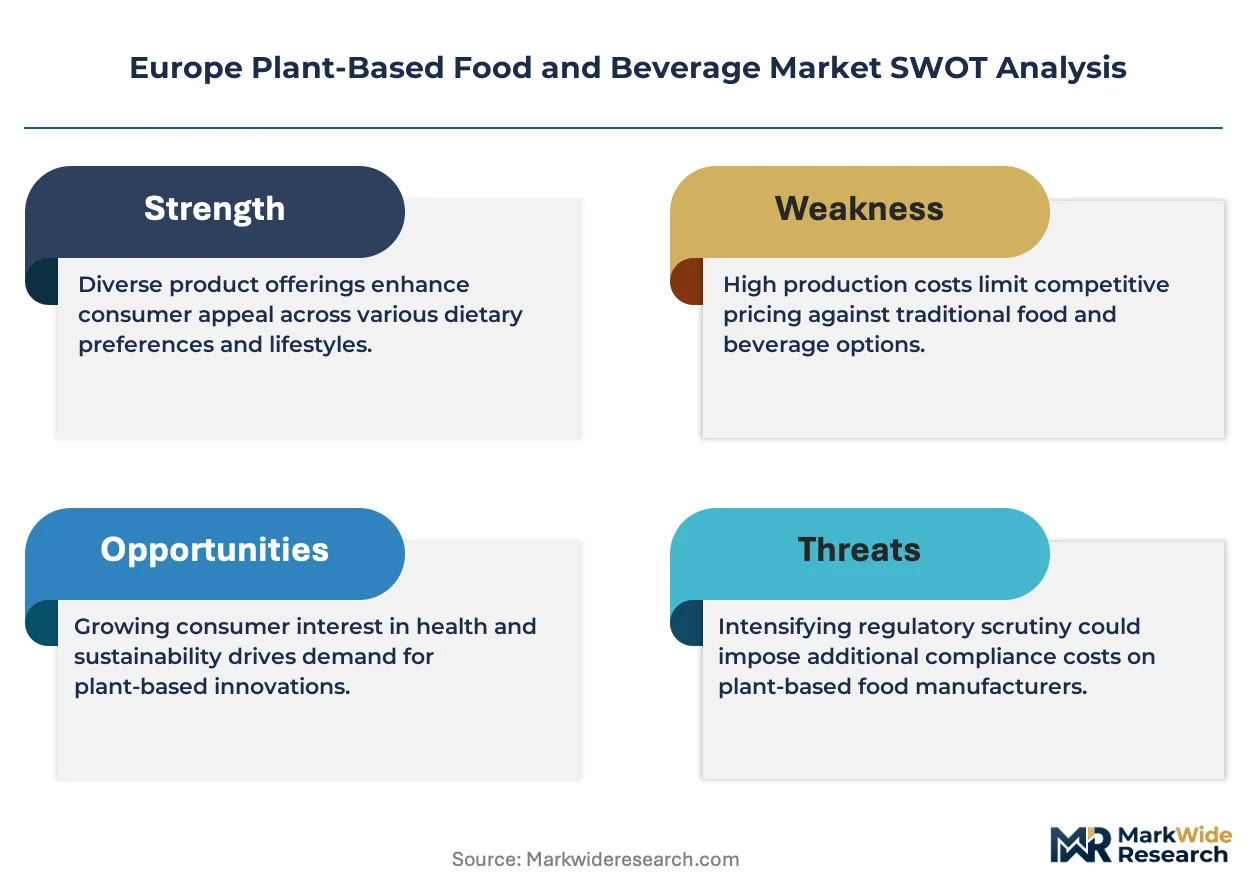
The EU Green Deal and Farm to Fork Strategy are compressing carbon-intensity thresholds for food producers while German discounters reallocate shelf space toward plant-based proteins, creating simultaneous regulatory and channel pressure that favors scaled operators with fermentation capabilities.
Growth Catalysts
- EU Green Deal carbon benchmarks:Binding sustainability thresholds force reformulation investments that lock in compliant suppliers and accelerate category consolidation.
- Flexitarian penetration in Germany:Reduced-meat households now exceed dedicated vegetarians, expanding addressable demand beyond niche positioning.
- Precision fermentation scale-up:Microbial protein production achieves cost parity with commodity isolates, unlocking clean-label positioning for meat alternatives.
Market Restraints
- Pea protein supply concentration:North American and Chinese processors control 70% of isolate supply, exposing European formulators to input volatility and tariff exposure.
- EFSA health-claims adjudication timelines:Average 18-month review cycles delay functional positioning launches and compress marketing runway.
- Analogue taste-performance gaps:Whole-cut texture replication in poultry alternatives remains below sensory parity, limiting repeat purchase rates in foodservice.
Strategic Opportunities
- Eastern European retail underpenetration:Polish and Romanian supermarket chains maintain minimal plant-based SKUs against rising urban disposable income.
- EU Packaging and Packaging Waste Directive:Extended producer responsibility mandates create first-mover advantage for compostable barrier film adopters.
- Enzymatic texturization + 3D extrusion convergence:Hybrid processing enables fibrous whole-cut structures previously unattainable with single-method systems.
Industry Challenges
- Food technologist talent scarcity:Formulation expertise spanning protein chemistry and sensory science commands premium compensation, constraining R&D velocity for mid-cap entrants.
- Multi-site REACH compliance:Cross-border manufacturing scale requires harmonized food-contact material certifications that delay facility activation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Plant-Based Food and Beverage Market |
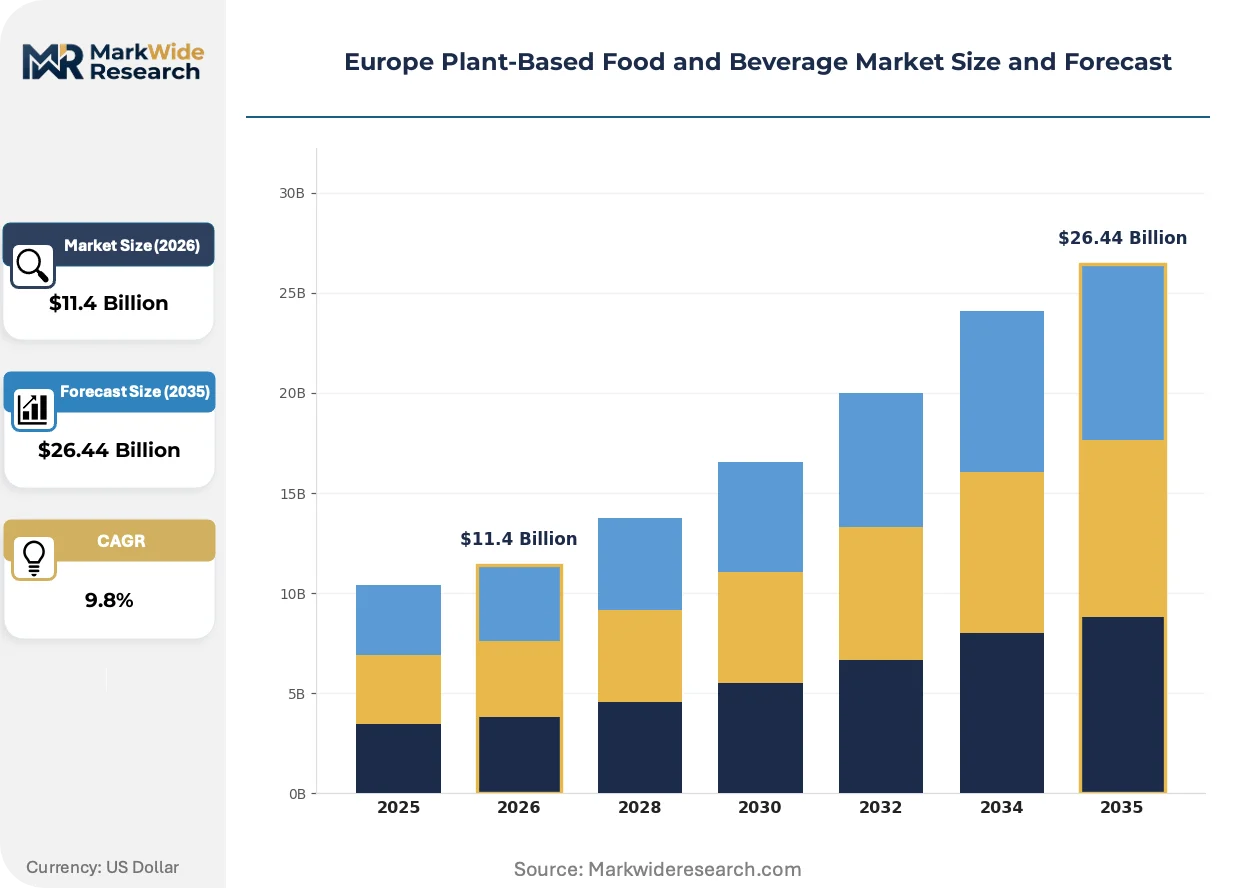
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $26.44 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plant-Based Milk, Meat Alternatives, Snacks, Sauces Consumer Segment: Vegans, Vegetarians, Flexitarians, Health-Conscious Consumers Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Specialty Shops Packaging Type: Recyclable, Biodegradable, Glass, Tetra Pack |
| Companies Covered | Oatly Group AB, Beyond Meat Inc., Danone SA, Conagra Brands Inc., Hain Celestial Group, Nestlé SA, Alpro, Taifun-Tofu GmbH, Unilever plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Plant-Based Food and Beverage Market Shifts & Advancements
Enzymatic processing breakthroughs and regulatory carbon-labeling mandates are rewriting formulation priorities while subscription commerce captures repeat-purchase loyalty previously anchored to supermarket perimeter placement.
High-pressure processing combined with enzymatic lipid structuring is collapsing the taste-texture gap between plant-based and conventional dairy in barista applications. Nordic coffee chains are adopting these reformulated oat bases within six-month procurement cycles. The compression of sensory parity timelines is forcing commodity milk alternatives into accelerated price competition.
EFSA's updated guidance on novel protein safety assessments tightens toxicology data requirements for fermentation-derived ingredients. European ingredient suppliers must now commission 90-day rodent studies before market authorization. This regulatory friction disproportionately burdens SME entrants in the microbial protein segment while favoring incumbents with established dossier libraries.
Direct-to-consumer subscription models for plant-based meal kits are displacing conventional supermarket trial purchases in UK urban centers. Young professional households prioritize convenience and personalization over price comparison. This channel rotation concentrates customer data ownership with vertically integrated brands and weakens traditional retailer gatekeeper power.
Europe Plant-Based Food and Beverage Market Segmentation
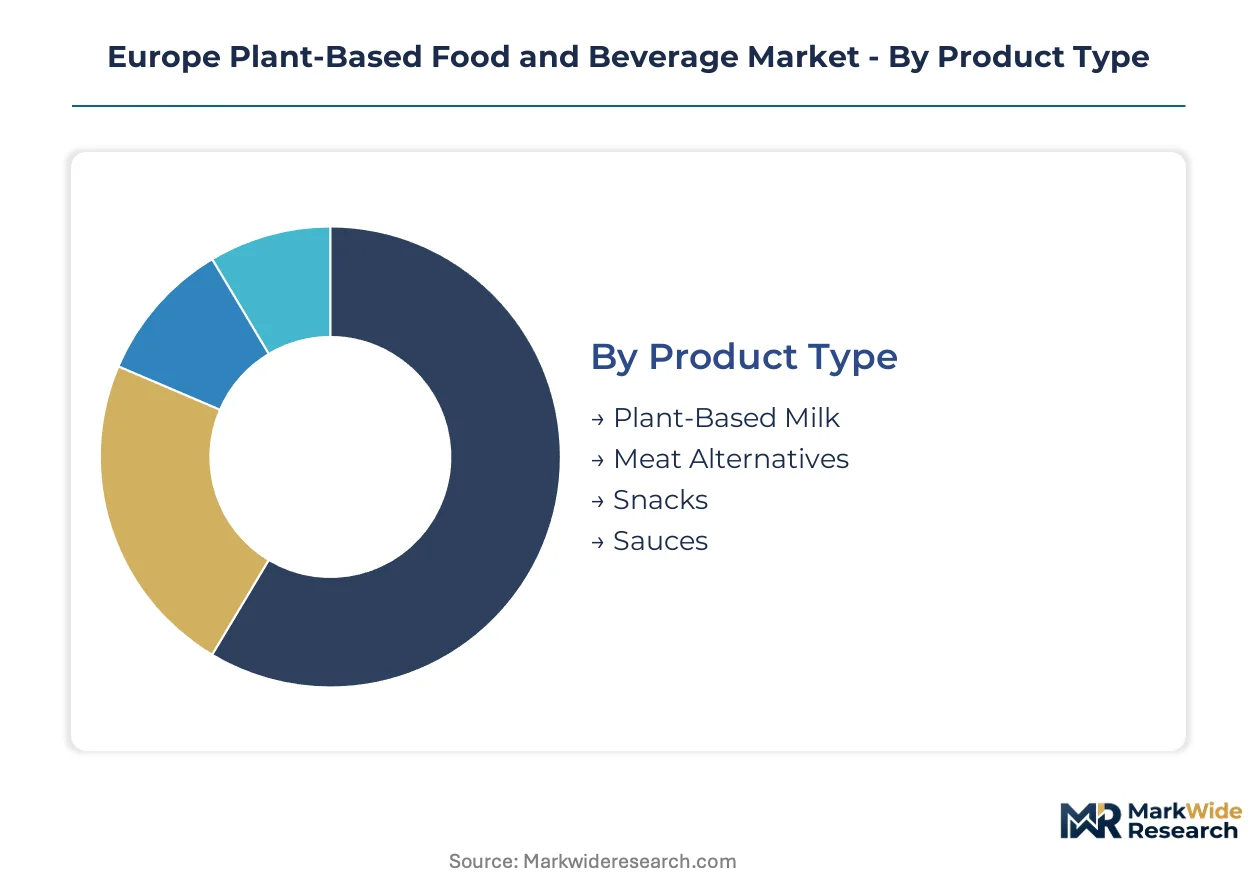
Segmentation in the European plant-based sector reveals divergent velocity profiles across consumption occasions and purchase channels. Understanding which segments turn inventory fastest versus which build long-term loyalty determines capital allocation and formulation roadmaps.
Product Type:
Plant-based milk restocks weekly in German and British supermarkets while meat alternatives cycle slower due to trial hesitancy and freezer logistics.
- Plant-Based Milk:Oat, almond, and soy formulations dominate refrigerated and ambient aisles. German discounters and Nordic coffee chains drive volume through barista-grade SKUs with enzymatic lipid structuring for foam stability.
- Meat Alternatives:Extruded and fermented whole-cut replications target flexitarian households reducing meat frequency. British and Dutch foodservice operators expand placement as price parity with conventional poultry improves.
- Snacks:Protein-fortified bars and chips capture impulse purchases in convenience retail.
- Sauces:Dairy-free dressings and cream alternatives serve niche vegan and allergen-avoidant segments.
Plant-based milk anchors the volume base while meat alternatives gain share at the steepest rate.
Consumer Segment:
Cost tier stratification separates premium-positioned vegan households from mass-market flexitarians driving category scale.
- Flexitarians:Reduced-meat households exceeding dedicated vegetarians in Germany and France. Weekly purchase frequency and price sensitivity shape product development toward sensory parity rather than ideological purity.
- Health-Conscious Consumers:Protein-seeking buyers prioritizing clean-label ingredient decks and EFSA-compliant health claims. French and Italian markets show concentration in organic-certified plant proteins.
- Vegans:Ethically motivated purchasers accepting taste trade-offs and premium pricing.
- Vegetarians:Long-established segment with stable demand for dairy alternatives and egg replacements.
Flexitarians generate the revenue base while health-conscious consumers expand most quickly as functional positioning tightens.
Distribution Channel:
Volume concentration in supermarket chains contrasts with margin capture in direct-to-consumer and specialty channels.
- Supermarkets:German Aldi and Lidl, British Tesco and Sainsbury's, and French Carrefour control mass-market penetration. Shelf-space reallocation toward plant-based proteins accelerates as private-label offerings multiply.
- Online Retail:Subscription models and meal-kit deliveries concentrate in UK urban centers. Young professional households prioritize convenience and personalization over price comparison.
- Health Food Stores:Independent retailers serving allergen-specific and organic-certified demand.
- Specialty Shops:Vegan boutiques and zero-waste refill stations in Berlin, Amsterdam, and Copenhagen.
Supermarkets anchor the volume base while online retail gains share at the steepest rate.
Packaging Type:
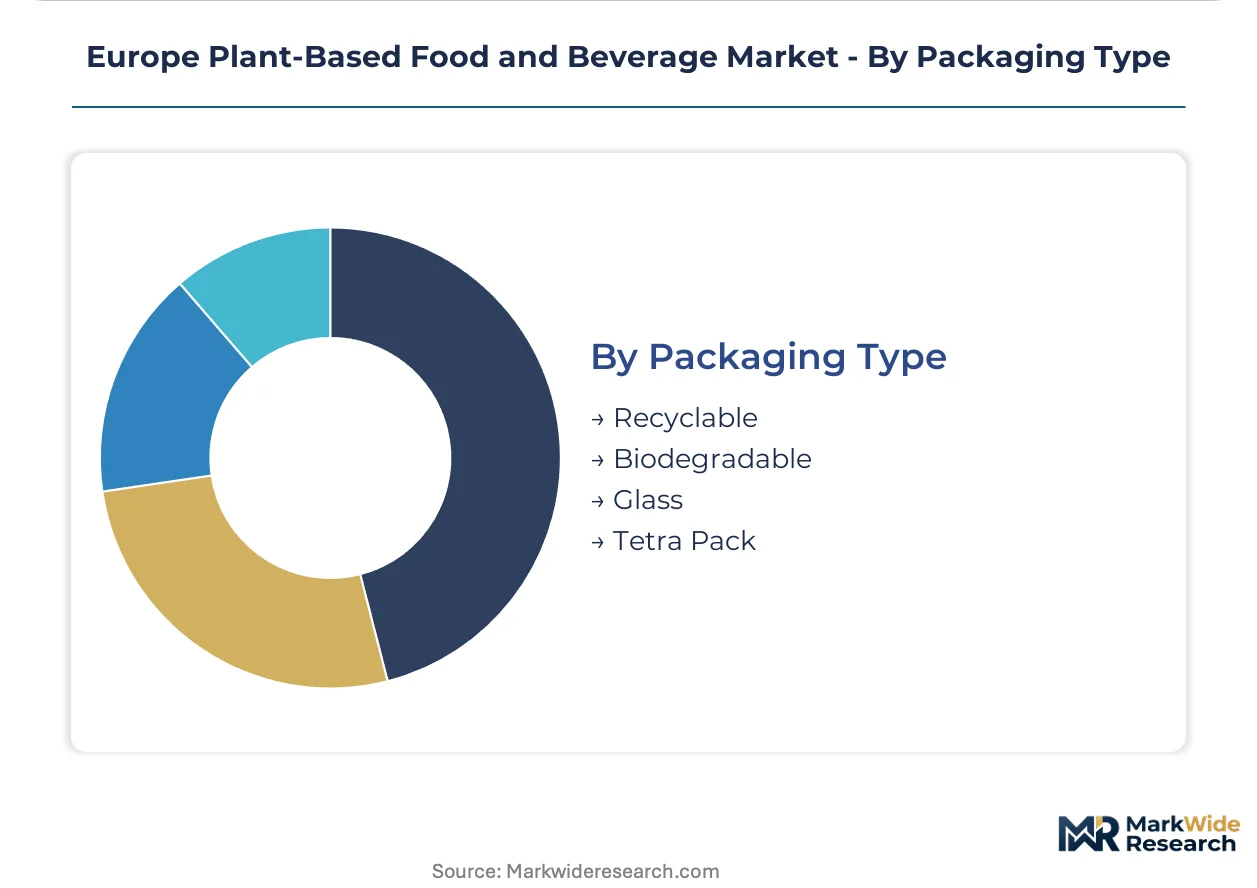
Regulatory pressure from the EU Packaging and Packaging Waste Directive reshapes material selection across price tiers.
- Recyclable:HDPE and PET bottles for plant-based milk meeting German and French extended producer responsibility mandates. Cost-competitive but facing competition from fiber-based alternatives.
- Biodegradable:Compostable barrier films and molded fiber trays for meat alternatives. First-mover advantage accrues to brands securing industrial composting certification.
- Glass:Premium positioning for organic-certified beverages in Italian and Spanish markets.
- Tetra Pack:Aseptic cartons dominating ambient shelf-stable milk alternatives with established recycling infrastructure.
Recyclable formats anchor the volume base while biodegradable solutions gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and Farm to Fork Strategy are compressing carbon-intensity thresholds for food producers across member states. German discounters reallocate shelf space toward plant-based proteins. French and Italian markets tighten organic certification requirements for dairy alternatives.
Germany
Flexitarian households now exceed dedicated vegetarians, driving weekly restock velocity in Aldi and Lidl refrigerated aisles. The Federal Ministry of Food and Agriculture enforces stricter animal welfare labeling that indirectly advantages plant-based positioning. Berlin-Brandenburg hosts fermentation scale-up facilities where precision protein startups secure industrial composting certification.
United Kingdom
Young professional households in London and Manchester prioritize subscription meal kits over supermarket perimeter browsing. The Food Standards Agency adjudicates novel protein safety assessments with tightened toxicology timelines. Cambridge and Oxford clusters concentrate enzymatic texturization R&D for whole-cut meat replication.
France
Health-conscious consumers concentrate demand for organic-certified plant proteins in Île-de-France and Auvergne-Rhône-Alpes. ANSM and DGCCRF coordinate EFSA-aligned health claims enforcement that delays functional positioning launches. Lyon-based foodservice operators expand plant-based poultry placement as price parity with conventional proteins narrows.
Netherlands
Dutch foodservice chains accelerate procurement cycles for barista-grade oat bases with enzymatic lipid structuring. The Netherlands Food and Consumer Product Safety Authority enforces REACH compliance for food-contact materials across multi-site manufacturing. Wageningen University clusters anchor microbial protein research with established dossier libraries.
Italy
Premium glass-bottled organic beverages capture shelf space in Milan and Rome specialty retail. The Ministry of Health implements EFSA nutrition claims standards that determine packaging functional benefit statements. Emilia-Romagna hosts extrusion technology specialists developing fibrous whole-cut structures.
Europe Plant-Based Food and Beverage Market Competitive Landscape
On the supply side, the industry is consolidating around scaled operators with captive fermentation capabilities and established cold-chain distribution. Mid-cap entrants rely on asset-light contract manufacturing to bypass capital-intensive facility buildouts. Two strategic archetypes dominate: enzymatic processing specialists commanding premium positioning in oat milk, and whole-cut texture replicators targeting flexitarian meat reduction. Competitive moves concentrate on co-packing partnerships and multi-site REACH compliance harmonization.
Within the Nordic enzymatic tier, Oatly Group AB exemplifies premium positioning sustained through proprietary process control. Danone SA anchors the established dairy-alternative segment through specialized fermentation infrastructure. Beyond Meat Inc. occupies a distinct archetype focused on whole-cut replication rather than commodity ground formats. These three represent contrasting strategic postures: proprietary technology lock-in, incumbent scale leverage, and format-specific innovation.
| Leading Market Players |
|---|
| Oatly Group AB |
| Beyond Meat Inc. |
| Danone SA |
| Conagra Brands Inc. |
| Hain Celestial Group |
| Nestlé SA |
| Alpro |
| Taifun-Tofu GmbH |
| Unilever plc |
| Others |
Supply & Pricing Matrix
Undercapacity in European precision fermentation facilities drives supplier consolidation and premium pricing for microbial protein isolates, while German discounter shelf-space reallocation compresses margins for commodity oat milk alternatives.
Pricing Analysis
Certification level (EFSA novel food authorization, organic EU logo) creates the primary spread between premium and mass-market tiers. Subscription-based direct-to-consumer models command recurring revenue premiums in UK urban centers, while Aldi and Lidl private-label SKUs anchor economy positioning. Cost compression in ambient-stable milk alternatives intensifies as enzymatic processing patents expire and Chinese equipment imports expand. Flexitarian households in Germany exhibit highest price sensitivity, whereas health-conscious French consumers accept organic-certified premiums.
Supply Chain Analysis
Pea protein isolate feedstock concentrates in Canada, China, and Ukraine, with European formulators drawing from North American processors for 70% of supply. Fava bean and lupin diversification efforts in Germany and France seek to reduce soy and pea dependency. Tariff exposure on Chinese-origin isolates under EU anti-dumping investigations creates input cost volatility. Distribution runs through German and British supermarket chains controlling mass-market volume, with cold-chain logistics for refrigerated meat alternatives commanding premium fulfillment costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation scale-up and EU Green Deal carbon labeling mandates are accelerating category disruption beyond incumbent dairy and meat supply chains.
For Market Incumbents: Insulate margin pools by securing captive fermentation capacity in Nordic industrial zones and accelerating EFSA novel food dossier submissions ahead of tightened toxicology timelines. Threats from precision fermentation startups achieving cost parity with commodity isolates demand backward integration into microbial protein production. For New Entrants and Emerging Players: Pursue white-space expansion in Polish and Romanian supermarket chains where plant-based SKU counts remain minimal against rising urban disposable income. Eastern European retail underpenetration offers the most penetrable geography, with foodservice co-packing partnerships providing lowest-capital market entry. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across precision fermentation sub-segments as modular bioreactor designs reduce facility buildout costs. Long-term viability favors acquisition targets with established EFSA dossier libraries and multi-site REACH compliance infrastructure. Signal to monitor: German discounter private-label market share crossing threshold levels that compress branded pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Authorization | Unlocks clean-label positioning for fermentation-derived ingredients in German and French retail. |
| Precision Fermentation Scale-Up | Reduces microbial protein production costs toward parity with commodity pea isolates. |
| Co-Packing Partnership Formation | Enables asset-light market entry for mid-cap brands without captive manufacturing facilities. |
| Organic Certification Investment | Captures premium pricing from health-conscious consumers in Île-de-France and Italian urban centers. |
| Direct-to-Consumer Channel Launch | Concentrates customer data ownership and subscription revenue in UK metropolitan households. |
Research Methodology
Desk research of EFSA novel food registers, EU Packaging and Packaging Waste Directive implementation timelines, and Nielsen retail audit data preceded structured interviews with plant-based R&D directors, German discounter category buyers, precision fermentation startup CEOs, and cold-chain logistics operators. Primary fieldwork combined with secondary validation across trade customs records and SEC filings of listed competitors enabled bottom-up volume triangulation against top-down macroeconomic benchmarks.
Assumptions held fixed include EU Green Deal carbon intensity thresholds and EFSA health claims adjudication timelines, while variables included precision fermentation cost curves and German flexitarian penetration rates. Segmentation modeling incorporated product type, consumer segment, distribution channel, and packaging format dimensions across the projection horizon. CAGRs derived from logistic adoption curves fitted to historical category velocity data, with inputs from enzymatic processing equipment cost indices and organic certification growth trajectories.
Sensitivities concentrate around EFSA toxicology requirement revisions and Ukrainian pea protein supply disruptions. Forecasts reflect documented assumptions on regulatory timelines and input cost trajectories. Cross-checking against Euromonitor retail audit benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant Derived Proteins Market
Plant Based Food
China Pea Protein Market
Plant Based Food
United States Meat Substitutes Market
Plant Based Food
Vegan Marshmallows Market
Plant Based Food
Indonesia Plant-Based Food and Beverages Market
Plant Based Food
Plant Based Food Colors Market
Plant Based Food
South America Soy Beverages Market
Plant Based Food
Vegan Protein Concentrate Market
Plant Based Food
Global Vegan Fast Foods Market
Plant Based Food
Fermented Plant-Based Ingredient Market
Plant Based Food
Plant-Based Chicken Market
Plant Based Food
Fermented Plant Extracts Market
Plant Based Food
Chicory Roots Market
Plant Based Food
Vegan Protein Foods Market
Plant Based Food
Soy Food Products Market
Plant Based Food
Kava Root Extract Market