
 Europe Rice Protein Market | 2026-2036
Europe Rice Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Rice Protein Market Foresight
Buyer concentration among European sports nutrition and dairy-alternative brands is pivoting toward specialized plant-protein suppliers with verified supply chains. Südzucker AG (BENEO) leverages its Belgian processing infrastructure to serve continental reformulation demand. Kerry Group sustains formulation partnerships with major food manufacturers seeking allergen-free protein systems. Axiom Foods competes through its concentrate and isolate specialization for meat-alternative applications.
Rice protein denotes the albumin and globulin fractions extracted from brown or white rice, typically processed through enzymatic hydrolysis or alkaline extraction to achieve protein contents ranging from 50% to 90% depending on grade. Its hypoallergenic profile and complete amino acid spectrum position it as a functional alternative to soy and whey in clean-label formulations. Isolate and concentrate grades command the deepest margin pools, with isolate purity above 80% protein driving premium positioning in sports nutrition and clinical nutrition segments. Hydrolyzed variants are gaining traction in beverage applications where solubility and digestibility determine formulation viability. Blends that combine rice protein with pea or pumpkin seed fractions occupy a growing niche in bakery and meat-alternative applications where texture modulation matters most.
EFSA novel food approvals and EU Green Deal sustainability benchmarks shape product development timelines and market access conditions for rice protein suppliers across Europe. REACH compliance and CE marking requirements for processing equipment add compliance layers that favor established operators with dedicated regulatory affairs capacity. Stakeholders must monitor evolving EFSA health claim pathways and national front-of-pack labeling schemes that could recalibrate consumer preference thresholds for plant-protein sources.
Market Dynamics
EFSA novel food approval timelines and EU Green Deal sustainability mandates are compressing product development cycles while favoring suppliers with dedicated regulatory affairs capacity and verified low-carbon processing infrastructure.
Growth Catalysts
- EU Green Deal carbon benchmarks:The EU Green Deal's farm-to-fork sustainability targets are forcing reformulation across dairy-alternative and sports nutrition categories, creating pull for rice protein's favorable carbon footprint versus animal-derived alternatives.
- Clean-label reformulation:German and French food manufacturers are eliminating soy and whey allergens from premium product lines, pivoting procurement toward hypoallergenic plant proteins with complete amino acid profiles.
- Enzymatic hydrolysis advances:Processing technology improvements are expanding rice protein solubility ranges, enabling beverage applications that previously excluded plant proteins due to texture limitations.
Market Restraints
- Input cost volatility:Brown rice feedstock prices fluctuate with Asian harvest cycles and shipping rates, compressing margins for European processors lacking long-term supply contracts.
- Supply concentration risk:Bulk isolate production concentrates among a handful of specialized extruders in Belgium and the Netherlands, creating single-source vulnerability for mid-tier brands.
- Functional limitations:Rice protein's lower leucine content versus whey requires blending or fortification, adding formulation complexity and cost in clinical nutrition segments.
Strategic Opportunities
- Italian meat-alternative expansion:Mediterranean plant-based meat startups are underpenetrated versus Northern European competitors, creating first-mover positioning for suppliers offering texture-optimized concentrates.
- EFSA health claim pathways:Pending approvals for muscle maintenance and satiety claims would unlock premium positioning in senior nutrition and weight management segments currently restricted to dairy proteins.
- Direct-to-manufacturer channels:Bypassing traditional ingredient distributors through technical sales teams is reducing customer acquisition costs for specialized isolate grades targeting craft sports nutrition brands.
Industry Challenges
- Regulatory affairs talent scarcity:Novel food dossier preparation requires specialized toxicology and nutritional science expertise that commands premium salaries and extended hiring timelines.
- REACH compliance capex:Processing equipment modifications for enzymatic hydrolysis systems require six-figure capital commitments to meet ECHA chemical safety registration requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Rice Protein Market |
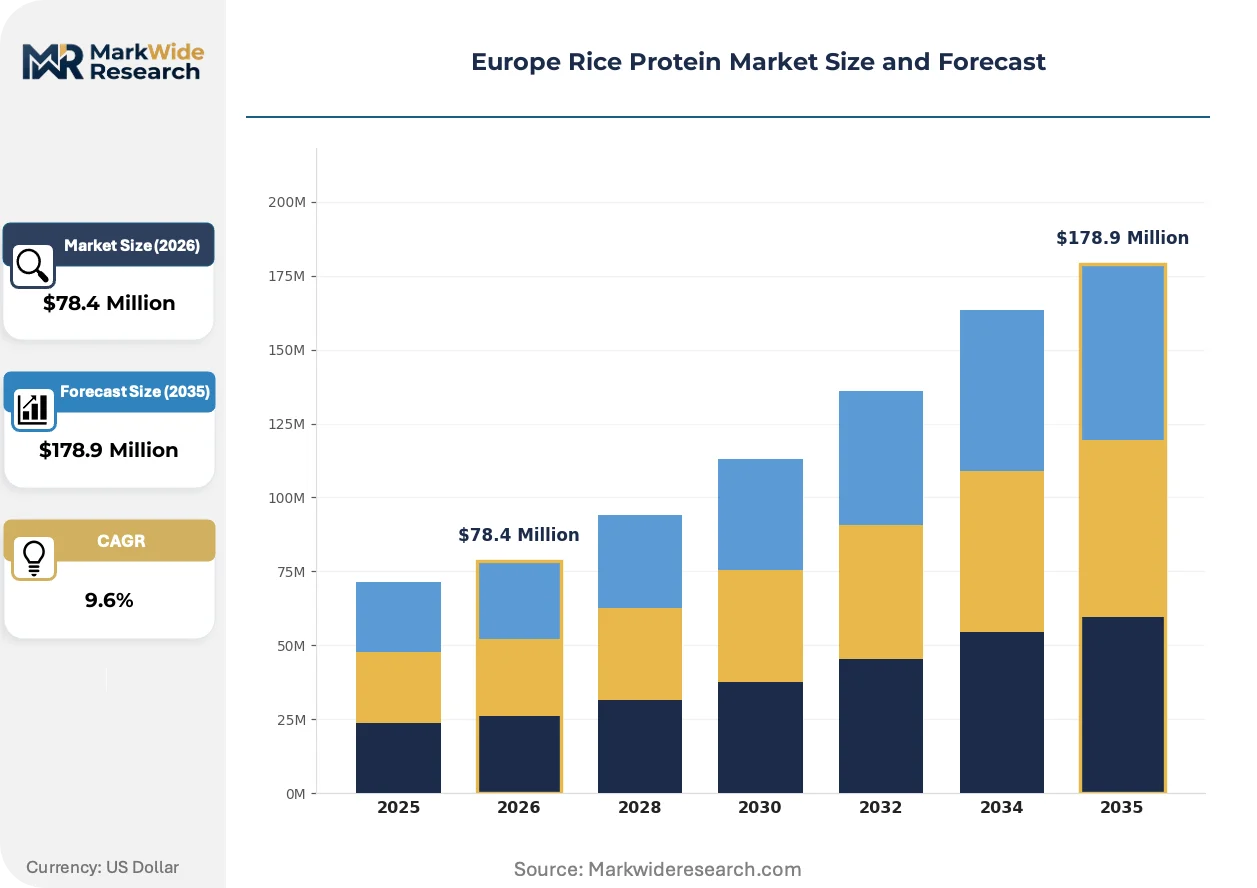
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $178.9 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Isolate, Hydrolyzed, Blends End User: Food Industry, Beverage Industry, Nutritional Supplements, Animal Feed Distribution Channel: Online Stores, Supermarkets, Health Food Shops, Pharmacies Application: Meat Alternatives, Dairy Alternatives, Bakery Products, Sports Nutrition |
| Companies Covered | Kerry Group, Axiom Foods, RiceBran Technologies, Südzucker AG (BENEO), Euroduna Food Ingredients, AIDP, Golden Grain Group, Shafi Gluco Chem, Nagase America Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Rice Protein Market Shifts & Advancements
Processing technology convergence and regulatory pathway acceleration are redefining competitive advantage around solubility performance and carbon-verified supply chains rather than commodity protein content alone.
Membrane filtration technology is integrating into brown rice protein extraction workflows, enabling processors to isolate protein fractions without hexane or harsh alkaline conditions. Dutch and Belgian equipment suppliers are retrofitting existing facilities with ceramic membrane systems that reduce water consumption and improve isolate purity consistency. This technology is integrating sustainability credentials with functional performance, allowing suppliers to command price premiums in clean-label segments where solvent-free processing is a procurement requirement.
EFSA's streamlined novel food approval procedures for traditional foods from third countries are reducing market access timelines for Asian-sourced rice protein ingredients. The regulatory revision eliminates redundant safety assessments for processing methods already established in the food supply, compressing approval cycles from 18 months to under 9 months for qualified applicants. French and German importers are responding by accelerating dossier submissions for hydrolyzed variants targeting beverage applications.
Brand procurement teams are consolidating supplier relationships around full-service formulation partners rather than commodity ingredient vendors. Sports nutrition manufacturers in Germany are demanding integrated technical support spanning protein selection, flavor masking, and finished product stability testing, displacing transactional purchasing models. This consolidation is most visible in the direct-to-consumer protein powder segment, where speed-to-market pressures favor single-source relationships with regulatory documentation included.
Europe Rice Protein Market Segmentation
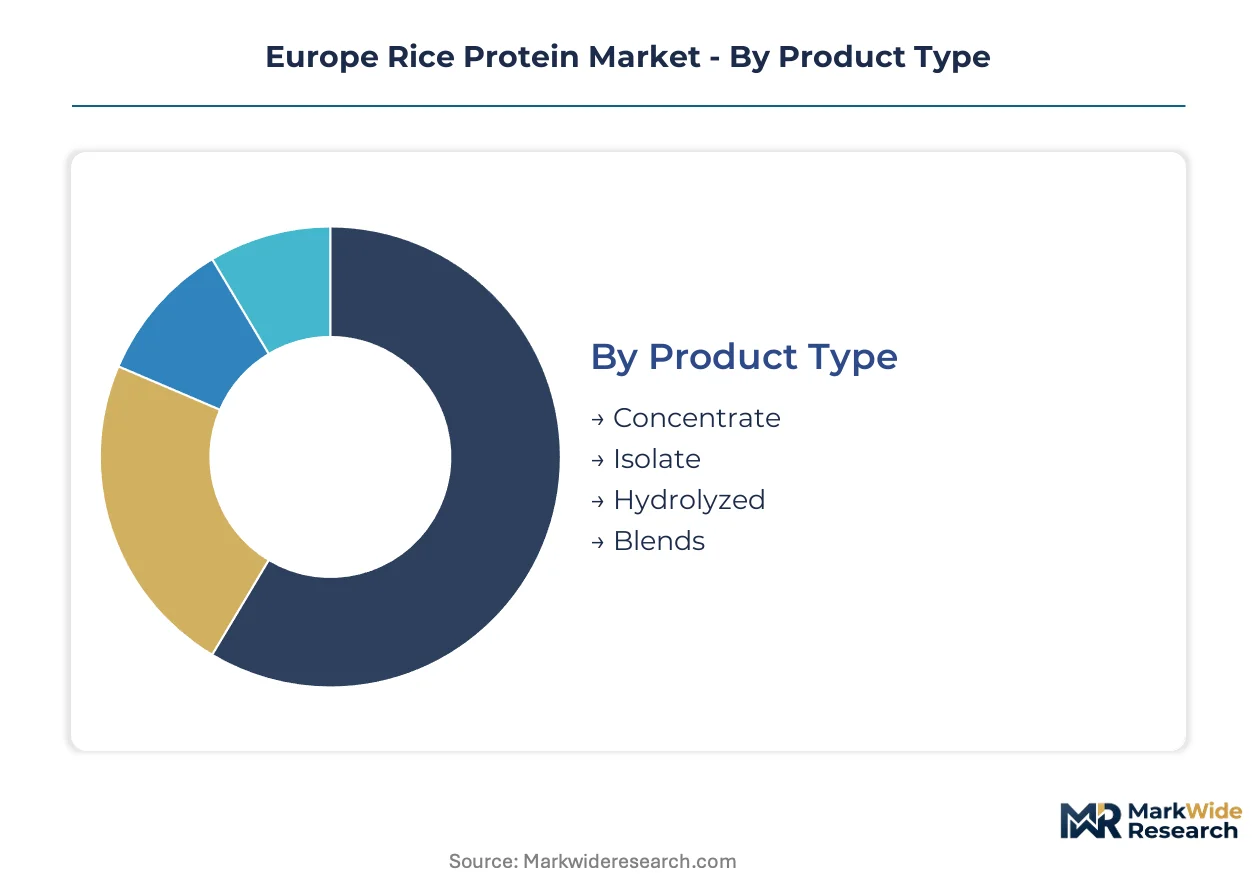
European rice protein procurement patterns diverge sharply across product grades and application channels, with isolate purity thresholds and EFSA compliance status determining supplier selection criteria. Understanding these segment boundaries reveals where formulation partnerships command premium positioning versus commodity trading dynamics.
Product Type:
Supply concentration among Belgian and Dutch extruders shapes grade availability, with enzymatic hydrolysis capacity limiting hydrolyzed variant output relative to concentrate and isolate volumes.
- Isolate:Protein purity exceeds 80% through alkaline extraction and membrane filtration, meeting sports nutrition and clinical nutrition specifications where leucine fortification addresses amino acid gaps. German sports nutrition brands in Cologne and Munich concentrate procurement here for premium positioning.
- Concentrate:50-70% protein content processed through simpler enzymatic methods, serving cost-sensitive bakery and meat-alternative applications across Northern Italy where texture modulation matters more than purity premiums.
- Hydrolyzed:Pre-digested peptides enabling beverage solubility; limited European production capacity restricts supply.
- Blends:Pea-rice or pumpkin-rice combinations for complete amino acid profiles; favored by French clean-label reformulators.
Isolate absorbs the bulk of installed capacity; hydrolyzed is expanding most quickly as beverage applications overcome solubility barriers.
End User:
Cost tier differentiation separates commodity feed applications from pharmaceutical-grade nutritional systems, with EFSA novel food dossier costs filtering supplier participation.
- Nutritional Supplements:Powder and capsule formats demanding batch-certified allergen-free status; Dutch direct-to-consumer brands in Amsterdam drive specification tightening.
- Food Industry:Meat-alternative and bakery manufacturers in Milan and Barcelona sourcing texture-optimized concentrates for reformulation pipelines.
- Beverage Industry:Ready-to-drink protein waters and plant milks requiring hydrolyzed grades for suspension stability.
- Animal Feed:Pet food and aquaculture applications accepting lower-purity concentrates with minimal regulatory documentation.
Nutritional supplements command the steepest price premiums; food industry volume is climbing the fastest as meat-alternative startups scale.
Distribution Channel:
Volume concentration through health food specialists and pharmacies reflects the technical sales support required for formulation integration, contrasting with transactional supermarket procurement.
- Health Food Shops:Independent retailers across Germany and Austria providing consumer education on hypoallergenic protein benefits; staff training programs drive brand loyalty.
- Online Stores:Direct-to-consumer platforms capturing subscription-based sports nutrition sales; Berlin and Hamburg startups dominate this channel.
- Supermarkets:Mass-market retail chains in France and the Netherlands adding plant-based protein powders to private-label ranges.
- Pharmacies:Clinical nutrition and senior protein supplements requiring pharmacist consultation; strongest in Swiss and Austrian markets.
Health food shops absorb the bulk of installed capacity; online stores are expanding most quickly as direct-to-consumer brands bypass traditional distribution.
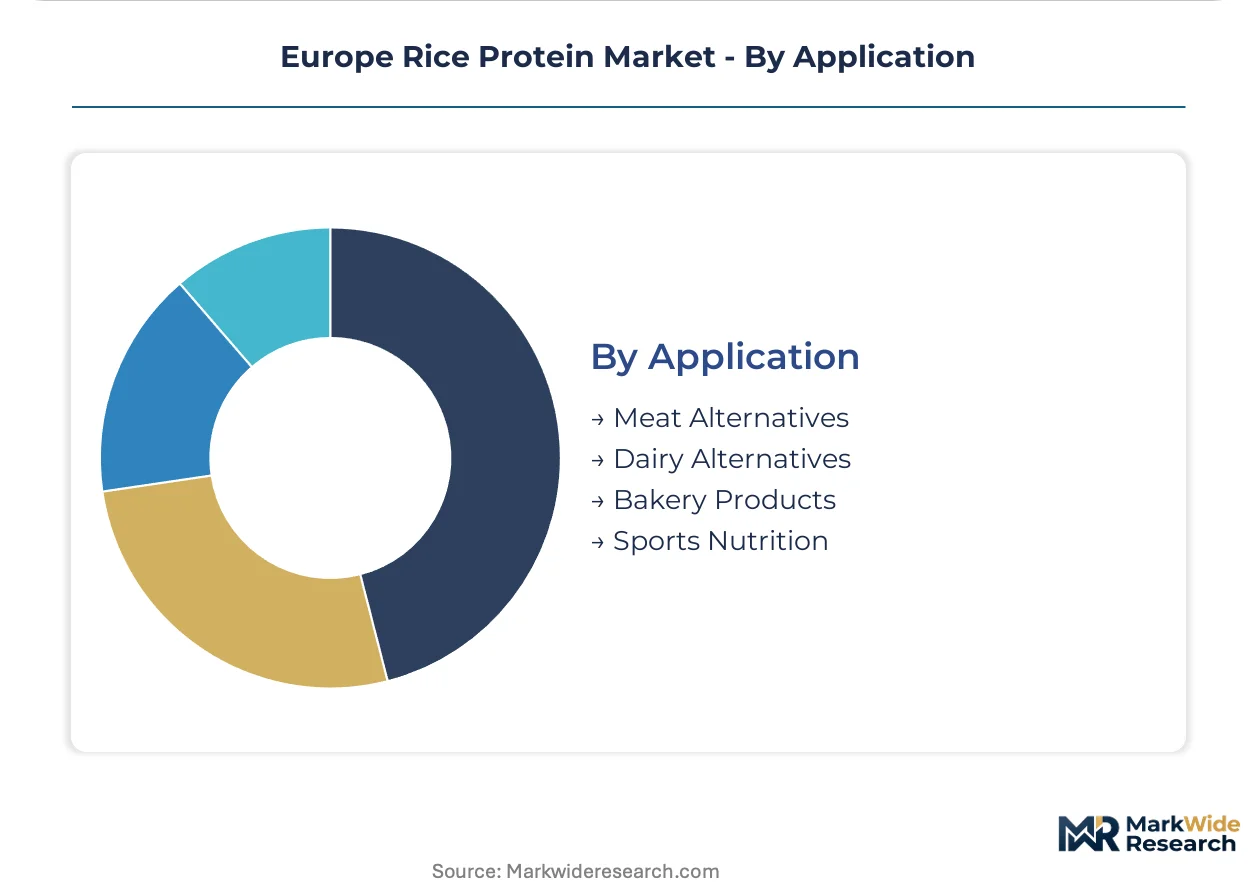
Application:
Customer type maturity separates established dairy-alternative manufacturers from emerging meat-alternative ventures, with technical support demands varying across application complexity.
- Sports Nutrition:Protein powders and bars requiring flavor masking and amino acid fortification; Cologne and Munich brands lead European innovation.
- Meat Alternatives:Textured concentrates for plant-based sausages and patties; Italian startups in Bologna and Milan represent underpenetrated demand.
- Dairy Alternatives:Yogurt and ice cream applications demanding emulsion stability; Dutch processors serve this segment through established formulation partnerships.
- Bakery Products:Bread and pastry fortification with lower solubility requirements; French bakers in Lyon and Paris drive clean-label adoption.
Sports nutrition absorbs the bulk of installed capacity; meat alternatives are expanding most quickly as Mediterranean plant-based ventures accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brown rice feedstock from Asian supply chains anchors European processing capacity, with enzymatic hydrolysis facilities clustering in the Benelux region and Northern Italy where reformulation demand concentrates.
Germany
Sports nutrition brands in Cologne and Munich are eliminating whey and soy allergens from premium product lines. EFSA novel food dossier requirements filter supplier participation, favoring established operators with dedicated regulatory affairs teams. The North Rhine-Westphalia cluster hosts formulation partnerships between processors and direct-to-consumer protein powder startups.
Netherlands
Dutch direct-to-consumer brands in Amsterdam are tightening allergen-free certification specifications for nutritional supplements. REACH compliance requirements for enzymatic hydrolysis equipment add capital intensity that favors scaled processors. Rotterdam and Amsterdam serve as import gateways for Asian-sourced rice protein feedstock.
Italy
Meat-alternative startups in Bologna and Milan represent underpenetrated demand versus Northern European competitors. EU Green Deal farm-to-fork sustainability targets are accelerating clean-label reformulation in Emilia-Romagna's food manufacturing base. Texture-optimized concentrates are gaining traction among Mediterranean plant-based ventures.
France
French clean-label reformulators in Lyon and Paris are adopting pea-rice and pumpkin-rice blends for complete amino acid profiles. EFSA's streamlined novel food approval procedures are compressing market access timelines for hydrolyzed variants. The Île-de-France region hosts technical sales teams serving bakery and beverage applications.
Belgium
Südzucker AG leverages Belgian processing infrastructure to serve continental reformulation demand. CE marking requirements for membrane filtration systems favor established equipment operators. The Flanders region concentrates isolate production capacity serving German and Dutch sports nutrition procurement.
Europe Rice Protein Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized isolate grades and direct-to-manufacturer channels. The vendor base stratifies across three maturity tiers: multinational ingredient conglomerates with formulation partnerships, regional processors with verified low-carbon infrastructure, and Asian-sourced suppliers navigating EFSA approval pathways. Competitive moves concentrate on M&A for enzymatic hydrolysis capacity and strategic partnerships with sports nutrition brands seeking technical support integration.
Within the multinational tier, Kerry Group and Südzucker AG (BENEO) exemplify full-service formulation partnerships spanning protein selection, flavor masking, and regulatory documentation. Axiom Foods occupies a position among specialized concentrate and isolate suppliers targeting meat-alternative applications. These three anchors represent distinct competitive archetypes: integrated technical service providers, backward-integrated processors with captive supply chains, and focused specialists competing on grade purity.
| Leading Market Players |
|---|
| Kerry Group |
| Axiom Foods |
| RiceBran Technologies |
| Südzucker AG (BENEO) |
| Euroduna Food Ingredients |
| AIDP |
| Golden Grain Group |
| Shafi Gluco Chem |
| Nagase America Corporation |
| Others |
Supply & Pricing Matrix
German and Dutch sports nutrition brands concentrate procurement among a narrow tier of EFSA-approved suppliers, anchoring a contract-based pricing model where enzymatic hydrolysis capacity scarcity props premium tiers. This buyer concentration compresses margin pools for mid-tier processors lacking verified low-carbon infrastructure or novel food dossiers.
Pricing Analysis
High-volume concentrate grades trade on thinner margins than isolate purity tiers, with three-tier pricing structure across premium, standard, and economy levels separating EFSA-certified isolates from commodity concentrates and feed-grade fractions. Certification tier and volume scale drive price differentiation, with hydrolyzed variants commanding premiums for beverage solubility. Cost compression in standard concentrates is intensifying because Asian feedstock volatility feeds through to European processors. Food industry manufacturers show highest price sensitivity, while clinical nutrition segments absorb premium positioning for allergen-free certification.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Antwerp anchor hub-and-spoke patterns for Asian-sourced brown rice feedstock, with Belgian and Dutch extruders serving German and French reformulation demand. Supply concentrates in China, India, and Thailand for raw brown rice, while enzymatic hydrolysis equipment and membrane filtration systems draw from German and Italian engineering bases. Single-source vulnerability pervades the hydrolyzed grade segment where Belgian capacity limits output. Distribution runs through direct-to-manufacturer technical sales channels for isolate grades, bypassing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic hydrolysis capacity scarcity across the Benelux region props pricing premiums, with bottlenecked equipment installation timelines filtering supplier participation to well-capitalized incumbents.
For Market Incumbents: Acquire membrane filtration assets and enzymatic hydrolysis capacity in the Flanders region to lock in isolate production advantages. EFSA regulatory affairs talent scarcity threatens dossier preparation timelines; build captive toxicology teams to accelerate novel food approvals. Backward integration into verified low-carbon brown rice supply chains from Asian contract farms secures sustainability credentials for EU Green Deal compliance. For New Entrants and Emerging Players: Begin with texture-optimized concentrate grades targeting Italian meat-alternative startups in Bologna and Milan, the most penetrable geography where Northern European suppliers remain underrepresented. Direct-to-manufacturer technical sales teams bypassing traditional distributors offer the strongest go-to-market angle for craft sports nutrition brands seeking integrated formulation support. For Investors and Strategic Acquirers: The window for entry favors processors with installed EFSA novel food approvals and low-carbon processing infrastructure over greenfield capacity builds. Acquisition targets should display established formulation partnerships with German sports nutrition brands. Watch EFSA health claim pathway decisions for muscle maintenance and satiety as the critical inflection signal unlocking premium clinical nutrition positioning.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Acceleration | Compresses approval timelines from 18 months to under 9 months for qualified Asian-sourced ingredients. |
| Membrane Filtration Capacity Expansion | Belgian and Dutch retrofit investments reduce water consumption while improving isolate purity consistency. |
| Direct-to-Manufacturer Channel Development | Berlin and Hamburg startups bypass traditional distributors through integrated technical sales teams. |
| Pea-Rice Blend Formulation Partnerships | French clean-label reformulators in Lyon adopt complete amino acid profiles for bakery applications. |
| Italian Meat-Alternative Technical Support | Bologna and Milan ventures demand texture-optimized concentrates as Mediterranean plant-based scaling accelerates. |
Research Methodology
Multi-period observation of EFSA approval timelines, enzymatic hydrolysis capacity installations, and brown rice feedstock pricing anchored the trend analysis, supplemented by interviews with plant protein processors, sports nutrition brand managers, regulatory affairs consultants, and bakery reformulation specialists. Secondary validation drew from EFSA novel food registers, EU Green Deal policy documents, REACH compliance filings, and Benelux customs trade data. Bottom-up segment sizing triangulated against top-down protein ingredient market allocations.
Segment-weighting across product grades, end-use applications, and distribution channels structured the analytical framework, with isolate purity thresholds and EFSA compliance status receiving differential weighting. CAGRs derived from trajectory fitting to historical capacity expansion rates and reformulation pipeline announcements. Forecast inputs incorporated EU Green Deal carbon benchmark adoption curves and enzymatic hydrolysis technology diffusion patterns across the projection horizon.
Underlying measurement precision varies by segment; isolate and hydrolyzed grades carry tighter precision than commodity concentrates given clearer certification boundaries. Forecasts reflect documented assumptions around EFSA regulatory pathway stability and Asian harvest cycle normalization. Brown rice price volatility, shipping rate disruptions, or EFSA health claim rejection could materially revise trajectory. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant Based Cheese Market
Plant Based Food
Asia Pacific Plant-Based Milk Market
Plant Based Food
Vegan Pastry Market
Plant Based Food
Global Tofu Market
Plant Based Food
Rhubarb Root Extract Market
Plant Based Food
Faba Bean Protein Market
Plant Based Food
Vegan Protein Foods Market
Plant Based Food
Plant-Based Frozen Dessert Market
Plant Based Food
Hemp-Based Food Market
Plant Based Food
Plant Chocolate Protein Powder Market
Plant Based Food
United Kingdom Tofu Market
Plant Based Food
Plant Based Breads Market
Plant Based Food
Canada Plant-Based Food and Beverages Market
Plant Based Food
South America Pea Protein Market
Plant Based Food
Vegan Noodles Market
Plant Based Food
Plant Based Meat Market