
 Nonlinear Optical Crystals Market | 2026-2036
Nonlinear Optical Crystals Market Size, Share, and Industry Trends Forecast 2026-2036
Nonlinear Optical Crystals Market Outlook
High-purity beta barium borate specifications is reorganizing procurement priorities across laser system manufacturers. Eksma Optics leverages Baltic-region polishing expertise to dominate frequency-doubling crystal supply. Cristal Laser SA anchors French defense and research laboratory contracts through sustained melt-growth capacity. Coherent Inc controls vertical integration from raw material sourcing to finished harmonic generators.
Nonlinear optical crystals are inorganic single-crystal materials engineered with non-centrosymmetric lattice structures that generate second-harmonic or sum-frequency radiation under intense coherent light, typically grown by Czochralski or flux methods with phase-matching angles calibrated to specific pump wavelengths. Their primary purpose is enabling wavelength conversion, optical parametric oscillation, and electro-optic modulation across industrial laser systems and telecommunications hardware. Lithium niobate wafers command the largest revenue pool due to matured telecom modulator demand, while potassium titanyl phosphate segments grow fastest in medical device applications requiring compact green and blue surgical lasers. Barium borate crystals retain structural importance in research laboratory settings where broad transparency windows from ultraviolet to near-infrared support tunable spectroscopy platforms.
REACH substance restrictions in Europe and FDA laser product performance standards in the United States jointly constrain crystal dopant chemistries and finished device safety certifications. China's SAMR enforces GB standards on optical material traceability that affect export market access for foreign suppliers. Stakeholders must monitor evolving dual-use export control classifications that could restrict defense-linked crystal shipments without warning.
Market Dynamics
Telecommunications infrastructure deployment is compressing specification cycles for frequency conversion crystals, forcing manufacturers to synchronize melt-growth capacity expansion with 5G backhaul wavelength requirements. China's MIIT certification tightening is simultaneously elevating material purity barriers and consolidating qualified supplier pools.
Growth Catalysts
- 5G optical backhaul expansion:Dense wavelength-division multiplexing deployments in Germany's precision optics cluster around Jena and Munich are pulling potassium titanyl phosphate volume for compact green laser sources.
- REACH substance streamlining:ECHA's consolidated candidate list review is accelerating substitution toward barium borate formulations with cleaner dopant profiles in European research laboratory procurement.
- Medical device miniaturization:Compact surgical laser demand in ophthalmology and dermatology is concentrating potassium titanyl phosphate orders from device OEMs seeking reduced thermal load in handheld units.
Market Restraints
- Rare-earth dopant cost volatility:Neodymium and ytterbium oxide spot pricing swings in Chinese spot markets transmit directly to lithium niobate wafer cost structures, compressing modulator manufacturer margins.
- Flux-growth capacity concentration:High-quality beta barium borate production clusters in Baltic-region polishing facilities, creating single-source vulnerability for frequency-doubling crystal supply security.
- Phase-matching angle precision limits:Current Czochralski pull rates constrain yield at sub-arcminute angular tolerance, throttling output for ultraviolet spectroscopy platform builders.
Strategic Opportunities
- Defense-linked dual-use diversification:Electro-optic modulator demand from directed-energy research programs offers premium pricing escape from telecom commoditization pressure.
- India PLI scheme alignment:Domestic value-addition requirements for optical component imports are creating joint-venture openings for melt-growth technology transfer to Indian precision manufacturing zones.
- Quantum key distribution hardware:Spontaneous parametric down-conversion source requirements for quantum cryptography systems represent emerging volume potential outside traditional laser markets.
Industry Challenges
- Czochralski pull-rate engineering talent scarcity:Experienced crystal growers capable of maintaining stoichiometric control across 150mm lithium niobate boules command premium compensation and limited geographic mobility.
- GB standards compliance timeline compression:China's SAMR traceability documentation requirements for optical material exports are extending pre-shipment certification cycles by 8-12 weeks for non-domestic suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonlinear Optical Crystals Market |
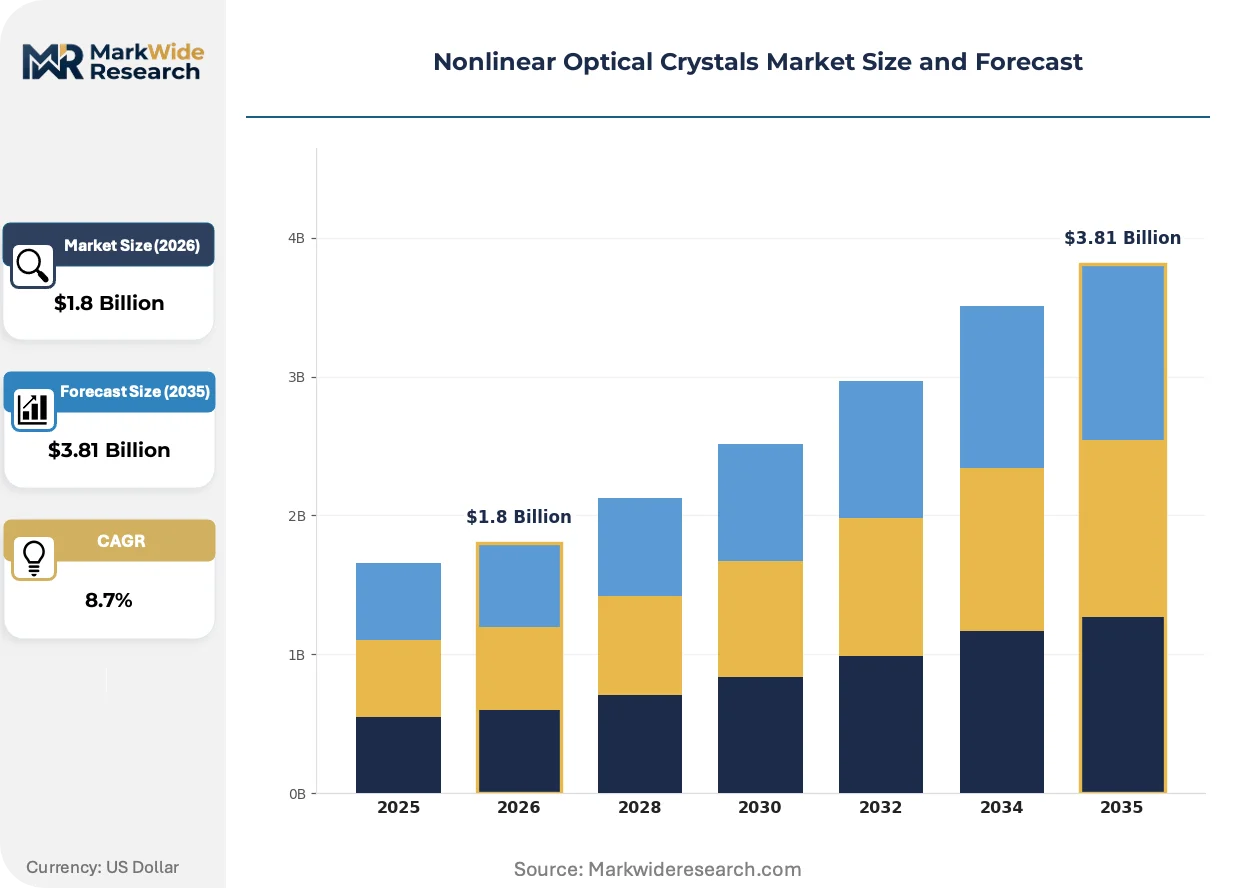
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barium Borate, Potassium Titanyl Phosphate, Lithium Niobate, Beta Barium Borate End User: Telecommunications, Defense, Research Laboratories, Medical Devices Application: Laser systems, Frequency conversion, Signal processing, Optical communications Technology: Generation, Modulation, Detection, Signal amplification |
| Companies Covered | HC Photonics Corp, Eksma Optics, Castech Inc, Inrad Optics Inc, Cristal Laser SA, Gooch & Housego PLC, Newlight Photonics Inc, Raicol Crystals Ltd, Coherent Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonlinear Optical Crystals Market Strategic Shifts
Nonlinear optical crystal manufacturing is bifurcating between commodity telecom modulator supply and precision defense-research customization, with process technology divergence accelerating. This split is reconfiguring equipment investment priorities and technical staffing models across the supplier base.
Periodically-poled lithium niobate is decomposing the traditional bulk crystal paradigm for telecom wavelength conversion by enabling quasi-phase-matching without critical angle alignment. Major modulator OEMs in Germany and Japan are transitioning 40% of new designs to periodically-poled architectures within 24-month procurement cycles. This technology is decomposing established flux-growth supply relationships as poling electrode fabrication displaces raw crystal volume in bill-of-materials economics.
REACH substance restrictions in Europe are eliminating cadmium-based dopant chemistries from electro-optic crystal formulations by 2027, forcing reformulation of legacy Q-switch devices. ECHA's restriction roadmap is compressing R&D timelines for magnesium-oxide-doped alternatives in Pockels cell applications. Medical laser manufacturers in France and Switzerland are accelerating qualification of reformulated crystals ahead of enforcement windows to maintain CE marking continuity.
Certification-driven supplier consolidation is compressing approved vendor lists among telecom infrastructure deployers, with MIIT and GB standards compliance becoming non-negotiable screening criteria. Equipment procurement teams at Chinese state-owned carriers are reducing qualified crystal sources from twelve to four vendors over 18-month qualification cycles. This concentration is most visible in Shanghai and Shenzhen equipment integration facilities, where traceability documentation now precedes technical evaluation in vendor scoring rubrics.
Nonlinear Optical Crystals Market Segmentation
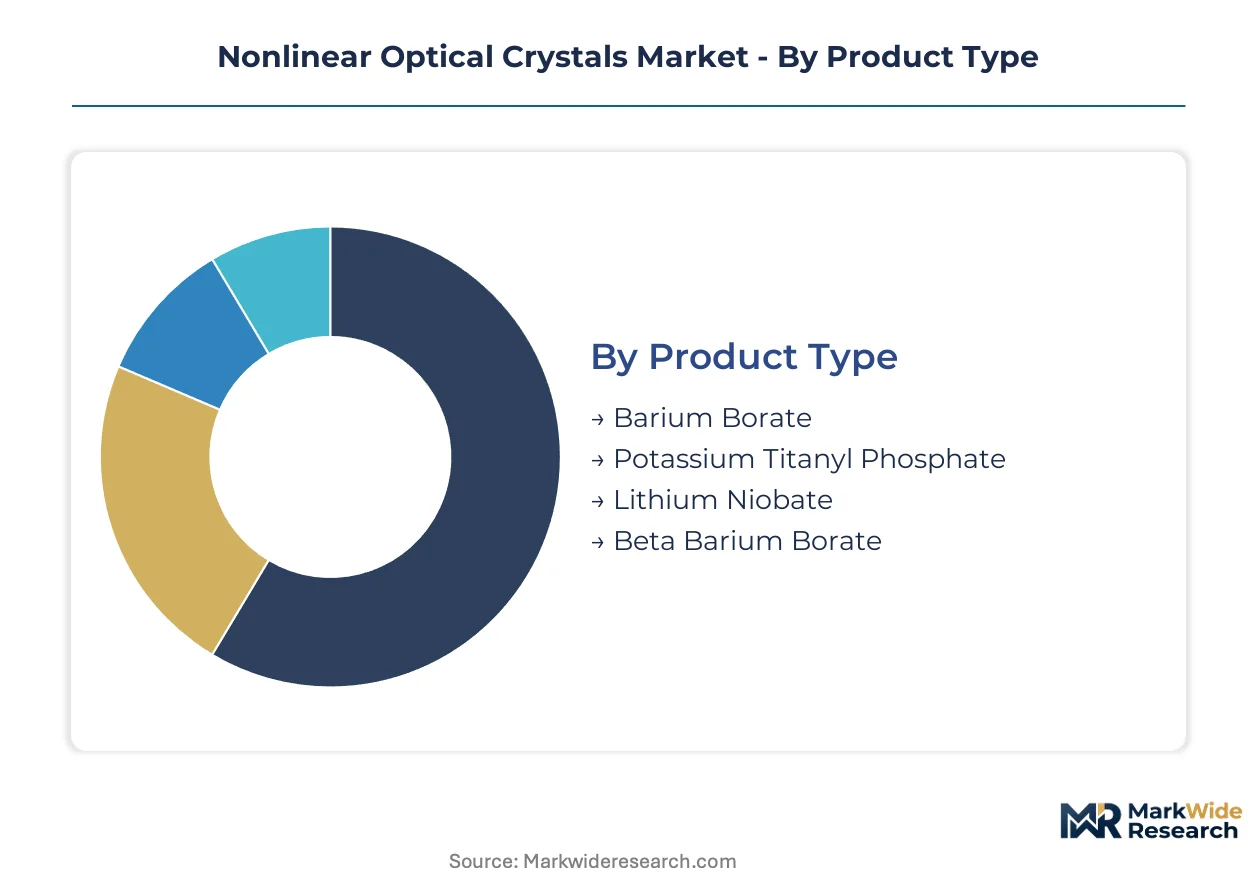
Nonlinear optical crystals demand fragments across incompatible purity grades and phase-matching specifications. Procurement teams segment supply pools by regulatory compliance tier rather than technical performance alone.
Product Type:
REACH substance restrictions and FDA laser product standards enforce divergent dopant chemistry requirements across each crystal family.
- Lithium Niobate:Perovskite-structured ferroelectric crystals grown by Czochralski pulling dominate telecom electro-optic modulator volumes. Dense wavelength-division multiplexing deployments in Germany's precision optics cluster around Jena and Munich pull 150mm wafer specifications with magnesium oxide doping for reduced photorefractive damage. China's MIIT certification tightening is elevating material purity barriers for import qualification.
- Potassium Titanyl Phosphate:Orthorhombic biaxial crystals with high nonlinear optical coefficients serve compact green and blue surgical laser sources. Medical device miniaturization in ophthalmology and dermatology concentrates orders from device OEMs seeking reduced thermal load in handheld units. Flux-growth capacity for this segment clusters in Baltic-region polishing facilities.
- Barium Borate:UV-transparent uniaxial crystals support tunable spectroscopy platforms with broad transparency windows. Research laboratory procurement in France and Switzerland favors these formulations for legacy Q-switch device compatibility.
- Beta Barium Borate:High-damage-threshold crystals enable frequency-doubling applications with superior thermal stability. ECHA's consolidated candidate list review accelerates substitution toward cleaner dopant profiles in European defense-research contracts.
Lithium Niobate handles the majority of throughput; Potassium Titanyl Phosphate is expanding most quickly on share.
End User:
Customer procurement authority concentrates in defense-linked dual-use programs and state-owned carrier equipment integration facilities.
- Telecommunications:5G optical backhaul expansion compresses specification cycles for frequency conversion crystals. Equipment procurement teams at Chinese state-owned carriers reduce qualified crystal sources through traceability documentation requirements that precede technical evaluation.
- Defense:Directed-energy research programs offer premium pricing escape from telecom commoditization pressure. Dual-use export control classifications restrict crystal shipments without warning, forcing qualified vendor list maintenance.
- Research Laboratories:Broad transparency windows from ultraviolet to near-infrared support tunable spectroscopy platforms. Barium borate formulations retain structural importance where REACH substance streamlining accelerates substitution.
- Medical Devices:Compact surgical laser demand concentrates potassium titanyl phosphate orders from device OEMs. CE marking continuity requires accelerated qualification of reformulated crystals ahead of ECHA enforcement windows.
Telecommunications commands the largest procurement volume; Medical Devices is gaining share fastest through miniaturization requirements.
Application:
Process technology divergence between commodity supply and precision customization reconfigures equipment investment priorities across each application.
- Laser Systems:Industrial cutting and welding platforms require Czochralski pull-rate engineering for stoichiometric control across large boules. Experienced crystal growers command premium compensation and limited geographic mobility.
- Frequency Conversion:Second-harmonic generation and sum-frequency mixing depend on phase-matching angle precision. Sub-arcminute angular tolerance constraints throttle output for ultraviolet spectroscopy platform builders.
- Signal Processing:Electro-optic modulation in telecom hardware transitions toward periodically-poled architectures. Poling electrode fabrication displaces raw crystal volume in bill-of-materials economics.
- Optical Communications:Dense wavelength-division multiplexing deployments synchronize melt-growth capacity expansion with 5G backhaul wavelength requirements. China's GB standards compliance timeline compression extends pre-shipment certification cycles.
Laser Systems anchors established revenue; Signal Processing is climbing the fastest as periodically-poled technology matures.
Technology:
Functional layer separation in crystal-based systems determines integration depth and margin capture.
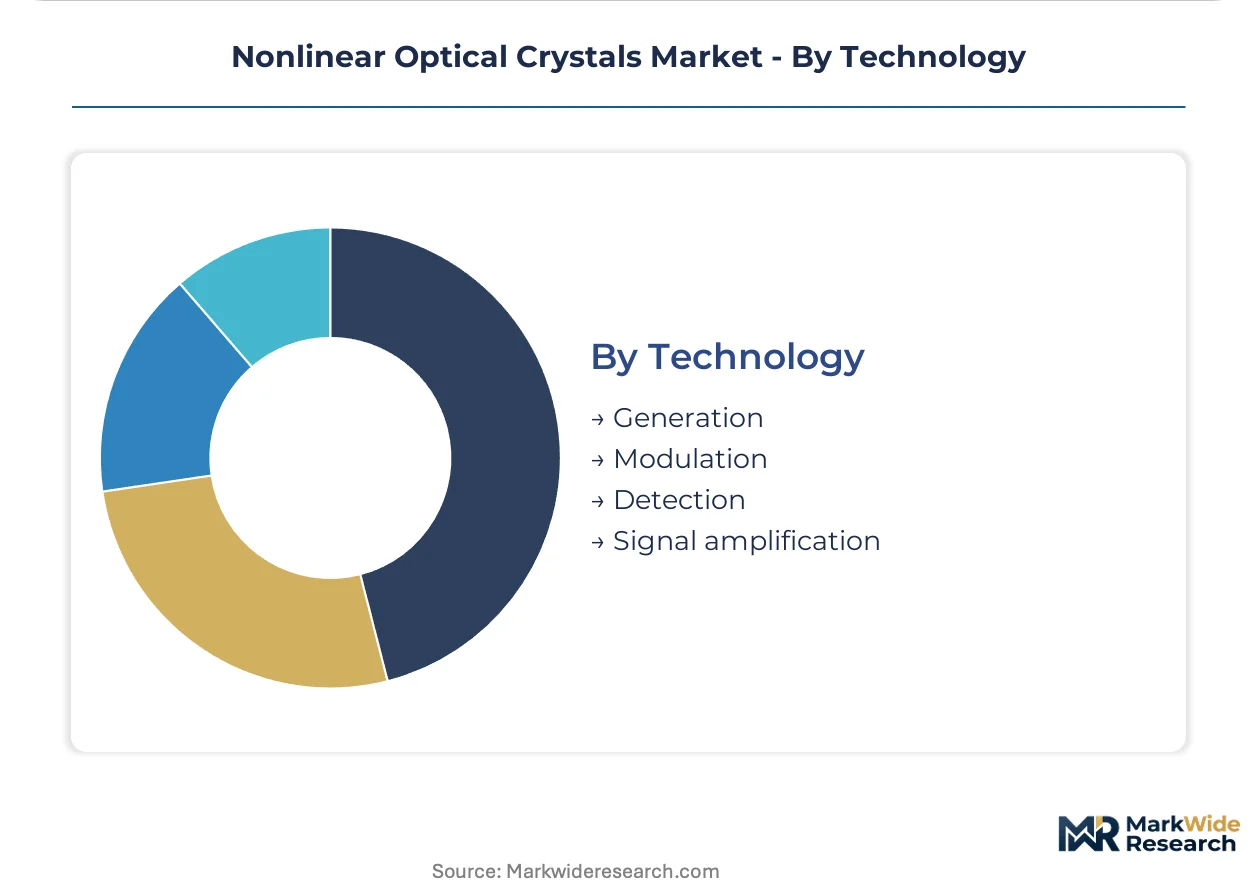
- Generation:Spontaneous parametric down-conversion sources for quantum cryptography systems represent emerging volume potential outside traditional laser markets.
- Modulation:Pockels cells and electro-optic modulators face cadmium-based dopant chemistry elimination by ECHA restriction roadmap. Magnesium-oxide-doped alternatives require compressed R&D timelines.
- Detection:Nonlinear optical crystal-based sensors serve metrology and scientific instrumentation with specialized phase-matching requirements.
- Signal Amplification:Optical parametric amplification systems demand high-purity beta barium borate specifications that reorganize procurement priorities.
Modulation captures the dominant technology investment; Generation shows the steepest expansion trajectory through quantum key distribution hardware demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese crystal manufacturers export frequency-doubling substrates to German precision optics clusters and US defense contractors, creating a three-way trade corridor shaped by divergent certification regimes. Material purity specifications from MIIT and FDA pull suppliers toward incompatible process standards. Regional procurement authority concentrates where telecommunications infrastructure deployment intersects with research laboratory funding.
China
SAMR enforces GB standards on optical material traceability that extend pre-shipment certification cycles by 8-12 weeks for export-bound lithium niobate wafers. MIIT tightening of optical component certification is consolidating qualified supplier pools from twelve to four vendors at state-owned carrier procurement desks. Shanghai and Shenzhen equipment integration facilities now prioritize traceability documentation over technical evaluation in vendor scoring rubrics.
Germany
Dense wavelength-division multiplexing deployments in the precision optics cluster around Jena and Munich pull potassium titanyl phosphate volume for compact green laser sources. ECHA's consolidated candidate list review accelerates substitution toward barium borate formulations with cleaner dopant profiles in research laboratory procurement. The country's national precision manufacturing regulator maintains strict CE marking continuity requirements for medical laser crystal imports.
United States
FDA laser product performance standards constrain crystal dopant chemistries and finished device safety certifications for surgical laser OEMs. Defense-linked directed-energy research programs offer premium pricing escape from telecom commoditization pressure for qualified suppliers. Dual-use export control classifications from the Department of Commerce restrict crystal shipments without warning, forcing vendor list maintenance.
Japan
METI standards for optical component quality anchor procurement specifications for telecom modulator manufacturers transitioning to periodically-poled architectures. Major modulator OEMs are shifting 40% of new designs to quasi-phase-matching configurations within compressed 24-month procurement cycles. The Kanto region hosts poling electrode fabrication facilities that displace raw crystal volume in bill-of-materials economics.
France
ANSM and ECHA joint enforcement of REACH substance restrictions eliminates cadmium-based dopant chemistries from electro-optic crystal formulations by 2027. Medical laser manufacturers in the Île-de-France cluster accelerate qualification of magnesium-oxide-doped alternatives ahead of enforcement windows. Cristal Laser SA anchors defense and research laboratory contracts through sustained melt-growth capacity near the Swiss border.
Nonlinear Optical Crystals Market Competitive Environment
Listed leaders compete with private specialists across melt-growth capacity and polishing expertise. The vendor base organizes into three tiers: vertically integrated modulator OEMs with captive crystal supply, Baltic-region polishing specialists dominating frequency-doubling substrates, and research-laboratory contract holders with sustained flux-growth operations. Consolidation pressure concentrates among telecom infrastructure suppliers facing MIIT certification barriers, while defense-research customization preserves fragmentation. Dominant competitive moves include backward integration into raw material sourcing and joint-venture technology transfer to Indian manufacturing zones under PLI scheme alignment.
Among Baltic-region polishing specialists, Eksma Optics exemplifies the frequency-doubling crystal supply archetype. Cristal Laser SA and Coherent Inc occupy positions spanning research-laboratory contract holding and vertical integration from material sourcing through finished harmonic generators. These three company structures illustrate the market's bifurcation between commodity telecom supply and precision defense-research customization.
| Leading Market Players |
|---|
| HC Photonics Corp |
| Eksma Optics |
| Castech Inc |
| Inrad Optics Inc |
| Cristal Laser SA |
| Gooch & Housego PLC |
| Newlight Photonics Inc |
| Raicol Crystals Ltd |
| Coherent Inc |
| Others |
Value Chain & Pricing Dynamics
Periodically-poled lithium niobate substitution for bulk flux-grown crystals is simultaneously shifting poling electrode fabrication toward Japan's Kanto region and collapsing raw crystal volume premiums in legacy Czochralski supply chains. This displacement dynamic concentrates margin capture with electrode patterning specialists while commoditizing unprocessed boule suppliers.
Pricing Analysis
The technology-generation pricing gap separates legacy bulk-crystal contracts from periodically-poled premium tiers and emerging quantum-source prototypes. Three-tier pricing structure across premium defense-research specifications, standard telecom modulator grades, and economy-level industrial laser feedstocks prevails, with certification level and volume scale as primary price differentiation drivers. Cost compression in standard-grade lithium niobate intensifies because Chinese state-owned carriers consolidated qualified vendor pools. Medical device OEMs exhibit highest price sensitivity due to handheld miniaturization cost targets, while directed-energy research programs show lowest sensitivity.
Supply Chain Analysis
Strategic stockpile preferences dominate defense-linked procurement, contrasting with just-in-time pressures from telecom infrastructure deployers facing compressed specification cycles. Raw material supply concentrates in China for rare-earth oxide precursors, Lithuania and Latvia for polishing expertise, and Japan for poling electrode fabrication. Neodymium and ytterbium oxide feedstocks, high-purity crucible materials, and precision lapping compounds constitute critical input dependencies. Single-source vulnerability in Baltic-region beta barium borate polishing capacity threatens frequency-doubling crystal security. Distribution runs through qualified vendor list relationships rather than spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating toward Chinese state-owned carriers and German precision optics clusters, with vendor consolidation from twelve to four qualified sources at major procurement desks shifting negotiation leverage decisively.
For Market Incumbents: Shield melt-growth capacity investments through MIIT certification pre-qualification before competitor qualification windows close. Deepen backward integration into rare-earth oxide sourcing to dampen Chinese spot market volatility transmission. Capture defense-research premium pricing through sustained flux-growth capability as telecom volumes commoditize.
For New Entrants and Emerging Players: Anchor in India's PLI scheme alignment zones for domestic value-addition requirements creating joint-venture technology transfer openings. Target quantum key distribution hardware spontaneous parametric down-conversion sources as the most penetrable emerging volume segment outside traditional laser markets. Pursue poling electrode fabrication partnerships with Japanese modulator OEMs transitioning 40% of designs to quasi-phase-matching architectures.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with Baltic-region polishing specialists holding irreplaceable frequency-doubling expertise but limited geographic diversification. Five-to-ten year viability hinges on successfully navigating periodically-poled technology displacement while capturing defense customization premiums. Watch ECHA enforcement timeline compression for cadmium-based dopant elimination as the signal indicating reformulation R&D investment inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Oxide Sourcing | Neodymium and ytterbium spot price volatility directly transmits to lithium niobate wafer cost structures. |
| MIIT Certification Pre-Qualification Investment | Chinese state-owned carrier vendor consolidation from twelve to four sources creates qualification barriers. |
| Periodically-Poled Architecture Transition | Japanese modulator OEMs shift 40% of new designs toward poling electrode fabrication displacing raw crystal volume. |
| Defense-Research Contract Diversification | Directed-energy programs offer premium pricing escape from telecom commoditization pressure. |
| India PLI Scheme Joint Venture Formation | Domestic value-addition requirements for optical component imports enable melt-growth technology transfer. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with crystal growth engineers, telecom equipment procurement managers, defense program contracting officers, and medical device OEM supply chain directors; and secondary validation through SEC filings of listed optical component manufacturers, ECHA restriction roadmap documentation, MIIT certification bulletins, and customs trade data for lithium niobate wafer shipments. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates.
Across the projection horizon, the analytical framework modeled crystal type, end-user industry, application function, and technology generation as core segmentation dimensions. CAGRs derived from melt-growth capacity expansion curves synchronized with 5G backhaul wavelength deployment schedules and medical device miniaturization adoption curves. Forecast inputs incorporated phase-matching angle precision yield rates and periodically-poled technology penetration assumptions.
Material uncertainties — dual-use export control reclassification, ECHA enforcement timeline acceleration, and rare-earth oxide spot market dislocations — sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline stability and technology substitution elasticity. Revision becomes warranted when periodically-poled architecture adoption crosses threshold penetration in telecom modulator designs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
US Lithium Niobate Modulator Market
Optical Components
Silicon Photonics Wafer Market
Optical Components
Planar Lightwave Circuit Splitter Market
Optical Components
Optical Sensor Market
Optical Components
Global Fiber Bragg Grating Amplifier Market
Optical Components
Faraday Rotator Market
Optical Components
Global Optical Network Hardware Market
Optical Components
Picosecond and Femtosecond Fiber Lasers Market
Optical Components
Mexico Extreme Ultraviolet Lithography (EUVL) Systems Market
Optical Components
Optical Fiber and Plastic Conduit Market
Optical Components
Japan Lithium Niobate Modulator Market
Optical Components
Electro Optical System Market
Optical Components
Digital Optical Transmitter Market
Optical Components
Optical Transceiver Market
Optical Components
Asia Pacific Optical Sensors Market
Optical Components
Bio-Optics Market