
 Cold Form Foil Market | 2026-2036
Cold Form Foil Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Form Foil Market Analysis
The cold form foil market is restructuring around a widening split between premium pharmaceutical-grade barrier films and commodity food-service wraps. Amcor leverages vertical integration across aluminum sourcing and lamination to sustain margin control in high-barrier pharmaceutical applications. Constantia Flexibles anchors European supply through specialized cold-forming lines certified for EMA compliance. UFlex competes on cost-engineered composites for emerging-market generics producers.
Cold form foil denotes a multilayer laminated structure—typically aluminum core with polyamide and PVC layers totaling 150–250 micrometers—engineered for zero-light, zero-moisture barrier protection in unit-dose packaging. Blister packs dominate pharmaceutical use cases where child-resistance and senior-compliance features determine regulatory acceptance. Composite materials are displacing pure aluminum in nutraceutical stick packs as brands seek source-reduction credentials without sacrificing shelf stability. Aluminum still leads margin pools in oncology and hormone therapies where EMA Annex I barrier requirements exclude polymer alternatives.
FDA 21 CFR 177.1390 and EMA Annex I govern laminate composition for direct drug contact, while EU REACH restrictions on phthalate plasticizers force reformulation of PVC-containing structures. Germany's national packaging regulator enforces extended producer responsibility fees that favor recyclable composite designs over traditional aluminum-PVC constructions. Stakeholders must monitor evolving monograph harmonization between FDA and EMA as divergence in extractables testing protocols threatens to fragment qualification costs for global pharmaceutical clients.
Market Dynamics
EMA Annex I barrier standards and FDA 21 CFR 177.1390 laminate specifications are forcing simultaneous reformulation of PVC-containing structures and qualification of zero-moisture alternatives, compressing product development cycles across pharmaceutical packaging supply chains.
Growth Catalysts
- Chronic Disease Prevalence:Rising oncology and hormone therapy patient volumes in Germany and the United States are expanding unit-dose blister pack requirements that specify aluminum-core laminates for light and moisture exclusion.
- REACH Phthalate Restrictions:ECHA's tightening limits on plasticizer content in pharmaceutical contact materials are accelerating migration toward polyamide-reinforced composite structures certified for EU market access.
- Extended Producer Responsibility:Germany's national packaging regulator fees for aluminum-PVC constructions are redirecting R&D investment toward recyclable multilayer designs that maintain barrier performance.
Market Restraints
- Aluminum Price Volatility:Raw material fluctuations in primary aluminum ingot markets transmit directly to laminate cost structures, squeezing margin pools for non-integrated converters serving generic drug producers.
- Supply Concentration Risk:Cold-forming line capacity clusters disproportionately in southern Germany, creating geographic vulnerability to energy cost shocks and logistics disruptions affecting just-in-time pharmaceutical supply chains.
- Polymer Substitution Ceiling:EMA Annex I barrier requirements for oncology and hormone therapies exclude full polymer alternatives, capping addressable market expansion for source-reduction composites in highest-value therapeutic categories.
Strategic Opportunities
- Indian Generic Pharma Expansion:CDSCO regulatory alignment with ICH guidelines is opening qualification pathways for export-oriented cold form foil suppliers to capture volume in rapidly scaling active pharmaceutical ingredient manufacturing clusters.
- Nutraceutical Stick Packs:Wellness brands seeking shelf stability without aluminum-heavy credentials are piloting composite laminates in single-serve format trials across North American direct-to-consumer channels.
- EU Green Deal Packaging Mandates:Circular economy action plan targets for 2030 recyclability are incentivizing pilot production of delaminable structures that separate aluminum and polymer fractions at end-of-life.
Industry Challenges
- Extractables Testing Divergence:FDA and EMA protocol misalignment on laminate qualification timelines forces redundant analytical work, extending new product introduction cycles by 8-14 months for global pharmaceutical clients.
- Specialized Lamination Engineering:Scarcity of technicians trained in 150-250 micrometer multilayer calibration and zero-defect sealing for child-resistant formats limits production line expansion regardless of capital availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Form Foil Market |
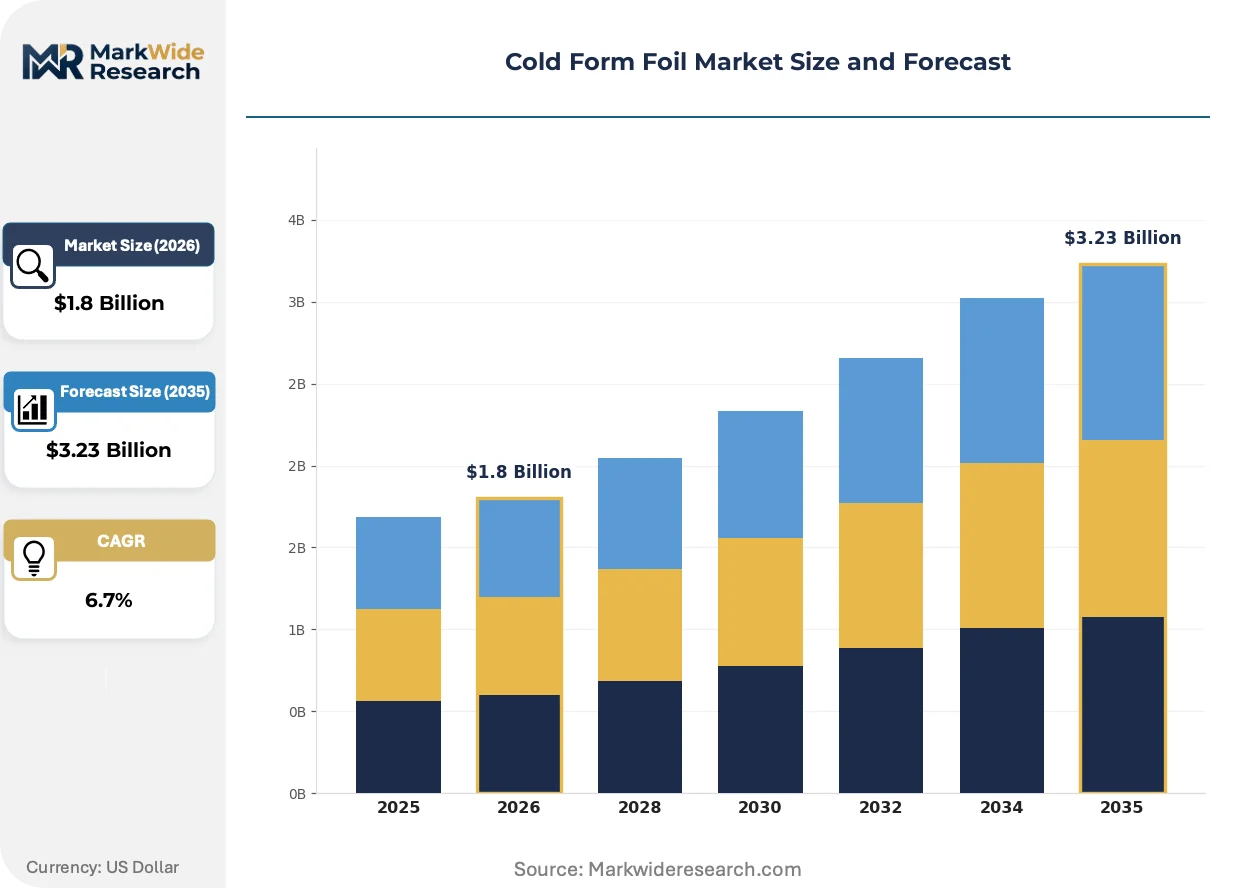
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Stick Packs, Pouches, Wraps Material: Aluminum, Plastic, Composite, Paper Use Case: Pharmaceuticals, Nutraceuticals, Personal Care, Food End User: Manufacturers, Retailers, Distributors, Consumers |
| Companies Covered | Amcor, Constantia Flexibles, UFlex, Winpak, Tekni-Plex, Huhtamaki, Essentra, Sonoco Products Company, Carcano, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Form Foil Market Emerging Trajectories
Active barrier material science and regulatory chemistry requirements are restructuring how laminates are formulated, qualified, and specified across pharmaceutical and adjacent packaging segments.
Polyamide-aluminum-PVC trilaminate construction is converging with high-barrier oxide-coated polymer films in pilot nutraceutical applications. Mid-tier wellness brands in the United States are testing these hybrid structures for moisture-sensitive probiotic formats. The convergence is compressing traditional aluminum thickness requirements while preserving shelf stability claims.
EU REACH restrictions on phthalate plasticizers are forcing systematic PVC layer reformulation across European pharmaceutical supply chains. Compounders are accelerating non-phthalate plasticizer adoption despite higher raw material costs and requalification burdens. German generics producers are absorbing these cost increments to maintain EMA compliance and avoid supply disruption.
Specification-driven procurement now dominates cold form foil purchasing for oncology and hormone therapy packaging. Pharmaceutical quality teams are consolidating supplier pools around converters with in-house extractables libraries and pre-qualified laminate constructions. This concentration is most visible in German and Swiss manufacturing clusters where EMA Annex I compliance documentation carries premium weight in contract awards.
Cold Form Foil Market Segmentation
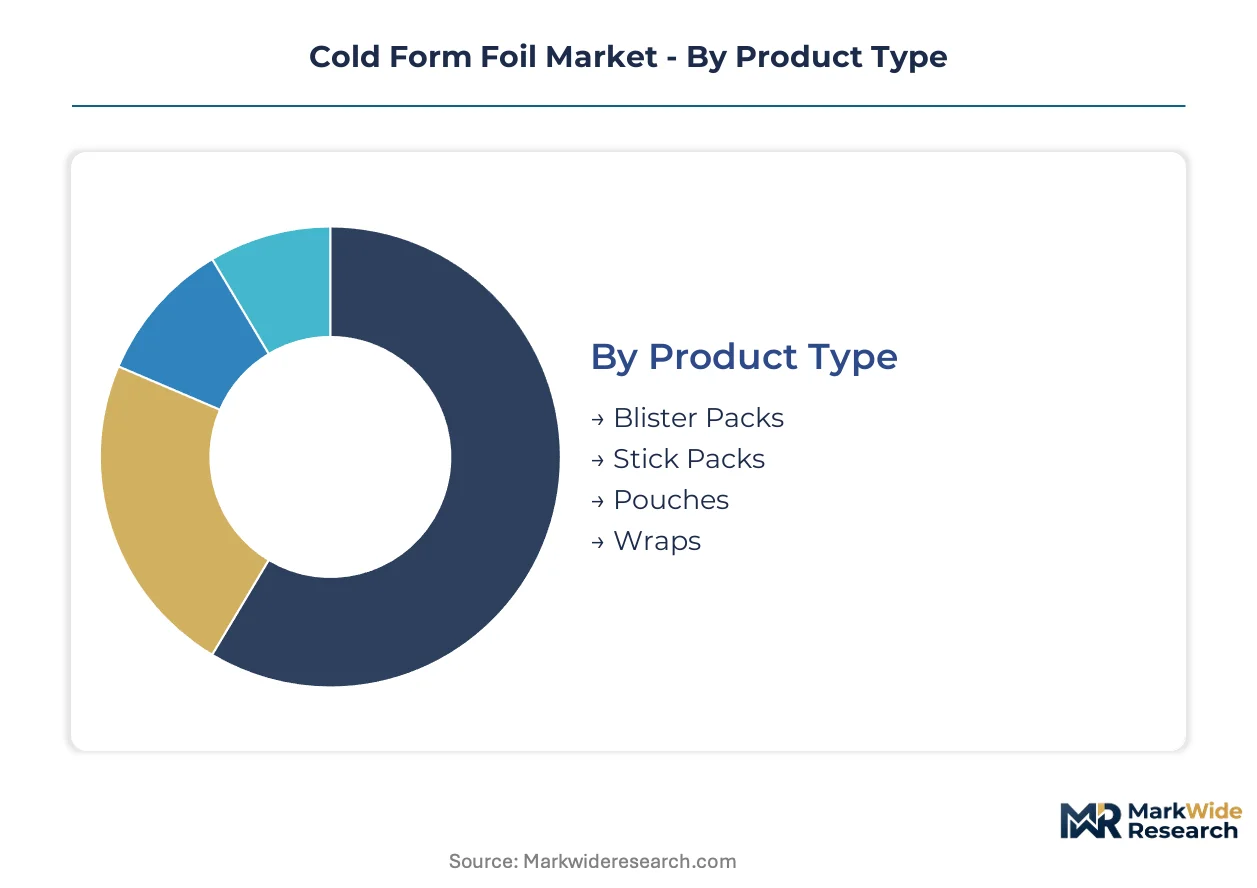
Cold form foil specifications diver sharply across therapeutic categories and regulatory jurisdictions, forcing converters to maintain parallel qualification tracks for pharmaceutical-grade versus food-service applications. Segmentation discipline separates margin pools: oncology blister packs command premium pricing against commodity nutraceutical wraps.
Product Type:
Packaging format selection tracks directly with barrier performance requirements and automated filling line compatibility, creating distinct upgrade cycles across pharmaceutical and consumer wellness segments.
- Blister Packs:Unit-dose aluminum-polyamide-PVC laminates engineered for zero-light, zero-moisture protection dominate oncology and hormone therapy applications. German and Swiss pharmaceutical manufacturers specify these formats for EMA Annex I compliance, with child-resistant push-through designs requiring 150-250 micrometer calibrations and validated heat-seal windows.
- Stick Packs:Narrow-format single-serve sachets are gaining traction in North American nutraceutical channels where wellness brands pilot composite laminates for probiotic and powder formulations. These structures trade absolute barrier performance for source-reduction credentials and improved recyclability profiles.
- Pouches:Multi-dose flexible formats serve veterinary pharmaceutical and diagnostic kit applications requiring resealability.
- Wraps:Sheet-fed laminates address specialty food-service and medical device sterile barrier needs with lower regulatory qualification burdens.
Blister packs sit at the top of the volume ranking, with stick packs climbing the fastest.
Material:
Raw material selection determines regulatory pathway, end-of-life handling, and margin structure across pharmaceutical and adjacent packaging segments.
- Aluminum:Primary metal cores deliver definitive barrier performance for moisture-sensitive and light-degradable APIs. FDA 21 CFR 177.1390 and EMA Annex I standards explicitly favor aluminum-containing laminates for high-value therapeutic categories where polymer alternatives fail qualification protocols.
- Composite:Engineered multilayers combining aluminum with oxide-coated polymers or bio-based films are displacing pure metal constructions in mid-tier nutraceutical and personal care applications. These structures respond to EU Green Deal circular economy mandates and Germany's extended producer responsibility fee structures.
- Plastic:High-barrier polymer films serve cost-sensitive generic pharmaceutical markets and food-contact applications where regulatory barriers permit.
- Paper:Fiber-based substrates with functional coatings occupy niche sustainable packaging trials for low-moisture nutraceutical formats.
Aluminum captures the dominant revenue share, while composite materials gain share fastest among reformulation investments.
Use Case:
End-use application dictates barrier specification, extractables testing protocol, and supplier qualification depth across divergent regulatory environments.
- Pharmaceuticals:Prescription drug packaging commands the most stringent laminate requirements, with FDA and EMA extractables protocols forcing dedicated production lines and analytical libraries. Oncology and hormone therapies exclude full polymer alternatives per EMA Annex I, cementing aluminum-core dominance.
- Nutraceuticals:Dietary supplement and wellness product packaging operates under FSSAI and FDA food-contact rules with lower barrier burdens, enabling composite material experimentation and faster supplier switching.
- Personal Care:Cosmetic and hygiene product laminates prioritize aesthetic finishing and tamper evidence over pharmaceutical-grade barrier metrics.
- Food:Moisture-sensitive confectionery and ingredient packaging applies modified atmosphere and oxygen barrier specifications distinct from pharmaceutical protocols.
Pharmaceuticals anchor absolute volume, with nutraceuticals expanding most quickly as wellness brand proliferation drives format experimentation.
End User:
Procurement authority and technical specification control vary sharply across the value chain, with pharmaceutical quality teams consolidating supplier pools around pre-qualified converters.
- Manufacturers:Pharmaceutical and nutraceutical producers hold primary specification authority, with CDSCO-aligned Indian generic houses and FDA-regulated US innovators driving divergent qualification timelines. These entities increasingly require in-house extractables libraries and EMA Annex I documentation packages.
- Retailers:Pharmacy chains and wellness distributors influence secondary packaging decisions, particularly for private-label nutraceutical lines where shelf presence and recyclability claims drive material selection.
- Distributors:Wholesale pharmaceutical and medical supply intermediaries manage inventory and logistics specifications without direct laminate engineering input.
- Consumers:End-patient compliance preferences—child resistance, senior accessibility, portability—feedback into format design through pharmaceutical brand owner research.
Manufacturers command the specification process, with retailers gaining influence fastest through sustainability-driven private-label expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the highest cold form foil specification density in Europe, while India scales export-oriented capacity fastest among emerging pharmaceutical manufacturing hubs. Regulatory divergence between FDA and EMA extractables protocols fragments qualification timelines for converters serving both markets.
Germany
Oncology and hormone therapy blister pack demand from Bayer and Merck KGaA drives premium laminate consumption. The national packaging regulator enforces extended producer responsibility fees that redirect investment toward recyclable composite designs. Production clusters concentrate in Bavaria and Baden-Württemberg where Constantia Flexibles and Huhtamaki operate specialized cold-forming lines certified for EMA Annex I compliance.
United States
Chronic disease patient volumes and generic pharmaceutical manufacturing expansion sustain unit-dose packaging requirements. FDA 21 CFR 177.1390 laminate specifications govern direct drug contact materials with strict extractables testing protocols. New Jersey and North Carolina host pharmaceutical packaging innovation corridors where converters maintain dedicated production lines for oncology applications.
India
CDSCO regulatory alignment with ICH guidelines accelerates export qualification for active pharmaceutical ingredient manufacturers. The PLI scheme for pharmaceuticals incentivizes domestic packaging material sourcing to reduce import dependence. Gujarat and Maharashtra industrial corridors attract cold form foil converters targeting European and North American generic drug export markets.
Switzerland
Specialty pharmaceutical and biologics packaging demands precision barrier performance for high-value therapeutics. Swissmedic enforces stringent laminate documentation requirements that favor converters with pre-qualified extractables libraries. Basel and Zurich regions anchor supply relationships with Roche and Novartis manufacturing networks requiring validated heat-seal specifications.
China
Domestic pharmaceutical production scale and nutraceutical export growth drive laminate consumption across multiple barrier tiers. NMPA pharmaceutical packaging regulations converge with international standards for export-oriented manufacturers. Yangtze River Delta pharmaceutical clusters in Jiangsu and Zhejiang provinces concentrate cold-forming capacity serving both regulated and semi-regulated Asian markets.
Cold Form Foil Market Vendor Landscape
Top-tier vendors anchor EMA-certified pharmaceutical supply chains, while mid-tier specialists compete on cost-engineered composites for nutraceutical and generic drug applications. The market structures around three strategic archetypes: integrated aluminum converters with captive lamination capacity, specialized flexible packaging houses with dedicated pharmaceutical lines, and regional composite material innovators targeting source-reduction credentials. Dominant competitive moves include backward integration into aluminum sourcing to control margin volatility and strategic partnerships with Indian generic pharmaceutical exporters to secure volume commitments.
Among European-based flexible packaging specialists, Constantia Flexibles and Huhtamaki occupy positions within the premium-tier pharmaceutical certification vector, while UFlex represents the cost-optimized composite archetype targeting emerging-market expansion. These three entities exemplify the geographic and strategic segmentation defining competitive positioning across regulated and semi-regulated pharmaceutical packaging corridors.
| Leading Market Players |
|---|
| Amcor |
| Constantia Flexibles |
| UFlex |
| Winpak |
| Tekni-Plex |
| Huhtamaki |
| Essentra |
| Sonoco Products Company |
| Carcano |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up flexible packaging specialists anchor cold form foil supply chains across Bavaria and Baden-Württemberg, concentrating pricing power among EMA-certified converters while compressing margins for non-integrated mid-tiers serving generic drug producers. This ownership pattern reinforces long-term contract discipline with Bayer and Merck KGaA while exposing spot-market buyers to aluminum ingot volatility transmission.
Pricing Analysis
Service bundling separates pharmaceutical-grade laminate suppliers from commodity converters. Three-tier pricing structure across EMA-certified premium, FDA-standard mid-tier, and emerging-market economy levels reflects extractables documentation depth and child-resistance validation. Price differentiation hinges on certification tier and volume commitment scale. Cost compression in the economy tier is intensifying because Indian generic houses leverage CDSCO-aligned export qualifications to negotiate supplier switching. Spot-market buyers exhibit highest price sensitivity; oncology packagers with validated heat-seal specifications show lowest.
Supply Chain Analysis
India's PLI scheme for pharmaceuticals is reshaping sourcing patterns by mandating domestic packaging material procurement for export-oriented API manufacturers. Raw material flows draw from German aluminum rolling mills, Chinese oxide-coated polymer film producers, and Indian PVC compounders. Supply chain risk centers on energy cost shocks affecting Bavarian cold-forming line clusters. Distribution runs through pharmaceutical contract packagers and direct-to-manufacturer laminate supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cold form foil market functions as a stable compounder anchored by chronic disease prevalence and regulatory barrier escalation that perpetually renews unit-dose packaging demand.
For Market Incumbents: Acquire extractables testing laboratories to internalize qualification timelines and defend against polymer substitution threats in nutraceutical adjacencies. Expand EMA Annex I pre-qualified laminate libraries to consolidate specification authority with Roche and Novartis procurement teams. Deepen backward integration into aluminum sourcing to buffer margin volatility from LME price swings.
For New Entrants and Emerging Players: Capture North American nutraceutical stick pack white space where wellness brands pilot composite laminates for probiotic shelf stability claims. Target CDSCO-aligned Indian generic exporters with cost-engineered multilayers qualified for European market access. Lead with source-reduction credentials and recyclability documentation to differentiate from aluminum-heavy incumbents.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier composite converters with nutraceutical customer concentration but limited pharmaceutical certification depth. Five-to-ten year viability rests on regulatory barrier persistence and chronic therapy volume expansion. Watch FDA-EMA extractables protocol harmonization progress as the critical inflection signal for qualification cost consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Annex I Certification Investment | Pre-qualifies laminates for oncology and hormone therapy contracts with Bayer and Merck KGaA. |
| Backward Integration into Aluminum Sourcing | Captive supply of primary metal cores insulates margin pools from LME volatility transmission. |
| Delaminable Structure Pilot Production | Separates aluminum and polymer fractions to satisfy EU Green Deal 2030 recyclability mandates. |
| CDSCO-Aligned Export Qualification | Opens volume pathways into Indian generic pharmaceutical manufacturing clusters under PLI incentives. |
| Extractables Testing Library Expansion | Accelerates new product introduction timelines for global clients facing FDA-EMA protocol divergence. |
Methodological Framework
Multiple input streams — primary interviews with pharmaceutical packaging procurement managers, regulatory affairs specialists, and flexible packaging plant engineers; secondary validation through FDA 21 CFR filings, EMA Annex I documentation databases, and customs trade flow records; plus SEC disclosure analysis of listed converters — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations probed specification authority shifts, laminate reformulation timelines, and qualification cost structures across German, Swiss, and North American manufacturing clusters.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include packaging format, material composition, therapeutic category, and regional regulatory cluster. CAGRs were derived from therapeutic volume growth trajectories, barrier specification escalation patterns, and substitution elasticity estimates for composite versus aluminum-core laminates. Forecast inputs incorporated REACH phthalate restriction implementation timelines and extended producer responsibility fee structures.
Aluminum price volatility, regulatory protocol divergence, and polymer substitution ceiling effects are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding EMA-FDA harmonization progress and chronic disease prevalence trends. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Transit Packaging Market
Packaging Materials
Myanmar Packaging Market
Packaging Materials
Cohesive Packaging Market
Packaging Materials
Tertiary Packaging Market
Packaging Materials
Metallized Rollstock Film Market
Packaging Materials
Anti-Scratch Film Market
Packaging Materials
Corrugated Wrap Around Market
Packaging Materials
Fiber Lids Market
Packaging Materials
Europe Airless Packaging Market
Packaging Materials
Tubes and Cores Market
Packaging Materials
Lid Laminates Market
Packaging Materials
Book Wraps Market
Packaging Materials
3D Printed Packaging Market
Packaging Materials
Paint Packaging Market
Packaging Materials
Laminated Tubes Market
Packaging Materials
Production Page Volume Market