
 Thermal Lamination Films Market | 2026-2036
Thermal Lamination Films Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Lamination Films Market Outlook
Asian biaxially oriented polypropylene (BOPP) film producers is repositioning capacity toward thermal lamination grades to capture premium packaging demand. COSMO Films leverages backward integration into resin compounding to control melt-index consistency across its thermal lamination portfolio. Drytac anchors its competitive stance through adhesive chemistry specialization for low-temperature thermal bonding on heat-sensitive substrates. GMP competes via geographic dominance in European print-finishing distribution channels.
Thermal lamination films are multilayer polymer constructions, typically 15–30 micron BOPP or polyester substrates pre-coated with ethylene-vinyl acetate or low-density polyethylene hot-melt adhesives, activated at 80–120°C to bond printed paper or board surfaces for protection and gloss enhancement. Glossy films dominate commercial print finishing due to established ink adhesion and visual impact, while matte films represent the fastest-growing product type as premium cosmetics and luxury goods brands reject high-reflectivity finishes. Polypropylene material types command the largest volume share given cost-positioning against polyester alternatives, though polyethylene formulations are gaining traction in flexible food packaging where moisture barrier requirements are less stringent.
FDA food-contact substance regulations and EU REACH restrictions on phthalate plasticizers constrain adhesive formulation choices for thermal lamination films serving food and beverage end users. China's SAMR enforces GB 4806 composite food-contact material standards that require migration testing for laminated structures, while Japan's METI promotes mono-material designs through its Plastic Resource Circulation Strategy to improve post-consumer recyclability. Stakeholders must monitor evolving extended producer responsibility schemes across major economies to anticipate material redesign investments and compliance cost shifts.
Market Dynamics
Converters across Southeast Asia are repositioning entire production lines toward thermal lamination grades as FMCG brands demand shelf-life extension without aluminum foil barriers. This capacity migration is compressing regional supply chains and forcing adhesive formulators to validate new ethylene-vinyl acetate chemistries under tightening food-contact protocols.
Growth Catalysts
- India's western industrial corridor:Mumbai-Pune packaging clusters serve domestic FMCG brands with expanding lamination capacity. Local converters benefit from proximity to polyethylene resin supply and established print-finishing infrastructure.
- Japan's METI Plastic Resource Circulation Strategy:Mono-material design mandates improve post-consumer recyclability of laminated flexible packaging. Brand owners accelerate adoption of single-substrate thermal films to preempt compliance deadlines.
- Low-temperature thermal bonding:Heat-sensitive substrate compatibility opens premium cosmetics and pharmaceutical leaflet applications. Drytac and specialty adhesive suppliers capture margin from temperature-critical bonding requirements.
Market Restraints
- Phthalate plasticizer restrictions:EU REACH constraints on adhesive formulations force reformulation cycles for food-contact thermal films. Migration testing costs burden mid-scale converters serving pan-European brand owners.
- Polypropylene resin concentration:BOPP substrate supply clusters in Middle East and Northeast Asian petrochemical corridors. Price volatility in propylene feedstock transmits directly to film converter margins.
- Polyethylene terephthalate substitution ceiling:Polyester thermal films retain premium print-finishing share despite polypropylene cost advantages. Gloss consistency and dimensional stability requirements constrain downgauging below 12-micron thresholds.
Strategic Opportunities
- Matte finish penetration:Premium cosmetics and luxury goods brands reject high-reflectivity surfaces. Thermal lamination suppliers capture value from anti-glare aesthetics in high-end packaging segments.
- China's GB 4806 composite standards:SAMR migration testing requirements for laminated structures create compliance service revenue streams. Third-party validation laboratories expand alongside film distribution networks.
- Digital print finishing integration:Short-run variable data printing converges with on-demand lamination workflows. Web-to-pack converters in North American and European markets reduce inventory carrying costs through synchronized finishing.
Industry Challenges
- Hot-melt adhesive formulation expertise:Ethylene-vinyl acetate and low-density polyethylene compounding requires specialized polymer science talent. Southeast Asian converters face recruitment gaps against semiconductor and battery material sectors.
- Extended producer responsibility scheme alignment:Divergent national recycling frameworks across EU member states complicate pan-European product specifications. Film producers must maintain multiple SKU variants for Germany's DSD, France's Citeo, and Italy's CONAI systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Lamination Films Market |
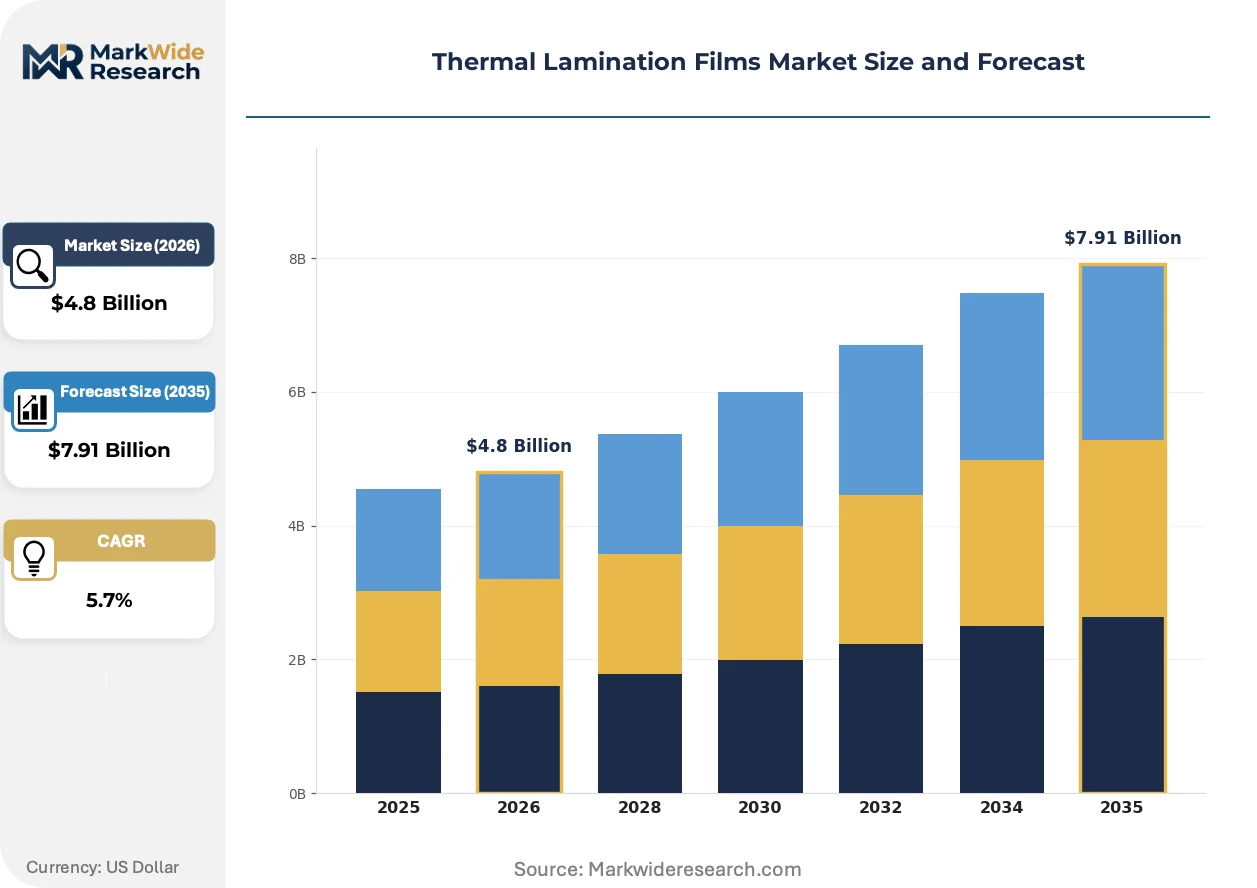
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glossy Films, Matte Films, Silk Films, Textured Films Application: Packaging, Labels, Stationery, Book Covers End User: Retail, Publishing, Food & Beverage, Electronics Material Type: Polypropylene, Polyester, Polyethylene, Others |
| Companies Covered | FlexFilm, GMP, COSMO Films, Ipak, Royal Sovereign, Transilwrap, Derprosa, Drytac, D&K, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Lamination Films Market Strategic Shifts
Active materials science and regulatory chemistry are compressing traditional substrate-adhesive boundaries in thermal lamination. Three developmental trajectories dominate investment priorities across formulation labs and converter equipment portfolios.
Co-extruded functional layers are unifying barrier, adhesive, and substrate functions within single-pass BOPP constructions. European flexible food packaging converters adopt these structures to eliminate separate coating steps. The technology is unifying previously discrete manufacturing stages, reducing capital intensity for mid-scale entrants while challenging standalone adhesive coaters.
China's SAMR enforcement of GB 4806.13-2019 composite food-contact material standards mandates migration testing for every laminated layer combination. Adhesive suppliers must submit substance declarations for each hot-melt formulation variant. Japanese food exporters to China face dual compliance burdens under both METI recycling directives and SAMR migration protocols, accelerating regional harmonization efforts through industry association working groups.
Brand owner sustainability scorecards now weight post-consumer recyclability above surface aesthetics in supplier selection. Matte thermal films gain preference in European premium cosmetics packaging as reflectivity becomes a negative attribute. Procurement teams in German and French headquarters consolidate vendor lists around mono-material thermal constructions, displacing multi-substrate legacy specifications.
Thermal Lamination Films Market Segmentation
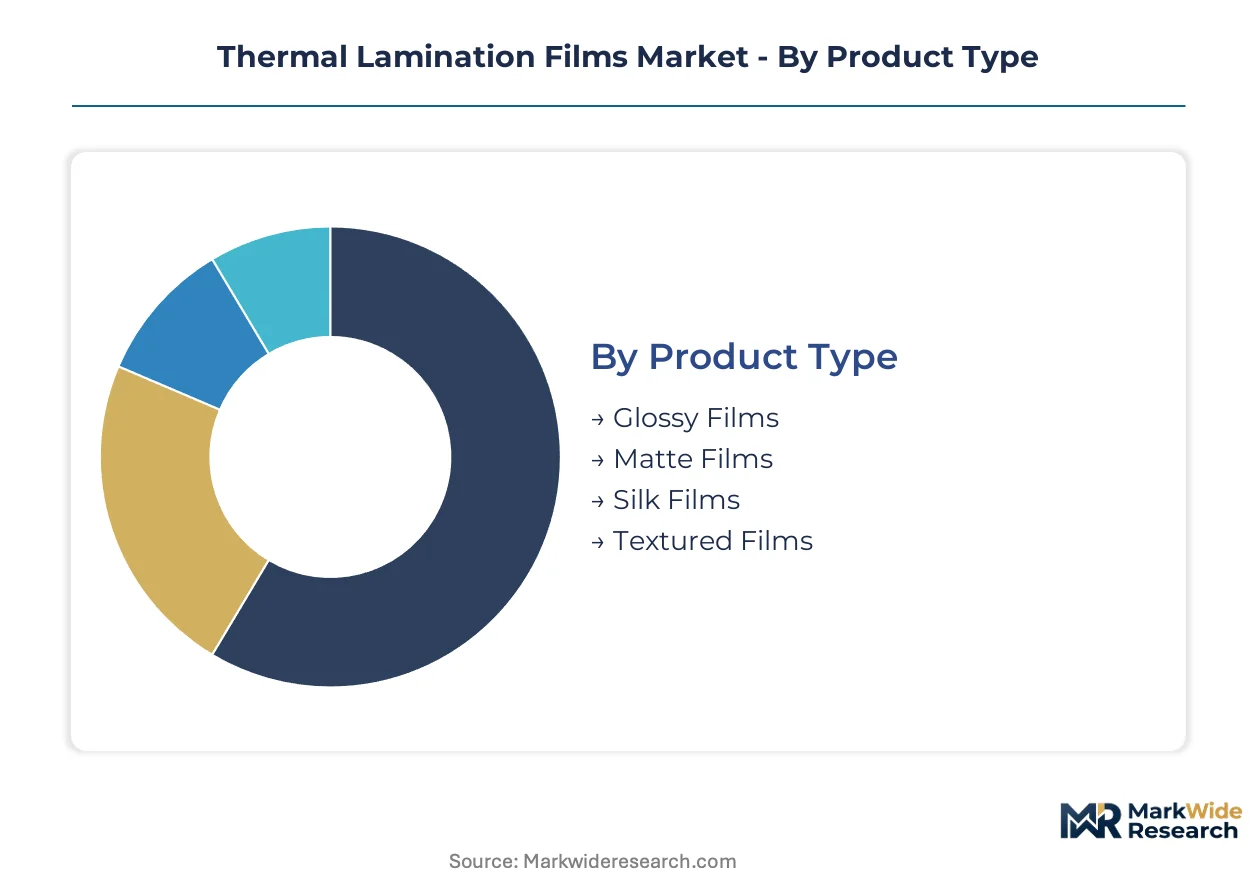
Thermal lamination films segment across four intersecting dimensions that determine specification requirements, pricing tiers, and compliance obligations. Each category carries distinct upgrade cycles as converters and brand owners rebalance performance against recyclability mandates and substrate compatibility demands.
Product Type:
Finish selection drives replacement cycles as brand aesthetics shift away from conventional high-gloss surfaces toward subdued alternatives that signal premium positioning.
- Glossy Films:Standard BOPP or polyester substrates with high-clarity EVA adhesive layers deliver maximum visual impact and ink vibrancy. Commercial print finishers across India's Mumbai-Pune corridor specify these for FMCG carton work where shelf visibility determines purchase decisions.
- Matte Films:Surface-etched or additive-modified constructions scatter light to eliminate reflectivity. Premium cosmetics brands in Germany and France now mandate matte finishes as sustainability scorecards penalize high-energy gloss coatings and metallic effects.
- Silk Films:Intermediate satin sheen occupies the perceptual space between gloss and matte extremes. Stationery and invitation printers favor silk for tactile differentiation without full matte premium pricing.
- Textured Films:Embossed or cast-pattern surfaces add dimensional interest to specialty packaging. Limited volume applications include luxury spirits cartons and high-end electronics unboxing experiences.
Glossy films sit at the top of the volume ranking, with matte films climbing the fastest as anti-glare aesthetics displace legacy specifications across European premium segments.
Application:
End-use concentration varies sharply by geography, with Asian converters prioritizing flexible food packaging while European and North American demand centers on commercial print finishing.
- Packaging:Flexible food packaging converters across Southeast Asia deploy thermal lamination for shelf-life extension without aluminum foil barriers. GB 4806 migration testing requirements from China's SAMR constrain adhesive selection for export-bound structures.
- Labels:Pressure-sensitive and in-mold label applications require precise dimensional stability. Polyester thermal films retain share here despite polypropylene cost advantages due to tighter tolerance requirements.
- Stationery:Document finishing and presentation materials favor lower-cost polypropylene constructions. Japanese office product distributors specify mono-material designs to align with METI Plastic Resource Circulation Strategy targets.
- Book Covers:Educational and trade publishing demand durability without excessive rigidity. India's domestic textbook market drives regional capacity expansion among Mumbai-based converters.
Packaging commands the dominant volume position, with labels expanding most quickly as pharmaceutical and cosmetics serialization requirements multiply label complexity.
End User:
Customer procurement patterns diverge between specification-driven verticals with centralized vendor management and fragmented sectors with distributed purchasing authority.
- Retail:Mass-market brand owners consolidate supplier lists around mono-material thermal constructions. German and French headquarters procurement teams now weight post-consumer recyclability above surface aesthetics in annual vendor reviews.
- Publishing:Educational publishers in India drive demand for cost-optimized polypropylene laminates. State-level textbook procurement tenders prioritize unit economics over premium finish characteristics.
- Food & Beverage:Migration testing burdens concentrate among converters serving pan-European brand owners. EU REACH phthalate restrictions force reformulation cycles that disadvantage mid-scale adhesive coaters.
- Electronics:Unboxing experience specifications favor textured and matte finishes for premium device packaging. Heat-sensitive substrate compatibility opens opportunities for low-temperature thermal bonding specialists.
Food & beverage leads by volume, with electronics gaining share fastest as device manufacturers invest in packaging-driven brand differentiation.
Material Type:
Substrate selection determines cost position, barrier performance, and recyclability profile within increasingly stringent extended producer responsibility frameworks.
- Polypropylene:Biaxially oriented polypropylene dominates volume through cost positioning against polyester alternatives. Middle East and Northeast Asian petrochemical corridors concentrate resin supply, transmitting propylene feedstock volatility directly to converter margins.
- Polyester:Polyethylene terephthalate substrates retain premium print-finishing share despite higher unit costs. Gloss consistency and dimensional stability requirements constrain downgauging below 12-micron thresholds in label and electronics applications.
- Polyethylene:Lower barrier performance suits flexible food packaging where moisture protection requirements are less stringent. Co-extruded functional layers increasingly unify barrier and adhesive functions within single-pass constructions.
- Others:Nylon and bio-based substrates occupy niche positions where specialized mechanical or sustainability properties justify premium positioning. Limited commercial scale constrains widespread converter adoption.
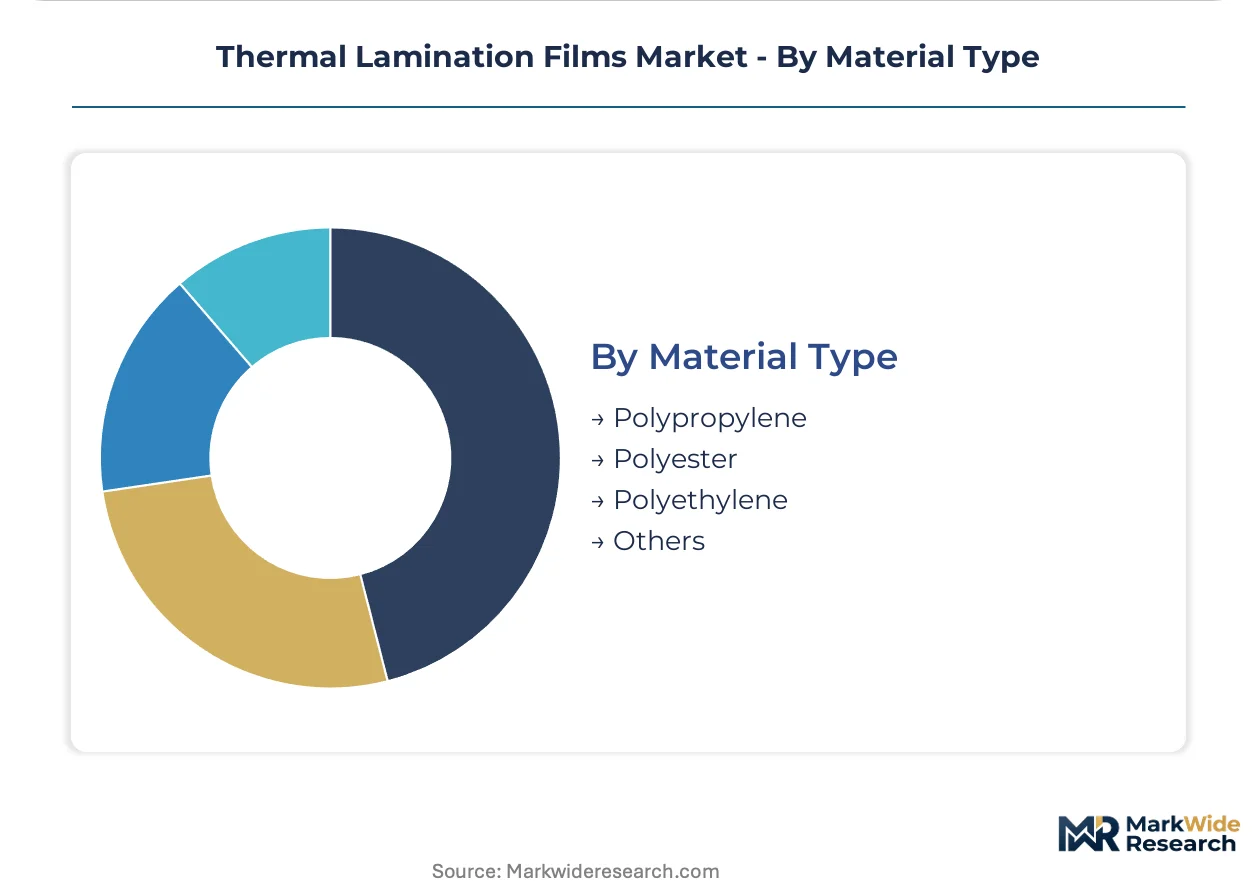
Polypropylene holds the volume leadership position, with polyethylene showing the steepest expansion trajectory as co-extrusion technology eliminates separate coating steps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's thermal lamination capacity expansion outpaces India's converter investments by a three-to-one ratio, yet Mumbai-Pune packaging clusters retain higher margin capture through proximity to polyethylene resin supply chains.
China
Flexible food packaging converters in Yangtze River Delta cities deploy thermal lamination for shelf-life extension without aluminum foil barriers. SAMR enforces GB 4806.13-2019 composite food-contact material standards requiring migration testing for every laminated layer combination. Zhejiang and Jiangsu province adhesive coaters face dual compliance burdens under domestic GB standards and export-market REACH protocols.
India
Mumbai-Pune packaging clusters serve domestic FMCG brands with expanding lamination capacity driven by state-level textbook procurement tenders and retail carton demand. BIS certification requirements for food-contact plastics constrain adhesive formulation choices among mid-scale converters. Maharashtra-based film distributors benefit from captive polyethylene resin supply through Reliance Industries' Jamnagar petrochemical corridor.
Japan
Mono-material thermal film specifications accelerate under METI Plastic Resource Circulation Strategy targets for improved post-consumer recyclability. Kanto region converters reposition production lines toward single-substrate constructions to preempt compliance deadlines. Tokyo-based brand owners now weight recyclability above surface aesthetics in annual vendor reviews.
Germany
Commercial print finishers in Baden-Württemberg and North Rhine-Westphalia specify matte thermal films as sustainability scorecards penalize high-energy gloss coatings. ECHA REACH restrictions on phthalate plasticizers force reformulation cycles for food-contact thermal films serving pan-European brand owners. Bavarian adhesive suppliers maintain multiple SKU variants for Germany's DSD extended producer responsibility system.
United States
Web-to-pack converters in Midwest and Southeast markets reduce inventory carrying costs through synchronized digital print finishing and on-demand lamination workflows. FDA food-contact substance regulations constrain hot-melt adhesive formulation choices for converters serving food and beverage end users. Chicago and Atlanta distribution hubs anchor thermal film supply chains for North American commercial print markets.
Thermal Lamination Films Market Competitive Environment
Asian producers anchor the volume-driven tier; European specialists hold premium positioning through adhesive chemistry differentiation and compliance service bundling. The market structure fragments across three strategic archetypes: petrochemical-integrated film manufacturers, standalone adhesive coaters, and regional distribution-focused converters. Competitive moves concentrate on backward integration into resin compounding and geographic expansion through distribution partnerships.
Within the petrochemical-integrated tier, COSMO Films exemplifies upstream control over melt-index consistency through captive resin operations. Among specialty adhesive suppliers, Drytac occupies a position representing low-temperature thermal bonding expertise for heat-sensitive substrates. GMP sits within the European print-finishing distribution channel archetype, anchoring geographic dominance in compliance-heavy Western European markets.
| Leading Market Players |
|---|
| FlexFilm |
| GMP |
| COSMO Films |
| Ipak |
| Royal Sovereign |
| Transilwrap |
| Derprosa |
| Drytac |
| D&K |
| Others |
Value Chain & Pricing Dynamics
Propylene feedstock indices cascade through thermal lamination film supply chains, compressing converter margins in Middle East and Northeast Asian petrochemical corridors while amplifying pricing power for backward-integrated manufacturers with captive resin operations.
Pricing Analysis
Distributor margins stratify across three tiers pegged to certification burden and volume commitment. Premium-mid-economy pricing differentiation reflects GB 4806 migration testing costs for food-contact grades against standard commercial print finishes. Cost compression in economy-tier BOPP constructions intensifies as Indian and Chinese converters expand capacity. Mid-scale adhesive coaters serving pan-European brand owners exhibit highest price sensitivity due to reformulation cycle burdens under REACH phthalate restrictions.
Supply Chain Analysis
Container freight rates from Middle East petrochemical hubs to Mumbai-Pune packaging clusters determine landed cost competitiveness for polyethylene resin feedstocks. Biaxially oriented polypropylene supply concentrates in Saudi Arabia, South Korea, and China. Raw material flows draw from propylene monomer, ethylene-vinyl acetate copolymers, and low-density polyethylene coating resins. Single-source vulnerability in EVA adhesive formulation expertise constrains Southeast Asian converter expansion. Distribution runs through regional film distributors anchoring European print-finishing channels and Asian flexible packaging corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
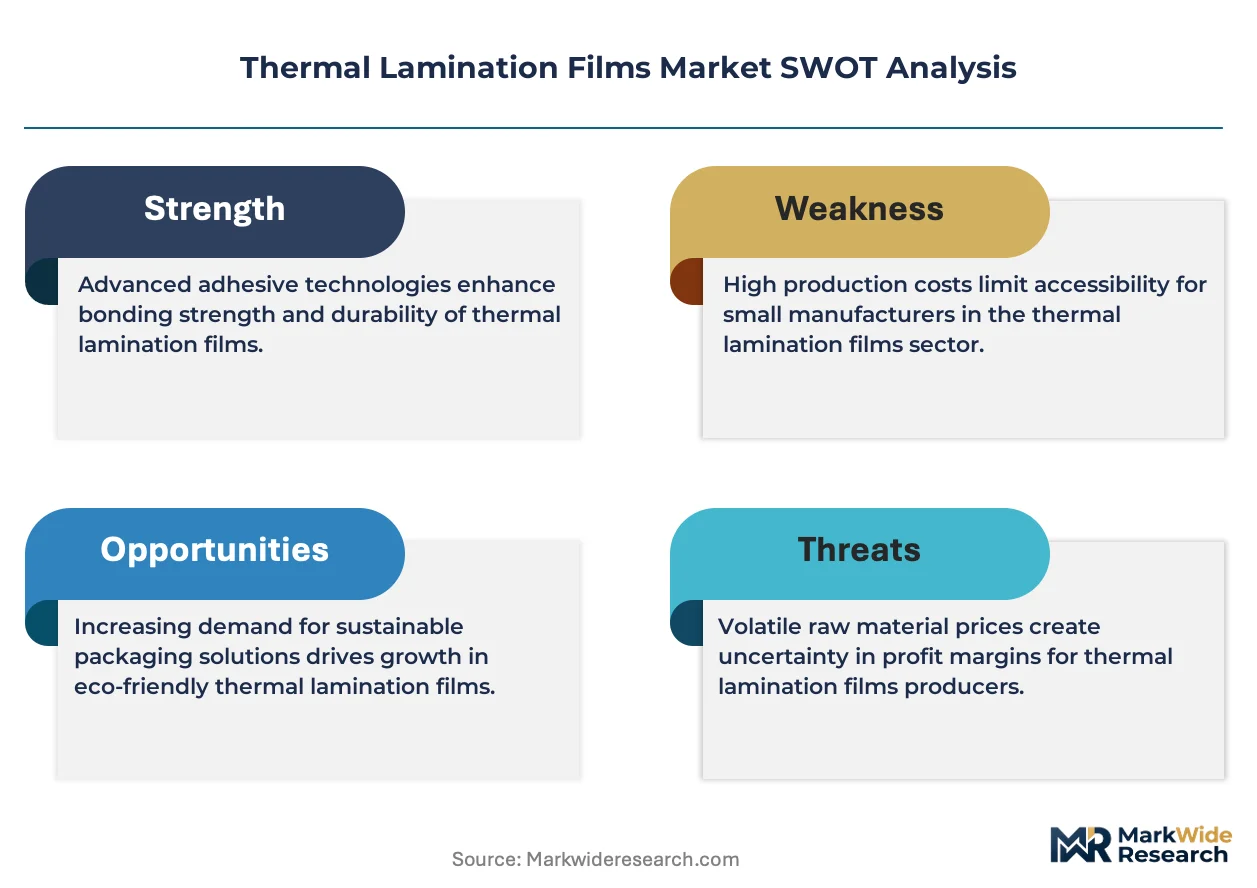
Thermal lamination films offer margin-expansion pathways through mono-material premium tier shifts and backward integration into resin compounding, offsetting feedstock volatility that erodes standalone adhesive coater economics.
For Market Incumbents: Lock in adhesive chemistry specialization for low-temperature thermal bonding to defend against emerging Asian petrochemical-integrated entrants. Deepen backward integration into melt-index-controlled resin compounding to neutralize propylene feedstock volatility. Capture compliance service revenue streams around China's SAMR migration testing requirements and EU REACH reformulation protocols.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in matte finish thermal films opens white-space targets in European cosmetics packaging where sustainability scorecards penalize gloss coatings. India's western industrial corridor offers the most penetrable geography given proximity to Reliance Industries' polyethylene supply and state-level textbook procurement growth. Lead with digital print finishing integration for web-to-pack converters seeking synchronized inventory reduction.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialty adhesive coaters possessing validated low-temperature bonding formulations for heat-sensitive pharmaceutical and electronics substrates. Long-term viability favors mono-material construction capabilities aligned with Japan's METI recycling mandates and EU extended producer responsibility schemes. Watch for consolidation signals when propylene feedstock volatility triggers distressed capacity among non-integrated Southeast Asian converters.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | COSMO Films exemplifies melt-index control that neutralizes propylene price volatility for thermal lamination grades. |
| Mono-Material Design Certification | Japanese METI compliance accelerates vendor consolidation around single-substrate thermal films in European premium packaging. |
| Low-Temperature Adhesive R&D Investment | Drytac's heat-sensitive substrate expertise captures margin from pharmaceutical leaflet and cosmetics packaging applications. |
| Geographic Distribution Partnership Expansion | GMP's European channel dominance demonstrates compliance-bundling value in REACH-regulated print-finishing markets. |
| Digital Print Finishing Workflow Integration | Web-to-pack converters in North American markets reduce inventory carrying costs through synchronized on-demand lamination. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with thermal lamination film plant managers, flexible food packaging procurement leads at FMCG brand owners, adhesive formulation R&D directors, and European print-finishing distribution channel partners. Secondary validation drew from customs trade data, SEC filings of petrochemical-integrated film manufacturers, China's SAMR regulatory bulletins, and EU ECHA REACH restriction updates. Bottom-up capacity assessments and top-down end-use demand modeling provided cross-verification.
Historical reference periods anchored the projection horizon to pre-pandemic baseline volumes and post-regulatory-shift demand patterns across the analysis window. The analytical framework modeled segmentation dimensions spanning finish type, substrate material, application vertical, and geographic regulatory cluster. CAGRs derived from compound growth trajectory fitting against validated capacity expansion announcements and brand owner procurement trend indicators. Forecast inputs incorporated propylene feedstock price elasticity assumptions and mono-material substitution rates under extended producer responsibility schemes.
Caveats apply where unforeseen phthalate plasticizer regulatory tightening or abrupt propylene supply disruptions could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Vacuum Packaging Market
Packaging Materials
Anti-Scratch Film Market
Packaging Materials
PET Strap Market
Packaging Materials
Nonwoven Packaging Market
Packaging Materials
Twist Tie Market
Packaging Materials
Trifold Packaging Market
Packaging Materials
New Packages and Materials for Power Devices Market
Packaging Materials
Metallized Rollstock Film Market
Packaging Materials
Bottle Sealing Wax Market
Packaging Materials
Strip Pack Laminates Market
Packaging Materials
MDO Films Market
Packaging Materials
Absorbent Tray Liners Market
Packaging Materials
Crimped End Mailing Tubes Market
Packaging Materials
Wooden and Plywood Packaging Market
Packaging Materials
Mylar Market
Packaging Materials
Cork Packaging Market