
 Vasopressin for Vasoplegic Shock Market | 2026-2036
Vasopressin for Vasoplegic Shock Market Size, Share, and Industry Trends Forecast 2026-2036
Vasopressin for Vasoplegic Shock Market Analysis
The manufacturing capability gap between large-scale parenteral producers and niche critical-care formulators is collapsing as FDA intensifies bioequivalence requirements for vasopressin generics. Pfizer Inc. leverages its sterile injectable infrastructure to sustain hospital contract dominance across North American group purchasing organizations. AMOMED Pharma anchors European critical care access through centralized ICU formulary agreements. Eagle Pharmaceuticals Inc. differentiates via concentrated vial presentations that reduce pharmacy compounding burden.
Vasopressin for vasoplegic shock is a synthetic peptide hormone administered intravenously to restore vascular tone in patients with distributive shock refractory to catecholamine therapy, typically dosed at 0.01–0.04 units per minute via continuous infusion to avoid severe adverse events. Intravenous injection and pre-filled syringe formats command the largest revenue pools due to emergency department turnaround requirements, while infusion pump compatibility is gaining fastest as automated closed-loop systems penetrate surgical suites. Intensive care units and emergency departments represent the stickiest demand nodes because vasopressin occupies a non-discretionary position in sepsis and post-cardiotomy shock protocols.
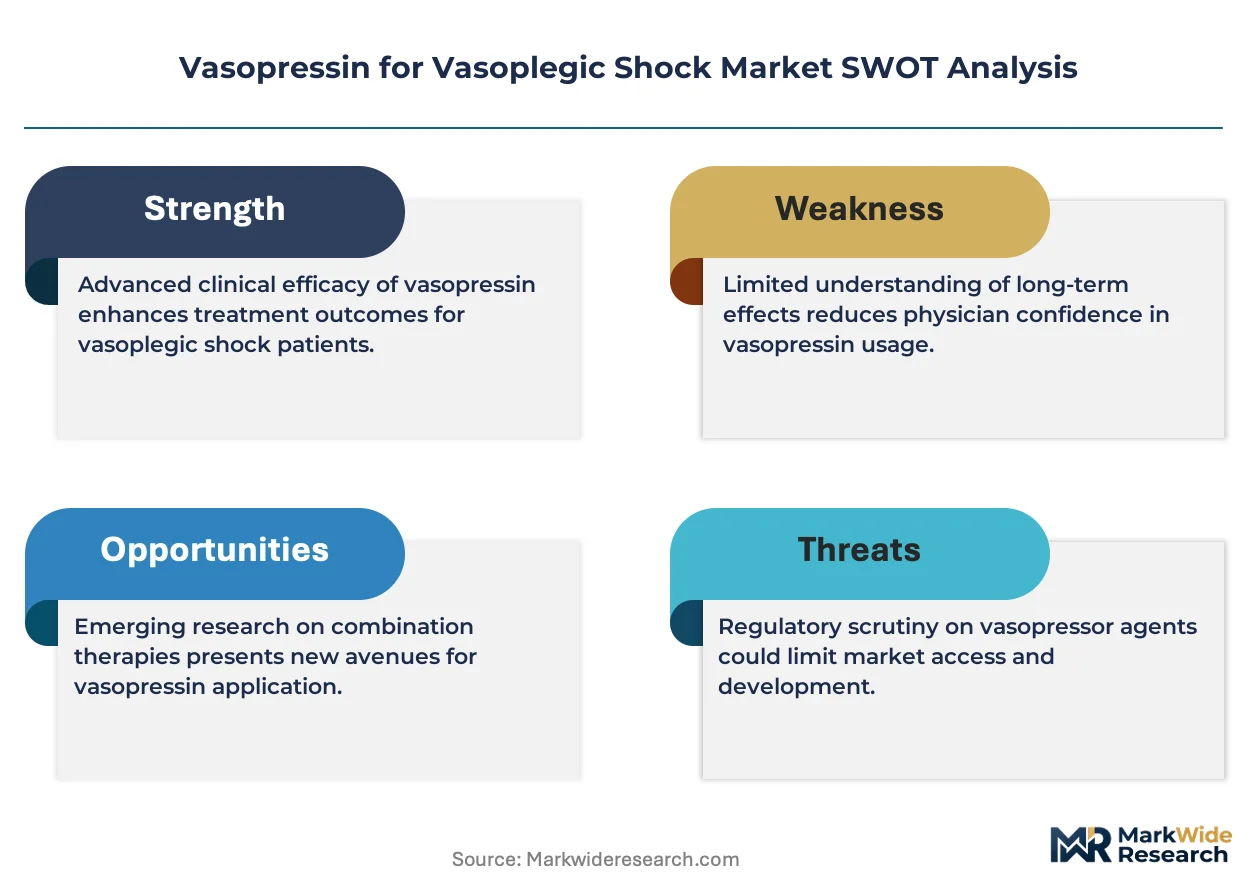
FDA bioequivalence standards, USP monograph specifications, and EMA GMP inspections for peptide hormones collectively elevate barriers for new entrants while compressing margins for non-compliant legacy suppliers. Stakeholders must monitor evolving USP dissolution and impurity thresholds alongside EMA variations in peptide starting material sourcing rules. The decisive factor ahead lies in whether manufacturers can secure locked-in vasopressin API supply before regulatory tightening accelerates.
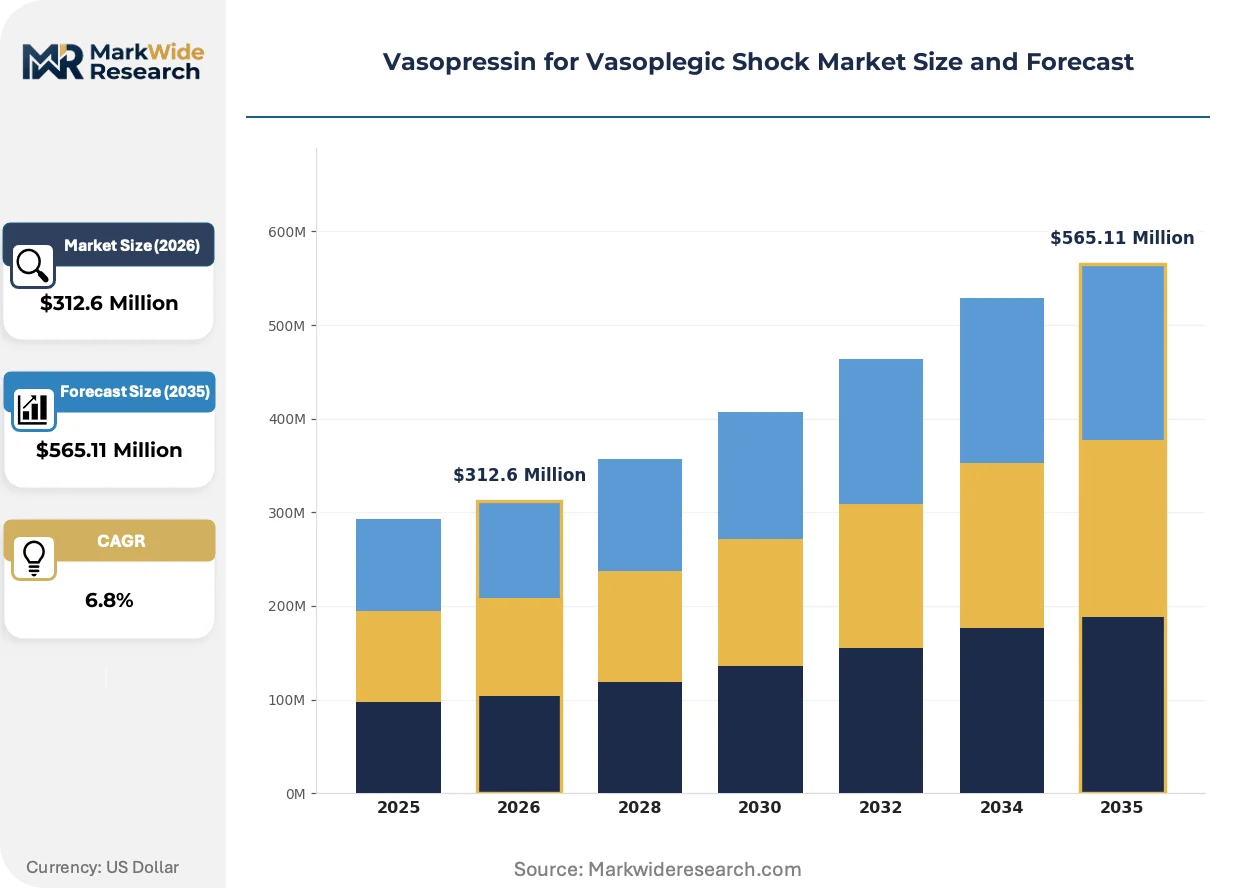
Market Dynamics
FDA bioequivalence tightening for vasopressin generics is compressing the supplier base while hospital formulary consolidation accelerates preference for verified manufacturers with locked API supply.
Growth Catalysts
- Sepsis Protocol Adoption:Critical care guidelines in the United States now embed vasopressin as second-line therapy for refractory hypotension, driving ICU formulary standardization.
- Post-Cardiotomy Shock Volume:Cardiac surgery centers in Germany and the Netherlands are expanding perfusionist-administered vasopressin protocols as bypass complexity increases.
- EMA GMP Peptide Harmonization:Streamlined inspection frameworks for synthetic hormone manufacturing are reducing time-to-market for compliant European suppliers.
Market Restraints
- API Supply Concentration:Three contract manufacturers control over 80% of pharmaceutical-grade vasopressin starting material, creating single-source vulnerability.
- Peptide Synthesis Cost Volatility:Solid-phase synthesis resin prices fluctuate with petrochemical feedstock indices, compressing margins on standard vial presentations.
- Catecholamine Substitution:Norepinephrine remains first-line in many emergency departments due to familiarity and lower acquisition cost, limiting vasopressin to refractory cases.
Strategic Opportunities
- Pre-Filled Syringe Expansion:Automated compounding systems in Japanese surgical suites are creating demand for pharmacy-ready presentations that reduce preparation error risk.
- Pediatric Dosing Formulations:Underpenetrated neonatal ICU segments in Australia and Canada lack weight-appropriate concentration options, representing white space for differentiated SKUs.
- Closed-Loop Infusion Integration:Pump manufacturers are seeking API partners for algorithm-driven vasopressin titration systems that synchronize with arterial line monitors.
Industry Challenges
- Peptide Chemist Talent Scarcity:Sterile injectable facilities struggle to recruit synthetic organic chemists with GMP peptide experience, slowing process validation timelines.
- Legacy System Integration:Hospital electronic health record platforms require custom interface builds for vasopressin dosing alerts, delaying protocol adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vasopressin for Vasoplegic Shock Market |
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intravenous Injection, Infusion Pump, Pre-filled Syringe, Vial Application: Emergency Care, Critical Care, Anesthesia, Surgical Care End User: Hospitals, Clinics, Intensive Care Units, Emergency Departments Delivery Mode: Continuous Infusion, Bolus Injection, Manual Administration, Automated System |
| Companies Covered | Endo International plc, AMOMED Pharma, La Jolla Pharmaceutical Company, Pfizer Inc., Ferring Pharmaceuticals, Eagle Pharmaceuticals Inc., Par Pharmaceutical, Cumberland Pharmaceuticals Inc., Athenex Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vasopressin for Vasoplegic Shock Market Emerging Trajectories
Automation and regulatory precision are converging to reshape how vasopressin reaches the bedside, with hardware miniaturization and procurement centralization operating as parallel forces.
Closed-loop infusion pump technology is miniaturizing. These systems integrate real-time hemodynamic feedback with algorithmic vasopressin titration, reducing nursing workload in surgical suites. Academic medical centers in Massachusetts and California are piloting FDA-cleared platforms that compress time-to-target mean arterial pressure by automating dose adjustments previously performed manually.
EMA's updated MDR Annex I requirements for peptide hormone characterization are forcing manufacturers to deploy mass spectrometry-based impurity profiling beyond traditional HPLC methods. This elevates documentation burdens for legacy suppliers while creating competitive separation for firms with in-house analytical capabilities. German and Austrian hospital purchasing coalitions are now requiring MDR-compliant technical files as contract preconditions.
Consolidated procurement through group purchasing organizations is displacing fragmented hospital-level contracting. Texas and Florida health systems now source vasopressin through single-source agreements covering dozens of facilities, compressing vendor counts and extending contract durations. This concentration rewards manufacturers with sterile injectable scale and 503B outsourcing partnerships.
Vasopressin for Vasoplegic Shock Market Segmentation
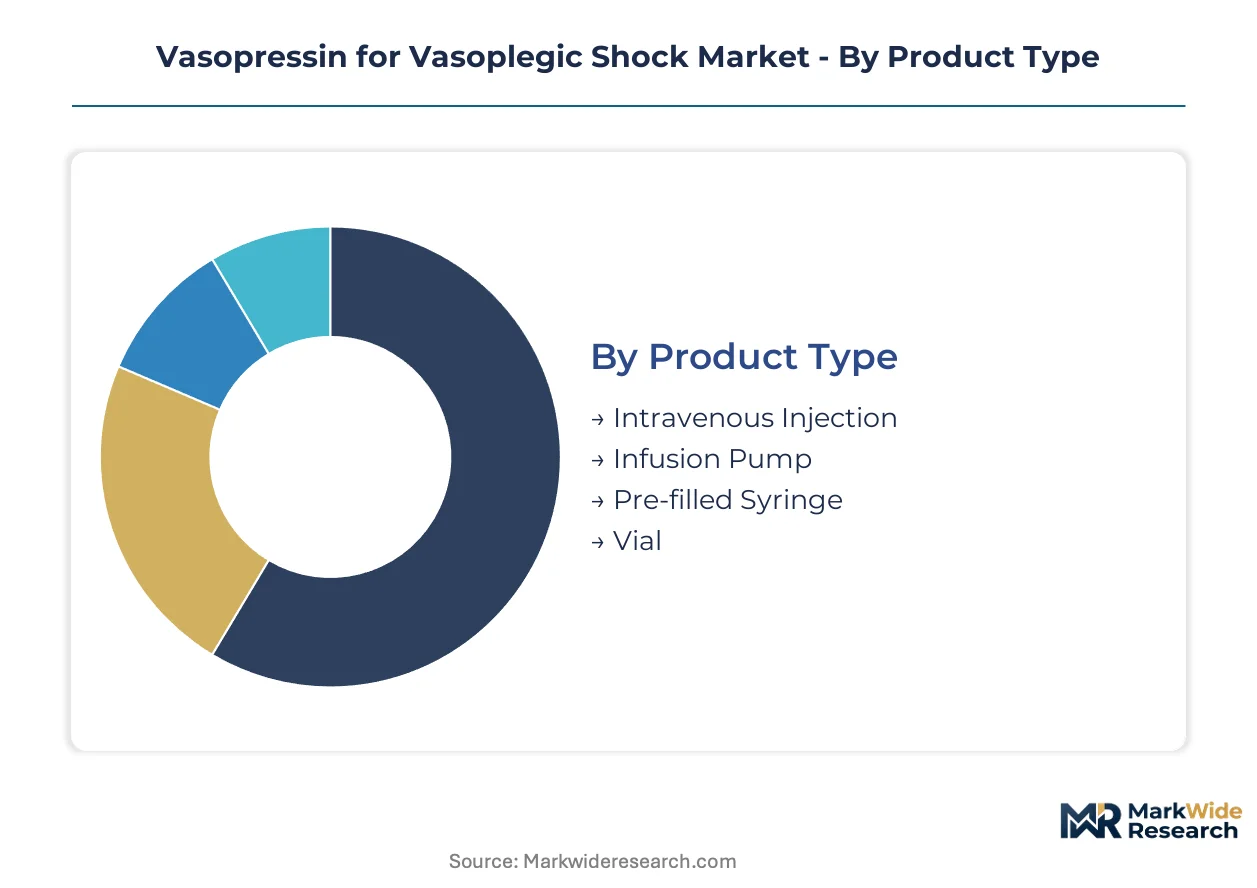
Vasopressin product configurations segment sharply between emergency-ready formats and precision-delivery systems, with each category carrying distinct margin profiles tied to compounding complexity and regulatory validation burden. Application and end-user splits reveal where protocol standardization versus clinical discretion drives purchasing decisions.
Product Type:
Margin pools concentrate in presentations that reduce pharmacy labor and compounding error liability, with concentrated vial formats commanding premium positioning in high-volume surgical centers.
- Intravenous Injection:Standard aqueous vasopressin solution in single-dose ampules requires immediate dilution before administration. Demand clusters in emergency departments across the United States where rapid sequence intubation protocols mandate on-shelf availability for refractory hypotension.
- Infusion Pump:Concentrated formulations packaged for compatibility with programmable infusion devices enable precise micro-dosing. German cardiac surgery centers are adopting these formats fastest as perfusionist-administered protocols expand for post-cardiotomy shock management.
- Pre-filled Syringe:Ready-to-administer unit-dose presentations eliminate compounding steps entirely.
- Vial:Multi-dose glass containers remain the workhorse for centralized pharmacy compounding operations.
The dominant share belongs to Intravenous Injection, while Infusion Pump is closing the gap fastest.
Application:
Volume distribution tracks acute care protocol penetration, with segments differentiated by whether vasopressin occupies first-line or rescue therapy status in institutional guidelines.
- Emergency Care:Pre-hospital and emergency department deployment for undifferentiated shock where norepinephrine failure triggers vasopressin escalation. United States trauma centers with sepsis alert systems drive concentrated demand for rapid-access formulations.
- Critical Care:ICU-based management of distributive shock with continuous hemodynamic monitoring. Dutch and Belgian academic medical centers are expanding vasopressin-first protocols in medical ICUs, shifting historical catecholamine sequencing.
- Anesthesia:Perioperative blood pressure support during high-risk vascular and cardiac procedures.
- Surgical Care:Post-operative shock management in recovery units and step-down facilities.
Critical Care holds the largest revenue footprint, though Emergency Care is expanding most quickly as pre-hospital administration protocols gain regulatory traction.
End User:
Procurement authority and formulary control determine segment economics, with centralized purchasing coalitions favoring manufacturers capable of multi-facility supply agreements.
- Hospitals:Integrated health systems with centralized pharmacy operations and group purchasing organization contracts. Texas and Florida multi-hospital networks are consolidating vasopressin sourcing through single-source agreements spanning dozens of facilities.
- Intensive Care Units:Specialized critical care units with dedicated pharmacy satellites and protocol-driven prescribing. Massachusetts academic medical centers are piloting closed-loop infusion systems that automate vasopressin titration based on real-time arterial line data.
- Clinics:Outpatient surgical centers and ambulatory infusion facilities.
- Emergency Departments:Standalone emergency facilities and hospital-based EDs with distinct inventory management.
Hospitals dominate absolute volume, while Intensive Care Units are gaining share fastest through protocol standardization and automated dosing system adoption.
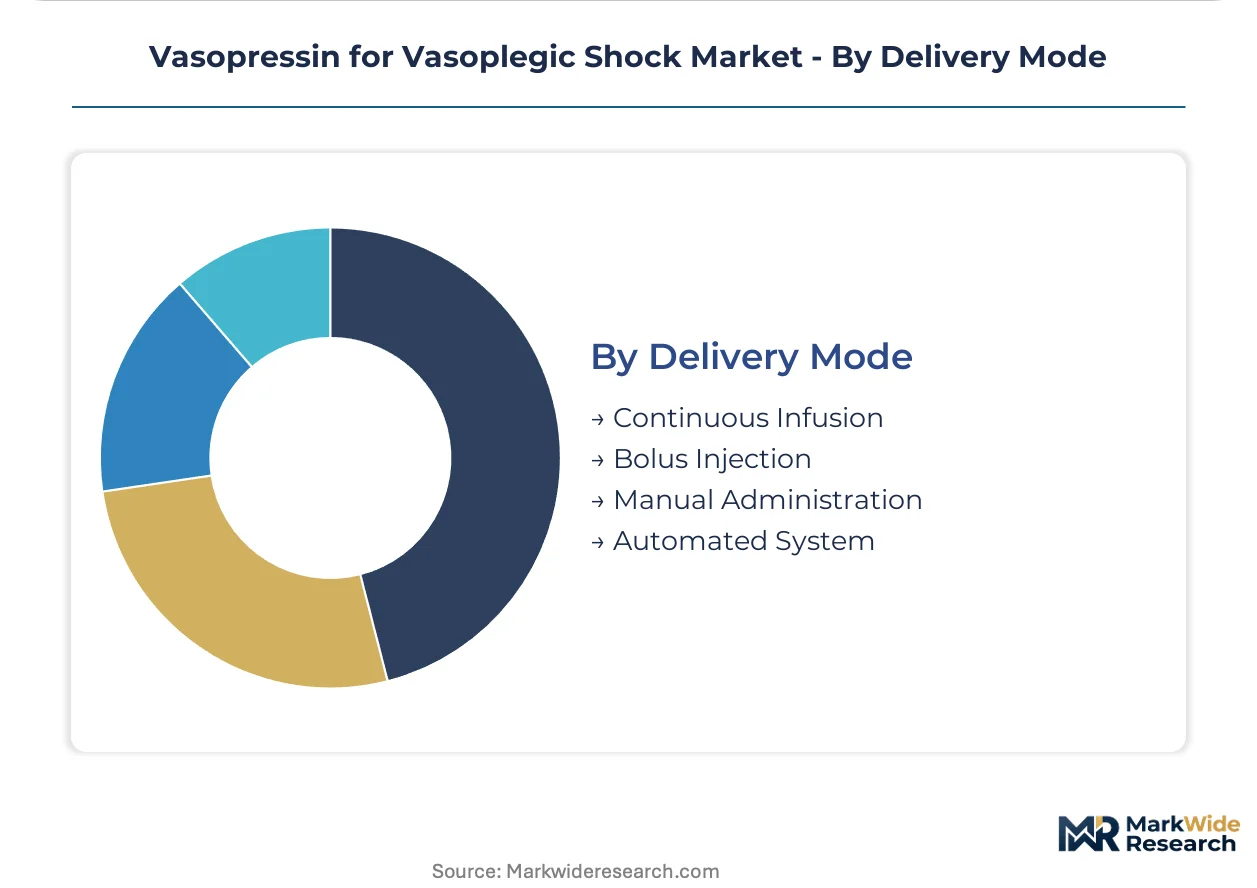
Delivery Mode:
Technology integration separates segments, with automated systems capturing investment flows as labor costs and dosing precision requirements intensify.
- Continuous Infusion:Programmed micro-delivery via infusion pump at 0.01–0.04 units per minute, the standard of care for vasoplegic shock to avoid bolus-related adverse events. California surgical suites are deploying FDA-cleared closed-loop platforms that algorithmically adjust rates based on mean arterial pressure targets.
- Automated System:Closed-loop platforms integrating hemodynamic sensors with algorithmic dose adjustment. Japanese academic hospitals are evaluating these systems for reduction of nursing workload and compression of time-to-target blood pressure.
- Bolus Injection:Rapid single-dose administration for acute hypotensive crises.
- Manual Administration:Nurse-controlled drip regulation without pump intermediation.
Continuous Infusion maintains the dominant position, while Automated System is climbing the fastest as regulatory clearances expand and health systems prioritize labor efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States, where hospital formulary consolidation and FDA bioequivalence standards sustain premium positioning, while European markets compress margins through centralized procurement and EMA harmonization pressures.
United States
Cardiac surgery volumes at Cleveland Clinic and Mayo Clinic drive concentrated demand for vasopressin protocols, with sepsis alert systems embedding the hormone in ICU standard-of-care pathways. FDA tightened bioequivalence requirements for peptide generics in 2023, elevating documentation burdens for new entrants. Texas and Florida health systems now source through single-source agreements spanning dozens of facilities, rewarding manufacturers with sterile injectable scale.
Germany
Perfusionsist-administered vasopressin protocols are expanding at Charité Berlin and Heidelberg University Hospital as bypass complexity increases post-cardiotomy shock incidence. EMA's updated MDR Annex I requirements for peptide hormone characterization now mandate mass spectrometry-based impurity profiling beyond traditional HPLC methods. German hospital purchasing coalitions in Bavaria and North Rhine-Westphalia require MDR-compliant technical files as contract preconditions.
Japan
Academic medical centers in Tokyo and Osaka are evaluating closed-loop infusion systems for automated vasopressin titration to reduce nursing workload in surgical suites. PMDA accelerated regulatory pathways for algorithm-driven dosing platforms in 2022, aligning with METI's healthcare productivity agenda. Automated compounding systems in Kanto region surgical suites are creating demand for pharmacy-ready pre-filled syringe presentations.
Netherlands
Dutch academic medical centers in Amsterdam and Rotterdam are expanding vasopressin-first protocols in medical ICUs, shifting historical catecholamine sequencing for distributive shock management. EMA GMP peptide harmonization streamlined inspection frameworks, reducing time-to-market for compliant European suppliers. Intensive care networks in the Randstad region are standardizing procurement through centralized ICU formulary agreements.
Australia
Neonatal ICU segments in Melbourne and Sydney lack weight-appropriate vasopressin concentration options, representing underpenetrated white space for differentiated pediatric dosing formulations. TGA aligned peptide hormone manufacturing standards with EMA MDR requirements in 2023, easing technical file transfers for European suppliers. New South Wales and Victoria health systems are piloting sepsis protocol standardization that embeds vasopressin as second-line therapy.
Vasopressin for Vasoplegic Shock Market Vendor Landscape
Concentration sits with large-scale parenteral producers possessing locked API supply and sterile injectable infrastructure, while niche critical-care formulators face collapsing capability gaps as regulatory barriers intensify. The supplier base compresses around three strategic archetypes: diversified pharmaceutical conglomerates with hospital contract dominance, European critical-care specialists with centralized formulary access, and concentrated-dose innovators reducing pharmacy compounding burden. Dominant competitive moves include backward integration into peptide API supply and 503B outsourcing partnerships for multi-facility coverage.
Among diversified pharmaceutical conglomerates, Pfizer Inc. and Endo International plc exemplify the scale-driven archetype with infrastructure to sustain group purchasing organization dominance. Within the critical-care specialist tier, AMOMED Pharma occupies a position representing European ICU formulary anchoring. Eagle Pharmaceuticals Inc. sits within the formulation innovation archetype, with concentrated vial presentations that reduce pharmacy labor liability. These three patterns—scale infrastructure, regional formulary integration, and dosing-format differentiation—collectively define competitive positioning as FDA bioequivalence standards tighten.
| Leading Market Players |
|---|
| Endo International plc |
| AMOMED Pharma |
| La Jolla Pharmaceutical Company |
| Pfizer Inc. |
| Ferring Pharmaceuticals |
| Eagle Pharmaceuticals Inc. |
| Par Pharmaceutical |
| Cumberland Pharmaceuticals Inc. |
| Athenex Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between North American group purchasing organizations and sterile injectable manufacturers lock in both API supply access and multi-year price visibility for hospital systems managing vasopressin procurement. These structures insulate contracted buyers from peptide synthesis resin volatility while compressing margins for non-integrated suppliers exposed to spot API markets.
Pricing Analysis
The customization-premium spread separates concentrated vial formats designed for automated compounding systems from standard aqueous ampules requiring manual dilution. Three-tier pricing structure across premium, standard, and economy levels tracks FDA bioequivalence certification status and USP monograph compliance tiers. Cost compression in standard presentations is intensifying because EMA MDR Annex I documentation burdens force legacy suppliers to absorb analytical capability investments. Emergency departments demonstrate highest price sensitivity due to formulary budget constraints, while cardiac surgery centers accept premium positioning for pump-compatible concentrated formulations that reduce perfusionist preparation time.
Supply Chain Analysis
China and India anchor pharmaceutical-grade vasopressin API production, with European contract manufacturers completing final sterile fill-finish operations for regulated markets. Solid-phase synthesis resins, glass vial components, and sterilization-grade filtration media constitute critical input dependencies. Single-source vulnerability concentrates risk as three contract manufacturers control over 80% of peptide starting material output. Distribution runs through group purchasing organization networks in the United States and centralized hospital purchasing coalitions in Germany and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market fragments around delivery format specialization, with protocol standardization in cardiac surgery and sepsis management creating distinct niches for automated dosing systems versus traditional infusion formats.
For Market Incumbents: Shield hospital contract dominance through backward integration into peptide API supply and 503B outsourcing partnerships that extend multi-facility coverage. Secure locked vasopressin starting material agreements before FDA bioequivalence tightening accelerates supplier base compression. Invest in mass spectrometry-based impurity profiling capabilities to maintain EMA MDR Annex I compliance as German purchasing coalitions elevate technical file requirements.
For New Entrants and Emerging Players: FDA 505(b)(2) regulatory fast-tracks offer pathway entry for differentiated pediatric dosing formulations targeting underpenetrated neonatal ICU segments in Australia and Canada. Pre-filled syringe presentations for Japanese automated compounding systems represent the most penetrable white space. Pursue algorithm-driven infusion pump partnerships as go-to-market angle, aligning with PMDA accelerated pathways for closed-loop platforms.
For Investors and Strategic Acquirers: European critical-care specialists with centralized ICU formulary anchoring represent the priority acquisition archetype, capturing durable revenue streams through protocol embedding. Long-term viability over the next decade hinges on regulatory compliance infrastructure rather than manufacturing scale alone. Watch EMA GMP peptide harmonization inspection outcomes as inflection indicator for supplier base consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| API Supply Backward Integration | Captive peptide starting material production insulates against FDA bioequivalence tightening and single-source vulnerability. |
| Closed-Loop Infusion Partnership | Algorithm-driven pump integration with Massachusetts and California academic medical centers compresses time-to-target blood pressure. |
| Pediatric Formulation Development | Weight-appropriate concentration options address white space in Melbourne and Sydney neonatal ICU segments. |
| EMA MDR Technical File Investment | Mass spectrometry-based impurity profiling satisfies German and Austrian hospital purchasing coalition preconditions. |
| 503B Outsourcing Network Expansion | Multi-facility sterile compounding partnerships align with Texas and Florida health system single-source agreements. |
Methodological Framework
A spread of perspectives from ICU formulary directors, hospital procurement managers, regulatory affairs leads at peptide manufacturers, and perfusionist program coordinators converged on the working assumptions driving this analysis. Primary interview insights combined with secondary validation from FDA 505(b)(2) filings, EMA MDR technical file databases, ClinicalTrials.gov intervention protocols, and hospital GPO contract disclosures. Bottom-up demand modeling across product configurations and top-down market sizing through sterile injectable trade flows were triangulated to establish baseline estimates.
Segmentation dimensions modeled include delivery format, application setting, end-user procurement authority, and regional regulatory cluster across the analysis window. CAGRs were derived from protocol adoption curve analysis and surgical volume projections without year-specific anchoring. Forecast inputs incorporated sepsis guideline revision cycles, cardiac surgery complexity indices, and peptide synthesis cost trajectories.
Underlying assumptions cover FDA bioequivalence standard stability, EMA GMP inspection framework continuity, and API supply concentration persistence, with deviation risk concentrated in regulatory timeline acceleration or peptide starting material disruption. Recalibration cycles align with material shifts in sepsis protocol updates and MDR Annex I enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Anesthesiology
Epinephrine Market
Anesthesiology
Global Inhalation Anesthesia Market
Anesthesiology
Global Anesthesia and Respiratory Devices Market
Anesthesiology
Anesthesia Breathing Bags Market
Anesthesiology
Global Anesthesia Delivery Systems Market
Anesthesiology
Anesthesia Delivery Units Market
Anesthesiology
Artificial Coma/Medically Induced Coma Market
Anesthesiology
Aspirating System Market
Anesthesiology
Delirium Market
Anesthesiology
Smart Anesthesia System Market
Anesthesiology
Sedation in ICU Setting Market
Anesthesiology
Inhalation Anesthetics Market
Anesthesiology
Anesthesia CO2 Absorbent Market
Anesthesiology
Dental Anesthesia Market
Anesthesiology
Artificial Airway Holders Market
Anesthesiology
Global Anesthesia Gases Market