
 Delirium Market | 2026-2036
Delirium Market Size, Share, and Industry Trends Forecast 2026-2036
Delirium Market Analysis
Aftermarket service revenue from delirium monitoring device maintenance is narrowing as manufacturers shift toward bundled software-subscription models. Pfizer sustains competitive positioning through its established antipsychotic manufacturing infrastructure across North American and European markets. Philips Healthcare dominates the connected monitoring segment, leveraging its ICU-grade sensor platforms to capture recurring telemetry contracts.
Delirium constitutes an acute neuropsychiatric syndrome characterized by fluctuating attention, awareness, and cognitive disturbance, typically triggered by infection, metabolic imbalance, medication toxicity, or surgical trauma in vulnerable patient populations. The syndrome demands rapid identification through validated screening instruments such as the Confusion Assessment Method, followed by multimodal intervention combining pharmacologic management with environmental modification. Antipsychotics command the largest current revenue pool within psychotropic medications, while intravenous delivery modes capture premium pricing in critical care settings where rapid sedation escalation proves necessary. Long-term care facilities represent the fastest-growing care setting segment as post-acute discharge protocols increasingly mandate delirium surveillance.
FDA pharmacovigilance requirements and EMA's Good Pharmacovigilance Practices shape clinical trial design and post-market surveillance obligations for delirium drug developers, directly influencing R&D allocation and labeling restrictions. The EU Medical Device Regulation and FDA's 510(k) pathway for digital therapeutics create divergent compliance burdens for companies pursuing algorithm-based delirium prediction tools across Atlantic markets. Stakeholders must calibrate portfolio investments against evolving reimbursement codes for non-pharmacologic delirium prevention bundled into hospital quality metrics.
Market Dynamics
Hospital reimbursement protocols are restructuring competitive positioning across the delirium care continuum, as Medicare quality metrics increasingly tie payment to documented prevention outcomes rather than episodic treatment volumes.
Growth Catalysts
- ICU Telemetry Integration:Connected sensor platforms now stream real-time cognitive indicators into electronic health records, enabling automated risk scoring before clinical deterioration.
- Medicare Hospital-Acquired Condition Reduction Program:Financial penalties for preventable delirium episodes are accelerating capital deployment toward non-pharmacologic prevention infrastructure.
- Post-Acute Surveillance Mandates:Skilled nursing facilities face escalating discharge protocol requirements that embed delirium screening into standard workflows.
Market Restraints
- Specialized Workforce Scarcity:Geriatric psychiatry fellowship programs produce insufficient clinicians to staff expanding hospital-based consultation services.
- Antipsychotic Safety Thresholds:FDA black box warnings on mortality risk in elderly dementia patients constrain prescribing latitude for first-line pharmacologic management.
- Device Validation Timelines:FDA 510(k) clearance pathways for algorithm-based prediction tools impose 18-24 month development cycles before commercial deployment.
Strategic Opportunities
- Home-Based Remote Monitoring:Post-discharge telemetry subscriptions extend revenue capture beyond acute episodes into 90-day recovery windows.
- EU Medical Device Regulation Harmonization:MDR compliance investments by established manufacturers create barriers against non-European algorithm developers seeking market entry.
- Electroencephalography-Pharmacology Convergence:Quantitative EEG biomarkers are enabling personalized sedation protocols that reduce antipsychotic exposure duration.
Industry Challenges
- Interoperability Architecture:Proprietary data formats between competing monitoring platforms fragment longitudinal patient records across care transitions.
- Clinical Workflow Integration:Nursing staff resistance to additional documentation burdens slows adoption of validated screening instruments despite regulatory pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Delirium Market |
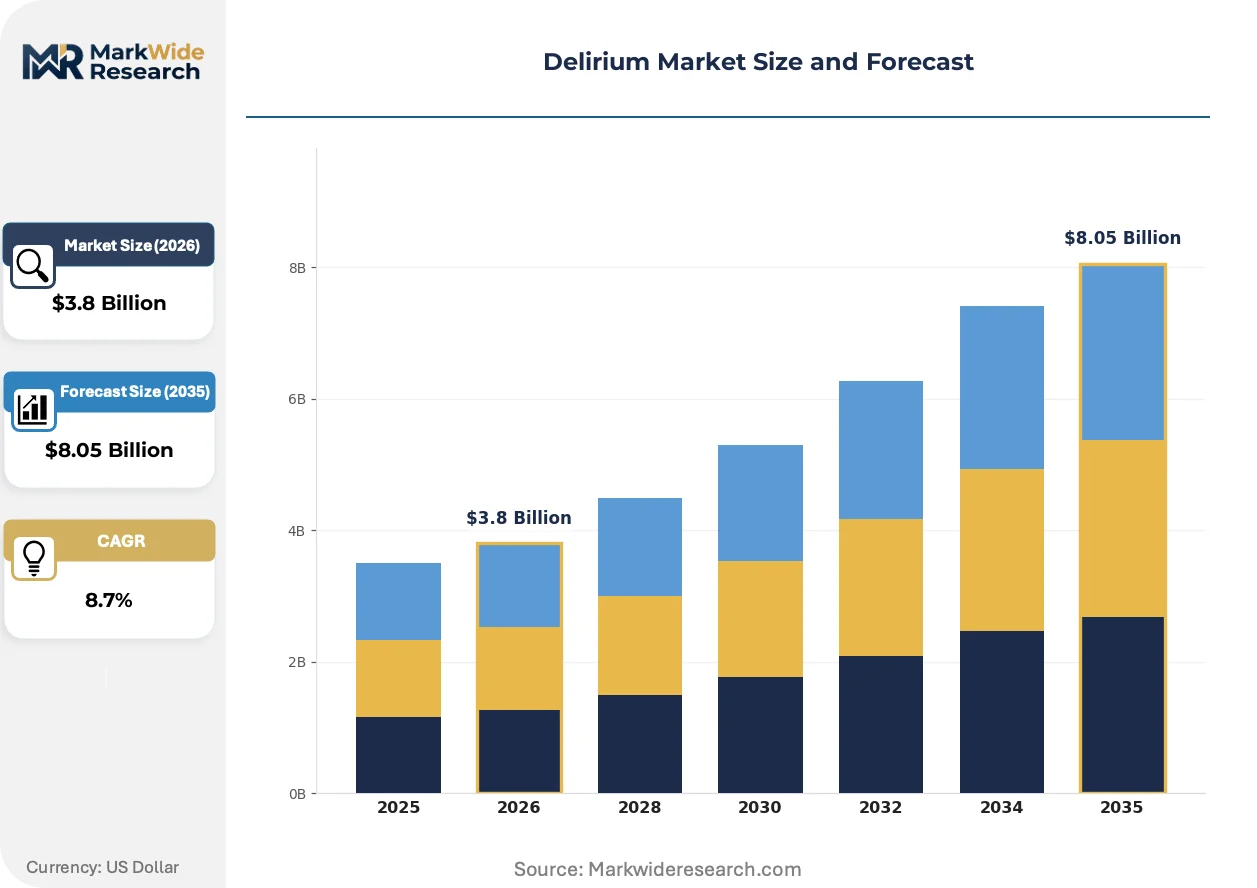
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Psychotropic Medications, Antipsychotics, Anxiolytics, Antidepressants Care Setting: Hospitals, Long-Term Care, Home Care, Rehabilitation Facilities Delivery Mode: Oral, Intravenous, Injectable, Transdermal Patient Age Group: Geriatric, Adult, Pediatric, Young Adults |
| Companies Covered | Otsuka Pharmaceutical Co., Ltd, Teva Pharmaceutical Industries Ltd, Pfizer, Novartis AG, Glenmark Pharmaceuticals Ltd, Zydus Group, Merck & Co, Philips Healthcare, GE HealthCare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Delirium Market Emerging Trajectories
Artificial intelligence is compressing the window between physiological disturbance and cognitive decompensation, enabling intervention before irreversible neuronal injury accumulates.
Multimodal sensor fusion is hybridizing accelerometry, photoplethysmography, and acoustic pattern recognition into single-platform delirium prediction systems. Critical care units at academic medical centers are piloting these integrated stacks during high-risk postoperative windows. The technology is hybridizing hardware margins with recurring software revenue, eroding traditional device-only business models.
EMA's Good Pharmacovigilance Practices are mandating real-world evidence collection for antipsychotic medications used in elderly populations. Post-authorization safety studies now consume 15-20% of regulatory affairs budgets for psychotropic developers. European sponsors are responding by embedding electronic data capture into routine clinical practice to satisfy ongoing safety surveillance obligations.
Long-term care operators are consolidating purchasing decisions through group purchasing organizations that bundle delirium prevention with fall reduction and pressure injury protocols. Skilled nursing chains now negotiate three-year service contracts covering training, device placement, and outcome reporting. This concentration is most visible in the United States, where the ten largest post-acute operators control 35% of Medicare-certified bed capacity.
Delirium Market Segmentation
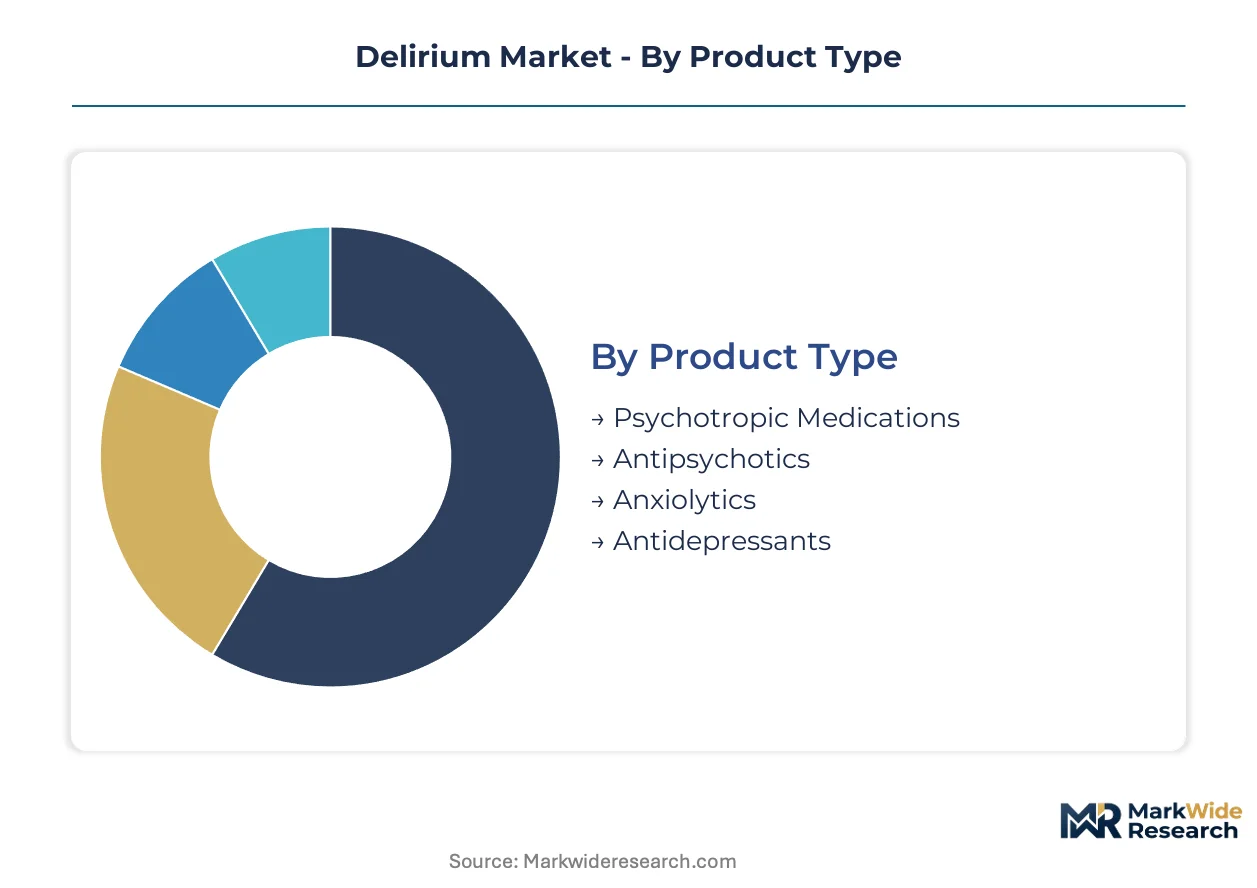
Delirium care pathways fragment across four distinct dimensions, each commanding different procurement cycles and margin structures. Understanding these divides reveals where bundled service contracts concentrate versus where transactional drug purchasing dominates.
Product Type:
After-sales service intensity varies sharply across psychotropic classes, with antipsychotic manufacturers embedding pharmacovigilance support into every contract while anxiolytic suppliers operate on pure volume terms.
- Psychotropic Medications:Broad-spectrum agents targeting multiple neurotransmitter pathways. Demand clusters in academic medical centers with embedded geriatric psychiatry consultation services, driven by Medicare quality metric penalties for uncontrolled delirium episodes.
- Antipsychotics:Dopamine antagonists remain the first-line pharmacologic intervention for hyperactive delirium presentations. Hospital formularies in the United States prioritize agents with established FDA labeling for acute agitation, constrained by black box mortality warnings in elderly dementia patients.
- Anxiolytics:Benzodiazepine and non-benzodiazepine agents used for alcohol withdrawal-related delirium prophylaxis. Surgical pre-admission clinics represent the primary volume channel.
- Antidepressants:Selective serotonin reuptake inhibitors deployed for persistent post-delirium mood disturbances. Long-term care pharmacies drive replenishment schedules.
By volume, antipsychotics lead. By growth pace, psychotropic combination therapies are expanding most quickly.
Care Setting:
Capital deployment cycles stretch longest in institutional settings where infrastructure investment precedes any service revenue recognition.
- Hospitals:ICU and general medical wards generate the majority of acute delirium diagnoses. Telemetry-integrated monitoring platforms command premium pricing in Magnet-designated facilities pursuing outcome-based reimbursement contracts.
- Long-Term Care:Skilled nursing facilities face escalating state survey requirements embedding delirium screening into minimum data set assessments. Group purchasing organizations now bundle prevention training with device placement across multi-state operators.
- Home Care:Post-discharge remote monitoring extends surveillance into 90-day recovery windows. Medicare Advantage plans in Florida and Arizona pilot subscription-based cognitive telemetry for high-risk discharges.
- Rehabilitation Facilities:Inpatient rehabilitation hospitals manage postoperative delirium during mobility restoration protocols. CARF accreditation standards increasingly mandate documented cognitive assessment.
Long-term care facilities capture the steepest expansion trajectory as post-acute discharge protocols proliferate.
Delivery Mode:
Route selection dictates pricing power, with parenteral forms capturing hospital premium tiers against commodified oral generics.
- Oral:Tablets and liquid formulations dominate maintenance phases and mild-to-moderate presentations. Retail pharmacy distribution erodes manufacturer margin through generic substitution.
- Intravenous:Rapid-onset sedation for severe agitation commands the highest unit economics in critical care settings. FDA 510(k) clearance requirements for novel IV formulations extend development timelines.
- Injectable:Intramuscular depot preparations bridge oral non-compliance in confused patients. Emergency department formularies stock specific agents for involuntary administration scenarios.
- Transdermal:Patch-based delivery avoids first-pass metabolism and aspiration risks in dysphagic patients. Hospice programs represent the primary adoption channel.
Intravenous delivery leads by revenue per dose; transdermal formats are climbing the fastest as palliative care protocols expand.
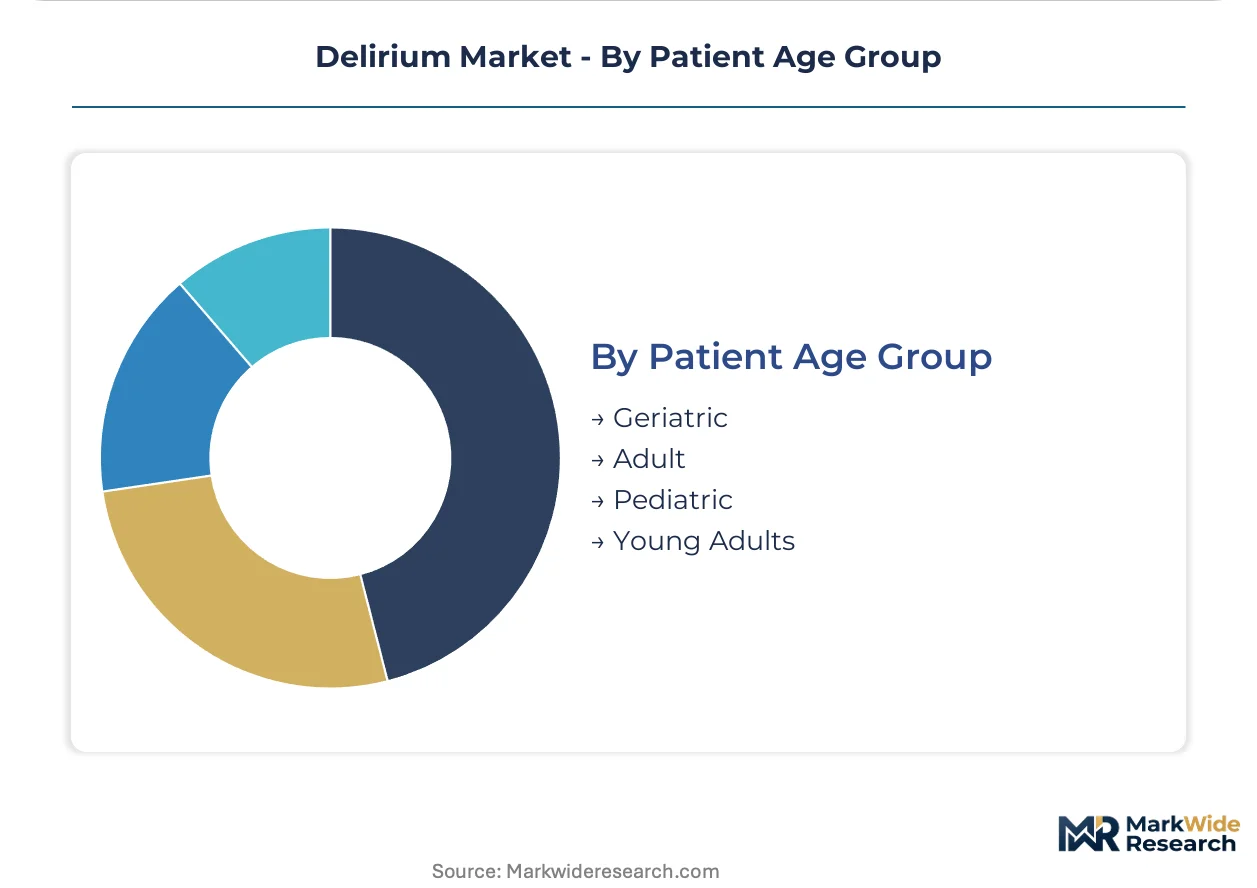
Patient Age Group:
Demographic concentration determines regulatory scrutiny intensity, with geriatric populations triggering enhanced pharmacovigilance obligations.
- Geriatric:Patients over 65 years account for the preponderance of delirium episodes, with prevalence climbing sharply above age 80. EMA Good Pharmacovigilance Practices mandate real-world evidence collection for all antipsychotic exposure in this cohort.
- Adult:Surgical and critical care populations between 18-64 years experience delirium secondary to sepsis, respiratory failure, or polypharmacy. Trauma centers represent high-volume acute intervention sites.
- Pediatric:Children exhibit distinct phenotypic presentations often misclassified as behavioral disturbance. Pediatric ICU specialists at Boston Children's Hospital and Cincinnati Children's have pioneered adapted screening instruments.
- Young Adults:Substance withdrawal and traumatic brain injury drive delirium incidence in 18-30 year-olds. Urban safety-net hospitals manage concentrated volumes.
Geriatric patients dominate current caseloads; pediatric recognition protocols are gaining share fastest as diagnostic awareness spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement teams in Germany and Switzerland demonstrate the lowest price elasticity for ICU-grade monitoring platforms, while skilled nursing facilities in India and Brazil operate under severe budget constraints that favor generic psychotropic purchasing.
United States
Medicare's Hospital-Acquired Condition Reduction Program imposes financial penalties on institutions with elevated delirium incidence rates, driving capital allocation toward prevention infrastructure. FDA pharmacovigilance protocols for antipsychotic medications in elderly populations mandate enhanced post-market surveillance. Academic medical centers in Boston and Baltimore pilot quantitative EEG-integrated sedation protocols that reduce antipsychotic exposure duration.
Germany
EMA Good Pharmacovigilance Practices require real-world evidence collection for all psychotropic exposure in patients over 65, elevating compliance costs for drug manufacturers. The country's statutory health insurance system reimburses hospital-based delirium prevention protocols at premium rates compared to neighboring markets. Medical technology clusters in Baden-Württemberg and Bavaria host concentrated development of AI-enabled prediction algorithms for postoperative cognitive monitoring.
Japan
PMDA accelerated review pathways for digital therapeutics are compressing commercialization timelines for algorithm-based delirium screening tools. METI funding programs support domestic development of multimodal sensor platforms that integrate into existing ICU telemetry architectures. Tokyo and Osaka academic hospitals lead adoption of electroencephalography-pharmacology convergence protocols for personalized sedation management.
India
CDSCO streamlined approval processes for fixed-dose psychotropic combinations are expanding access to first-line delirium pharmacotherapy in tertiary care settings. The country's national health insurance expansion is embedding delirium screening into standard hospital accreditation requirements. Pharmaceutical manufacturing corridors in Gujarat and Maharashtra supply generic antipsychotic formulations across South Asian and African export markets.
United Kingdom
NICE clinical guidelines mandating routine delirium risk assessment in all acute hospital admissions are standardizing screening instrument deployment across NHS trusts. MHRA post-Brexit regulatory autonomy is diverging from EMA pharmacovigilance timelines for novel antipsychotic formulations. London and Manchester health systems concentrate pilot programs for home-based remote monitoring of post-discharge cognitive recovery.
Delirium Market Vendor Landscape
Capability concentration sits with established pharmaceutical manufacturers possessing integrated pharmacovigilance infrastructure; scale advantage sits with diversified health technology conglomerates leveraging existing ICU sensor platforms. The market structures around three archetypes: legacy antipsychotic developers with embedded regulatory affairs capabilities, medical device manufacturers extending into algorithm-based prediction, and emerging digital health specialists pursuing software-subscription revenue models. Dominant competitive moves include strategic partnerships between drug developers and telemetry platform vendors, plus backward integration into sensor hardware production by established monitoring equipment suppliers.
Within the pharmaceutical archetype, Pfizer and Novartis occupy positions reflecting decades of antipsychotic manufacturing experience and established relationships with hospital formularies. Among diversified health technology manufacturers, Philips Healthcare exemplifies the device-to-software transition pattern, while GE HealthCare represents the imaging-equipment origin point for cognitive monitoring expansion. Otsuka Pharmaceutical Co., Ltd anchors the specialized psychiatry-focused tier with concentrated expertise in CNS therapeutic development.
| Leading Market Players |
|---|
| Otsuka Pharmaceutical Co., Ltd |
| Teva Pharmaceutical Industries Ltd |
| Pfizer |
| Novartis AG |
| Glenmark Pharmaceuticals Ltd |
| Zydus Group |
| Merck & Co |
| Philips Healthcare |
| GE HealthCare |
| Others |
Supply Flow & Price Mechanics
Active pharmaceutical ingredient manufacturing for antipsychotic formulations clusters in Gujarat and Maharashtra, India, and the Yangtze River Delta, China, concentrating cost leverage with generic API suppliers and compressing finished-dose margins for Western formulators. This upstream consolidation funnels pricing power toward contract manufacturers with captive raw material access, while hospital procurement teams exploit transparent spot-market quotes to squeeze branded-product premiums.
Pricing Analysis
After-sales service contracts for telemetry platform maintenance now generate recurring revenue exceeding hardware margins by substantial multiples. Pricing stratifies across premium ICU-integrated systems, standard ward-based monitors, and economy-grade screening tools for long-term care. Cost compression in oral generic psychotropics is intensifying because Indian and Chinese API suppliers have expanded batch capacity. Skilled nursing facilities exhibit highest price sensitivity; academic medical centers with Magnet designation show lowest elasticity due to outcome-based reimbursement contracts.
Supply Chain Analysis
Contract manufacturing for delirium monitoring devices concentrates with Foxconn, Jabil, and Flex holding dominant EMS capacity for sensor assembly and firmware integration. Finished-device production rests on China, Mexico, and Malaysia for hardware; software development centers on Israel, the United States, and Estonia for algorithm engineering. Single-source vulnerability runs through Taiwanese semiconductor foundries supplying edge-computing chips for real-time cognitive analytics. Distribution runs through group purchasing organizations consolidating hospital and skilled-nursing procurement at national scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The delirium market constitutes a high-growth disruption as FDA and EMA pharmacovigilance protocols tighten mortality-risk thresholds for antipsychotic prescribing in elderly populations, forcing rapid substitution toward non-pharmacologic prevention infrastructure and algorithm-based early detection systems.
For Market Incumbents: Harden pharmacovigilance infrastructure to absorb escalating post-authorization safety study costs mandated by EMA Good Pharmacovigilance Practices. Expand backward integration into sensor hardware production to capture telemetry platform margins threatened by software-subscription entrants. Lock in three-year exclusive service contracts with the ten largest U.S. post-acute operators before GPO consolidation accelerates.
For New Entrants and Emerging Players: Build out home-based remote monitoring capabilities targeting the 90-day post-discharge window where Medicare Advantage plans in Florida and Arizona pilot subscription reimbursement. Pediatric ICU delirium detection represents the most penetrable segment, with adapted screening instruments gaining traction at Boston Children's Hospital and Cincinnati Children's. Pursue FDA 510(k) clearance for EEG-pharmacology convergence tools as a differentiated go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed digital health specialists possessing FDA-cleared prediction algorithms but lacking hospital GPO distribution channels. Five-to-ten-year viability hinges on reimbursement code expansion for non-pharmacologic prevention bundled into Medicare quality metrics. Monitor quarterly FDA guidance documents on digital therapeutics as the inflection signal for algorithm-based tool commercialization timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates commercial deployment for algorithm-based delirium prediction tools in ICU settings. |
| Hospital System Partnership | Secures recurring telemetry contracts through embedded EHR integration at academic medical centers. |
| Backward Integration into Sensors | Captures hardware margins and reduces dependency on Foxconn and Jabil assembly capacity. |
| Reimbursement Strategy | Aligns prevention protocol pricing with Medicare Hospital-Acquired Condition Reduction Program incentives. |
| Software Companion Development | Extends antipsychotic revenue through pharmacovigilance data capture satisfying EMA surveillance obligations. |
Methodological Framework
A standing panel of geriatric psychiatrists, ICU nursing directors, hospital formulary managers, biomedical engineers, and GPO contract specialists provided ongoing calibration throughout the research cycle. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EMA regulatory submissions, ClinicalTrials.gov protocol registries, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up demand modeling triangulated against top-down epidemiological prevalence estimates.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning psychotropic medication class, care setting, delivery mode, and patient age cohort. CAGRs derived from fitted growth curves incorporating ICU telemetry adoption rates, Medicare penalty expansion timelines, and skilled-nursing facility accreditation mandates. Forecast inputs included PMDA accelerated review pathway decisions and CDSCO streamlined approval timelines for fixed-dose combinations.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified health technology conglomerates or sudden FDA digital therapeutics guidance shifts would shift outcomes. Quarterly review of FDA 510(k) clearance timelines, Medicare Advantage pilot expansion decisions, and EMA post-authorization safety study obligation changes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Anesthesiology
Inhalation Anesthetics Market
Anesthesiology
Aspirating System Market
Anesthesiology
US Anesthesiology Service Market
Anesthesiology
Global Anesthesia Delivery Systems Market
Anesthesiology
Sedation in ICU Setting Market
Anesthesiology
Artificial Airway Holders Market
Anesthesiology
Global Anesthesia and Respiratory Devices Market
Anesthesiology
Epinephrine Market
Anesthesiology
Smart Anesthesia System Market
Anesthesiology
Vasopressin for Vasoplegic Shock Market
Anesthesiology
Anesthesia Delivery Units Market
Anesthesiology
Anesthetics Market
Anesthesiology
Global Inhalation Anesthesia Market
Anesthesiology
Global Anesthesia Gases Market
Anesthesiology
Artificial Coma/Medically Induced Coma Market
Anesthesiology
Anesthesia Breathing Circuits Market