
 Smart Anesthesia System Market | 2026-2036
Smart Anesthesia System Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Anesthesia System Market Insights
Closed-loop anesthesia delivery is redrawing competitive boundaries in the smart anesthesia system sector. GE Healthcare leverages its installed base of patient monitors to sustain recurring software revenue streams. Dräger anchors European hospital procurement through integrated gas delivery platforms. Masimo Corporation differentiates via proprietary pulse oximetry algorithms embedded in anesthesia workstations.
A smart anesthesia system comprises electromechanical delivery hardware, physiologic monitoring sensors, and algorithmic control software that automates anesthetic agent titration based on real-time patient feedback loops. These systems employ minimum alveolar concentration targeting and pharmacokinetic modeling to maintain precise hypnotic depth while minimizing agent consumption. Anesthesia machines with integrated low-flow technology occupy the largest product tier, while artificial intelligence modules represent the fastest-expanding technology segment as vendors embed predictive adverse-event algorithms. Pediatric surgery applications command premium pricing due to narrow therapeutic indices and specialized ventilation protocols.
FDA 510(k) clearance requirements and EU MDR technical documentation standards shape product development timelines and commercial launch sequencing for anesthesia device manufacturers. The EU AI Act risk-classification framework will impose additional conformity obligations on closed-loop decision-support algorithms deployed in European clinical settings. Stakeholders must weigh regulatory capital requirements against the margin compression from hospital value-analysis committees standardizing procurement around integrated platform vendors.
Market Dynamics
Closed-loop automation is compressing the anesthesia workstation supply chain by collapsing monitoring, delivery, and decision-support into unified platforms. Hospital value-analysis committees now mandate AI-enabled safety modules as baseline procurement criteria.
Growth Catalysts
- EU AI Act risk-classification mandates:European tertiary hospitals must upgrade to algorithmic decision-support systems by 2026, forcing replacement cycles for legacy gas delivery platforms.
- Pediatric surgical volume concentration:Specialized children's hospitals in the United States and Japan are procuring precision-targeted anesthesia systems with narrow therapeutic index protocols.
- Low-flow volatile anesthetic conservation:Integrated breathing circuit technology reduces agent consumption by 40-60% per procedure, aligning with hospital sustainability procurement scorecards.
Market Restraints
- EU MDR technical documentation burden:Conformity assessment timelines for closed-loop software modules now extend 18-24 months, freezing product launch sequencing.
- Sevoflurane and desflurane supply concentration:Three chemical manufacturers control 80% of global volatile anesthetic production, exposing device vendors to input cost volatility.
- Biometric sensor interoperability gaps:Proprietary pulse oximetry algorithms from incumbent monitor manufacturers block third-party anesthesia workstation integration.
Strategic Opportunities
- Ambulatory surgical center penetration in Germany:Outpatient facilities remain underpenetrated for AI-enabled anesthesia platforms, presenting white-space expansion for integrated system vendors.
- Predictive adverse-event algorithm bundling:Machine learning modules for hypotension prediction and respiratory depression alerts create new recurring revenue streams alongside hardware sales.
- Japan METI carbon-neutral hospital incentives:Government subsidies for low-flow anesthesia technology adoption accelerate procurement cycles in tertiary care networks.
Industry Challenges
- Clinical validation timeline compression:FDA 510(k) clearance for novel closed-loop control algorithms requires prospective patient studies that extend development cycles 12-18 months.
- Anesthesiologist workflow retraining:Automated titration systems demand new competency certifications, creating adoption friction in academic medical centers with entrenched training protocols.
- Legacy monitor integration complexity:Hospital IT infrastructure fragmentation forces costly middleware development for anesthesia workstations to communicate with existing EMR systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Anesthesia System Market |
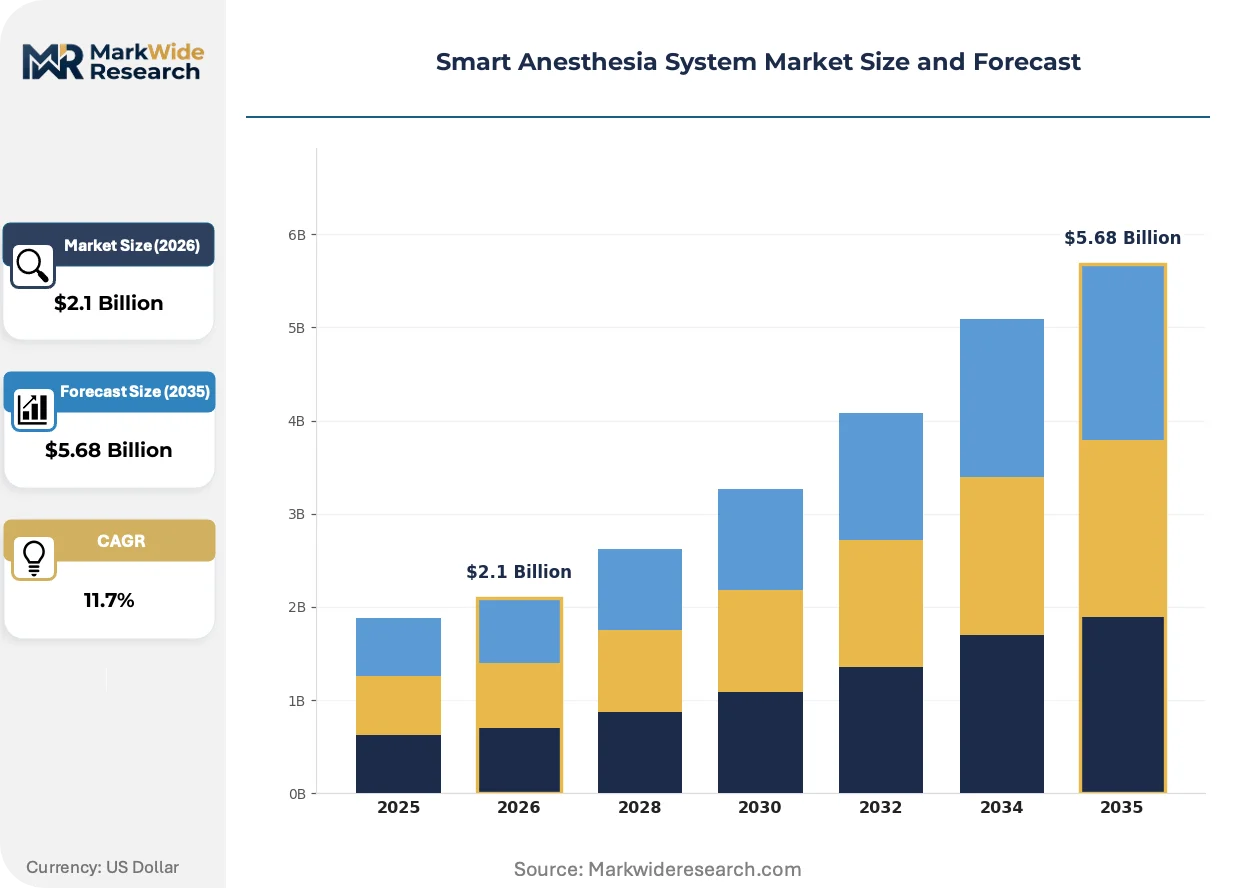
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.68 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anesthesia Machines, Monitors, Delivery Systems, Software Solutions End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Laboratories Technology: Low-flow Anesthesia, Automation, Real-time Monitoring, Artificial Intelligence Application: Pediatric Surgery, Orthopedic Surgery, Cardiac Surgery, Emergency Procedures |
| Companies Covered | Koninklijke Philips N.V., Masimo Corporation, Mindray Global, Siemens Healthineers, Medtronic, GE Healthcare, Smiths Medical, Hamilton Medical, Dräger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Anesthesia System Market Trends and Innovations
Algorithmic control architectures are fragmenting the competitive landscape between integrated platform vendors and specialized AI module suppliers. Three developments are compressing product development cycles and reshaping procurement criteria.
Pharmacokinetic modeling software is bifurcating the anesthesia delivery market. Tertiary care networks in the United States are deploying patient-specific propofol and remifentanil target-controlled infusion systems at accelerated replacement cycles. This technology is bifurcating hardware margins by shifting value capture toward software licensing and algorithm updates.
FDA premarket review pathways for closed-loop physiological control systems now mandate adaptive algorithm transparency documentation. Device manufacturers must submit source code audits and real-world performance monitoring protocols, extending clearance timelines. Pediatric anesthesia applications face the most stringent scrutiny due to narrow therapeutic indices and off-label use risks.
Hospital procurement committees are unbundling anesthesia workstation purchasing from gas delivery contracts. Value-analysis teams in Germany and Japan now separate monitor, ventilator, and vaporizer sourcing decisions, compressing vendor lock-in. This pattern is most visible in United States academic medical centers consolidating purchasing through regional group purchasing organizations.
Smart Anesthesia System Market Segmentation
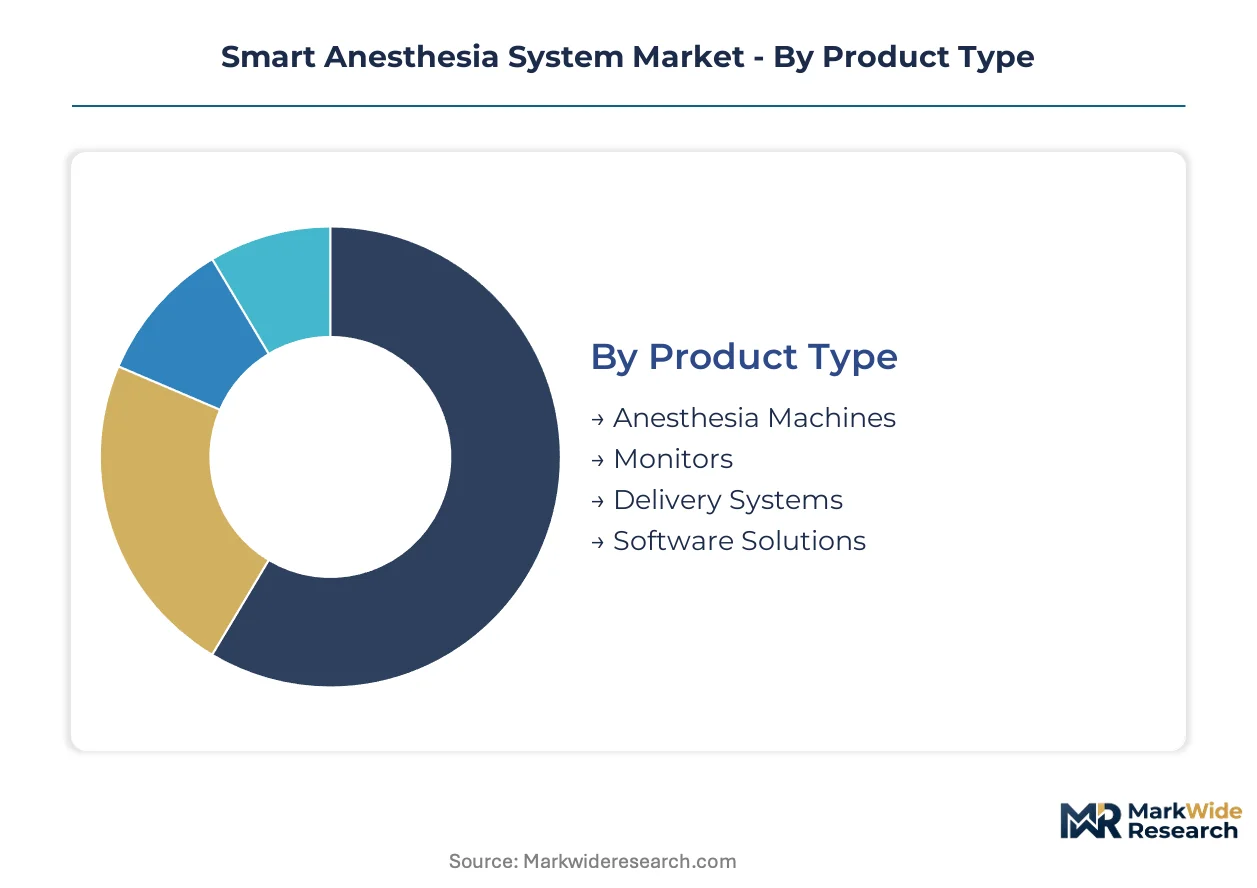
Segmentation in the smart anesthesia system market reveals how substitution pressures reshape procurement patterns. Hospital value-analysis committees now unbundle integrated platforms, creating discrete purchasing decisions across hardware, software, and monitoring layers.
Product Type:
Anesthesia machines face the most acute substitution threat as modular software solutions displace integrated hardware in cost-conscious procurement cycles.
- Anesthesia Machines:Electromechanical platforms integrating gas delivery, ventilation, and vaporization functions. Tertiary care networks in the United States concentrate replacement demand around closed-loop control architectures that reduce anesthesiologist cognitive load during complex procedures.
- Monitors:Physiologic sensing arrays tracking hypnotic depth, hemodynamics, and respiratory parameters. German university hospitals drive procurement of multi-parameter platforms with embedded AI alert algorithms that satisfy EU AI Act risk-classification mandates.
- Delivery Systems:Target-controlled infusion pumps and vaporizer modules.
- Software Solutions:Pharmacokinetic modeling and predictive adverse-event algorithms.
Anesthesia machines anchor the volume base while software solutions gain share at the steepest rate.
End User:
Cost tier stratification dominates this dimension, with reimbursement differentials creating sharp procurement behavior divergence across facility types.
- Hospitals:Acute care institutions with 24-hour surgical services and residency programs. Japanese tertiary networks accelerate procurement through METI carbon-neutral subsidies that favor low-flow anesthesia workstation upgrades.
- Ambulatory Surgical Centers:Outpatient facilities performing same-day procedures. German ASCs remain underpenetrated for AI-enabled platforms, presenting white-space expansion as regional purchasing cooperatives consolidate.
- Clinics:Office-based surgical facilities with limited anesthesia capabilities.
- Research Laboratories:Academic and commercial sites conducting anesthesia pharmacology studies.
Hospitals capture the dominant revenue share while ambulatory surgical centers expand most quickly as outpatient migration accelerates.
Technology:
Maturity gradients separate established low-flow methods from emerging AI architectures still navigating regulatory validation timelines.
- Low-flow Anesthesia:Breathing circuit designs minimizing fresh gas flow and volatile agent consumption. Sustainability procurement scorecards in United States health systems mandate this technology for new equipment acquisitions.
- Artificial Intelligence:Machine learning modules for hypotension prediction, depth-of-anesthesia optimization, and respiratory depression alerting. FDA 510(k) clearance requirements for closed-loop control algorithms extend commercialization timelines.
- Automation:Closed-loop titration systems adjusting agent delivery without clinician intervention.
- Real-time Monitoring:Continuous physiologic feedback loops enabling immediate parameter adjustment.
Low-flow anesthesia anchors installed base economics while artificial intelligence commands the steepest expansion trajectory.
Application:
Volume concentration in high-throughput procedures contrasts with premium pricing capture in narrow-therapeutic-index specialties.
- Pediatric Surgery:Neonatal and infant procedures requiring precision-targeted dosing protocols. Specialized children's hospitals in Japan procure systems with customized ventilation algorithms that address developmental physiologic differences.
- Cardiac Surgery:Procedures demanding hemodynamic stability through cardiopulmonary bypass. United States academic medical centers concentrate demand for integrated platforms combining bypass management with anesthetic depth control.
- Orthopedic Surgery:High-volume joint replacement and trauma procedures.
- Emergency Procedures:Rapid-sequence induction contexts with limited preoperative assessment.
Orthopedic surgery anchors procedure volume while pediatric surgery captures the highest per-procedure system pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export dependence on volatile anesthetic agents shapes import strategies across major economies. The United States runs a structural deficit in closed-loop anesthesia hardware, sourcing integrated platforms from European and Asian manufacturers. Germany and Japan maintain trade surpluses in precision delivery systems, capitalizing on established med-tech industrial bases.
United States
Tertiary care networks in the United States concentrate replacement demand for AI-enabled anesthesia workstations. FDA 510(k) clearance requirements for closed-loop control algorithms extend product launch timelines by 12-18 months. The Boston-Cambridge corridor anchors development activity for pharmacokinetic modeling software targeting academic medical centers.
Germany
German university hospitals drive procurement of multi-parameter monitoring platforms with embedded AI alert algorithms. EU MDR technical documentation standards and the EU AI Act risk-classification framework impose 18-24 month conformity assessment timelines. The Baden-Württemberg industrial cluster around Tübingen and Stuttgart concentrates vaporizer manufacturing and gas delivery engineering expertise.
Japan
Japanese tertiary networks accelerate procurement through METI carbon-neutral hospital subsidies favoring low-flow anesthesia technology. PMDA premarket approval pathways for closed-loop physiological control systems mandate adaptive algorithm transparency documentation. The Kanto region around Tokyo hosts specialized children's hospitals procuring precision-targeted systems for narrow therapeutic index protocols.
United Kingdom
UK academic medical centers consolidate purchasing through regional group purchasing organizations, unbundling anesthesia workstation decisions from gas delivery contracts. MHRA recognition of EU MDR certificates streamlines market access for continental manufacturers. The Oxford-Cambridge-London golden triangle concentrates digital health research partnerships between NHS trusts and algorithm developers.
China
China's NMPA medical device registration pathways for Class III anesthesia equipment require domestic clinical trials, extending market entry timelines for foreign vendors. Hospital procurement in the Yangtze River Delta prioritizes cost-competitive low-flow systems over premium AI-enabled platforms. Shanghai-based medical device distributors increasingly serve as gatekeepers for international manufacturers seeking provincial hospital access.
Smart Anesthesia System Market Competitive Landscape
Listed leaders compete with private specialists across software licensing and hardware integration dimensions. The vendor base stratifies into three tiers: diversified health conglomerates with anesthesia as a product line, dedicated respiratory and monitoring specialists, and emerging AI module suppliers. Archetypes include integrated platform vendors leveraging installed monitor bases, European engineering-focused gas delivery specialists, and algorithm developers seeking hardware partnerships. Competitive moves center on strategic partnerships between software developers and established device manufacturers, plus portfolio diversification into pediatric-specific protocols.
Within the integrated platform tier, GE Healthcare and Dräger occupy positions exemplifying divergent geographic anchoring strategies. Masimo Corporation represents the monitoring-centric archetype, embedding proprietary pulse oximetry algorithms into anesthesia workstation partnerships. Siemens Healthineers and Philips N.V. sit within the diversified conglomerate tier, leveraging cross-modal imaging and critical care portfolios to bundle anesthesia systems into enterprise-wide procurement contracts.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Masimo Corporation |
| Mindray Global |
| Siemens Healthineers |
| Medtronic |
| GE Healthcare |
| Smiths Medical |
| Hamilton Medical |
| Dräger |
| Others |
Pricing and Supply Chain Analysis
FDA 510(k) clearance requirements gate both supplier qualification and price stratification in the smart anesthesia system sector, forcing vendors to absorb extended validation costs into premium tiering while hospital value-analysis committees exploit unbundled procurement to compress mid-market pricing.
Pricing Analysis
Hospital value-analysis committees anchor three-tier pricing structure across premium, standard, and economy levels in anesthesia workstation procurement. Price differentiation separates FDA-cleared closed-loop systems from CE-marked configurations and non-certified legacy platforms. Cost compression in the standard tier intensifies because German and Japanese regional purchasing cooperatives consolidate volume negotiations. Ambulatory surgical centers in Germany exhibit the highest price sensitivity, while United States academic medical centers prioritize certification grade over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for volatile anesthetic agent precursors sourced from Chinese chemical manufacturers. Supply concentrates in Germany for precision vaporizer engineering, Japan for compact integrated platform assembly, and the United States for pharmacokinetic modeling software development. Raw material dependencies include sevoflurane and desflurane active pharmaceutical ingredients, medical-grade aluminum for breathing circuits, and semiconductor components for sensor arrays. Single-source vulnerability in volatile anesthetic production exposes device vendors to input cost volatility. Distribution runs through regional group purchasing organizations in the United States and hospital procurement consortia in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospital value-analysis committees in the United States and Germany, fragmenting vendor lock-in as unbundled procurement separates hardware, software, and monitoring layer decisions.
For Market Incumbents: Fortify installed base retention by embedding proprietary pulse oximetry algorithms into anesthesia workstation partnerships and deepening backward integration into low-flow breathing circuit manufacturing. GE Healthcare and Dräger face substitution threat from modular AI module suppliers unbundling decision-support software from gas delivery hardware. Certification investment in FDA 510(k) adaptive algorithm transparency documentation remains the critical defensive lever. For New Entrants and Emerging Players: Predictive adverse-event algorithm bundling gaps in incumbent service layers offer white-space entry points for specialized AI developers. German ambulatory surgical centers remain the most penetrable geography, with outpatient facilities under-served by integrated platform vendors. A software-first go-to-market angle partnering with established monitor manufacturers bypasses capital-intensive hardware development cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed anesthesia software specialists holding FDA-cleared pharmacokinetic modeling modules. Long-term viability across the analysis window hinges on regulatory moat sustainability and hospital IT integration depth. Watch FDA premarket review pathway expansions for closed-loop physiological control systems as the inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Closed-Loop Algorithms | Clearance mandates from the FDA gate commercial launch sequencing for AI-enabled titration systems in United States tertiary networks. |
| EU MDR Conformity Assessment Completion | Technical documentation standards from the EU MDR impose 18-24 month timelines that freeze product launch sequencing for European entry. |
| Hospital System Partnership for Integrated Platform Deployment | Regional purchasing cooperatives in Germany and Japan consolidate procurement decisions around vendors offering unified gas delivery and monitoring architectures. |
| Software Companion Development for Predictive Adverse-Event Alerting | Machine learning modules for hypotension prediction create recurring revenue streams alongside hardware sales in United States academic medical centers. |
| Reimbursement Strategy for Pediatric Precision-Targeted Protocols | Narrow therapeutic index applications in Japanese children's hospitals command premium pricing through specialized ventilation algorithm customization. |
Research Methodology
A standing panel of anesthesiologists, hospital biomedical engineers, group purchasing organization contract managers, and anesthesia device regulatory affairs leads provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR technical documentation filings, Japanese METI carbon-neutral hospital subsidy records, and hospital procurement database extracts. Bottom-up triangulation across equipment replacement cycle surveys and top-down reconciliation against volatile anesthetic agent consumption statistics ensured cross-verification.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling spanned product type, end-user facility tier, technology maturity gradient, and application-specific therapeutic index requirements. CAGRs were derived from fitted growth curves applied to replacement cycle data and procurement pipeline tracking. Industry-specific forecast inputs included EU AI Act risk-classification mandate compliance deadlines and METI subsidy program uptake rates in Japanese tertiary networks.
Material uncertainties — regulatory timeline delays, volatile anesthetic supply disruptions, and hospital IT infrastructure fragmentation — sit outside the modeled envelope. Forecasts reflect assumptions about closed-loop algorithm adoption velocity and unbundled procurement persistence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Anesthesiology
Global Anesthesia Gases Market
Anesthesiology
Sedation in ICU Setting Market
Anesthesiology
Global Inhalation Anesthesia Market
Anesthesiology
Airway Catheters Market
Anesthesiology
Aspirating System Market
Anesthesiology
Epinephrine Market
Anesthesiology
Global Anesthesia Endotracheal Tubes Market
Anesthesiology
Anesthesia Delivery Units Market
Anesthesiology
Anesthesia Breathing Bags Market
Anesthesiology
Endotracheal Tube Cuffs Market
Anesthesiology
Artificial Coma/Medically Induced Coma Market
Anesthesiology
Anesthesia CO2 Absorbent Market
Anesthesiology
Artificial Airway Holders Market
Anesthesiology
Anesthesia Breathing Circuits Market
Anesthesiology
Global Anesthesia Delivery Systems Market
Anesthesiology
Anaesthesia Machines Market