
 Inhalation Anesthetics Market | 2026-2036
Inhalation Anesthetics Market Size, Share, and Industry Trends Forecast 2026-2036
Inhalation Anesthetics Market Outlook
Ambulatory surgical centers is hardening as the fastest-expanding end-use vertical for inhalation anesthetics, shifting volume away from traditional hospital settings. Baxter leverages its integrated anesthesia portfolio to sustain leadership across volatile agent supply chains. Piramal Enterprises anchors its position through specialized manufacturing of sevoflurane active pharmaceutical ingredients. Fresenius Kabi competes aggressively in the hospital segment with broad distribution networks across Europe and Asia.
Inhalation anesthetics comprise volatile and gaseous pharmaceutical compounds administered via pulmonary uptake to induce reversible loss of consciousness, with sevoflurane, desflurane, and isoflurane representing the primary fluorinated ether agents characterized by specific blood-gas partition coefficients determining induction and emergence kinetics. These agents serve the fundamental purpose of enabling controlled, titratable general anesthesia for surgical procedures requiring unconsciousness, analgesia, and muscle relaxation. Sevoflurane dominates current revenue pools due to its favorable pharmacokinetic profile and low airway irritability, while desflurane captures premium positioning in bariatric and ambulatory settings where rapid emergence commands value. The delivery mode dimension segments into vaporized agents and precision gas mixtures, with vaporized agent systems representing the mature installed base and gas mixture protocols gaining traction in specialized cardiothoracic applications.
The FDA regulates inhalation anesthetics as New Drug Applications with stringent purity specifications for fluorinated ether compounds, while the EMA's Committee for Medicinal Products for Human Use enforces additional environmental risk assessments given the greenhouse gas potency of desflurane and nitrous oxide. ISO 80601-2-13 standards for anesthetic workstation safety shape equipment compatibility requirements and constrain product formulation flexibility. Stakeholders must monitor evolving sustainability mandates from regulators in Germany and France that are beginning to penalize high-global-warming-potential anesthetic agents through procurement restrictions and carbon accounting protocols.
Market Dynamics
The FDA's ongoing safety reviews of anesthetic agents are compressing formulation flexibility while simultaneously accelerating the migration of surgical volume toward ambulatory settings where rapid-emergence agents command premium positioning.
Growth Catalysts
- Sevoflurane pharmacokinetics:Favorable blood-gas partition coefficients and minimal airway irritability are pulling volume away from isoflurane in pediatric and geriatric populations. Ambulatory surgical centers favor this profile for same-day discharge protocols.
- Germany's carbon accounting mandates:Procurement restrictions on high-global-warming-potential agents are creating tiered demand for desflurane alternatives with lower environmental footprints. Hospital pharmacy committees now weight sustainability metrics alongside clinical efficacy.
- Outpatient procedure expansion:Minimally invasive techniques are hardening demand for inhalation anesthetics in settings outside traditional hospital operating rooms. Same-day surgery centers require agents compatible with rapid turnover workflows.
Market Restraints
- Fluorinated ether supply concentration:Active pharmaceutical ingredient manufacturing clusters in India and China create vulnerability to export licensing delays. Piramal Enterprises and select Chinese API houses control critical upstream capacity.
- EMA environmental risk assessments:Additional regulatory layers for desflurane and nitrous oxide are extending approval timelines for new formulations. The F-Gas Regulation compounds compliance burdens across European markets.
- Intravenous anesthetic substitution:Propofol infusion systems are capturing share in short-duration procedures where inhalation delivery infrastructure proves capital-intensive. Total intravenous anesthesia protocols reduce agent consumption per case.
Strategic Opportunities
- Japan's aging surgical population:METI healthcare infrastructure investments are expanding ambulatory surgery capacity in prefectures outside Tokyo and Osaka. Rapid-emergence agents align with geriatric anesthesia safety protocols.
- Closed-circuit anesthesia systems:Convergence of precision vaporizer technology with real-time gas monitoring is enabling reduced fresh gas flows. This dual-technology integration cuts agent consumption and environmental exposure simultaneously.
- India's PLI scheme for pharmaceuticals:Domestic manufacturing incentives are attracting investment in sevoflurane API and finished dosage forms. CDSCO streamlined approvals for locally produced inhalation agents accelerate market access.
Industry Challenges
- Anesthesia workstation interoperability:ISO 80601-2-13 compliance testing creates bottlenecks when introducing reformulated agents. Vaporizer calibration protocols must be revalidated across mixed-vintage installed equipment bases.
- Specialized compounding expertise:Fluorinated ether synthesis requires handling capabilities scarce outside established pharmaceutical manufacturing corridors. CDSCO and FDA inspection backlogs delay qualification of new production sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inhalation Anesthetics Market |
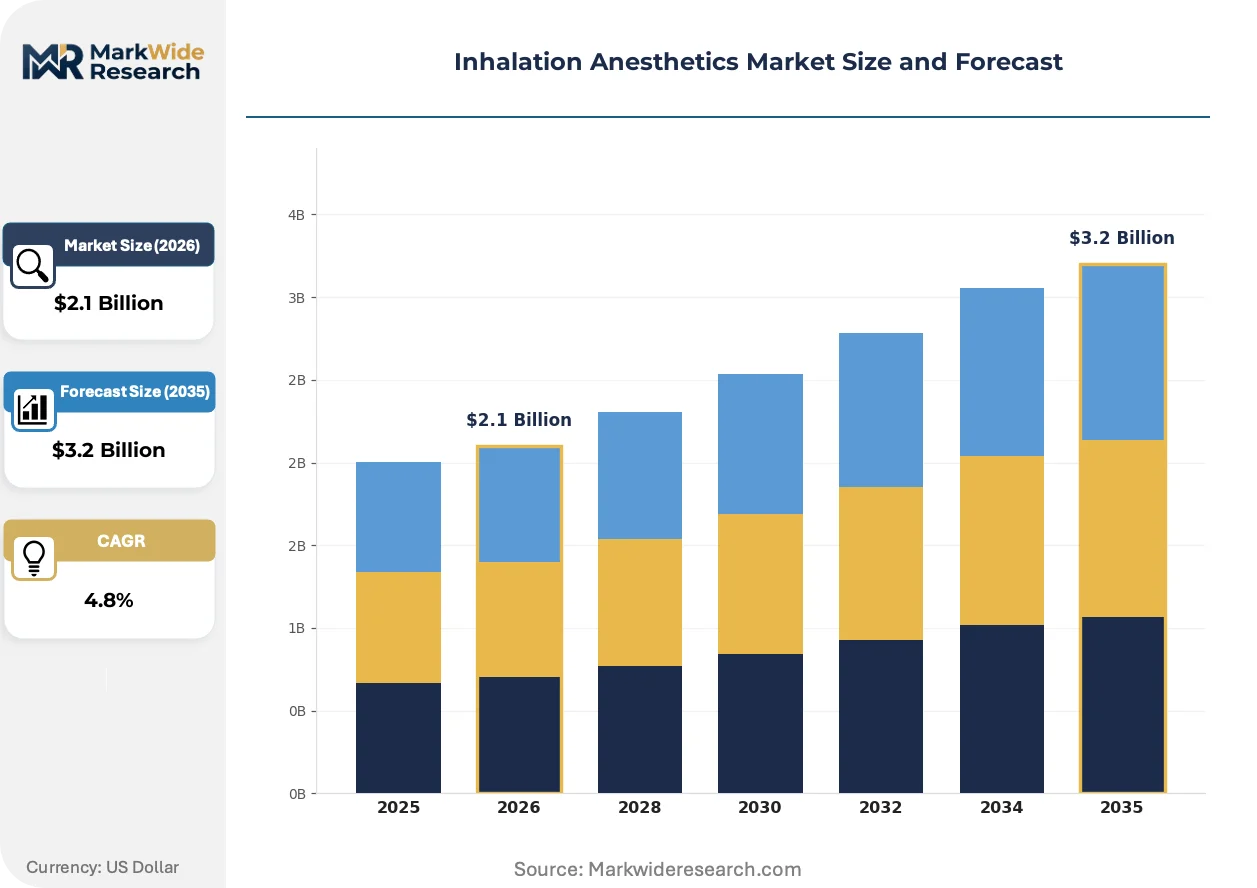
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sevoflurane, Desflurane, Isoflurane, Nitrous Oxide Delivery Mode: Volatile Agents, Vaporized Agents, Gas Mixtures, Others End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Institutions Application: General Surgery, Cardiothoracic Surgery, Dental Surgery, Orthopedic Surgery |
| Companies Covered | Baxter, AbbVie, Fresenius Kabi, Piramal Enterprises, Halocarbon Products Corporation, Lunan Pharmaceutical Group, Dechra Pharmaceuticals, Hikma Pharmaceuticals, Troikaa Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inhalation Anesthetics Market Strategic Shifts
Precision delivery systems and environmental accountability frameworks are simultaneously reshaping product development priorities and procurement criteria across hospital and ambulatory settings.
Closed-circuit anesthesia with automated fresh gas flow optimization is decentralizing agent consumption patterns away from high-flow open systems. Academic medical centers in the United States and university hospitals in Germany are piloting these installations at accelerated procurement cycles. This technology is decentralizing the traditional link between case volume and environmental exposure, enabling carbon footprint reduction without compromising emergence kinetics.
The EU F-Gas Regulation's progressive phase-down schedules for hydrofluorocarbons are forcing reformulation strategies for desflurane-containing products. Pharmaceutical manufacturers must now submit comprehensive lifecycle greenhouse gas assessments alongside traditional safety and efficacy data. The hospital segment across France, Germany, and the Netherlands is responding by elevating sevoflurane in procurement hierarchies and retrofitting vaporizer infrastructure.
Consolidated purchasing through regional health system formularies is compressing vendor relationships and unbundling after-sales service contracts. Integrated delivery networks in the United States are replacing individual hospital pharmacy decisions with centralized committee governance. This concentration is most visible in the Southeast and Midwest regions where Catholic health systems and for-profit chains dominate surgical service line planning.
Inhalation Anesthetics Market Segmentation
Segmentation in inhalation anesthetics reveals how pharmacokinetic properties, delivery infrastructure requirements, and surgical setting economics create distinct competitive battlegrounds. Understanding these divisions exposes where formulation investments concentrate and which customer types command pricing power.
Product Type:
Fluorinated ether chemistry and blood-gas partition coefficients define the clinical utility and environmental footprint of each agent class.
- Sevoflurane:A polyfluorinated methyl isopropyl ether with low blood-gas solubility enabling rapid induction and emergence. Demand concentrates in pediatric anesthesia and ambulatory surgical centers across the United States, where same-day discharge protocols favor its minimal airway irritability and stable hemodynamic profile.
- Desflurane:A highly fluorinated methyl ethyl ether with the lowest blood-gas partition coefficient among volatile agents, supporting ultra-rapid emergence. Bariatric surgery suites and high-turnover ambulatory centers in Germany and France value this profile despite elevated greenhouse gas potency triggering procurement restrictions under carbon accounting mandates.
- Isoflurane:A chlorofluorinated ether with intermediate solubility and established safety data in resource-constrained settings.
- Nitrous Oxide:An inorganic gas with analgesic properties requiring specialized scavenging systems due to occupational exposure risks.
Mature deployment sits with isoflurane in cost-sensitive hospital systems. Newer deployment is concentrated in sevoflurane for ambulatory protocols.
Delivery Mode:
Capital investment requirements and precision control capabilities separate delivery modalities across installed anesthesia workstation bases.
- Volatile Agents:Standard vaporizer-based delivery of liquid fluorinated ethers through calibrated flow systems. Hospitals in the United States and Western Europe maintain extensive installed bases of variable-bypass vaporizers compatible with sevoflurane and desflurane, though interoperability testing under ISO 80601-2-13 creates upgrade friction.
- Vaporized Agents:Precision temperature-compensated vaporization enabling closed-circuit low-flow anesthesia. Academic medical centers in Germany piloting automated fresh gas flow optimization report reduced agent consumption and environmental exposure without compromising emergence kinetics.
- Gas Mixtures:Pre-blended precision gas combinations for specialized cardiothoracic applications requiring controlled hypoxia or hyperoxia.
- Others:Emerging delivery technologies including target-controlled inhalation systems and portable vaporizer units for field anesthesia.
Capital intensity peaks with gas mixture infrastructure. Vaporized agent adoption is climbing fastest where sustainability metrics influence procurement.
End User:
Facility type determines case volume, reimbursement structure, and anesthesia workstation capital availability.
- Hospitals:Integrated surgical departments with 24-hour anesthesia coverage and diversified procedure mix. United States health systems and European university hospitals sustain the largest absolute consumption volumes, though centralized formulary governance is compressing vendor relationships and unbundling service contracts.
- Ambulatory Surgical Centers:Dedicated outpatient facilities optimized for rapid turnover and same-day discharge. This segment is expanding most quickly in Japan's prefectures outside Tokyo and Osaka, where METI infrastructure investments align with geriatric anesthesia safety protocols favoring rapid-emergence agents.
- Clinics:Limited-procedure settings with basic anesthesia capabilities for minor interventions.
- Research Institutions:Specialized facilities requiring precise anesthetic control for experimental protocols and veterinary applications.
Volume concentration remains with hospitals. Steepest expansion trajectory belongs to ambulatory surgical centers capturing migrated outpatient procedures.
Application:
Surgical invasiveness and duration dictate agent selection based on emergence requirements and hemodynamic stability needs.
- General Surgery:Broad abdominal and soft tissue procedures spanning open and laparoscopic approaches. United States hospital systems and European integrated delivery networks drive consistent demand for sevoflurane across diverse case lengths and patient risk profiles.
- Cardiothoracic Surgery:Open-heart and major vascular procedures requiring precise hemodynamic control and potential circulatory arrest. German and French university hospitals favor specialized gas mixture protocols and desflurane for its sympathetic activation profile supporting cardiovascular stability.
- Dental Surgery:Short-duration procedures often combining nitrous oxide analgesia with intravenous sedation.
- Orthopedic Surgery:Extremity and joint procedures with variable positioning requirements and tourniquet management considerations.
Procedure standardization is greatest in general surgery. Technical complexity and specialized gas requirements concentrate in cardiothoracic applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API manufacturing concentrates in India and China, while consumption clusters in the United States, Germany, and Japan where surgical volumes and regulatory sophistication sustain premium agent demand.
United States
Ambulatory surgical centers drive sevoflurane consumption through same-day discharge protocols. The FDA maintains stringent purity specifications for fluorinated ether compounds under New Drug Application pathways. Hospital systems in the Southeast and Midwest consolidate purchasing through integrated delivery networks.
Germany
Carbon accounting mandates reshape procurement hierarchies for desflurane alternatives. The EU F-Gas Regulation imposes progressive phase-down schedules on hydrofluorocarbon-based agents. University hospitals in Bavaria pilot closed-circuit anesthesia with automated fresh gas flow optimization.
Japan
METI healthcare infrastructure investments expand ambulatory surgery capacity in prefectures outside Tokyo and Osaka. The PMDA regulates inhalation agents with emphasis on geriatric anesthesia safety. Rapid-emergence protocols align with aging surgical population requirements in Kansai region facilities.
India
PLI scheme incentives attract domestic manufacturing investment for sevoflurane API and finished dosage forms. The CDSCO streamlines approvals for locally produced inhalation agents. Piramal Enterprises anchors critical upstream capacity in specialized fluorinated ether synthesis.
China
Export licensing controls over fluorinated ether API create supply vulnerability for downstream formulators. The NMPA enforces Good Manufacturing Practice standards for volatile anesthetic production. Manufacturing clusters in coastal provinces face inspection backlogs delaying new site qualifications.
Inhalation Anesthetics Market Competitive Environment
Top-tier vendors anchor integrated anesthesia portfolios, while specialized API manufacturers and regional distributors occupy lower tiers. The market structure reflects supply-side concentration in fluorinated ether synthesis against fragmented downstream formulation. Three archetypes dominate: integrated pharmaceutical conglomerates with vaporizer-to-agent portfolios, specialized API houses controlling upstream fluorinated ether capacity, and regional distributors with hospital segment penetration. Competitive moves center on backward integration into API supply and geographic expansion through distribution partnerships.
Among integrated portfolio holders, Baxter and Fresenius Kabi exemplify the conglomerate archetype with breadth across anesthesia delivery systems. Piramal Enterprises occupies a distinct position as a specialized API manufacturer with concentrated fluorinated ether synthesis capabilities. These three entities represent the competitive spectrum from downstream integration to upstream supply control.
| Leading Market Players |
|---|
| Baxter |
| AbbVie |
| Fresenius Kabi |
| Piramal Enterprises |
| Halocarbon Products Corporation |
| Lunan Pharmaceutical Group |
| Dechra Pharmaceuticals |
| Hikma Pharmaceuticals |
| Troikaa Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Pharmacokinetic performance divergence between rapid-emergence and standard-induction agents manifests in dual pricing architectures and geographically concentrated supply networks. Premium positioning for desflurane in bariatric and ambulatory settings commands elevated margins alongside sevoflurane's volume-driven standard tier, while API manufacturing clusters in India and China constrain downstream formulation flexibility.
Pricing Analysis
Short lead-time premiums for sevoflurane API from Indian manufacturers contrast with discounted spot inventory for isoflurane in cost-sensitive hospital systems. Three-tier pricing structure across premium, standard, and economy levels reflects blood-gas partition coefficient performance, FDA certification tier, and after-sales vaporizer calibration bundling. Pricing pressure stems from EMA environmental risk assessments extending approval timelines. Ambulatory surgical centers exhibit highest price sensitivity; cardiothoracic suites demonstrate lowest sensitivity due to hemodynamic protocol requirements.
Supply Chain Analysis
Single-source vulnerability sits with fluorinated ether API synthesis, where Piramal Enterprises and select Chinese manufacturers control critical upstream capacity. Active pharmaceutical ingredient production concentrates in India, China, and limited European facilities. Raw material dependencies include hydrofluorocarbon feedstocks, specialized catalysts, and high-purity packaging components. Tariff exposure on Chinese API exports creates supply risk. Distribution runs through hospital pharmacy committees and regional GPO contracts in the United States, direct tender systems in Germany, and centralized procurement in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Closed-circuit anesthesia technology is displacing high-flow open systems, creating transition-phase investment windows for stakeholders positioning around automated fresh gas flow optimization and carbon accounting compliance.
For Market Incumbents: Anchor market position through backward integration into sevoflurane API supply and vaporizer infrastructure lock-in. Invest in ISO 80601-2-13 recertification programs to defend installed base against generic vaporizer substitutes. Prioritize sustainability credentials to capture German hospital procurement committees elevating environmental metrics alongside clinical efficacy. For New Entrants and Emerging Players: Enter via India's PLI scheme incentives for domestic fluorinated ether manufacturing, leveraging CDSCO streamlined approvals against FDA inspection backlogs. Target Japan's prefectural ambulatory surgery expansion outside Tokyo and Osaka, where METI infrastructure investments align with rapid-emergence agent demand. Pursue closed-circuit anesthesia system partnerships with academic medical centers piloting automated flow optimization. For Investors and Strategic Acquirers: Exit pathways concentrate in specialized API manufacturers with captive fluorinated ether synthesis capabilities. Long-term viability hinges on regulatory moats around environmental compliance and vaporizer interoperability standards. Watch for EU F-Gas Regulation enforcement intensity as inflection signal for desflurane demand compression and sevoflurane substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Manufacturing | Captive sevoflurane supply secures margin control against Indian and Chinese export licensing volatility. |
| Closed-Circuit Anesthesia System Deployment | Automated fresh gas flow optimization reduces agent consumption and satisfies German carbon accounting mandates. |
| ISO 80601-2-13 Recertification Investment | Vaporizer calibration protocol validation defends installed base against interoperability friction from reformulated agents. |
| Sustainability Credential Development | Lifecycle greenhouse gas assessments enable positioning for French and Dutch procurement restrictions on high-GWP agents. |
| Regional Distribution Partnership Expansion | Direct relationships with Japan's prefectural ambulatory surgery centers capture METI infrastructure investment flows. |
Study Parameters
FDA filings, EMA environmental risk assessments, and hospital procurement databases formed the secondary backbone for this analysis. Primary interviews with anesthesiology department heads, hospital pharmacy directors, GPO contracts managers, and fluorinated ether manufacturing executives validated demand assumptions and supply constraints. Bottom-up and top-down triangulation reconciled vaporizer installed base data with agent consumption patterns across ambulatory and hospital settings.
Bottom-up modeling of sevoflurane, desflurane, and isoflurane volume flows by delivery mode and end-user facility type anchored the analytical framework. Segmentation dimensions included pharmacokinetic profile, anesthesia workstation capital intensity, and regional regulatory cluster. CAGRs derived from procedure volume elasticity to surgical setting expansion and agent substitution dynamics. Forecast inputs incorporated EU F-Gas Regulation phase-down schedules and Japan's geriatric population surgical demand projections.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export licensing disruptions from China and accelerated carbon accounting mandate adoption in Europe. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Anesthesiology
Anesthesia Breathing Circuits Market
Anesthesiology
Airway Catheters Market
Anesthesiology
Delirium Market
Anesthesiology
Anesthesia Delivery Units Market
Anesthesiology
Smart Anesthesia System Market
Anesthesiology
Anesthesia Breathing Bags Market
Anesthesiology
Global Anesthesia and Respiratory Devices Market
Anesthesiology
Artificial Airway Holders Market
Anesthesiology
Artificial Coma/Medically Induced Coma Market
Anesthesiology
Sedation in ICU Setting Market
Anesthesiology
Vasopressin for Vasoplegic Shock Market
Anesthesiology
Global Inhalation Anesthesia Market
Anesthesiology
Endotracheal Tube Cuffs Market
Anesthesiology
Aspirating System Market
Anesthesiology
Global Anesthesia Gases Market
Anesthesiology
Anesthesia CO2 Absorbent Market