
 Anesthesia Delivery Units Market | 2026-2036
Anesthesia Delivery Units Market Size, Share, and Industry Trends Forecast 2026-2036
Anesthesia Delivery Units Market Insights
Polymer composites in breathing circuit housings are replacing traditional metal assemblies and is realigning unit economics across mid-tier product lines. Drägerwerk AG & Co. KGaA leverages captive manufacturing of precision gas mixers to sustain margin structures in European tenders. Mindray Medical International anchors its cost position through in-house production of monitoring modules in Shenzhen. Koninklijke Philips N.V. differentiates via software-integrated ventilation algorithms that occupy the premium anesthesia workstation tier.
An anesthesia delivery unit is a medical system that precisely blends oxygen, nitrous oxide, and volatile anesthetic agents to achieve targeted patient sedation levels, typically controlling gas flow rates within 0.1 to 15 liters per minute through electromechanical vaporizers and breathing circuits. Its primary purpose is to enable safe, controllable unconsciousness during surgical procedures while maintaining respiratory support and real-time physiological monitoring. General anesthesia machines represent the mature revenue core where replacement cycles drive predictable demand, while portable anesthesia devices are capturing faster growth as ambulatory surgical centers expand their service breadth. Software solutions embedded in anesthesia workstations are emerging as the highest-margin segment, with recurring license revenue offsetting hardware commoditization in gas delivery systems.
FDA premarket notification requirements under 21 CFR 892.1970 govern anesthesia apparatus classification and shape new product development timelines for US market access. EMA's Medical Device Regulation and ISO 80601-2-13 standards for basic safety and essential performance of anesthesia workstations create layered compliance obligations that filter out undercapitalized competitors. Stakeholders must monitor how AI-enabled closed-loop anesthesia control algorithms trigger new software validation pathways across multiple regulatory jurisdictions.
Market Dynamics
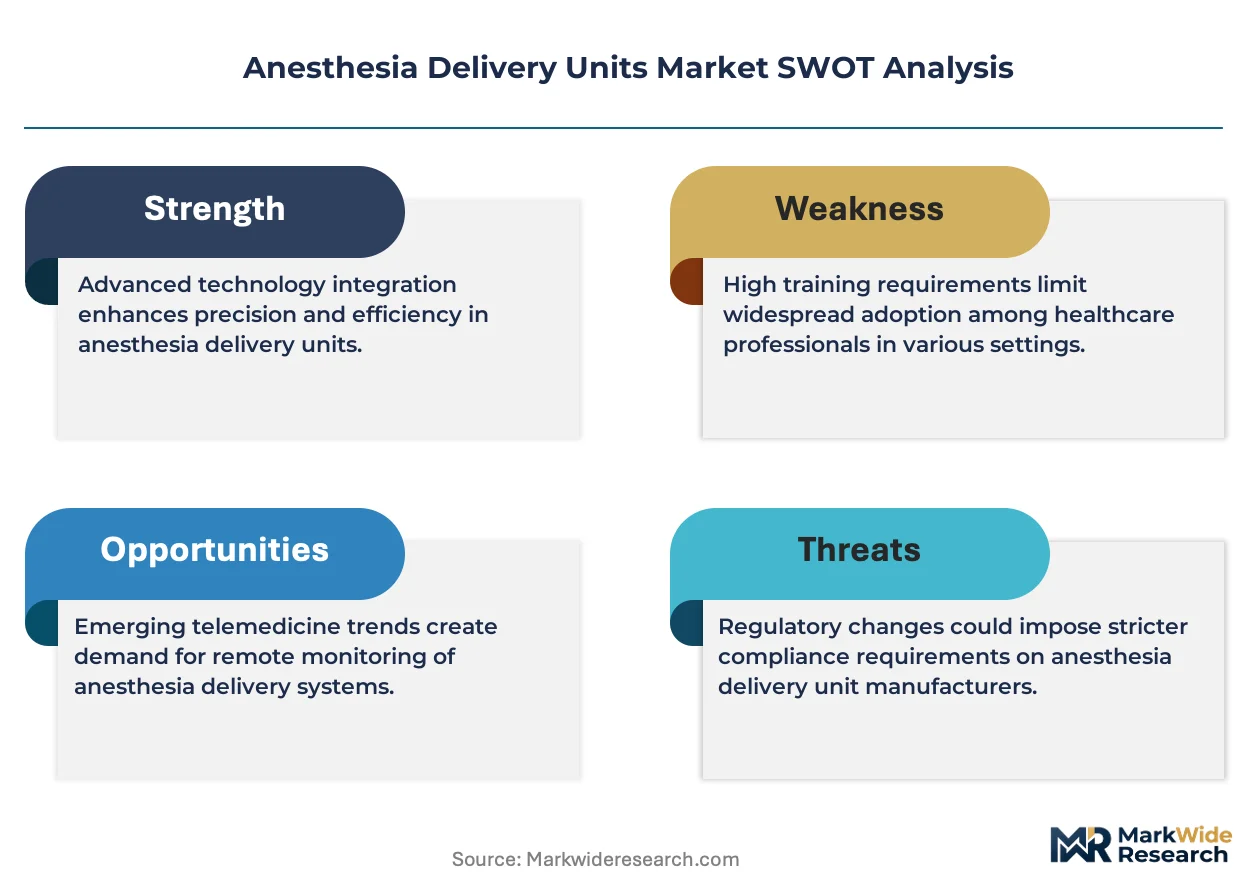
Integrated anesthesia workstations are capturing procurement budgets as hospitals prioritize connected gas delivery systems capable of real-time physiological monitoring and automated record-keeping during surgical procedures.
Growth Catalysts
- Surgical Volume Rebound:Hospital systems in the United States are expanding operating theater capacity to address procedure backlogs accumulated during pandemic-era delays, directly lifting capital equipment procurement cycles for anesthesia infrastructure.
- EMA Medical Device Regulation:The MDR's enhanced clinical evidence requirements for Class IIb devices are filtering out marginal competitors, concentrating demand among certified manufacturers capable of sustaining compliance documentation.
- Polymer Composite Adoption:Breathing circuit housings manufactured from advanced polymer composites are replacing metal assemblies, reducing unit weight and enabling modular workstation designs that simplify field servicing.
Market Restraints
- Precision Component Concentration:Electromechanical vaporizers and gas mixer subassemblies rely on specialized machining capabilities concentrated in German and Swiss precision manufacturing clusters, creating supply vulnerability.
- FDA Premarket Notification Burden:21 CFR 892.1970 classification requirements impose documentation and testing costs that extend development timelines by 18-24 months for new market entrants.
- Volatile Anesthetic Agent Substitution:Intravenous anesthesia protocols using propofol and remifentanil combinations are capturing select ambulatory procedures, compressing addressable demand for inhalational delivery systems.
Strategic Opportunities
- Ambulatory Surgical Center Expansion:Freestanding ASCs in the United States are modernizing procedure suites to capture higher-acuity cases previously restricted to hospital settings, creating demand for compact anesthesia workstations.
- AI-Enabled Closed-Loop Control:Automated anesthesia depth management algorithms are converging with existing monitoring platforms, opening software licensing revenue streams that offset hardware margin compression.
- University Hospital Modernization:German academic medical centers are prioritizing connected operating theater infrastructure as part of federally supported digital health initiatives.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Cross-functional expertise combining anesthesia physiology, electromechanical systems, and software validation is concentrated among experienced practitioners nearing retirement.
- Legacy System Integration Complexity:Hospital information system interoperability requirements demand customized middleware development for each major electronic health record platform.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anesthesia Delivery Units Market |
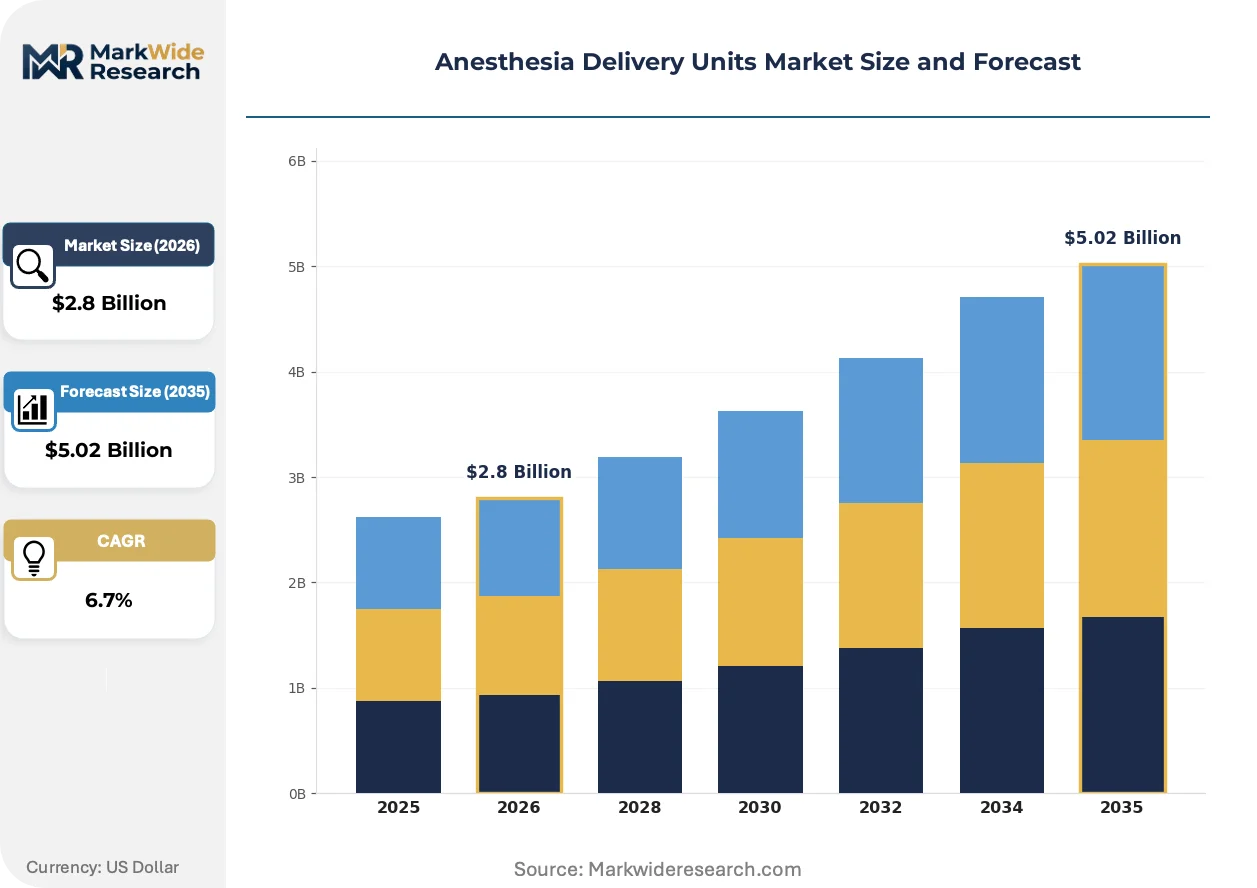
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: General Anesthesia Machines, Regional Anesthesia Systems, Portable Anesthesia Devices, Anesthesia Workstations Application: Dental Surgery, Pain Management, Cardiothoracic Procedures, Emergency Care End User: Hospitals, Ambulatory Surgical Centers, Research Laboratories, Clinics Technology: Electromechanical Systems, Monitoring Equipment, Gas Delivery Systems, Software Solutions |
| Companies Covered | General Electric, Drägerwerk AG & Co. KGaA, Medtronic, Koninklijke Philips N.V., Mindray Medical International, ICU Medical, Getinge AB, Teleflex Incorporated, MAQUET Holding B.V. & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anesthesia Delivery Units Market Trends and Innovations
Software-integrated ventilation algorithms and closed-loop control systems are displacing manual gas delivery adjustments, while material substitution in breathing circuits and evolving procurement models reshape competitive positioning across product tiers.
Closed-loop anesthesia control systems incorporating bispectral index monitoring and automated propofol infusion are expanding into university hospital networks and high-volume surgical centers seeking standardized sedation protocols. These systems reduce anesthesiologist cognitive load during lengthy procedures. The technology is expanding into mid-tier product lines as component costs decline and liability frameworks mature.
The FDA's software validation guidance for AI-enabled medical devices under 21 CFR 820 is elevating documentation requirements for algorithm-driven anesthesia systems. Manufacturers must demonstrate robustness across patient phenotypes and surgical contexts. European manufacturers are responding by establishing dedicated US regulatory affairs functions to accelerate premarket notification preparation.
Equipment-as-a-service contracts are displacing traditional capital purchase arrangements among US hospital systems seeking to convert anesthesia workstation investments from balance-sheet assets to operational expenditures. Original equipment manufacturers are unbundling hardware, software licensing, and preventive maintenance into multi-year subscription structures. This shift is most visible in integrated delivery networks consolidating procurement across multiple surgical facilities.
Anesthesia Delivery Units Market Segmentation
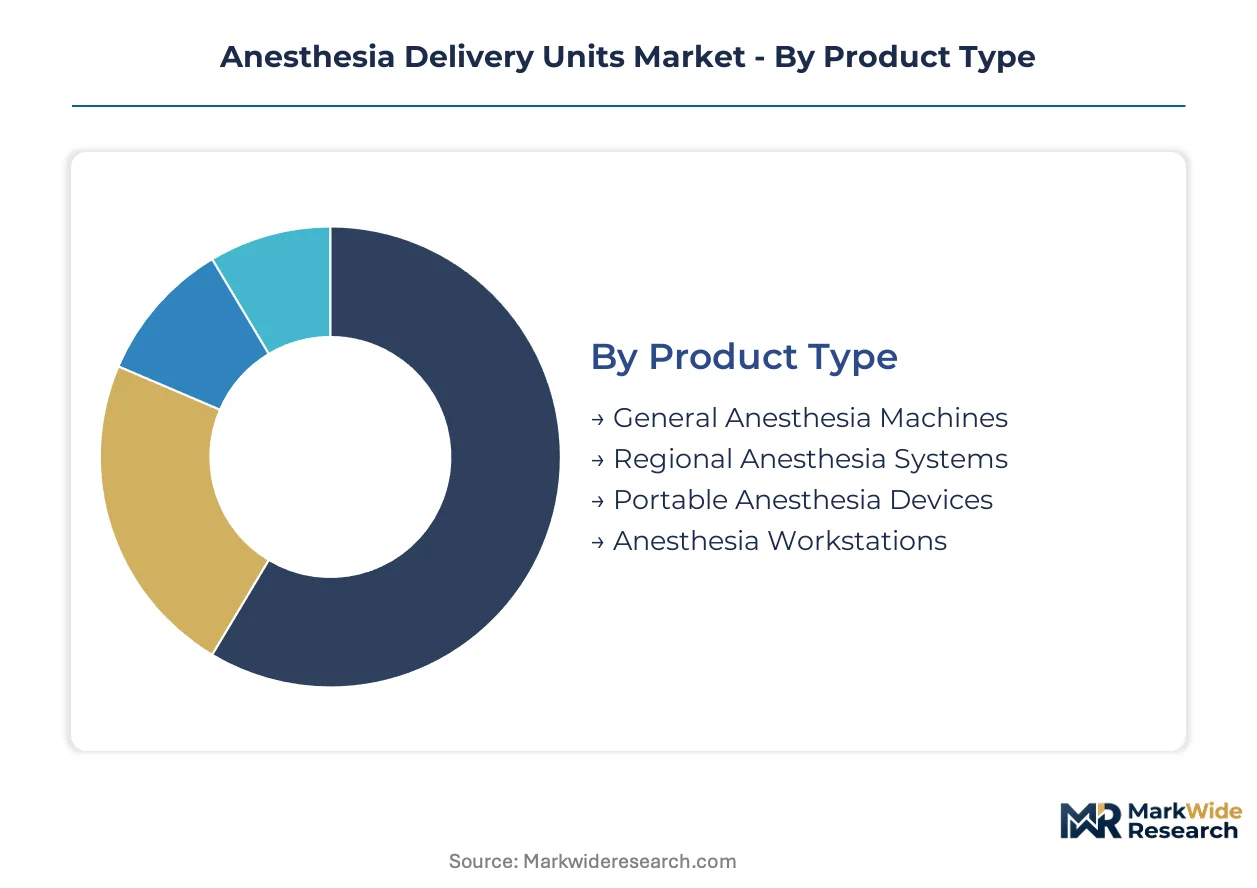
Anesthesia delivery units segment across multiple dimensions that determine procurement priorities, regulatory pathways, and margin structures. Product architecture, clinical application, and technology integration each create distinct competitive battlegrounds with divergent growth trajectories.
Product Type:
Customization intensity spans from standardized portable units to highly configurable integrated workstations, with configuration flexibility directly correlating to price tier and service contract value.
- General Anesthesia Machines:Full-featured systems integrating vaporizers, ventilators, and scavenging systems for inhalational anesthesia delivery. Demand concentrates in United States hospital systems addressing surgical backlog expansion, constrained by extended replacement cycles of 10-15 years that compress annual unit volume.
- Anesthesia Workstations:Modular platforms combining gas delivery, physiological monitoring, and automated record-keeping capabilities. German university hospitals are prioritizing these systems for operating theater modernization under digital health infrastructure programs, driving premium-tier procurement.
- Regional Anesthesia Systems:Dedicated platforms for neuraxial and peripheral nerve block delivery with precise pressure sensing.
- Portable Anesthesia Devices:Compact battery-powered units for field and transport applications.
Leading the category by volume: General Anesthesia Machines. Expanding most quickly: Anesthesia Workstations.
Application:
Procedure acuity determines equipment specification requirements, with high-complexity interventions demanding redundant safety systems and low-acuity settings prioritizing footprint efficiency.
- Cardiothoracic Procedures:High-flow anesthesia delivery supporting cardiopulmonary bypass and one-lung ventilation protocols. United States academic medical centers concentrate demand for these systems, driven by rising coronary artery bypass graft volumes and minimally invasive valve replacement adoption.
- Emergency Care:Rapid-sequence induction capabilities with automated ventilation support for trauma and critical airway management. Demand is accelerating in Level I trauma centers across the United States as emergency department surgical capabilities expand.
- Dental Surgery:Nitrous oxide sedation systems with scavenging for outpatient oral procedures.
- Pain Management:Targeted drug delivery platforms for chronic and acute pain intervention suites.
Cardiothoracic Procedures commands the highest average selling prices. Emergency Care is gaining share fastest as pre-hospital capabilities expand.
End User:
Capital availability and procurement sophistication vary sharply across settings, with consolidated health systems leveraging multi-year service contracts unavailable to independent operators.
- Hospitals:Integrated delivery networks with centralized biomedical engineering and standardized EHR platforms. United States hospital systems are expanding anesthesia workstation fleets as surgical volumes rebound from pandemic-era deferrals, prioritizing connected systems with automated documentation.
- Ambulatory Surgical Centers:Freestanding facilities capturing higher-acuity cases previously restricted to hospital settings. United States ASCs are modernizing procedure suites with compact anesthesia workstations, constrained by limited capital budgets and space constraints.
- Research Laboratories:Preclinical and clinical trial settings requiring precise gas control for protocol standardization.
- Clinics:Office-based settings with basic sedation requirements for minor procedures.
Hospitals dominate absolute unit demand. Ambulatory Surgical Centers show the steepest expansion trajectory as case migration accelerates.
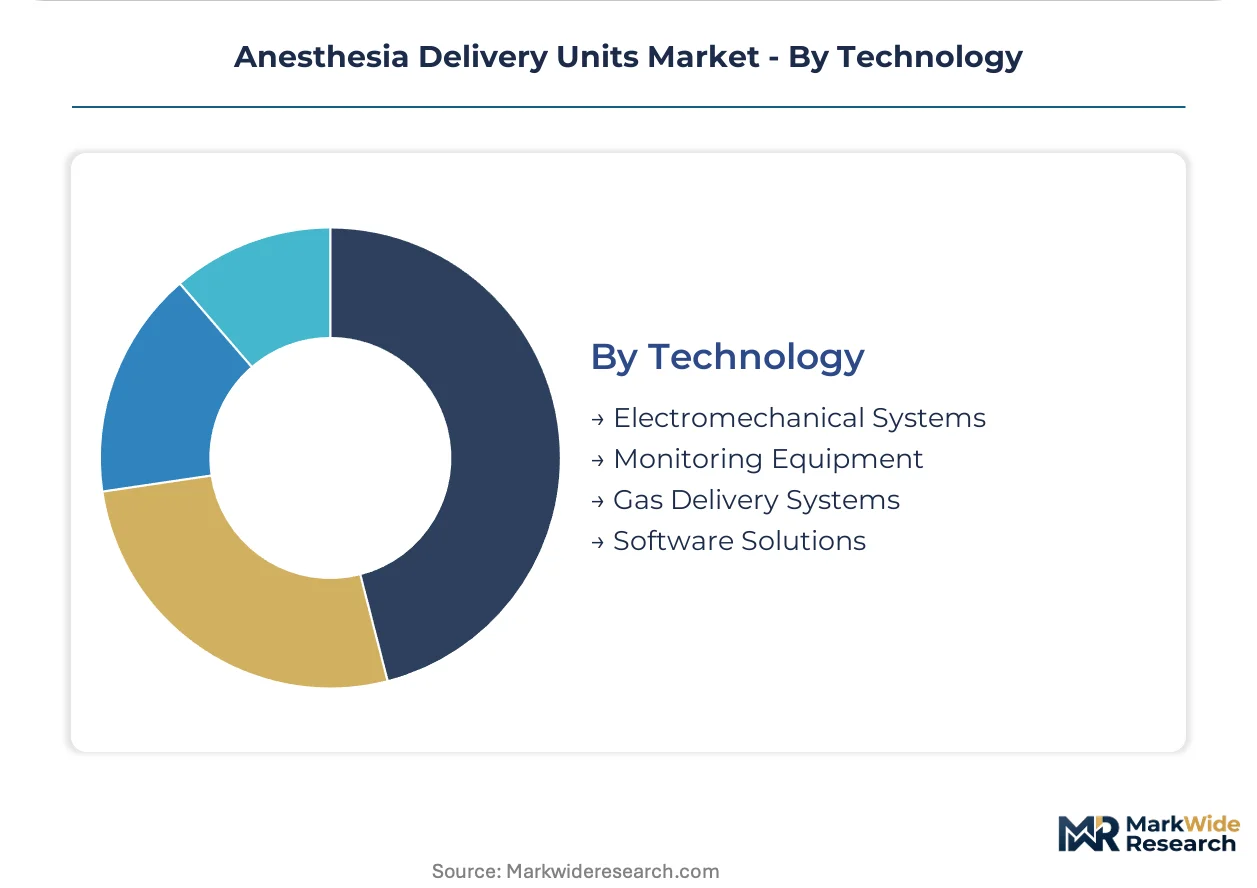
Technology:
Hardware commoditization is elevating software and monitoring components as primary margin sources, with gas delivery mechanics becoming increasingly standardized.
- Software Solutions:Embedded control algorithms, automated record-keeping, and AI-enabled closed-loop anesthesia management. These components generate recurring license revenue that offsets hardware margin compression, with FDA 21 CFR 820 validation requirements creating barriers to rapid competitive entry.
- Monitoring Equipment:Integrated physiological parameter sensing including capnography, pulse oximetry, and anesthetic agent analysis. Demand concentrates in premium workstation configurations where real-time data integration supports clinical decision support.
- Electromechanical Systems:Precision vaporizers and flow control valves with specialized machining requirements.
- Gas Delivery Systems:Oxygen, nitrous oxide, and medical air sourcing with pressure regulation.
Gas Delivery Systems provides the installed base foundation. Software Solutions delivers the fastest-climbing margin contribution as licensing models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized manufacturing zones in southern Germany concentrate precision gas mixer production for anesthesia delivery systems, drawing component suppliers into clustered supply networks around Stuttgart and Tübingen.
United States
Hospital systems in Texas and Florida are expanding operating theater capacity to address surgical backlogs accumulated during pandemic-era deferrals. FDA premarket notification requirements under 21 CFR 892.1970 extend development timelines for new market entrants by 18-24 months. The Minneapolis-St. Paul medical device corridor hosts established anesthesia workstation manufacturers with integrated service networks.
Germany
University hospitals in Bavaria and Baden-Württemberg are modernizing operating theater infrastructure under federally supported digital health initiatives. EMA Medical Device Regulation compliance documentation filters out undercapitalized competitors from European tenders. The Tübingen-Stuttgart precision manufacturing cluster supplies electromechanical vaporizer subassemblies to workstation assemblers.
China
Tier-1 hospitals in Shanghai and Beijing are importing premium anesthesia workstations while domestic manufacturers capture mid-tier demand in provincial cities. NMPA registration requirements for Class II medical devices create layered approval pathways for multinational entrants. The Shenzhen electronics manufacturing hub enables in-house production of monitoring modules for cost-competitive system integration.
Japan
Academic medical centers in Tokyo and Osaka are adopting closed-loop anesthesia control systems for standardized sedation protocols. PMDA software validation guidance elevates documentation requirements for AI-enabled medical devices. The Nagoya industrial corridor maintains specialized machining capabilities for precision flow control valve production.
India
Corporate hospital chains in Maharashtra and Karnataka are upgrading anesthesia infrastructure as surgical volumes expand in metro markets. CDSCO medical device registration timelines shape product launch sequencing for multinational suppliers. The Delhi-Mumbai industrial corridor hosts contract manufacturers assembling portable anesthesia devices for domestic and export markets.
Anesthesia Delivery Units Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated workstation vendors commanding premium pricing while regional assemblers compete on delivery speed for portable units. The vendor base concentrates among three strategic archetypes: diversified medical technology conglomerates with captive anesthesia divisions, pure-play anesthesia specialists leveraging precision manufacturing heritage, and emerging Asian manufacturers exploiting modular component sourcing. Consolidation pressure is accelerating through strategic partnerships between gas delivery component suppliers and monitoring platform developers, alongside geographic expansion via distribution licensing in underserved markets.
Within the diversified medical technology tier, General Electric and Medtronic occupy positions anchored by broad hospital system relationships and integrated service networks. Drägerwerk AG & Co. KGaA exemplifies the precision manufacturing specialist archetype with German heritage in breathing gas technologies. Mindray Medical International represents the cost-optimized Asian manufacturer segment, leveraging Shenzhen-based production capabilities for competitive positioning in price-sensitive procurement environments.
| Leading Market Players |
|---|
| General Electric |
| Drägerwerk AG & Co. KGaA |
| Medtronic |
| Koninklijke Philips N.V. |
| Mindray Medical International |
| ICU Medical |
| Getinge AB |
| Teleflex Incorporated |
| MAQUET Holding B.V. & Co. KG |
| Others |
Pricing and Supply Chain Analysis
Family-owned precision manufacturers in southern Germany anchor electromechanical vaporizer production, translating captive machining capabilities into pricing discipline that resists commoditization pressure from Asian modular assemblers. Their long-tenured supplier relationships with university hospital procurement networks reinforce contract stability even as equipment-as-a-service models reshape downstream payment structures.
Pricing Analysis
Short-lead-time premiums for precision gas mixer subassemblies command substantial markups over standard-cycle procurement, while spot inventory of polymer composite breathing circuits trades at discounts to contracted volumes. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated workstations from CE-marked European configurations and unlicensed regional alternatives. Pricing pressure stems from Mindray's Shenzhen-based cost position compressing mid-tier margins. Ambulatory surgical centers exhibit acute price sensitivity, whereas German academic medical centers prioritize specification compliance over unit cost.
Supply Chain Analysis
Electromechanical vaporizer supply rests on specialized machining capabilities concentrated in Germany, Switzerland, and Japan, with Tübingen-Stuttgart and Nagoya industrial corridors maintaining irreplaceable precision flow control expertise. Key inputs include medical-grade aluminum alloys, fluoropolymer seals, and piezoelectric pressure sensors. Single-source vulnerability concentrates in German captive producers of gas mixer subassemblies. Distribution runs through hospital group purchasing organizations in the United States and direct tender participation in European university hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anesthesia delivery units market is consolidating as EMA Medical Device Regulation documentation burdens filter out undercapitalized competitors incapable of sustaining clinical evidence portfolios. This regulatory pressure is accelerating acquisition activity among precision manufacturing specialists seeking compliant scale.
For Market Incumbents: Anticipate margin compression in portable anesthesia devices as Shenzhen-based manufacturers exploit modular component sourcing, and respond by deepening software licensing revenue through AI-enabled closed-loop control algorithms that trigger FDA 21 CFR 820 validation barriers for challengers. Prioritize backward integration into precision gas mixer production to defend supply security against German-Swiss machining cluster bottlenecks. For New Entrants and Emerging Players: Direct-to-ambulatory-surgical-center digital sales channels bypass entrenched hospital GPO relationships and open procurement access for compact workstation configurations. Target United States freestanding ASCs migrating higher-acuity cases from hospital settings, where space constraints and capital limitations favor modular, service-contract-bundled offerings over integrated premium platforms. For Investors and Strategic Acquirers: FDA premarket notification submission volume for Class II anesthesia apparatus is the leading indicator that regulatory validation capacity is becoming the scarcest competitive asset. Position for five-to-ten-year horizon consolidation by acquiring mid-cap European workstation assemblers with established EMA MDR technical documentation and underutilized precision manufacturing footprints. Monitor CDSCO registration timeline acceleration in India as signal of emerging market premium-tier readiness.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Notification Pathway | 21 CFR 892.1970 compliance documentation creates 18-24 month competitive moats for validated entrants. |
| CE Marking Pathway | EMA MDR technical file preparation filters marginal competitors from European university hospital tenders. |
| Hospital System Partnership | Integrated delivery network service contracts convert capital expenditures to recurring operational revenue streams. |
| Software Companion Development | AI-enabled closed-loop anesthesia algorithms generate highest-margin recurring license revenue offsetting hardware commoditization. |
| Reimbursement Strategy | CMS procedural coding alignment for closed-loop sedation management supports premium workstation adoption in United States academic centers. |
Research Methodology
Multi-period observation of surgical volume recovery patterns, regulatory submission timelines, and procurement contract structures anchored the trend analysis, supplemented by interviews with anesthesiology department heads, biomedical engineering directors, hospital purchasing committee members, and GPO contracts managers. Secondary validation drew from FDA 510(k) clearance databases, EMA MDR notified body certificates, hospital capital expenditure disclosures, and ISO 80601-2-13 standard revision tracking. Bottom-up unit demand modeling triangulated against top-down healthcare infrastructure spending forecasts.
Input-output matrices mapped gas delivery system component costs through vaporizer, monitoring module, and software licensing value chains across product architecture segments. Segmentation dimensions modeled included workstation modularity tier, procedure acuity application, end-user capital availability cluster, and technology integration intensity. CAGRs derived from surgical volume elasticity coefficients applied to replacement cycle timing and ambulatory surgical center expansion trajectories. Forecast inputs incorporated precision machining capacity utilization rates and polymer composite substitution curves in breathing circuit manufacturing.
The model holds under stable regulatory validation timelines and continued surgical volume recovery; deviation in FDA software guidance stringency or intravenous anesthesia protocol adoption would shift workstation demand trajectories. A small set of named triggers—EMA MDR enforcement escalation, AI-enabled device liability frameworks, and volatile anesthetic agent environmental regulation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Anesthesiology
Vasopressin for Vasoplegic Shock Market
Anesthesiology
Anesthesia Breathing Bags Market
Anesthesiology
Dental Anesthesia Market
Anesthesiology
Artificial Coma/Medically Induced Coma Market
Anesthesiology
US Anesthesiology Service Market
Anesthesiology
Anaesthesia Machines Market
Anesthesiology
Global Inhalation Anesthesia Market
Anesthesiology
Global Anesthesia Endotracheal Tubes Market
Anesthesiology
Anesthetics Market
Anesthesiology
Airway Catheters Market
Anesthesiology
Anesthesia Breathing Circuits Market
Anesthesiology
Delirium Market
Anesthesiology
Smart Anesthesia System Market
Anesthesiology
Endotracheal Tube Cuffs Market
Anesthesiology
Aspirating System Market
Anesthesiology
Global Anesthesia and Respiratory Devices Market