
 Epinephrine Market | 2026-2036
Epinephrine Market Size, Share, and Industry Trends Forecast 2026-2036
Epinephrine Market Analysis
Emergency medical services and school district buyers are redrawing procurement priorities toward portable, single-use delivery systems. Kaleo Inc. anchors the premium auto-injector segment through patented temperature-stable formulations. Fresenius Kabi AG leverages hospital infusion channel dominance to sustain vial and pre-filled syringe volumes. Viatris Inc. competes aggressively on price in the generic epinephrine space, pressuring incumbent margin structures.
Epinephrine is a catecholamine hormone and sympathomimetic agent synthesized from norepinephrine via phenylethanolamine N-methyltransferase, functioning as both an endogenous neurotransmitter and exogenous emergency therapeutic for acute bronchospasm and cardiovascular collapse. Auto-injectors command the highest unit margins due to device complexity and patient-carried replacement cycles, while intramuscular delivery dominates hospital protocols for anaphylaxis treatment. Inhalation solutions occupy a mature niche within asthma management, with nebulizer formats losing share to metered-dose alternatives in home care settings.
FDA bioequivalence standards and EMA MDR device classification rules jointly shape product development timelines and market access barriers for new entrants. The US National School Lunch Act amendments and state-level stock epinephrine mandates create institutional demand floors that buffer against retail pharmacy volatility. Stakeholders must monitor pending FDA guidance on generic auto-injector interchangeability, as this determination will reshape competitive dynamics across pharmacy benefit manager formularies.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while mandating device interoperability standards that favor suppliers with integrated quality management systems.
Growth Catalysts
- US school stock epinephrine mandates:State-level legislation requires emergency anaphylaxis kits in educational facilities, institutionalizing replacement demand independent of individual prescriptions.
- Temperature-stable formulations:Novel excipient technologies eliminate cold-chain dependency, expanding distribution reach into ambulatory and military field settings previously inaccessible.
- EMA MDR device classification:Stricter conformity assessment procedures for combination products accelerate quality differentiation, rewarding manufacturers with pre-certified manufacturing infrastructure.
Market Restraints
- API supply concentration:Bulk epinephrine synthesis clusters among three specialized chemical manufacturers, creating single-source vulnerability for finished dose producers.
- FDA bioequivalence barriers:Complex pharmacokinetic modeling requirements for generic auto-injectors extend development timelines and elevate capital requirements for market entry.
- Needle-free delivery alternatives:Intranasal catecholamine formulations under clinical investigation threaten to capture mild anaphylaxis episodes currently served by intramuscular injection.
Strategic Opportunities
- Rural EMS network expansion:Underserved paramedic services in the central United States present white-space demand for pre-hospital auto-injector deployment programs.
- Connected device integration:Bluetooth-enabled injection timestamping converges with electronic health record systems, enabling outcome tracking that satisfies value-based reimbursement pilots.
- Workplace safety mandates:OSHA-aligned employer stock requirements in food service and hospitality sectors open institutional purchasing channels beyond traditional healthcare procurement.
Industry Challenges
- Combination product expertise scarcity:Qualified personnel bridging pharmaceutical formulation and mechanical device engineering command premium compensation, constraining scaling velocity.
- ISO 13485 certification timelines:Extended audit backlogs at notified bodies delay quality management system validation, pushing commercial launch schedules.
- Legacy device remediation:Retrospective validation of existing auto-injector platforms against revised FDA human factors guidance consumes engineering resources without revenue offset.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epinephrine Market |
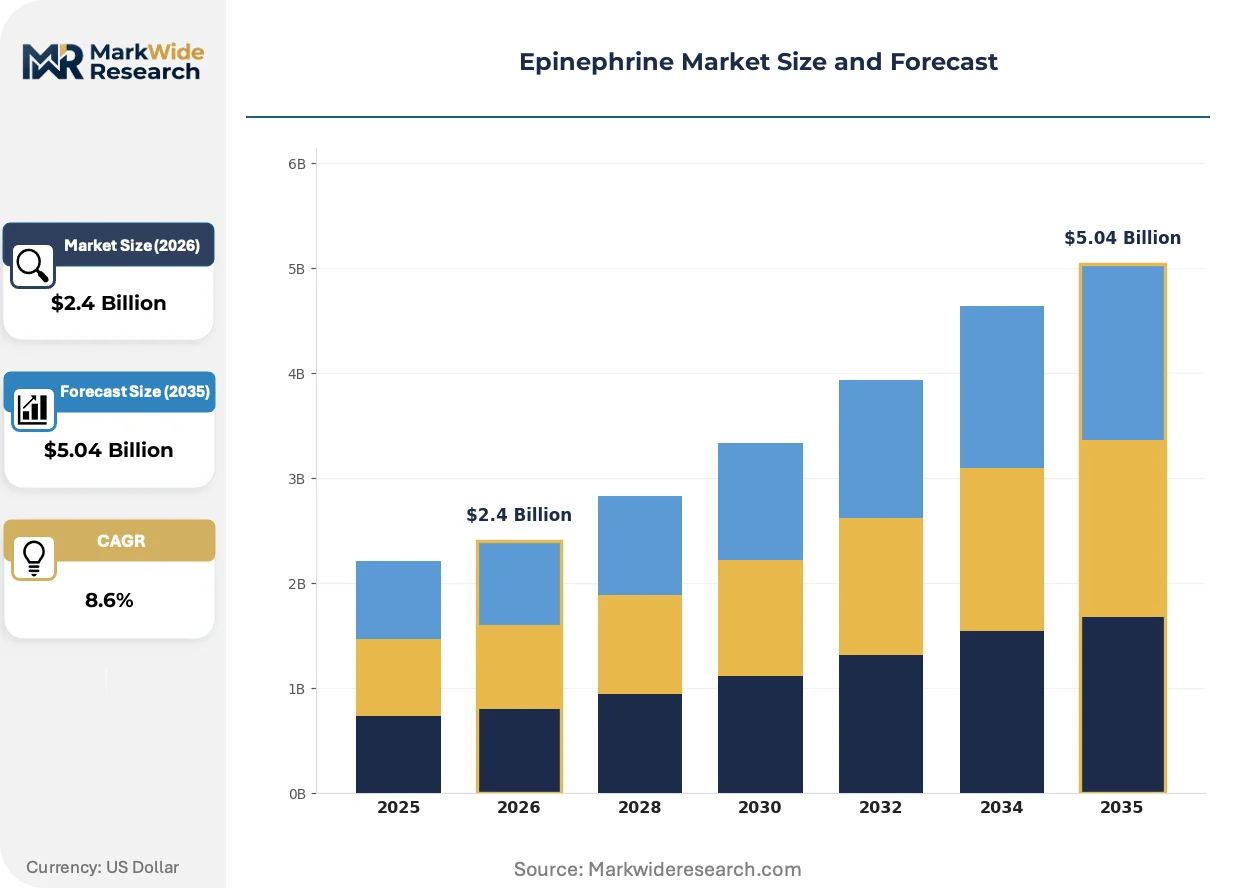
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.04 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalation Solutions, Auto-Injectors, Nebulizers, Vials Delivery Mode: Intramuscular, Subcutaneous, Intravenous, Inhalation End User: Hospitals, Clinics, Emergency Services, Home Care Application: Allergic Reactions, Anaphylaxis Treatment, Asthma Management, Cardiac Arrest |
| Companies Covered | Kaleo Inc., Fresenius Kabi AG, Viatris Inc., ALK-Abelló A/S, Sandoz, Teva Pharmaceutical Industries Ltd., Pfizer Inc., Adamis Pharmaceuticals Corporation, Amneal Pharmaceuticals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epinephrine Market Emerging Trajectories
Device miniaturization and digital connectivity are converging to transform patient-carried emergency medication from passive hardware into active health data nodes.
Needle-retraction safety mechanisms are decomposing the traditional two-step injection sequence into single-motion activation, reducing cognitive load during acute stress episodes. School nurses and lay caregivers adopt these simplified formats fastest, particularly in districts with high staff turnover. The technology is decomposing the training burden that previously limited stock epinephrine deployment to credentialed medical personnel.
FDA draft guidance on generic auto-injector interchangeability is forcing sponsors to demonstrate equivalent activation force and injection duration profiles, not merely pharmacokinetic parity. Manufacturers must now instrument human factors studies with biometric stress indicators. Hospital pharmacy committees await final rulemaking before expanding formulary access to substitutable alternatives.
Emergency medical services are consolidating purchasing through regional cooperative agreements that aggregate ambulance fleet volumes and standardize device specifications across municipal boundaries. This aggregation displaces fragmented municipal procurement that previously tolerated format heterogeneity. The pattern is most pronounced in the southeastern United States, where state-level EMS associations negotiate sole-source contracts covering dozens of independent service districts.
Epinephrine Market Segmentation
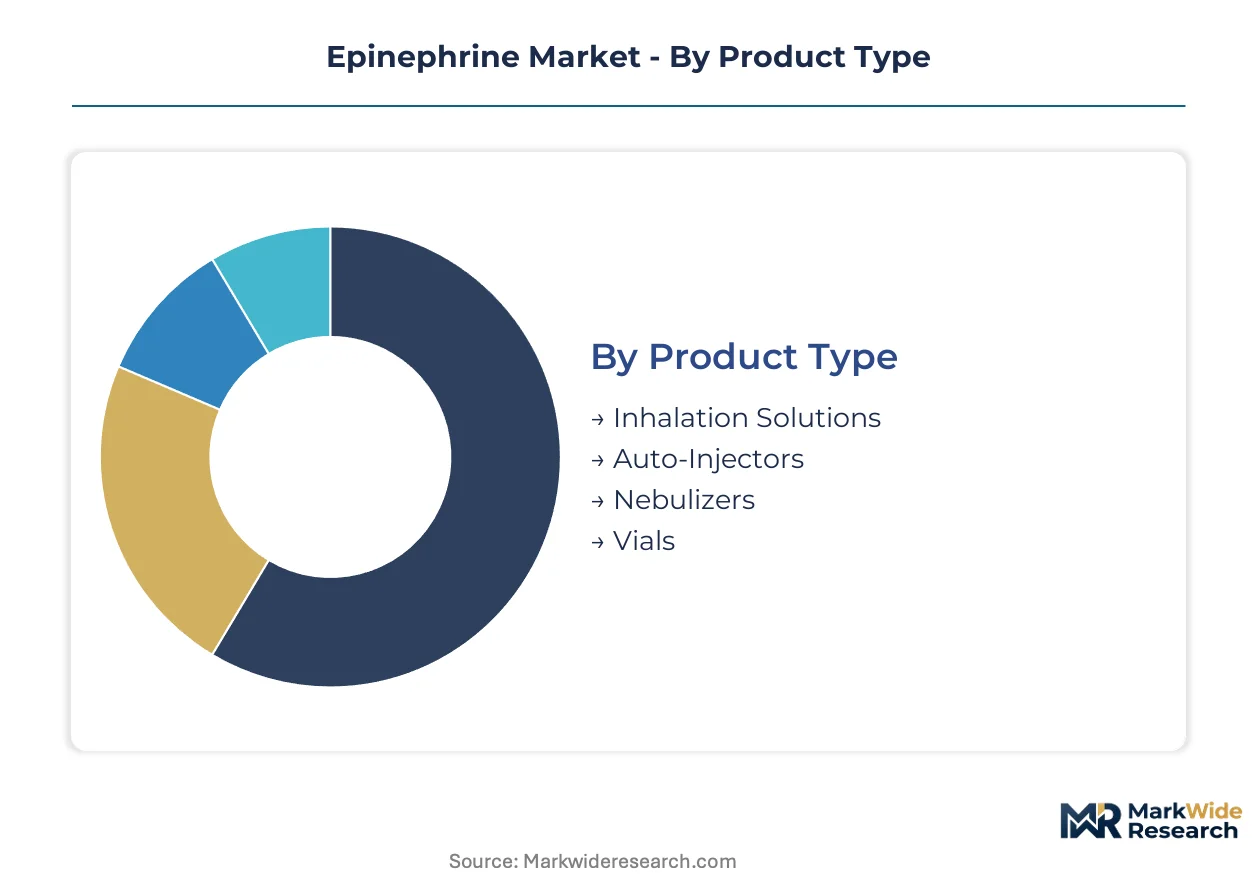
Epinephrine market segmentation reveals distinct channel economics across product formats, with procurement pathways diverging sharply between institutional buyers and patient-carried emergency supplies. Delivery mode and end-user configuration directly determine pricing power, regulatory burden, and replacement cycle frequency for manufacturers.
Product Type:
Channel mix splits between hospital-direct procurement for sterile vials and retail pharmacy distribution for patient-carried auto-injectors, with ambulatory clinics bridging both pathways.
- Auto-Injectors:Spring-loaded, single-use devices delivering fixed-dose intramuscular injection through needle-safety systems. US school district and emergency medical service purchasing concentrates here, driven by layperson usability requirements and state-level stock epinephrine mandates.
- Vials:Multi-dose glass or polymer containers for sterile epinephrine solution requiring syringe withdrawal. Hospital pharmacy and anesthesia department procurement dominates, constrained by USP <797> compounding standards and beyond-use dating protocols.
- Inhalation Solutions:Racemic or L-epinephrine formulations for nebulized delivery in acute bronchospasm. Pulmonology clinic dispensing and home respiratory therapy suppliers channel these products, with Medicare durable medical equipment reimbursement shaping volume.
- Nebulizers:Device-dependent delivery systems now losing share to metered-dose alternatives in home asthma management. Pediatric pulmonology practices retain preference for hospital-grade jet nebulizers in acute exacerbation protocols.
Auto-injectors dominate installed base in patient-carried emergency medication. Vials are where expansion concentrates as hospital consolidation drives standardized formulary adoption.
Delivery Mode:
Cost tier stratification separates high-complexity combination products from commodity injection formats, with reimbursement differentials widening between inpatient and outpatient settings.
- Intramuscular:Vastus lateralis or deltoid injection delivering rapid systemic absorption for anaphylaxis reversal. Emergency department and pre-hospital protocols standardize on this route, with EMA MDR device classification elevating quality system requirements for combination products.
- Intravenous:Continuous infusion or bolus administration in cardiac arrest and shock states. Hospital critical care and operating room utilization concentrates demand, with USP <797> sterile compounding standards governing pharmacy preparation workflows.
- Subcutaneous:Slower absorption route reserved for mild allergic reactions and specific asthma protocols. Allergy immunology practices and urgent care centers maintain limited utilization as intramuscular protocols expand.
- Inhalation:Direct bronchial deposition via nebulization or metered-dose inhalation for localized beta-2 agonist effect. Pediatric asthma management and emergency department observation units sustain niche demand.
Intramuscular delivery anchors clinical guidelines for anaphylaxis. Intravenous administration is climbing the fastest as hospital code blue preparedness standardizes epinephrine availability.
End User:
Customer type fragmentation creates divergent purchasing behaviors, with institutional buyers prioritizing total cost of ownership and individual patients responding to out-of-pocket exposure.
- Hospitals:Integrated delivery networks and academic medical centers procuring through group purchasing organizations. FDA 503B outsourcing facility regulations and USP <797> compliance costs are concentrating vendor relationships toward suppliers with validated sterile manufacturing infrastructure.
- Emergency Services:Municipal and private ambulance operators with regional cooperative purchasing agreements. Southeastern US state-level EMS associations are aggregating fleet volumes into sole-source contracts covering dozens of independent service districts.
- Clinics:Outpatient allergy, pulmonology, and urgent care facilities with mixed procurement patterns. Federally qualified health centers and rural health clinics operate under distinct 340B drug pricing program constraints.
- Home Care:Individual patients and caregivers obtaining prescriptions through retail pharmacy or mail order. High-deductible health plan prevalence and pharmacy benefit manager formulary placement directly influence brand and generic substitution patterns.
Hospitals dominate absolute volume consumption. Home care is gaining share fastest as patient-carried emergency medication protocols expand beyond traditional healthcare settings.
Application:
Application-based demand stratifies across acute emergency versus chronic maintenance contexts, with regulatory and training requirements diverging accordingly.
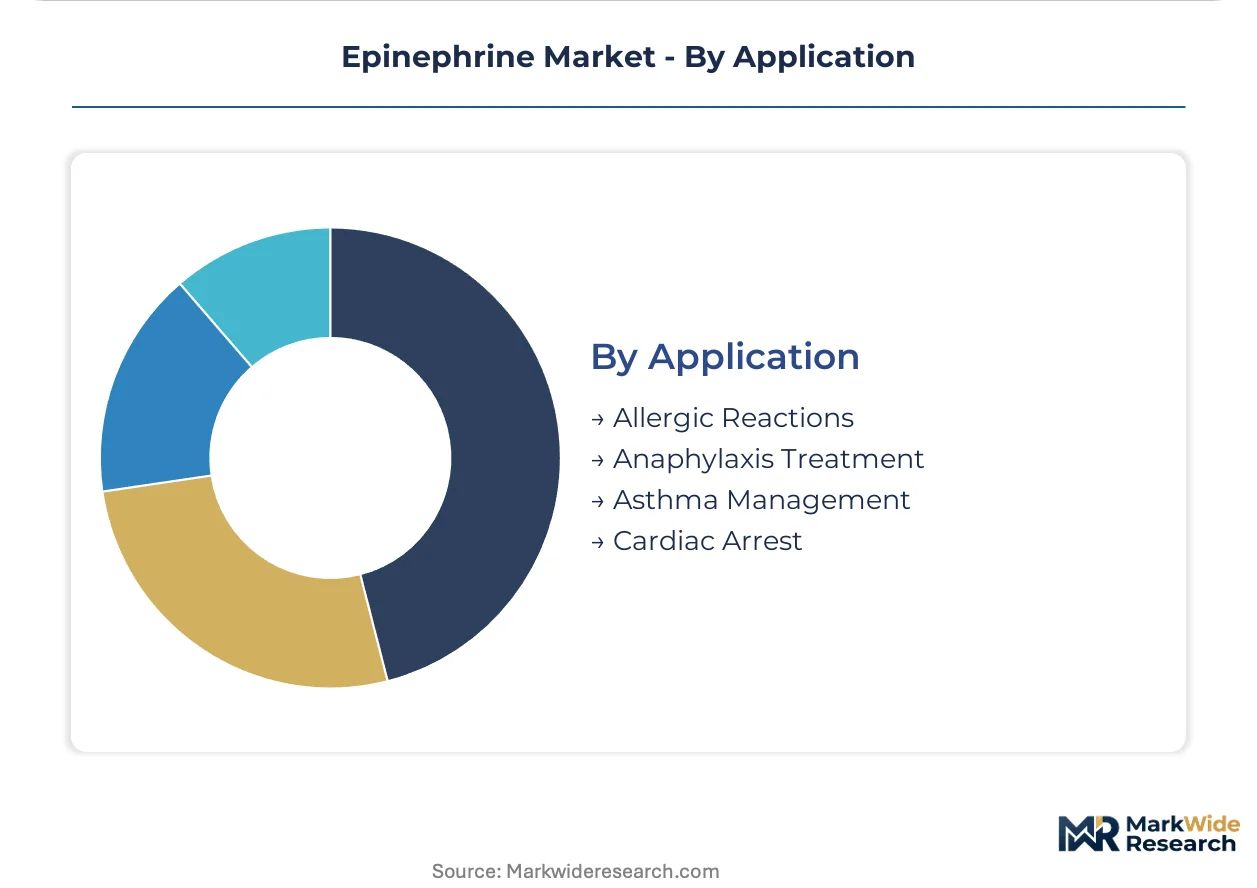
- Anaphylaxis Treatment:Immediate epinephrine administration for IgE-mediated systemic allergic reactions. US National School Lunch Act amendments and state-level stock epinephrine mandates institutionalize replacement demand independent of individual prescription patterns.
- Cardiac Arrest:Advanced cardiovascular life support protocol requiring intravenous or intraosseous epinephrine during resuscitation. Hospital code blue cart standardization and American Heart Association guideline adherence sustain predictable consumption.
- Allergic Reactions:Mild to moderate cutaneous and respiratory manifestations managed in outpatient settings. Urgent care expansion and retail clinic proliferation are extending treatment venue options beyond emergency departments.
- Asthma Management:Adjunctive bronchodilator therapy in acute exacerbations, particularly pediatric populations. Nebulized racemic epinephrine retains niche utilization as inhaled corticosteroid-long-acting beta agonist combinations dominate maintenance therapy.
Anaphylaxis treatment commands premium pricing for patient-carried formats. Cardiac arrest applications are expanding most quickly as hospital resuscitation preparedness standardizes epinephrine stocking requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export temperature-stable auto-injector formulations to emergency medical services across the United States and Canada. This trade corridor channels European device engineering into North American institutional procurement networks.
United States
School district purchasing and emergency medical service fleet standardization drive volume concentration. FDA bioequivalence standards for generic auto-injectors compress formulation variance while extending development timelines. The southeastern United States anchors regional cooperative purchasing agreements that aggregate ambulance fleet volumes across municipal boundaries.
Germany
Hospital group purchasing organizations and anesthesia department procurement sustain vial and pre-filled syringe demand. EMA MDR device classification rules elevate quality system requirements for combination products. The Rhine-Ruhr industrial corridor concentrates sterile manufacturing infrastructure serving integrated delivery networks.
Canada
Provincial health authority procurement and workplace safety mandates in food service sectors expand institutional channels. Health Canada guidance on epinephrine dose standardization aligns with FDA frameworks. The Greater Toronto Area anchors distribution networks serving rural paramedic services across Ontario and Quebec.
Switzerland
Specialty pharmaceutical manufacturing and precision device engineering support premium auto-injector development. Swissmedic regulations on combination product quality systems reward manufacturers with pre-certified infrastructure. The Basel pharmaceutical cluster concentrates formulation expertise for temperature-stable excipient technologies.
Japan
Ambulance fleet modernization and school nursing protocols institutionalize auto-injector replacement cycles. PMDA guidance on human factors testing shapes device development timelines for new entrants. The Kanto region around Tokyo anchors emergency medical service purchasing coordination.
Epinephrine Market Vendor Landscape
Listed leaders compete with private specialists across device engineering and formulation expertise. The market structure concentrates around three to five dominant participants controlling combination product platforms while generic manufacturers fragment the vial and pre-filled syringe segments. Strategic archetypes include premium auto-injector specialists, hospital infusion channel incumbents, and aggressive generic price competitors. Dominant competitive moves encompass portfolio diversification into temperature-stable formulations and geographic expansion through regional cooperative purchasing agreements.
Within the premium auto-injector tier, Kaleo Inc. and ALK-Abelló A/S exemplify device-combination expertise. Among hospital channel suppliers, Fresenius Kabi AG occupies a position reflecting infusion therapy infrastructure. Viatris Inc. represents the generic price-competition archetype pressuring incumbent margin structures.
| Leading Market Players |
|---|
| Kaleo Inc. |
| Fresenius Kabi AG |
| Viatris Inc. |
| ALK-Abelló A/S |
| Sandoz |
| Teva Pharmaceutical Industries Ltd. |
| Pfizer Inc. |
| Adamis Pharmaceuticals Corporation |
| Amneal Pharmaceuticals Inc. |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at sterile API synthesis facilities in India and China anchors cost structures across finished dose tiers, concentrating margin leverage among manufacturers with backward-integrated excipient supply. Scale asymmetries between bulk epinephrine producers and device assemblers compress negotiation room for mid-tier auto-injector sponsors caught between API spot volatility and hospital GPO pricing floors.
Pricing Analysis
Next-generation temperature-stable formulations command substantial premia over conventional cold-chain-dependent devices, while legacy vial formats face commoditization as hospital consolidation standardizes procurement. Pricing stratifies across premium auto-injector, standard pre-filled syringe, and economy multi-dose vial tiers, with differentiation driven by FDA bioequivalence certification status and cold-chain exemption claims. Cost compression in the generic auto-injector segment is intensifying because Viatris and Teva Pharmaceutical Industries compete aggressively on pharmacy benefit manager formulary placement. Emergency medical services represent the most price-sensitive buyer archetype due to municipal budget constraints, while school district purchasers exhibit lower sensitivity given state-level mandate funding.
Supply Chain Analysis
Bulk epinephrine API synthesis clusters among three specialized chemical manufacturers in India, China, and the United States, creating single-source vulnerability for finished dose producers. Device component sourcing draws from precision spring manufacturers in Switzerland and Germany, with needle-safety systems resting on polymer injection molding capacity in the Rhine-Ruhr corridor. Tariff exposure on Chinese-sourced API intermediates elevates cost unpredictability for sponsors without long-term offtake agreements. Distribution runs through hospital group purchasing organizations and regional EMS cooperative agreements that aggregate volume and standardize specifications across municipal boundaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intranasal catecholamine formulations under clinical investigation threaten to capture mild anaphylaxis episodes currently served by intramuscular injection, forcing incumbents to defend device-combination positions against needle-free substitutes.
For Market Incumbents: Shield premium auto-injector margins by accelerating FDA submission timelines for temperature-stable formulations that eliminate cold-chain dependency and expand military field access. Deepen backward integration into API synthesis capacity to reduce exposure to Indian and Chinese bulk manufacturer pricing volatility. Monitor Health Canada and Swissmedic guidance on generic auto-injector interchangeability as a regulatory inflection point that could reshape pharmacy benefit manager formularies. For New Entrants and Emerging Players: Rural EMS network gaps in the central United States present white-space demand for pre-hospital auto-injector deployment programs underserved by incumbent distribution infrastructure. Target workplace safety mandates in food service and hospitality sectors as institutional purchasing channels beyond traditional healthcare procurement, leveraging OSHA-aligned employer stock requirements as a go-to-market wedge. Pursue sole-source contracts through state-level EMS associations in the southeastern United States that aggregate fleet volumes across dozens of independent service districts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with pre-certified ISO 13485 quality management systems and validated combination product platforms that compress regulatory timelines for new entrants. Long-term viability across the projection horizon rests on portfolio diversification into connected device integration and Bluetooth-enabled injection timestamping that satisfies value-based reimbursement pilots. Watch FDA draft guidance finalization on generic auto-injector interchangeability as the signal indicating whether pharmacy benefit managers will expand formulary access to substitutable alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Temperature-Stable Formulation Development | FDA submissions for cold-chain exemption expand distribution into military and ambulatory settings previously inaccessible. |
| Connected Device Integration | Bluetooth-enabled timestamping converges with electronic health record systems for value-based reimbursement pilots. |
| Regional EMS Cooperative Agreements | Sole-source contracts through state-level associations aggregate ambulance fleet volumes across municipal boundaries. |
| Backward Integration into API Synthesis | Captive supply of bulk epinephrine reduces vulnerability to Indian and Chinese manufacturer concentration. |
| Workplace Safety Mandate Alignment | OSHA-aligned employer stock requirements in food service open institutional channels beyond healthcare procurement. |
Methodological Framework
A standing panel of hospital pharmacy directors, emergency medical service procurement officers, allergy immunology clinicians, and group purchasing organization contract managers provided ongoing calibration across the study period. Primary interview insights combined with secondary validation from FDA 503B outsourcing facility filings, EMA MDR device classification databases, state-level stock epinephrine legislation trackers, and hospital procurement database extracts. Bottom-up volume modeling across product formats, delivery modes, and end-user segments triangulated against top-down market sizing from regulatory filing analysis and trade flow data.
Consistency checks validated volume and value outputs against external benchmarks including CMS Medicare Part B reimbursement data, 340B drug pricing program reports, and ambulance fleet inventory disclosures. The analytical framework segmented across the analysis window by product type, delivery mode, end-user configuration, and application context, with CAGRs derived from regression analysis of historical procurement patterns and mandate-driven replacement cycle modeling. Industry-specific forecast inputs incorporated FDA bioequivalence guidance timelines, EMA notified body audit backlogs, and state-level EMS association contract renewal schedules.
Underlying assumptions cover stable regulatory enforcement of school stock epinephrine mandates, with deviation risk concentrated in FDA generic auto-injector interchangeability determinations and needle-free delivery alternative clinical trial outcomes. Practitioners should keep alternative scenarios live as intranasal formulation efficacy data and regional EMS cooperative purchasing consolidation patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Anesthesiology
Global Inhalation Anesthesia Market
Anesthesiology
Artificial Airway Holders Market
Anesthesiology
Anesthesia CO2 Absorbent Market
Anesthesiology
Anesthesia Breathing Circuits Market
Anesthesiology
Sedation in ICU Setting Market
Anesthesiology
Vasopressin for Vasoplegic Shock Market
Anesthesiology
Dental Anesthesia Market
Anesthesiology
Global Anesthesia Delivery Systems Market
Anesthesiology
Anesthesia Breathing Bags Market
Anesthesiology
Artificial Coma/Medically Induced Coma Market
Anesthesiology
Anaesthesia Machines Market
Anesthesiology
Endotracheal Tube Cuffs Market
Anesthesiology
Global Anesthesia Endotracheal Tubes Market
Anesthesiology
Global Anesthesia and Respiratory Devices Market
Anesthesiology
Delirium Market
Anesthesiology
Aspirating System Market