
 Anesthesia CO2 Absorbent Market | 2026-2036
Anesthesia CO2 Absorbent Market Size, Share, and Industry Trends Forecast 2026-2036
Anesthesia CO2 Absorbent Market Intelligence
Project finance for hospital anesthesia suite upgrades is tilting procurement decisions toward bundled equipment-and-consumable contracts. Drägerwerk AG & Co. KGaA leverages its captive absorbent production to lock in long-term service agreements with European hospital networks. GE Healthcare Technologies anchors its position through integrated delivery systems that specify proprietary canister designs. Becton Dickinson competes via broad distribution reach across North American ambulatory surgery centers.
Anesthesia CO2 absorbent comprises alkaline hydroxide compounds—primarily calcium hydroxide with sodium hydroxide or potassium hydroxide activators—formulated into granular or pellet forms that chemically neutralize exhaled carbon dioxide in closed and semi-closed anesthesia breathing circuits, maintaining inspired gas CO2 below clinically safe thresholds. Soda lime formulations still occupy the majority installed base due to cost familiarity, though lithium hydroxide variants are gaining traction in military and aerospace medical applications where weight and absorptive efficiency carry premium value. Pellet and granular forms dominate hospital procurement, while tablet formats sustain niche demand in portable anesthesia systems for field veterinary use.
The FDA enforces biocompatibility and performance standards under 21 CFR 868.5240 for carbon dioxide absorbents used in human anesthesia, while the EU MDR requires notified body certification for absorbent canisters classified as Class IIa medical devices. Health Canada and TGA maintain parallel premarket review pathways that manufacturers must navigate for parallel market access. Stakeholders should monitor evolving national pharmacopeial monographs for hydroxide purity specifications, as these standards directly determine formulation costs and competitive moats.
Market Dynamics
The EU Medical Device Regulation is tightening certification requirements for CO2 absorbent canisters, forcing manufacturers to restructure quality systems and notified body relationships ahead of Class IIa reclassification deadlines.
Growth Catalysts
- Tertiary Hospital Expansion:Rising surgical volumes at academic medical centers in Germany, France, and the United States are expanding installed bases of anesthesia machines and driving recurring absorbent purchases through captive service contracts.
- REACH Chemical Standards:Evolving EU chemical safety protocols for alkaline hydroxide formulations are accelerating R&D investment in lower-dust pellet geometries that reduce occupational exposure risks for operating room staff.
- Military-Aerospace Specifications:Lithium hydroxide variants with superior weight-to-absorption ratios are gaining procurement traction in defense medical systems and aeromedical evacuation platforms where payload constraints override cost considerations.
Market Restraints
- Calcium Hydroxide Price Volatility:Feedstock costs for mined limestone and processed lime fluctuate with construction sector demand cycles, compressing formulation margins for commodity-grade soda lime producers.
- Notified Body Bottleneck:EU MDR implementation has reduced the pool of certified bodies for Class IIa device review, extending time-to-market for new absorbent formulations by 12-18 months.
- Baralyme Substitution Legacy:Historical recalls of barium hydroxide-based absorbents due to compound A formation risks continue to constrain hospital willingness to trial novel alkaline earth formulations.
Strategic Opportunities
- Veterinary Field Anesthesia:Tablet-format absorbents for portable veterinary systems remain underpenetrated in Australia and Canada, where mobile large-animal surgical services lack standardized consumable supply chains.
- Closed-Loop Reprocessing:Spent absorbent regeneration technologies are converging with hospital sustainability mandates, creating service-revenue models that decouple growth from virgin chemical consumption.
- Health Canada Streamlined Review:Parallel recognition pathways with FDA 510(k) clearances are reducing regulatory duplication costs for manufacturers seeking North American market access.
Industry Challenges
- Anesthesia Equipment Integration:Proprietary canister geometries from dominant machine manufacturers force absorbent producers to maintain multiple tooling configurations, fragmenting production runs and inflating changeover costs.
- Biocompatibility Testing Burden:ISO 10993 cytotoxicity and sensitization protocols for new hydroxide activator combinations require 18-24 month validation timelines that delay formulation launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anesthesia CO2 Absorbent Market |
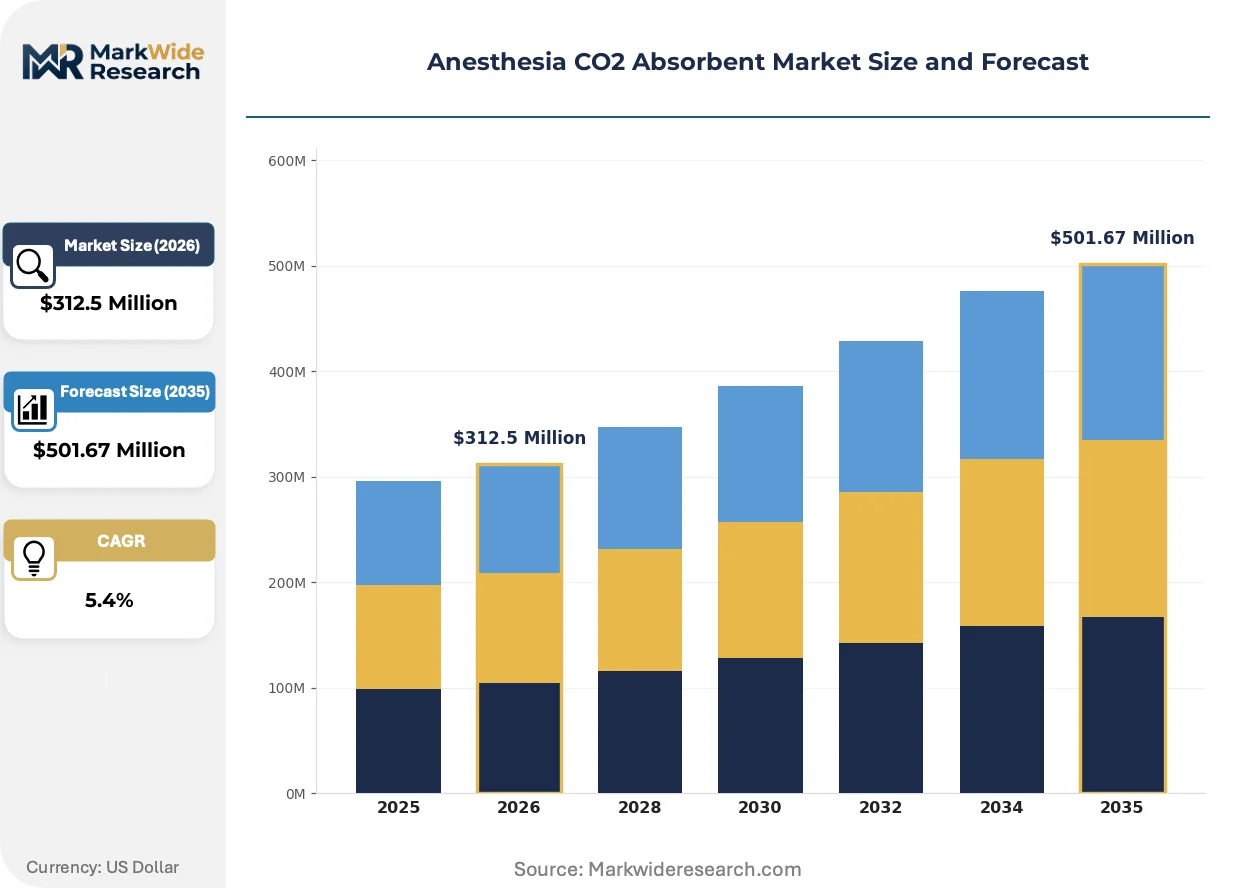
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barium Hydroxide, Calcium Hydroxide, Lithium Hydroxide, Soda Lime Application: Anesthesia Delivery, Laboratory Procedures, Veterinary Medicine, Medical Devices Form: Granular, Pellets, Tablets, Powder End User: Hospitals, Clinics, Research Labs, Dental Practices |
| Companies Covered | Drägerwerk AG & Co. KGaA, GE Healthcare Technologies, Becton Dickinson, Smiths Group, Allied Healthcare, Armstrong Medical, Micropore, Molecular Products, Intersurgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anesthesia CO2 Absorbent Market Strategic Shifts & Innovations
Formulation chemistry and regulatory compliance frameworks are converging to reshape competitive positioning in anesthesia CO2 absorbents. Three distinct vectors are redefining product development priorities and go-to-market architectures.
Lithium hydroxide monohydrate formulations are hybridizing traditional calcium-based chemistries in premium medical segments. Defense procurement agencies and aeromedical operators specify these blends for extended mission duration without canister changeout. The technology is compressing the addressable market for conventional soda lime in weight-sensitive applications while establishing performance benchmarks that civilian hospital buyers increasingly reference.
The EU MDR's Class IIa classification for absorbent canisters is mandating expanded clinical evidence packages and post-market surveillance systems. Manufacturers must now maintain vigilance databases for chemical degradation products and patient exposure incidents. German and French hospital networks are responding by consolidating supplier panels to entities with established notified body relationships and quality management maturity.
Hospital purchasing cooperatives are unbundling anesthesia consumables from equipment lease agreements that previously locked in proprietary absorbent specifications. Independent ambulatory surgery centers in the United States and United Kingdom are driving this disintermediation, sourcing generic-compatible canisters through group purchasing organizations. The shift is most visible in North American outpatient settings where anesthesia machine fleet heterogeneity limits single-source contract feasibility.
Anesthesia CO2 Absorbent Market Segmentation
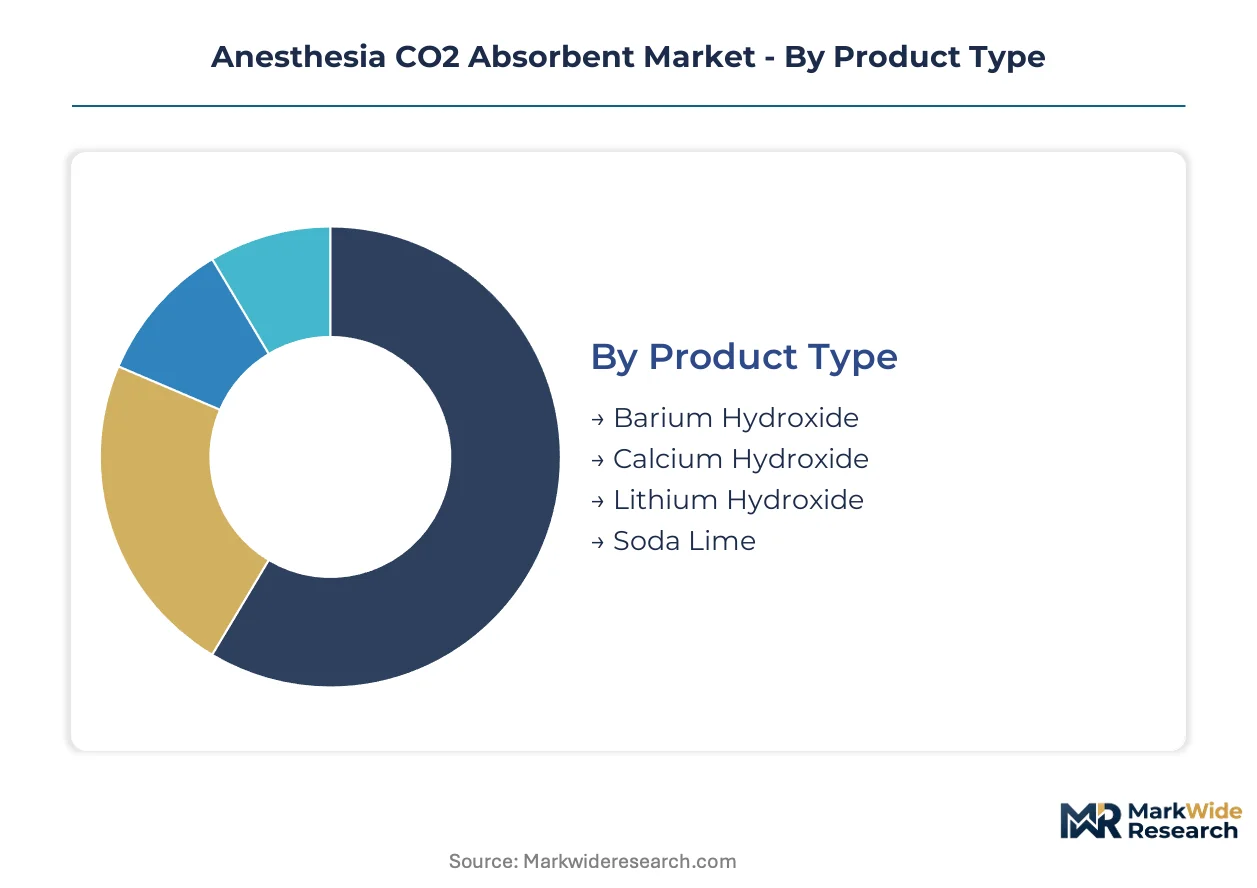
Segmentation in anesthesia CO2 absorbents determines service contract structures, formulation margins, and regulatory pathway complexity. Product chemistry dictates equipment compatibility requirements. End-user concentration shapes distribution economics and captive supply arrangements.
Product Type:
After-sales service intensity varies sharply across alkaline hydroxide chemistries, with lithium hydroxide demanding specialized handling protocols and calcium-based formulations supporting commodity replenishment models.
- Soda Lime:Comprising calcium hydroxide with sodium hydroxide activator, this formulation dominates hospital installed bases due to cost familiarity and broad equipment compatibility. Demand concentrates in German and French tertiary hospitals where Drägerwerk and GE Healthcare anesthesia machines specify standardized canister geometries. REACH compliance costs for dust mitigation are compressing margins for regional compounders.
- Lithium Hydroxide:Monohydrate variants deliver superior weight-to-absorption ratios with minimal dust generation. Military medical procurement in the United States and aeromedical evacuation platforms in the United Kingdom drive specification, where payload constraints override per-unit cost premiums. Health Canada and FDA dual-track submissions extend commercialization timelines.
- Calcium Hydroxide:Unactivated base formulations serve veterinary and laboratory segments with reduced performance requirements. Feedstock price volatility tied to construction sector lime demand cycles creates margin pressure.
- Barium Hydroxide:Legacy compound A formation risks from baralyme recalls constrain hospital willingness to trial novel alkaline earth activators. Niche demand persists in specialized industrial gas purification.
By volume, soda lime leads. By growth pace, lithium hydroxide is ahead.
Application:
Application segments diverge by regulatory burden and equipment integration depth, with anesthesia delivery commanding the most stringent biocompatibility validation.
- Anesthesia Delivery:Closed and semi-closed breathing circuits in human surgical settings demand ISO 10993 cytotoxicity certification and EU MDR Class IIa canister classification. Tertiary hospital networks in Germany consolidate procurement around notified body-certified suppliers.
- Veterinary Medicine:Field anesthesia systems for large-animal mobile surgical services in Australia and Canada use tablet-format absorbents with standardized supply chain gaps. Lower regulatory barriers enable faster formulation iteration.
- Medical Devices:Integrated portable respiratory support equipment specifies proprietary absorbent geometries. OEM captive supply agreements lock out independent compounders.
- Laboratory Procedures:Research and quality control applications tolerate higher variability in absorption kinetics. Academic procurement favors cost-minimization over performance optimization.
Revenue concentrates in anesthesia delivery. Steepest expansion trajectory belongs to veterinary medicine.
Form:
Physical geometry determines occupational exposure profiles and equipment compatibility, with pellet formats gaining share against legacy granular installations.
- Pellets:Engineered spherical geometries reduce dust generation during canister loading, addressing REACH-mandated workplace exposure limits. French hospital purchasing cooperatives specify pellet-only contracts for operating room staff protection.
- Granular:Irregular particle distributions maintain cost advantage in price-sensitive segments. Installed base persistence in older anesthesia machine fleets sustains demand despite ergonomic disadvantages.
- Tablets:Compressed disk formats suit portable veterinary systems with vibration-resistant packaging requirements. Mobile large-animal surgical units in Canada source through non-standard distribution channels.
- Powder:Fine particulate forms serve industrial carbon capture and specialized laboratory applications outside regulated medical device pathways.
Pellet formats command premium positioning. Granular forms retain volume leadership.
End User:
Customer type segmentation reveals divergent procurement sophistication, with hospital networks leveraging equipment lease bundling against independent clinic spot purchasing.
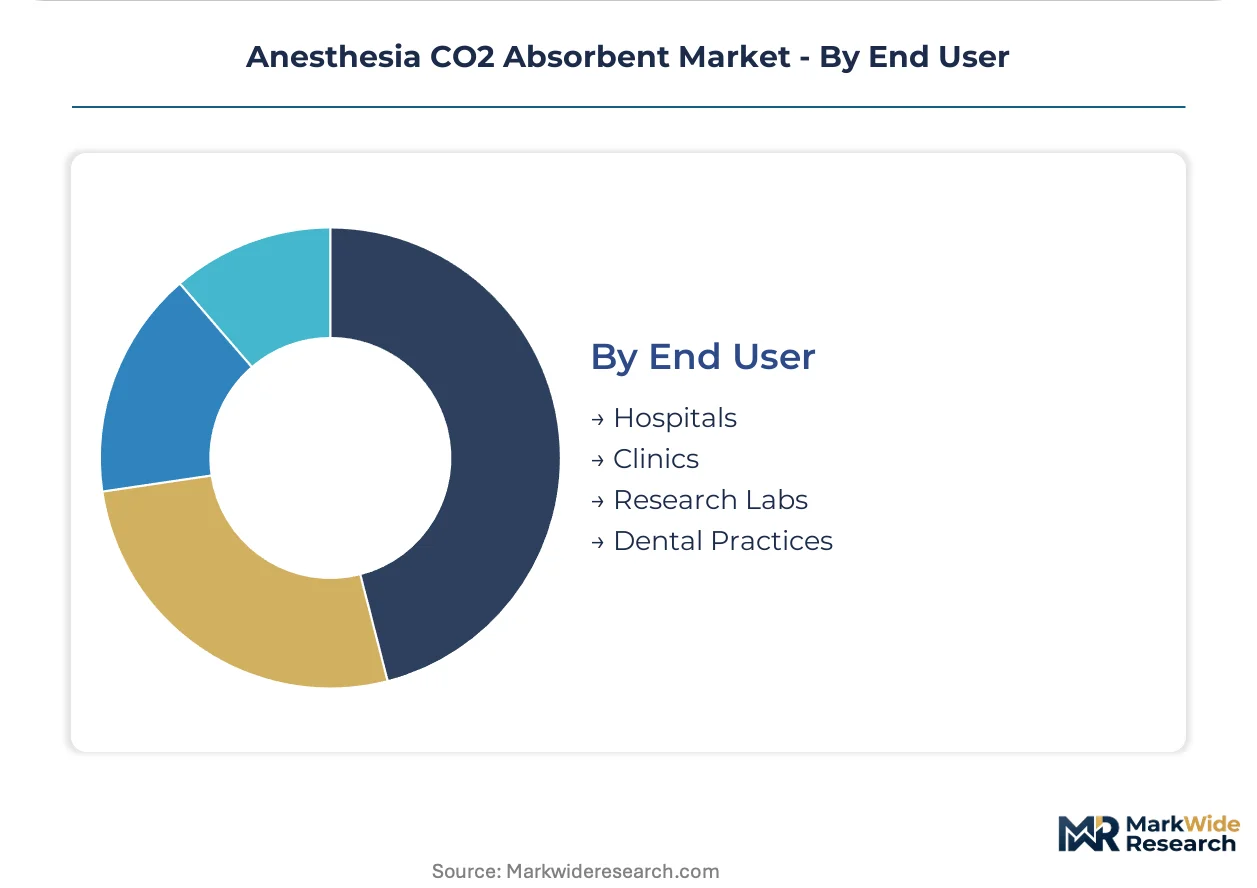
- Hospitals:Academic medical centers in the United States and Germany drive absorbent consumption through captive service contracts tied to anesthesia machine leases. EU MDR compliance requirements favor suppliers with established notified body relationships.
- Clinics:Ambulatory surgery centers in the United Kingdom and United States are disintermediating from proprietary equipment agreements, sourcing generic-compatible canisters through group purchasing organizations.
- Research Labs:University and pharmaceutical R&D facilities prioritize absorption kinetics precision over cost minimization. Smaller order quantities fragment supplier attention.
- Dental Practices:Sedation dentistry applications use miniaturized canister formats with limited aftermarket service infrastructure.
Hospitals anchor revenue concentration. Clinics are gaining share fastest through procurement unbundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement officers in Germany, the United States, and France dominate absorbent purchasing decisions through bundled equipment-service contracts. Military medical buyers in the United Kingdom and Canada specify lightweight formulations for aeromedical platforms. Regulatory divergence across FDA, EU MDR, and Health Canada pathways fragments supplier certification strategies.
Germany
Drägerwerk AG & Co. KGaA anchors absorbent demand through captive anesthesia machine installations at academic medical centers in Berlin and Munich. The EU MDR Class IIa reclassification forces manufacturers to restructure notified body relationships for canister certification. The Rhine-Ruhr industrial corridor concentrates formulation compounding capacity for pelletized soda lime serving French and Benelux export markets.
United States
GE Healthcare Technologies locks in recurring absorbent purchases through integrated delivery system contracts spanning Cleveland Clinic and Mayo Clinic networks. FDA 21 CFR 868.5240 biocompatibility standards enforce ISO 10993 cytotoxicity testing for new hydroxide activator combinations. The Minneapolis-St. Paul medical device cluster hosts Becton Dickinson distribution infrastructure feeding ambulatory surgery centers across the Upper Midwest.
United Kingdom
Royal Air Force aeromedical evacuation specifications drive lithium hydroxide procurement for extended mission duration without canister changeout. The Medicines and Healthcare products Regulatory Agency maintains parallel recognition with FDA 510(k) pathways to reduce regulatory duplication. Smiths Group manufacturing in Luton supplies tablet-format absorbents for portable military field anesthesia systems.
France
Assistance Publique-Hôpitaux de Paris purchasing cooperatives specify pellet-only contracts to meet REACH-mandated workplace exposure limits for operating room staff. The ANSM enforces post-market surveillance for chemical degradation products under EU MDR vigilance database requirements. The Lyon biomedical cluster concentrates R&D investment in lower-dust pellet geometries reducing occupational inhalation risks.
Canada
Mobile large-animal veterinary surgical services in Alberta and Saskatchewan source tablet-format absorbents through non-standard distribution channels with supply chain gaps. Health Canada streamlined review pathways recognize FDA 510(k) clearances for parallel North American market access. Molecular Products distribution through Toronto serves defense medical procurement for Arctic search-and-rescue platforms requiring weight-optimized formulations.
Anesthesia CO2 Absorbent Market Key Industry Players
Channel-controlling players compete with product-specialist players across divergent procurement pathways. Equipment-integrated suppliers capture hospital networks through bundled lease agreements, while independent compounders serve unbundled ambulatory demand. Three archetypes dominate: anesthesia machine OEMs with captive absorbent production, diversified medical device distributors with broad ASC reach, and specialty chemical compounders focused on military-aerospace specifications. Competitive moves concentrate on notified body certification acceleration and pellet geometry R&D to satisfy REACH dust exposure mandates.
Among diversified medical technology conglomerates, Drägerwerk AG & Co. KGaA and GE Healthcare Technologies exemplify the equipment-integrated archetype through anesthesia machine fleet penetration. Becton Dickinson occupies a position within the distribution-focused tier, leveraging North American supply chain scale. These three entities represent contrasting pathways to hospital procurement officers: captive vertical integration versus independent sourcing flexibility.
| Leading Market Players |
|---|
| Drägerwerk AG & Co. KGaA |
| GE Healthcare Technologies |
| Becton Dickinson |
| Smiths Group |
| Allied Healthcare |
| Armstrong Medical |
| Micropore |
| Molecular Products |
| Intersurgical |
| Others |
Cost & Logistics Intelligence
Calcium hydroxide feedstock volatility tied to construction sector lime demand cycles compresses formulation margins while simultaneously widening pricing tier spreads between commodity soda lime and premium lithium hydroxide variants, forcing compounders to restructure supply networks around dual-sourcing strategies and geographic hedging.
Pricing Analysis
Cost-plus contracts with limestone indexation dominate procurement between German pellet manufacturers and Rhine-Ruhr industrial compounders, creating transparent pass-through mechanisms for feedstock fluctuations. Three-tier pricing structure across premium lithium hydroxide, standard soda lime, and economy-grade calcium hydroxide separates military-aerospace buyers from tertiary hospital networks and veterinary field services. Cost compression in commodity soda lime is intensifying because REACH dust-mitigation compliance adds processing overhead without commensurate absorption performance gains. Ambulatory surgery centers in the United States exhibit highest price sensitivity through group purchasing organization spot-buying, while defense medical procurement in the United Kingdom shows lowest sensitivity due to mission-critical payload constraints.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier financing arrangements between notified body-certified compounders and French hospital purchasing cooperatives, compressing working capital cycles for tier-two producers. Manufacturing concentrates in Germany, France, and the United States, with pellet compounding anchored in the Rhine-Ruhr corridor and military-specification production centered in Luton and Minneapolis-St. Paul. Raw material dependencies rest on mined limestone from Bavarian quarries, processed sodium hydroxide from chlor-alkali facilities, and monohydrate lithium salts from specialized chemical suppliers. Single-source vulnerability permeates the notified body certification bottleneck, where EU MDR Class IIa reclassification has reduced qualified audit capacity. Distribution runs through anesthesia machine OEM captive service agreements for hospital networks and independent medical distributors for ambulatory settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU MDR Class IIa reclassification constitutes a regulatory inflection that accelerates market consolidation around quality-mature suppliers, transforming a fragmented compounding landscape into a certification-gated oligopoly within the analysis window.
For Market Incumbents: Build certification moats by accelerating notified body relationship investments ahead of competitor queue positions, defending against emerging lithium hydroxide specialists from military-aerospace crossover. Deepen backward integration into pellet geometry R&D to satisfy REACH dust exposure mandates while locking in long-term service contracts with German academic medical centers. Channel control through anesthesia machine fleet penetration remains the decisive lever for recurring absorbent revenue capture. For New Entrants and Emerging Players: Pursue veterinary field anesthesia white space in Australia and Canada, where tablet-format absorbents for mobile large-animal surgical services lack standardized supply chains and incumbent equipment bundling is weakest. Target ambulatory surgery center procurement unbundling in the United Kingdom and United States, where group purchasing organization spot-buying creates entry paths outside proprietary canister geometries. A direct-to-clinic distribution model bypassing OEM service agreements offers the cleanest go-to-market angle. For Investors and Strategic Acquirers: EU MDR implementation reshapes the acquisition landscape toward notified body-certified compounders with established quality management systems and post-market surveillance infrastructure. Five-to-ten year viability centers on suppliers capable of serving both civilian hospital and defense medical procurement channels with formulation flexibility. Acquire specialty chemical compounders with military-aerospace lithium hydroxide capabilities and bridge them into civilian premium segments. The signal to watch is Health Canada-FDA parallel recognition pathway expansion, which would unlock North American scale advantages for dual-certified producers.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Certification Acceleration | EU MDR Class IIa reclassification creates 12-18 month queue advantages for early filers against lagging competitors. |
| Pellet Geometry R&D Investment | REACH workplace exposure mandates in France and Germany drive specification shifts toward engineered spherical formats. |
| Veterinary Distribution Partnership | Tablet-format supply chain gaps in Canadian mobile large-animal services enable first-mover channel establishment. |
| Closed-Loop Reprocessing Service Model | Hospital sustainability mandates converge with spent absorbent regeneration technologies to decouple growth from virgin chemical consumption. |
| Dual-Track FDA-Health Canada Submission | Parallel recognition pathways reduce regulatory duplication costs for North American market access expansion. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR notified body certification databases, and REACH compliance documentation, combining structured interviews with anesthesia equipment OEM procurement directors, hospital biomedical engineers, GPO contracts managers, and military medical supply officers with bottom-up and top-down triangulation across formulation chemistry and end-use demand segmentation.
Forecast inputs include surgical volume trajectories at tertiary hospitals, anesthesia machine installed base replacement cycles, and regulatory pathway evolution across FDA, EU MDR, and Health Canada frameworks. The analytical framework models product chemistry, application segment, physical form, and end-user procurement sophistication across the projection horizon, with CAGRs derived from regression analysis against historical absorbent consumption patterns and equipment fleet expansion rates.
Sensitivities concentrate around notified body capacity constraints, calcium hydroxide feedstock price cycles, and procurement unbundling velocity in ambulatory settings. Forecasts reflect documented assumptions regarding regulatory implementation timelines and hospital capital expenditure continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Anesthesiology
Anesthesia Breathing Circuits Market
Anesthesiology
Dental Anesthesia Market
Anesthesiology
Anesthetics Market
Anesthesiology
Anaesthesia Machines Market
Anesthesiology
Anesthesia Delivery Units Market
Anesthesiology
Artificial Airway Holders Market
Anesthesiology
Global Anesthesia Endotracheal Tubes Market
Anesthesiology
Airway Catheters Market
Anesthesiology
Smart Anesthesia System Market
Anesthesiology
Endotracheal Tube Cuffs Market
Anesthesiology
Delirium Market
Anesthesiology
Artificial Coma/Medically Induced Coma Market
Anesthesiology
Inhalation Anesthetics Market
Anesthesiology
Global Anesthesia Gases Market
Anesthesiology
Anesthesia Breathing Bags Market
Anesthesiology
Aspirating System Market