
 Artificial Coma/Medically Induced Coma Market | 2026-2036
Artificial Coma/Medically Induced Coma Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Coma/Medically Induced Coma Market Analysis
Intensivist staffing shortages across North American and European trauma centers is collapsing available bed capacity for prolonged sedation management. Baxter Healthcare Corporation leverages its integrated infusion platform to sustain institutional contracts in high-acuity settings. Fresenius SE & Co. KGaA anchors critical care pharmacy operations through its hospital supply networks. Hikma Pharmaceuticals competes on injectable anesthetic portfolios across emerging markets.
Artificial coma, or medically induced coma, denotes a controlled state of deep unconsciousness achieved through continuous intravenous administration of anesthetic agents such as propofol at dosages typically exceeding standard sedation thresholds, serving to reduce cerebral metabolic demand and intracranial pressure in patients with traumatic brain injury or refractory status epilepticus. The technique dimension splits across propofol, thiopental, barbiturates, and benzodiazepines, with barbiturate protocols retaining dominance in refractory intracranial hypertension despite propofol's wider availability in general ICUs. Intravenous administration controls the majority of value flow, though inhalational routes sustain niche positioning in cardiac surgery centers requiring rapid neurophysiologic recovery assessment.
FDA sedation monitoring requirements and EMA pharmacovigilance frameworks for prolonged anesthetic exposure shape product labeling, dosing limits, and mandatory adverse event reporting across jurisdictions. The EU MDR and ISO 13485 standards govern infusion device interoperability and alarm integration for continuous coma induction protocols. Stakeholders must monitor evolving ICU staffing models and reimbursement thresholds for prolonged mechanical ventilation with deep sedation.
Market Dynamics
Intensivist staffing shortages across tertiary trauma centers are compressing bed capacity for prolonged sedation management, forcing hospitals to consolidate artificial coma protocols around automated infusion platforms that reduce nursing labor intensity.
Growth Catalysts
- Neurocritical Care Admissions:Rising traumatic brain injury volumes at Level I trauma centers in the United States, Germany, and Japan are expanding demand for barbiturate-based sedation protocols.
- FDA Continuous Monitoring Mandates:Tightened documentation standards for prolonged coma induction are institutionalizing advanced infusion systems with integrated alarm architectures.
- Refractory Status Epilepticus Protocols:Thiopental and pentobarbital are gaining traction in emergency neurology units seeking rapid cerebral metabolic suppression beyond standard anticonvulsant failure.
Market Restraints
- Propofol Supply Concentration:Manufacturing of the intravenous emulsion concentrates in European contract manufacturing organizations, exposing purchasers to single-source disruption risk.
- EMA Pharmacovigilance Burden:Prolonged anesthetic exposure reporting requirements are extending product labeling timelines and limiting dose range extensions.
- Alternative Neuroprotection Modalities:Targeted temperature management and decompressive craniectomy are displacing pharmacologic coma in select intracranial hypertension presentations.
Strategic Opportunities
- Emerging Market Hospital Construction:Greenfield tertiary facilities in Brazil and Saudi Arabia are installing integrated critical care infrastructure without legacy sedation equipment constraints.
- Inhalational Anesthetic Resurgence:Isoflurane and sevoflurane delivery systems are penetrating cardiac surgery centers requiring rapid neurophysiologic recovery assessment.
- EU MDR Certification Pathways:Harmonized infusion device interoperability standards under ISO 13485 are reducing regulatory fragmentation for multi-modal sedation platforms.
Industry Challenges
- Neurocritical Care Fellowship Scarcity:Training program bottlenecks in North American academic medical centers are limiting protocol standardization and quality assurance oversight.
- Device-Sedative Integration Complexity:Legacy patient monitoring architectures in European hospitals require costly middleware development to achieve seamless closed-loop anesthesia delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Coma/Medically Induced Coma Market |
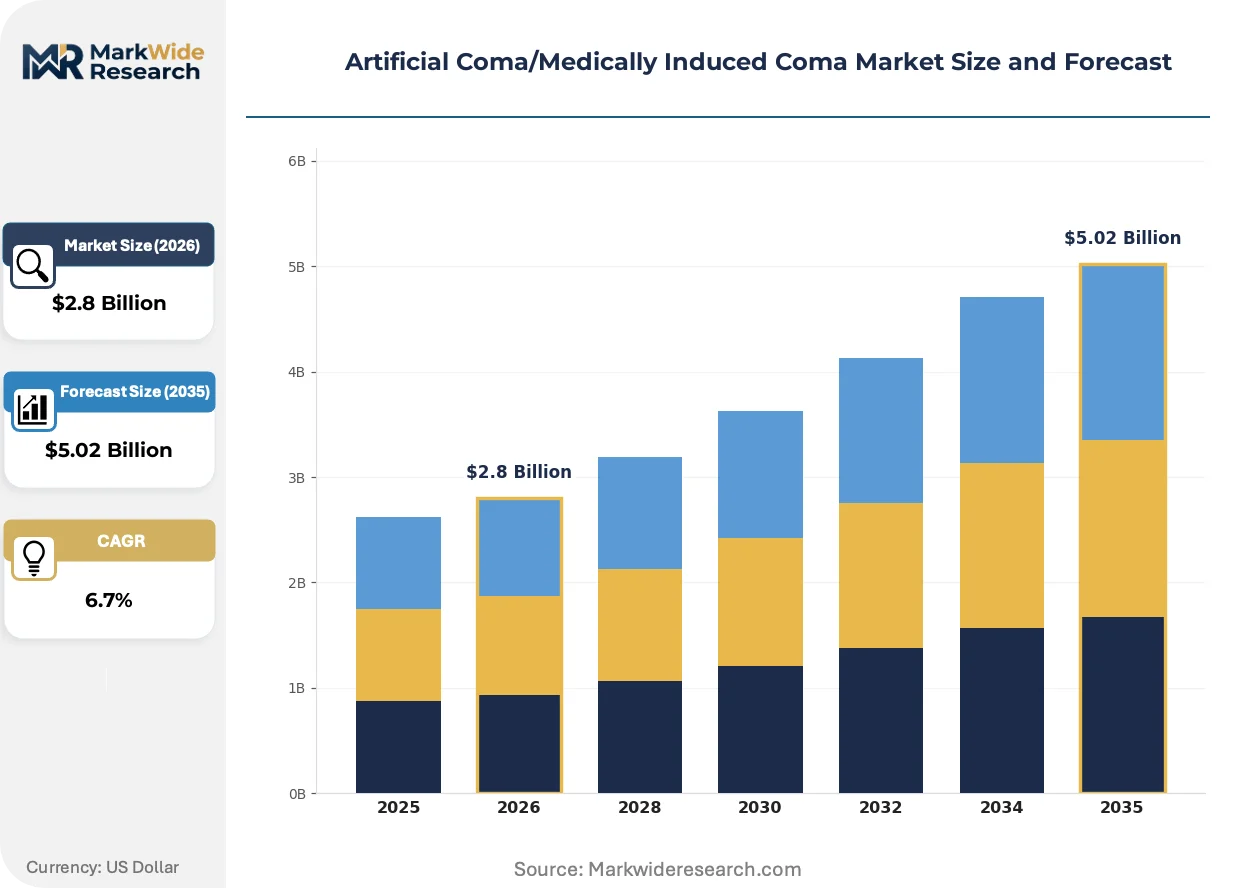
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technique: Propofol, Thiopental, Barbiturates, Benzodiazepines Indication: Head Trauma, Stroke, Cardiac Surgery, Severe Burns End User: Hospitals, Recovery Centers, Emergency Rooms, Intensive Care Units Administration Route: Intravenous, Inhalational, Epidural, Subcutaneous |
| Companies Covered | B Braun SE, Baxter Healthcare Corporation, Fresenius SE & Co. KGaA, Aspen Holdings, Piramal Enterprises Ltd, Dr Reddy's Laboratories, Hikma Pharmaceuticals, Pfizer Inc, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Coma/Medically Induced Coma Market Emerging Trajectories
Closed-loop sedation control architectures are displacing manual titration workflows, while pharmacogenomic screening and portable brain monitoring are compressing the latency between induction and therapeutic effect confirmation.
Processed electroencephalography modules embedded in compact bedside units are enabling real-time burst suppression monitoring without dedicated neurophysiology technicians. Neurosurgical ICUs at Johns Hopkins Hospital and Charité Berlin are deploying these systems for refractory intracranial hypertension cases. The form factor is miniaturizing from cart-based platforms to clip-on infusion pump accessories, collapsing the capital barrier for mid-tier trauma centers.
EMA's 2023 revision to pharmacovigilance frameworks for prolonged anesthetic exposure is mandating cumulative dose tracking across hospital admissions. This industrial consequence is forcing manufacturers to redesign drug labeling with implantable medical device-style unique device identifiers. Pentobarbital and thiopental suppliers serving the European market are responding with serialized vial tracking and blockchain-enabled adverse event reporting.
Hospital pharmacy committees are consolidating sedation purchasing around integrated critical care contracts that bundle anesthetics with infusion devices and monitoring hardware. This channel consolidation is displacing standalone pharmaceutical procurement at academic medical centers in the United States and Germany. The shift is most visible in tertiary hospitals pursuing Magnet nursing designation, where standardization across ICU pods reduces medication error variance.
Artificial Coma/Medically Induced Coma Market Segmentation
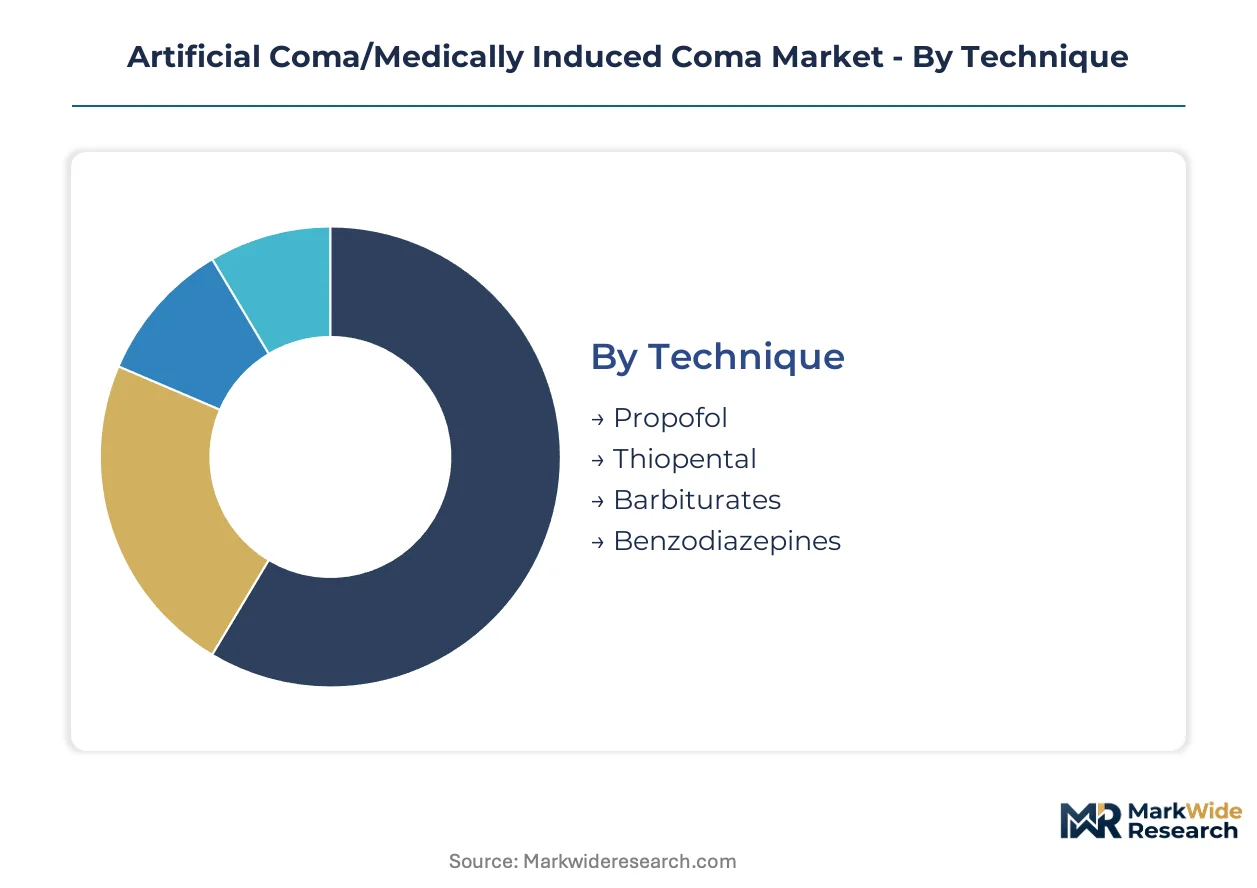
Segmentation in the artificial coma market reveals how clinical utility, regulatory constraints, and infrastructure readiness fragment purchasing decisions across acute care settings. Understanding these divides exposes where substitution pressures and premium pricing opportunities concentrate.
Technique:
Barbiturate protocols face intensifying substitution pressure from propofol in general ICUs, though refractory intracranial hypertension cases preserve their neurosurgical niche.
- Propofol:An intravenous phenol derivative emulsion enabling rapid induction and emergence through hepatic metabolism. Demand concentrates in United States community hospitals where nursing protocols favor short-acting agents for daily sedation interruption.
- Barbiturates:Pentobarbital and thiopental sodium formulations producing profound cerebral metabolic suppression via GABA receptor potentiation. Neurocritical care units at Level I trauma centers in Germany and Japan retain these protocols for refractory status epilepticus where propofol failure rates climb.
- Thiopental:Ultra-short-acting barbiturate reserved for emergency neurology units requiring immediate burst suppression.
- Benzodiazepines:Midazolam and lorazepam alternatives deployed where hemodynamic stability trumps rapid emergence.
Propofol retains volume leadership across general sedation; barbiturates hold the steepest expansion curve in specialized neurocritical care.
Indication:
Cost tier differentiation separates high-acuity trauma presentations from scheduled surgical interventions, with reimbursement intensity tracking procedural urgency.
- Head Trauma:Traumatic brain injury requiring intracranial pressure control through metabolic suppression. United States tertiary trauma centers drive protocol standardization around FDA-mandated continuous monitoring architectures.
- Stroke:Hemorrhagic and ischemic events with malignant cerebral edema. Japanese stroke centers deploy barbiturate coma for posterior circulation infarcts where decompressive options are anatomically limited.
- Cardiac Surgery:Deep hypothermic circulatory arrest cases requiring neuroprotection.
- Severe Burns:Inhalation injury with refractory hypoxemia where sedation facilitates permissive hypercapnia.
Head trauma commands the largest addressable patient volume; stroke applications are climbing the fastest as thrombectomy capabilities expand.
End User:
Customer type fragmentation reflects staffing model economics, with intensivist availability determining whether prolonged coma protocols are sustainable.
- Intensive Care Units:Dedicated neurosurgical and medical ICUs with 24-hour intensivist coverage. Academic medical centers in the United States and Germany anchor demand for integrated infusion-monitoring platforms.
- Emergency Rooms:Resuscitation bays managing refractory status epilepticus prior to ICU admission. Capacity constraints limit protocol duration to stabilization windows.
- Hospitals:General acute care facilities without dedicated neurocritical care infrastructure.
- Recovery Centers:Post-acute settings managing prolonged ventilation weaning.
Intensive Care Units dominate value capture; Emergency Rooms are expanding most quickly as pre-hospital notification systems compress door-to-sedation intervals.
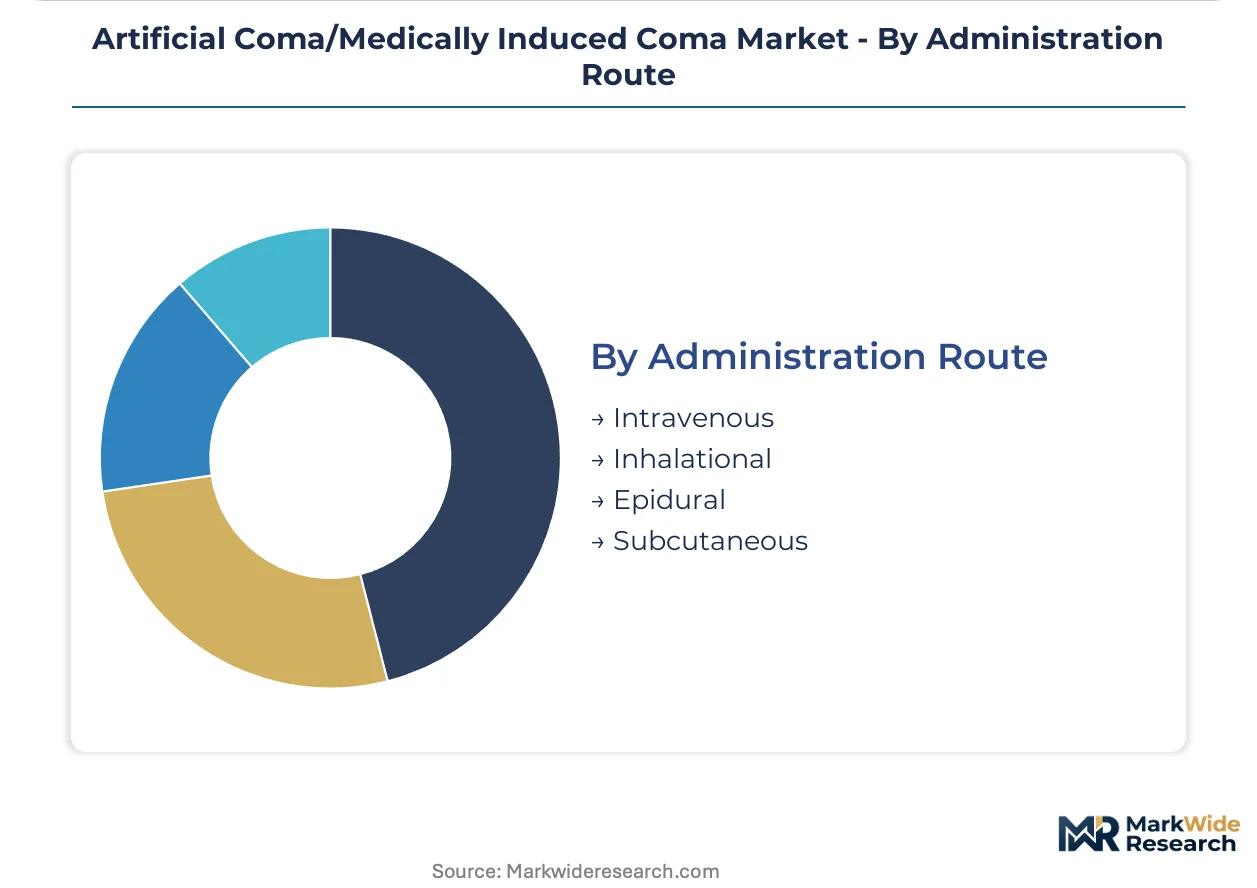
Administration Route:
Supply concentration in intravenous emulsion manufacturing shapes procurement security priorities across purchasing committees.
- Intravenous:Continuous infusion via central venous access enabling precise titration. European contract manufacturing concentration for propofol lipid emulsions exposes United States hospitals to single-source disruption risk.
- Inhalational:Isoflurane and sevoflurane delivery through anesthetic conserving devices. Cardiac surgery centers in Germany favor this route for rapid neurophysiologic recovery assessment post-circulatory arrest.
- Epidural:Regional anesthesia adjuncts in polytrauma with thoracic injury.
- Subcutaneous:Palliative sedation applications where vascular access is compromised.
Intravenous administration retains absolute volume leadership; inhalational delivery is gaining share fastest in specialized cardiac centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for artificial coma protocols diverge sharply across major markets. United States hospitals favor propofol-based short-acting regimens with daily interruption protocols, while German and Japanese neurocritical care units retain barbiturate dominance for refractory intracranial hypertension. This technique-mix differential reflects varying intensivist staffing models, trauma center certification standards, and reimbursement structures for prolonged sedation.
United States
Level I trauma center density in Baltimore, Houston, and Los Angeles anchors demand for integrated infusion-monitoring platforms. FDA continuous sedation monitoring mandates institutionalize advanced alarm architectures across tertiary hospitals. The Johns Hopkins neurosurgical ICU in Baltimore deploys closed-loop burst suppression systems for refractory status epilepticus cases.
Germany
Charité Berlin and Heidelberg University Hospital drive protocol standardization for barbiturate coma in posterior circulation stroke. EMA pharmacovigilance frameworks for prolonged anesthetic exposure mandate cumulative dose tracking across admissions. The Baden-Württemberg medical device cluster around Tuttlingen supplies infusion pump interoperability hardware for ISO 13485-compliant sedation platforms.
Japan
Stroke center certification expansion in Tokyo and Osaka accelerates thiopental adoption for malignant cerebral edema. PMDA guidelines on neurocritical care device approval harmonize with EU MDR interoperability standards. The Kansai region's academic medical centers pioneer portable processed EEG modules for bedside burst suppression monitoring.
Brazil
Greenfield tertiary hospital construction in São Paulo and Rio de Janeiro installs integrated critical care infrastructure without legacy equipment constraints. ANVISA regulatory pathways for imported infusion devices favor European-certified platforms with pre-existing CE marking. The São Paulo metropolitan corridor concentrates demand for mid-tier propofol emulsion supply contracts.
Saudi Arabia
SFDA medical device registration reforms accelerate deployment of multi-modal sedation platforms in Riyadh and Jeddah trauma centers. Ministry of Health hospital privatization programs specify intensivist-staffed neurocritical care units in new facility designs. The King Faisal Specialist Hospital in Riyadh anchors regional protocol standardization for cardiac surgery neuroprotection.
Artificial Coma/Medically Induced Coma Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in artificial coma market structure. Baxter Healthcare Corporation and Fresenius SE & Co. KGaA occupy the integrated tier through captive infusion platform and hospital supply network combinations. Specialist pharmaceutical manufacturers compete on injectable anesthetic portfolios and regional regulatory registration speed. Dominant competitive moves include strategic partnerships between device and drug manufacturers for bundled critical care contracts, and geographic expansion through distributor acquisitions in emerging markets.
Within the integrated tier, Baxter Healthcare Corporation and Fresenius SE & Co. KGaA anchor institutional contract positions through combined device and pharmaceutical offerings. Among specialist pharmaceutical suppliers, Hikma Pharmaceuticals exemplifies the emerging market-focused archetype with concentrated injectable anesthetic portfolios. Piramal Enterprises Ltd occupies a position bridging domestic Indian hospital supply with export-oriented regulatory registration capabilities. These three named entities represent distinct competitive positioning vectors: integrated platform dominance, emerging market volume capture, and regulatory agility across multiple jurisdictions.
| Leading Market Players |
|---|
| B Braun SE |
| Baxter Healthcare Corporation |
| Fresenius SE & Co. KGaA |
| Aspen Holdings |
| Piramal Enterprises Ltd |
| Dr Reddy's Laboratories |
| Hikma Pharmaceuticals |
| Pfizer Inc |
| AstraZeneca |
| Others |
Supply Flow & Price Mechanics
European contract manufacturing concentration for propofol lipid emulsions creates scale economies that simultaneously depress price floors and amplify single-source disruption exposure across United States hospital purchasing committees. This structural configuration forces buyers into long-term offtake commitments with Baxter Healthcare Corporation and Fresenius SE & Co. KGaA to secure volume allocation, while mid-tier trauma centers absorb spot-market volatility for barbiturate alternatives.
Pricing Analysis
Contract-based long-term offtake agreements dominate artificial coma agent procurement, with integrated critical care contracts bundling propofol emulsions, infusion pumps, and processed EEG modules under single-source terms. Price differentiation separates FDA-cleared platforms with ISO 13485 alarm integration from standard sedation equipment lacking interoperability certification. Pricing pressure stems from EMA pharmacovigilance mandates requiring serialized vial tracking and blockchain-enabled adverse event reporting, which inflate compliance costs. Community hospitals in the United States exhibit highest price sensitivity due to constrained pharmacy budgets, while German Level I trauma centers prioritize premium-tier platforms with closed-loop burst suppression architectures regardless of cost.
Supply Chain Analysis
Italy and Germany anchor propofol lipid emulsion manufacturing through European contract manufacturing organizations serving global hospital networks. Active pharmaceutical ingredient production for pentobarbital and thiopental sodium draws from Indian specialty chemical manufacturers and domestic United States DEA-registered facilities. Supply chain risk centers on single-source vulnerability for propofol emulsion concentrate, where Italian manufacturing site disruption would cascade across North American tertiary hospitals within weeks. Distribution runs through hospital supply networks controlled by Fresenius SE & Co. KGaA and group purchasing organizations consolidating sedation procurement at academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The artificial coma market rewards players who control intensivist-caliber protocol expertise and integrated device-drug platforms, with scarcity concentrated in neurocritical care fellowship training and EMA-certified serialization infrastructure. Organizations bridging this capability gap capture institutional contract renewals as hospital pharmacy committees consolidate purchasing around bundled critical care offerings.
For Market Incumbents: Shield market position by deepening backward integration into propofol lipid emulsion manufacturing to reduce European single-source dependency, while accelerating ISO 13485-certified infusion pump interoperability investments to preempt EU MDR compliance deadlines. The threat of inhalational anesthetic resurgence in German cardiac surgery centers demands defensive patent portfolio expansion around isoflurane delivery system interfaces. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for processed EEG modules with embedded burst suppression algorithms offer the most penetrable entry vector, targeting mid-tier United States trauma centers lacking dedicated neurophysiology technicians. Brazil and Saudi Arabia greenfield hospital construction presents white-space demand for mid-tier propofol supply contracts without legacy equipment displacement costs. A go-to-market strategy anchored by distributor partnerships with established critical care equipment vendors accelerates hospital pharmacy committee access. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated platform providers combining infusion devices with captive anesthetic supply, as hospital system consolidation favors single-vendor relationships over fragmented procurement. Long-term viability across the projection horizon depends on regulatory agility across FDA, EMA, and PMDA jurisdictions rather than pure manufacturing scale. Acquisition targets should demonstrate pre-existing CE marking and active SFDA registration pipelines for Middle East expansion. The signal to watch is intensivist staffing ratio compression at United States Level I trauma centers, which accelerates automation demand and premium platform pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR compliance unlocks EU hospital system contracts requiring ISO 13485 alarm integration. |
| Hospital System Partnership | Johns Hopkins and Charité Berlin anchor protocol standardization that cascades to affiliated networks. |
| Software Companion Development | Processed EEG modules with real-time burst suppression monitoring reduce nursing labor intensity. |
| Backward Integration | In-house propofol emulsion production mitigates European contract manufacturing concentration risk. |
| Reimbursement Strategy | CMS Medicare coding alignment for prolonged sedation with continuous monitoring expands addressable patient volume. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA pharmacovigilance databases, and hospital procurement contract disclosures. Intensive care unit directors, neurocritical care fellowship program directors, hospital pharmacy committee chairs, and biomedical engineering managers at Level I trauma centers in the United States, Germany, and Japan provided operational perspective on protocol adoption barriers. Secondary validation incorporated GPO contract databases, CMS Medicare claims data, and ANVISA medical device registration records. Bottom-up patient volume modeling and top-down pharmaceutical manufacturer revenue analysis were cross-referenced for triangulation.
Segmentation dimensions modeled include technique type, indication severity, end-user infrastructure tier, and administration route complexity across the projection horizon. CAGRs were derived from historical neurocritical care admission trajectories and pharmaceutical pricing elasticity estimates. Forecast inputs incorporated PMDA stroke center certification expansion timelines, EMA cumulative dose tracking mandate implementation schedules, and United States trauma center designation density projections.
Underlying assumptions cover sustained intensivist staffing shortages, stable propofol emulsion manufacturing capacity, and harmonized EU MDR enforcement timelines, with deviation risk concentrated in alternative neuroprotection modality substitution rates and inhalational anesthetic technology breakthroughs. Recalibration cycles align with material shifts in FDA continuous monitoring guidance revisions and emerging market hospital privatization program specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Anesthesiology
Dental Anesthesia Market
Anesthesiology
Anaesthesia Machines Market
Anesthesiology
Delirium Market
Anesthesiology
Anesthesia Breathing Circuits Market
Anesthesiology
Anesthetics Market
Anesthesiology
Airway Catheters Market
Anesthesiology
Global Anesthesia and Respiratory Devices Market
Anesthesiology
Global Anesthesia Gases Market
Anesthesiology
Anesthesia Delivery Units Market
Anesthesiology
Anesthesia CO2 Absorbent Market
Anesthesiology
Endotracheal Tube Cuffs Market
Anesthesiology
Anesthesia Breathing Bags Market
Anesthesiology
US Anesthesiology Service Market
Anesthesiology
Aspirating System Market
Anesthesiology
Vasopressin for Vasoplegic Shock Market
Anesthesiology
Global Anesthesia Delivery Systems Market