
 Global Anesthesia and Respiratory Devices Market | 2026-2036
Global Anesthesia and Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anesthesia and Respiratory Devices Market Foresight
The EU Green Deal's medical device sustainability criteria is shifting procurement specifications toward energy-efficient anesthesia delivery systems. Drägerwerk AG & Co. KGaA leverages its German manufacturing base to dominate European ventilator supply chains. Medtronic anchors North American hospital accounts through intensive care application specialization. Fisher & Paykel Healthcare Limited competes in humidification technology for acute respiratory support.
Anesthesia and respiratory devices encompass mechanically or pneumatically actuated systems designed to deliver precise gas mixtures, airway pressure control within 5-20 cm H₂O ranges, and ventilatory support for patients undergoing surgery or managing pulmonary insufficiency. These systems integrate flow sensors, vaporizers, and breathing circuits to maintain oxygenation and eliminate carbon dioxide during controlled ventilation or spontaneous breathing assistance. Ventilators and anesthesia machines command the largest installed base across hospital end users, reflecting their centrality to surgical throughput and critical care capacity. Oxygen concentrators and CPAP devices sustain faster expansion through home healthcare provider channels, where reimbursement shifts favor decentralized respiratory management for chronic conditions.
FDA 510(k) pathways and EU MDR conformity assessments govern market access, with ISO 80601-2-80 electrical safety standards shaping product design requirements for anesthesia workstations. Japan's PMDA enforces JIS T 0601-1 electromagnetic compatibility rules that filter non-compliant imports from Asian supply chains. Stakeholders must monitor evolving EPA sterilization gas emissions rules and their impact on ethylene oxide-dependent device reprocessing economics.
Market Dynamics
Hospital procurement departments are consolidating anesthesia workstation purchases into multi-year fleet agreements, compressing vendor selection cycles and privileging manufacturers with integrated service networks over component specialists.
Growth Catalysts
- EU MDR compliance deadlines:German university hospital networks are accelerating perioperative infrastructure modernization to meet conformity assessment timelines. This creates replacement demand for legacy anesthesia delivery systems.
- FDA emergency use authorization reforms:North American health systems are expanding ventilator fleet procurement to satisfy revised pandemic preparedness mandates. ICU capacity planning now embeds mechanical redundancy requirements.
- Home healthcare channel expansion:Reimbursement frameworks in multiple jurisdictions favor decentralized respiratory management for chronic obstructive pulmonary disease. Oxygen concentrators and CPAP devices capture volume through durable medical equipment distributors.
Market Restraints
- Ethylene oxide sterilization dependency:EPA emissions rules are tightening reprocessing economics for breathing circuits and vaporizer components. Alternative sterilization modalities require capital-intensive facility retrofits.
- Semiconductor flow sensor supply:Precision gas measurement modules concentrate among Asian contract manufacturers. Geopolitical friction threatens just-in-time delivery for anesthesia workstation production lines.
- Isoflurane and sevoflurane vaporizer calibration:Agent-specific delivery systems lock hospitals into proprietary consumable ecosystems. Switching costs inhibit competitive displacement of installed anesthesia machines.
Strategic Opportunities
- Energy-efficient anesthesia delivery:EU Green Deal sustainability criteria are shifting procurement specifications toward low-power consumption workstations. German manufacturers leverage domestic production to capture specification-driven demand.
- AI-integrated ventilator weaning protocols:Machine learning algorithms for spontaneous breathing trial prediction are converging with mechanical ventilation hardware. Critical care units in tertiary hospitals pilot automated liberation pathways.
- Direct-to-home respiratory therapy:Sleep apnea diagnostics and CPAP titration are migrating from hospital sleep centers to telemedicine-enabled home channels. Remote monitoring platforms displace traditional polysomnography workflows.
Industry Challenges
- Biomedical engineering specialization:Anesthesia workstation field service requires combined competencies in pneumatic systems, electronics, and clinical workflow integration. Training pipelines lag fleet expansion timelines.
- Legacy HL7 interface fragmentation:Electronic health record connectivity for anesthesia information management systems demands customized middleware development. Hospital IT departments face integration backlogs.
- EU MDR technical documentation:Conformity assessment body capacity constraints extend certification cycles for Class IIb respiratory devices. Small manufacturers face survival-threatening approval delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anesthesia and Respiratory Devices Market |
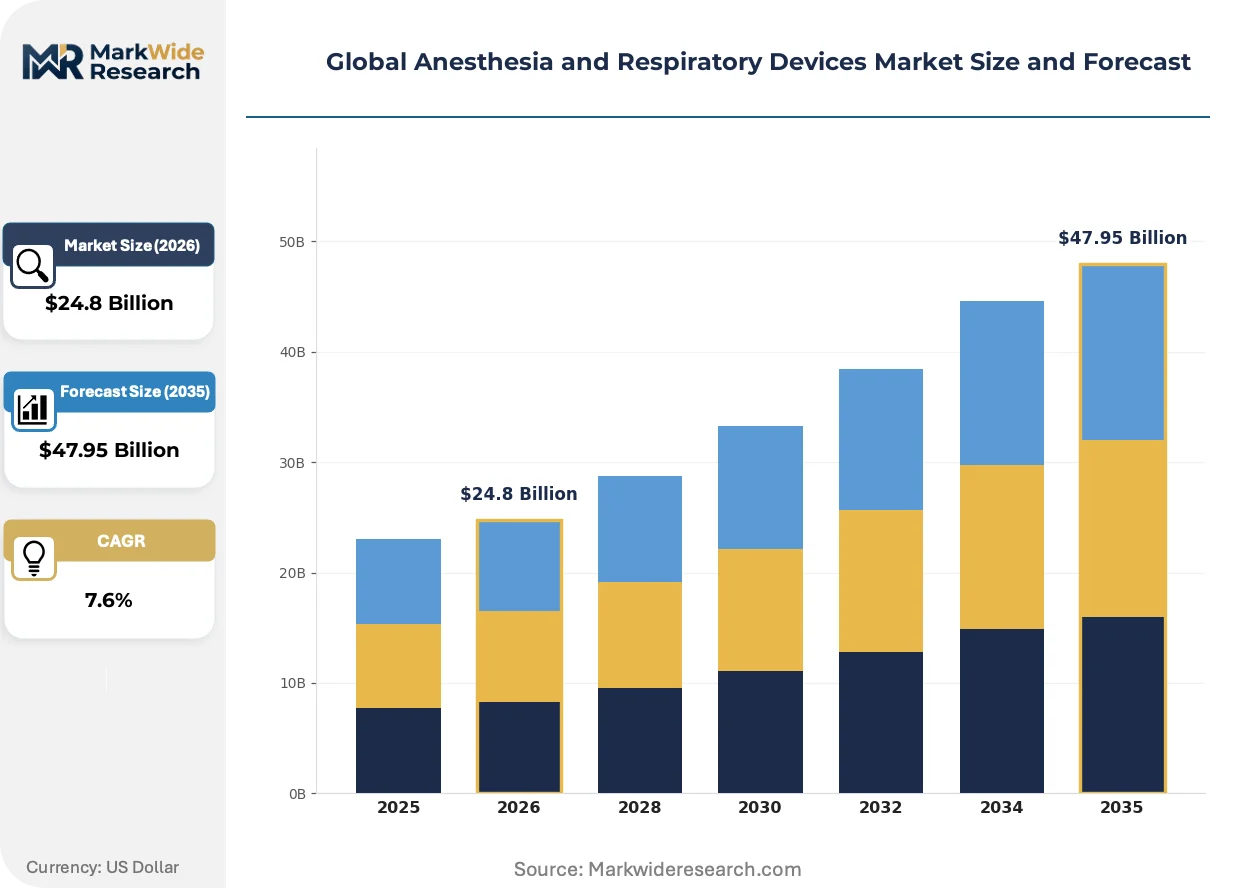
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $47.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anesthesia Machines, Ventilators, Oxygen Concentrators, Nebulizers, CPAP Devices Technology: Mechanical, Electrical, Electronic, Microprocessor-Based, Pneumatic Application: Surgical Procedures, Emergency Care, Sleep Apnea Management, Chronic Respiratory Disease, Intensive Care End User: Hospitals, Ambulatory Surgical Centers, Emergency Response Units, Home Healthcare Providers |
| Companies Covered | Drägerwerk AG & Co. KGaA, Getinge AB, Medtronic, Smiths Group plc, Masimo, Koninklijke Philips N.V., GE Healthcare, Fisher & Paykel Healthcare Limited, Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anesthesia and Respiratory Devices Market Shifts & Advancements
Digital integration and sustainability mandates are restructuring how anesthesia and respiratory devices are specified, operated, and maintained across acute and ambulatory settings.
Closed-loop anesthesia delivery systems incorporating bispectral index monitoring and automated propofol titration are automating depth-of-control maintenance. Tertiary surgical centers in Germany and the United States deploy these platforms for prolonged neurosurgical procedures. The technology is automating anesthesiologist cognitive load reduction while standardizing emergence profiles across operator experience levels.
Japan's PMDA has tightened JIS T 0601-1 electromagnetic compatibility enforcement for imported anesthesia workstations. Non-compliant devices face automatic import suspension without grandfathering provisions. Asian contract manufacturers serving Japanese hospital groups are restructuring printed circuit board shielding and filtration architectures to satisfy revised testing protocols.
Hospital supply chain departments are unbundling preventive maintenance contracts from capital equipment purchases. Independent service organizations and manufacturer-affiliated technical groups now compete for multi-vendor anesthesia machine fleet coverage. This transition is most visible in North American integrated delivery networks seeking to reduce per-procedure equipment cost allocations.
Global Anesthesia and Respiratory Devices Market Segmentation
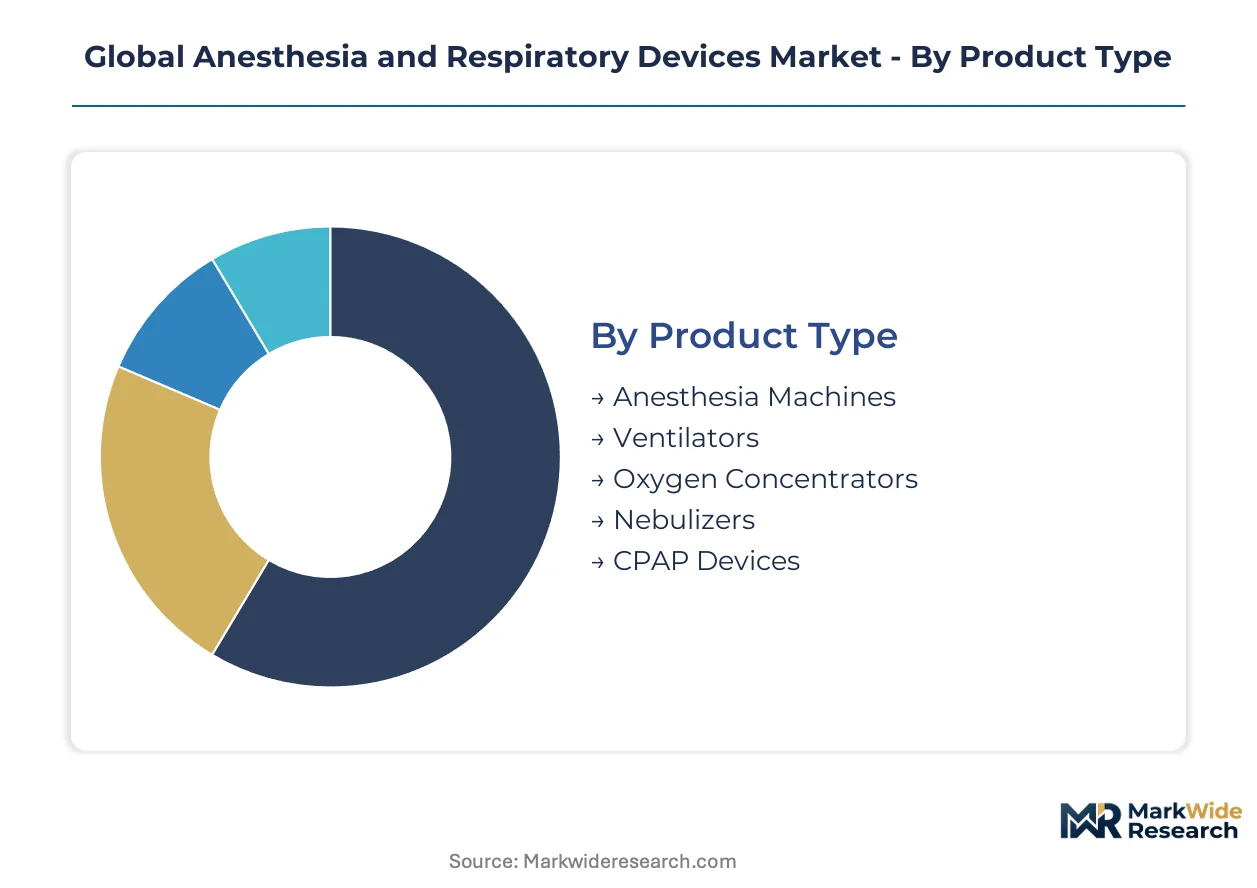
Segmentation reveals how regulatory pathways, clinical settings, and technical architectures fragment commercial opportunity across the anesthesia and respiratory devices landscape. Procurement specifications diverge sharply between acute hospital systems and decentralized home care channels, while certification burdens cluster disproportionately in electronic and microprocessor-based technologies.
Product Type:
FDA 510(k) and EU MDR Class IIb conformity assessments concentrate on anesthesia machines and ventilators, while oxygen concentrators and CPAP devices navigate lighter Class IIa pathways with reduced clinical data requirements.
- Anesthesia Machines:Integrated workstations combine gas delivery, vaporizer control, and patient monitoring within ISO 80601-2-80 electrical safety frameworks. German university hospital networks drive replacement demand as EU MDR deadlines compress procurement timelines for legacy system upgrades.
- Ventilators:Critical care mechanical ventilation systems incorporate precision flow sensors and adaptive pressure control algorithms. North American health systems are expanding fleet procurement following FDA emergency use authorization reforms that embed pandemic redundancy into ICU capacity planning.
- Oxygen Concentrators:Pressure swing adsorption units separate nitrogen from ambient air to deliver therapeutic oxygen concentrations. Home healthcare reimbursement shifts favor durable medical equipment channel expansion for chronic obstructive pulmonary disease management.
- Nebulizers:Jet and ultrasonic aerosol generators convert liquid bronchodilators into respirable particle distributions. Pediatric asthma protocols in ambulatory settings sustain volume for compressor-driven delivery systems.
- CPAP Devices:Continuous positive airway pressure generators maintain pharyngeal patency through nasal or oronasal interfaces. Telemedicine-enabled home sleep apnea diagnostics are displacing traditional polysomnography workflows.
Ventilators sit at the top of the volume ranking, with oxygen concentrators climbing the fastest through home healthcare channel expansion.
Technology:
Cost tier stratification separates capital-intensive electronic platforms from maintenance-heavy pneumatic alternatives, with microprocessor-based systems commanding premium positioning through software-enabled feature differentiation.
- Mechanical:Spring-loaded valves and bellows assemblies provide gas mixing without electrical dependency. Resource-constrained emergency response units in developing markets sustain demand for ruggedized mechanical ventilator architectures.
- Electrical:Solenoid-actuated flow control replaces manual adjustment with programmable setpoints. Mid-tier anesthesia workstations in ambulatory surgical centers balance acquisition cost against automated safety interlock functionality.
- Electronic:Analog sensor arrays and discrete logic circuits enable proportional valve response. Transitional product architectures bridge pneumatic legacy systems toward digital integration pathways.
- Microprocessor-Based:Embedded software platforms execute closed-loop control algorithms with real-time physiological feedback. Tertiary surgical centers in Germany and the United States deploy bispectral index-integrated propofol titration for neurosurgical depth-of-anesthesia automation.
- Pneumatic:Compressed gas-driven actuation eliminates electrical ignition risks in oxygen-enriched environments. Hyperbaric and military field applications specify pneumatic redundancy for electromagnetic compatibility resilience.
Microprocessor-based systems capture the steepest expansion trajectory as AI-integrated weaning protocols converge with mechanical ventilation hardware.
Application:
Customer type fragmentation separates high-acuity hospital procurement from decentralized chronic disease management, with reimbursement frameworks determining channel economics across surgical, emergency, and home-based settings.
- Surgical Procedures:General anesthesia delivery for operative interventions requires precise inhaled agent control and neuromuscular blockade reversal. Perioperative infrastructure modernization in German hospital networks accelerates workstation replacement cycles.
- Emergency Care:Rapid sequence intubation and mechanical ventilation initiation in pre-hospital and trauma settings demand portable, ruggedized equipment. FDA emergency use authorization reforms are expanding North American ventilator fleet procurement for pandemic preparedness mandates.
- Sleep Apnea Management:Diagnostic polysomnography and therapeutic CPAP titration address obstructive sleep-disordered breathing. Direct-to-home respiratory therapy channels are migrating sleep diagnostics from hospital centers to telemedicine platforms.
- Chronic Respiratory Disease:Long-term oxygen therapy and non-invasive ventilation support for chronic obstructive pulmonary disease and interstitial lung disorders. Reimbursement frameworks in multiple jurisdictions favor decentralized respiratory management through durable medical equipment distributors.
- Intensive Care:Prolonged mechanical ventilation with lung-protective strategies and automated liberation protocols. Critical care units in tertiary hospitals pilot machine learning algorithms for spontaneous breathing trial prediction.
Intensive care commands the largest installed base, with sleep apnea management gaining share fastest through home healthcare channel displacement of traditional diagnostic workflows.
End User:
Supply concentration in integrated service networks privileges manufacturers with multi-vendor maintenance capabilities over component specialists, reshaping vendor selection dynamics across institutional settings.
- Hospitals:Acute care systems with 24-hour surgical throughput and critical care capacity require anesthesia workstation fleet standardization. North American integrated delivery networks are unbundling preventive maintenance contracts from capital equipment purchases.
- Ambulatory Surgical Centers:Same-day procedure facilities prioritize compact anesthesia delivery with rapid turnover capabilities. Cost pressure drives procurement toward streamlined mechanical configurations with reduced vaporizer agent options.
- Emergency Response Units:Pre-hospital and disaster medical assistance teams specify lightweight, battery-independent ventilation. Military and humanitarian logistics channels demand ruggedized pneumatic architectures for field deployment reliability.
- Home Healthcare Providers:Durable medical equipment distributors manage oxygen concentrator and CPAP device provisioning for chronic respiratory conditions. Remote monitoring platforms enable telemedicine-enabled adherence tracking and therapy optimization.
Hospitals anchor procurement volume, with home healthcare providers expanding most quickly through reimbursement-driven decentralization of chronic respiratory management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Anesthesia device manufacturing traces its industrial lineage to German precision engineering traditions established in Lübeck and Tuttlingen during the early twentieth century, with subsequent scaling in the United States through post-war hospital infrastructure buildouts. Contemporary demand distributes across acute care modernization programs in multiple jurisdictions.
United States
Hospital systems in the United States are expanding ventilator fleet procurement following FDA emergency use authorization reforms that embed pandemic redundancy into ICU capacity planning. The EPA is tightening ethylene oxide emissions rules for sterilization-dependent device reprocessing. Integrated delivery networks in the Midwest and Southeast are unbundling preventive maintenance contracts from capital equipment purchases.
Germany
University hospital networks across Germany are accelerating perioperative infrastructure modernization to satisfy EU MDR conformity assessment timelines. The EU Green Deal's medical device sustainability criteria are shifting procurement specifications toward energy-efficient anesthesia delivery systems. Manufacturing clusters in Lübeck and Tuttlingen leverage domestic production bases to capture specification-driven demand from hospital procurement departments.
Japan
PMDA enforcement of JIS T 0601-1 electromagnetic compatibility rules is filtering non-compliant anesthesia workstation imports from Asian supply chains. METI guidelines on medical device software validation are extending certification cycles for microprocessor-based systems. Tokyo and Osaka metropolitan hospital networks are piloting closed-loop anesthesia delivery platforms for neurosurgical procedures.
China
NMPA registration pathways for Class III respiratory devices are compressing market access timelines for domestic manufacturers. The country's dual carbon goals are pressuring hospital procurement toward energy-efficient ventilation platforms. Manufacturing concentration in the Yangtze River Delta is scaling precision flow sensor module production for anesthesia workstation integration.
India
CDSCO medical device rules are aligning with IMDRF standards to streamline import registration for critical care ventilators. The PLI scheme for medical devices is incentivizing domestic manufacturing of oxygen concentrators for chronic respiratory disease management. Hospital networks in Maharashtra and Karnataka are modernizing perioperative infrastructure through public-private partnership models.
Global Anesthesia and Respiratory Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth, with microprocessor-based anesthesia workstations commanding pricing multiples over mechanical alternatives. Market structure exhibits tiered consolidation around integrated service networks and component specialists. Three archetypes dominate: diversified medical technology conglomerates with intensive care application specialization, German-engineered precision manufacturers with domestic production advantages, and Asia-Pacific-based respiratory support specialists in humidification and home care channels. Dominant competitive moves include multi-year fleet agreement consolidation by hospital procurement departments and unbundling of preventive maintenance contracts from capital equipment sales.
Within the diversified conglomerate tier, Medtronic and GE Healthcare represent positioning anchored in North American hospital account density and intensive care application breadth. Among German-engineered specialists, Drägerwerk AG & Co. KGaA exemplifies the archetype of domestic manufacturing base leverage for European ventilator supply chain dominance. Fisher & Paykel Healthcare Limited occupies a position within the Asia-Pacific specialist tier focused on respiratory support technologies.
| Leading Market Players |
|---|
| Drägerwerk AG & Co. KGaA |
| Getinge AB |
| Medtronic |
| Smiths Group plc |
| Masimo |
| Koninklijke Philips N.V. |
| GE Healthcare |
| Fisher & Paykel Healthcare Limited |
| Teleflex Incorporated |
| Others |
Supply & Pricing Matrix
Precision flow sensors sourced from Asian contract manufacturers feed into tiered workstation pricing that stratifies across ISO 80601-2-80 certification grades, with German production clusters commanding premium positioning over Southeast Asian assembly alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates microprocessor-based anesthesia workstations with closed-loop control from mechanical ventilators for emergency response units. Price differentiation rests on FDA 510(k) clearance status and EU MDR Class IIb conformity assessment completion, with German university hospital networks showing lowest price sensitivity for energy-efficient platforms. Cost compression in mid-tier electrical workstations is intensifying because semiconductor flow sensor supply constraints are forcing longer lead times. Ambulatory surgical centers in North America exhibit highest price sensitivity, prioritizing compact mechanical configurations with reduced vaporizer agent options.
Supply Chain Analysis
Direct-to-hospital channels handle fleet agreement procurement for integrated delivery networks, while durable medical equipment distributors manage oxygen concentrator volume for home healthcare providers. Manufacturing concentrates in Germany for anesthesia workstation final assembly, China for precision flow sensor module production, and Malaysia for breathing circuit component molding. Raw material dependencies draw from medical-grade polymers for circuit housings, rare earth elements for sensor magnetics, and specialized alloys for vaporizer heat exchangers. Single-source vulnerability in Taiwanese semiconductor foundries threatens just-in-time delivery for microprocessor-based system production lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German university hospital procurement timelines compress faster than North American integrated delivery network cycles, creating arbitrage opportunities for manufacturers with EU MDR pre-certification and FDA 510(k) parallel submission capabilities.
For Market Incumbents: Deepen backward integration into precision flow sensor production to offset Asian contract manufacturer concentration risk, while expanding captive service networks across North American Midwest and Southeast integrated delivery networks. Threat from emerging Asia-Pacific humidification specialists in home healthcare channels demands preemptive channel control investments in durable medical equipment distributor relationships. For New Entrants and Emerging Players: The gap between premium microprocessor-based workstations and economy mechanical ventilators offers entry space for mid-tier electrical platforms with programmable safety interlocks. Target ambulatory surgical centers in cost-pressured North American markets with streamlined anesthesia delivery configurations. Go-to-market leverage rests on unbundled preventive maintenance contracts that compete against manufacturer-affiliated technical groups. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR technical documentation requirements exceed small manufacturer survival capacity. Long-term viability favors diversified medical technology conglomerates with intensive care application breadth and German-engineered precision manufacturers with domestic production advantages. Signal to watch: conformity assessment body queue lengths for Class IIb respiratory devices.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Assessment Acceleration | Compresses certification cycles for anesthesia workstation manufacturers ahead of German hospital procurement deadlines. |
| FDA 510(k) Parallel Submission Pathway | Enables simultaneous market access in North American and European jurisdictions for ventilator fleet suppliers. |
| Hospital System Fleet Agreement Consolidation | Privileges manufacturers with integrated service networks over component specialists in multi-year procurement cycles. |
| Software Companion Development for Closed-Loop Control | Integrates bispectral index monitoring with automated propofol titration for neurosurgical depth-of-anesthesia automation. |
| Reimbursement Strategy for Home Healthcare Channels | Captures oxygen concentrator and CPAP device volume through durable medical equipment distributor relationships. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and anesthesia workstation field service technicians with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and ISO 80601-2-80 certification registries. Bottom-up installed base estimates triangulated against top-down healthcare expenditure flows.
Historical reference periods anchored volume and value trajectories across the projection horizon, with segmentation modeling across product type, technology architecture, clinical application, and end-user channel. CAGRs derived from weighted regression across disclosed manufacturer shipment data and hospital capital equipment budget allocations, incorporating semiconductor supply lead times and ethylene oxide sterilization facility capacity as industry-specific forecast inputs.
Caveats apply where EPA emissions rule enforcement, EU MDR conformity assessment body capacity constraints, or geopolitical friction in Asian semiconductor supply chains could materially shift the outlook. Forecasts reflect documented assumptions about reimbursement framework stability and pandemic preparedness mandate persistence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Anesthesiology
US Anesthesiology Service Market
Anesthesiology
Anesthetics Market
Anesthesiology
Anesthesia Delivery Units Market
Anesthesiology
Airway Catheters Market
Anesthesiology
Inhalation Anesthetics Market
Anesthesiology
Artificial Coma/Medically Induced Coma Market
Anesthesiology
Global Anesthesia Delivery Systems Market
Anesthesiology
Delirium Market
Anesthesiology
Smart Anesthesia System Market
Anesthesiology
Anaesthesia Machines Market
Anesthesiology
Global Anesthesia Endotracheal Tubes Market
Anesthesiology
Epinephrine Market
Anesthesiology
Global Anesthesia Gases Market
Anesthesiology
Aspirating System Market
Anesthesiology
Global Inhalation Anesthesia Market
Anesthesiology
Sedation in ICU Setting Market