
 Anesthesia Breathing Bags Market | 2026-2036
Anesthesia Breathing Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Anesthesia Breathing Bags Market Analysis
Ambulatory surgical centers is consolidating as the fastest-growing end-use channel for anesthesia breathing bags, while hospital purchasing committees tighten standardization protocols. Smiths Medical leverages its integrated anesthesia workstation portfolio to bundle breathing bag contracts with ventilator sales. Drägerwerk anchors European supply relationships through its dominance in operating room infrastructure. Ambu competes aggressively on disposable latex-free formulations for outpatient settings.
Anesthesia breathing bags are collapsible reservoir devices, typically manufactured from medical-grade silicone, polyvinyl chloride, or rubber, designed to store and deliver oxygen-anesthetic gas mixtures while enabling manual ventilation control during surgical or emergency procedures. Disposable polyvinyl chloride segments dominate volume due to infection control mandates, though silicone variants command premium positioning in reusable programs where sterilization cycles exceed fifty uses. Pediatric configurations represent a specialized margin pool constrained by dimensional precision requirements and smaller production batches.
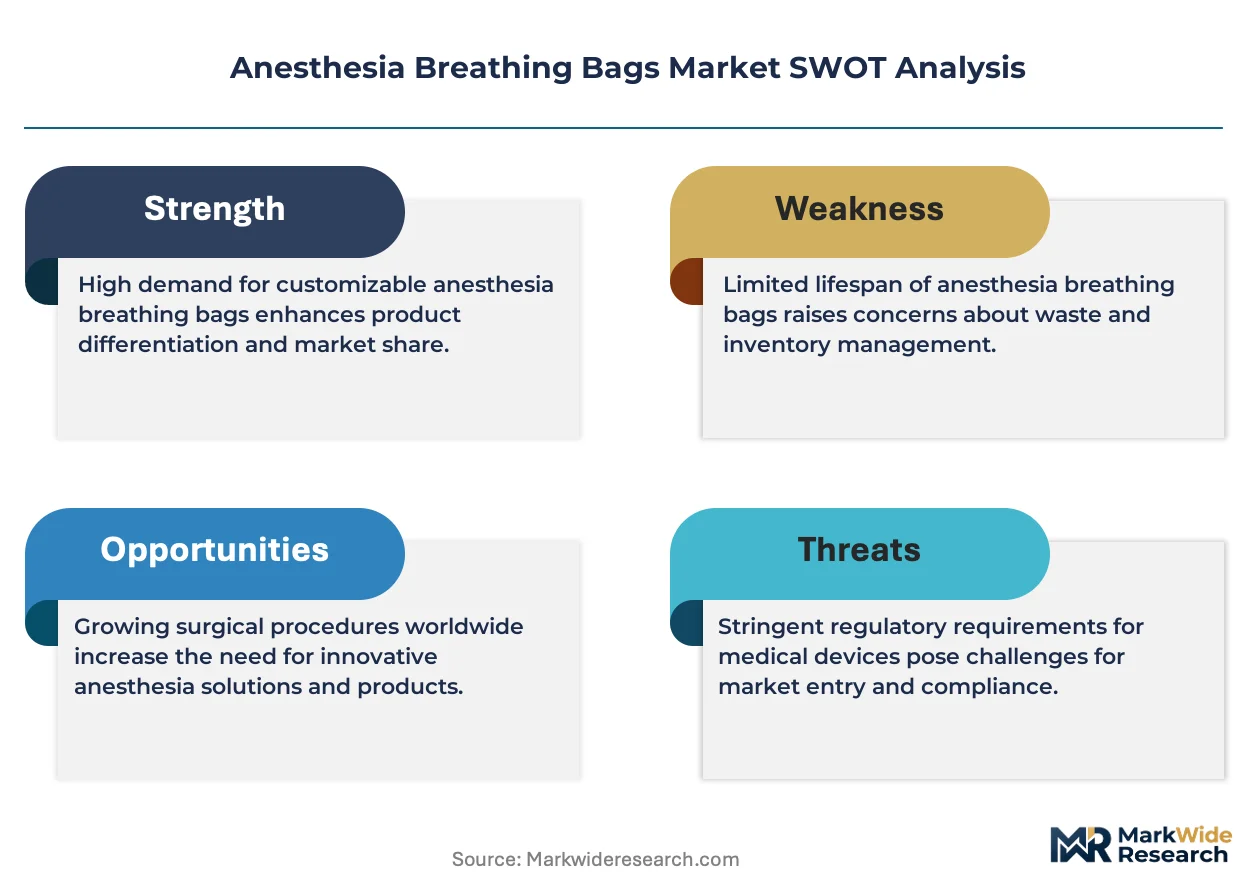
FDA 510(k) clearance pathways and ISO 5362 standards govern material biocompatibility and performance validation for breathing bags sold in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for reusable systems entering European markets. Facilities must reconcile these divergent compliance costs against total cost-of-ownership models spanning reprocessing labor, sterilization validation, and single-use waste disposal fees. Stakeholders should monitor how sustainability reporting pressures under the EU Corporate Sustainability Reporting Directive reshape procurement scoring weights for disposable versus reusable anesthesia accessories.
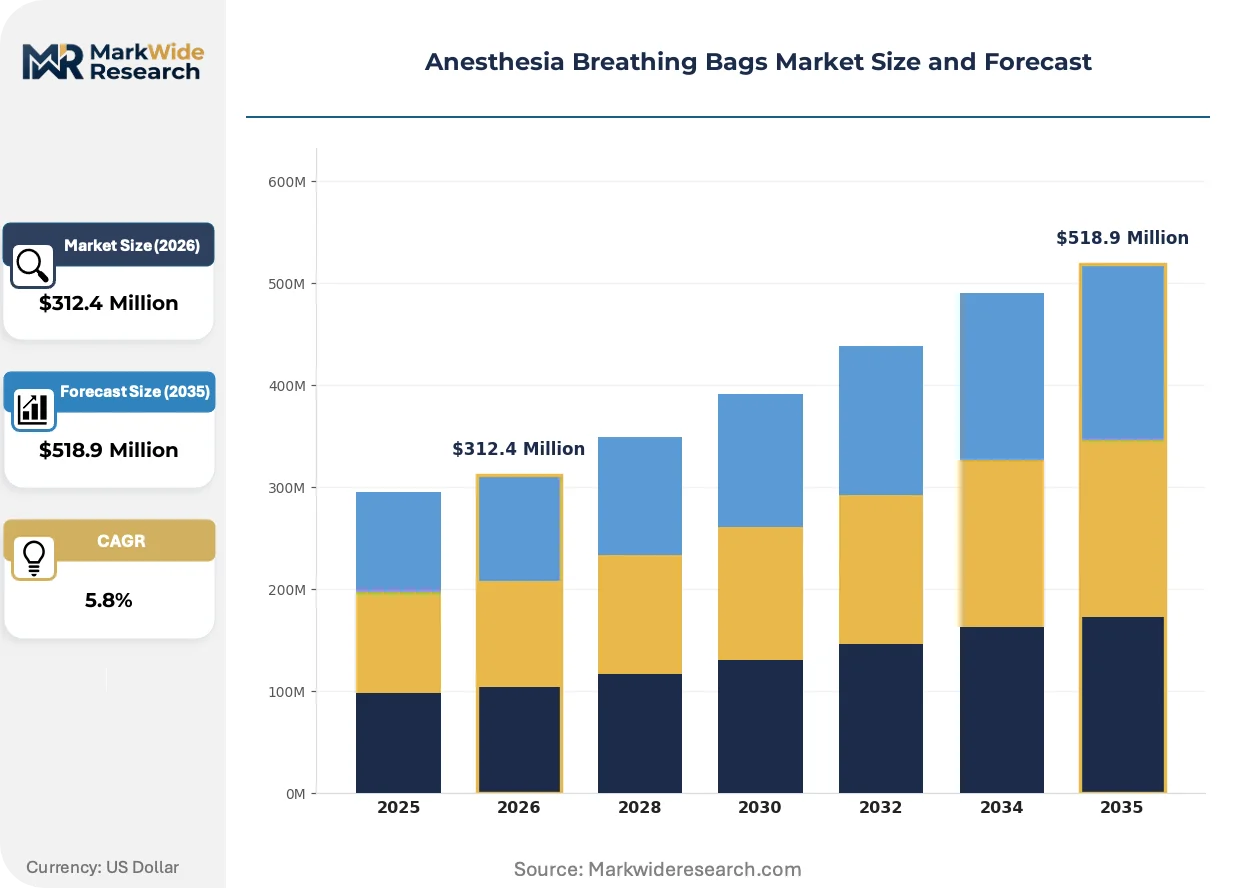
Market Dynamics
Hospital consolidation across the United States is compressing vendor rosters and forcing anesthesia breathing bag suppliers into exclusive supply agreements with integrated delivery networks. This concentration is accelerating standardization protocols and displacing smaller regional manufacturers from institutional procurement pipelines.
Growth Catalysts
- Outpatient surgery expansion:Ambulatory surgical centers in the United States are scaling procedure volumes, driving disposable breathing bag procurement as same-day discharge protocols eliminate reprocessing windows.
- FDA reprocessing guidance:Updated FDA guidelines for reusable medical devices are elevating compliance costs for sterilization validation, tilting facility economics toward single-use alternatives.
- Latex-free material transition:Polyvinyl chloride and silicone formulations are capturing preference in pediatric and allergy-sensitive patient populations, opening specialized product lines.
Market Restraints
- Medical-grade silicone price volatility:Raw material costs for silicone variants fluctuate with petrochemical feedstock markets, compressing margins on premium reusable programs.
- EU MDR clinical evidence requirements:Stricter European Union Medical Device Regulation mandates for reusable systems are extending time-to-market and raising regulatory spend for manufacturers targeting European hospitals.
- Sterilization infrastructure concentration:Centralized sterilization services in consolidated health systems create single-point-of-failure risk for reusable bag programs.
Strategic Opportunities
- CSRD procurement scoring:The EU Corporate Sustainability Reporting Directive is embedding environmental metrics into hospital purchasing evaluations, creating scoring advantages for reusable system vendors.
- Pediatric precision segments:Underserved neonatal and infant configurations require dimensional tolerances that mass-market suppliers avoid, supporting premium positioning.
- Emergency medical services channels:Pre-hospital care expansion is opening direct-to-ambulance distribution models bypassing traditional hospital supply chains.
Industry Challenges
- ISO 5362 validation timelines:Biocompatibility and performance certification cycles are extending product development schedules, delaying revenue recognition for new material formulations.
- Legacy anesthesia workstation integration:Proprietary connector standards from incumbent ventilator manufacturers are fragmentating breathing bag compatibility and raising switching costs for facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anesthesia Breathing Bags Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Pediatric, Adult Material: Polyvinyl Chloride, Silicone, Rubber, Others Application: Surgical Procedures, Emergency Care, Anesthesia Delivery, Patient Transport End User: Hospitals, Clinics, Ambulatory Surgical Centers, Veterinary Facilities |
| Companies Covered | Teleflex, Smiths Medical, Medline Industries, Flexicare Medical, GE Healthcare, Ambu, 3M, BOMImed, Drägerwerk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anesthesia Breathing Bags Market Emerging Trajectories
Material science advances and regulatory transparency mandates are restructuring how anesthesia breathing bags are specified, purchased, and disposed across acute and ambulatory settings.
Single-use polyvinyl chloride configurations are overtaking reusable latex systems in hospital procurement evaluations. Ambulatory surgical centers are adopting these disposables at accelerated rates to eliminate reprocessing labor and documentation burdens. This shift is compressing the addressable market for sterilization service providers and redirecting capital toward automated packaging lines.
REACH substance restrictions and EU MDR post-market surveillance requirements are tightening material traceability obligations for European market entry. Manufacturers must now maintain batch-level documentation for phthalate content and biocompatibility testing. Reusable silicone programs face heightened scrutiny in Germany and France, where hospital sustainability officers are weighing extended device lifecycles against disposable waste reporting thresholds.
Integrated delivery networks are consolidating vendor contracts across anesthesia accessories, ventilators, and consumables. Purchasing committees in Texas and California health systems are unbundling historically separate product categories into single-source agreements. This concentration is visible most acutely in multi-hospital systems where standardization protocols override individual facility preferences for specialty configurations.
Anesthesia Breathing Bags Market Segmentation
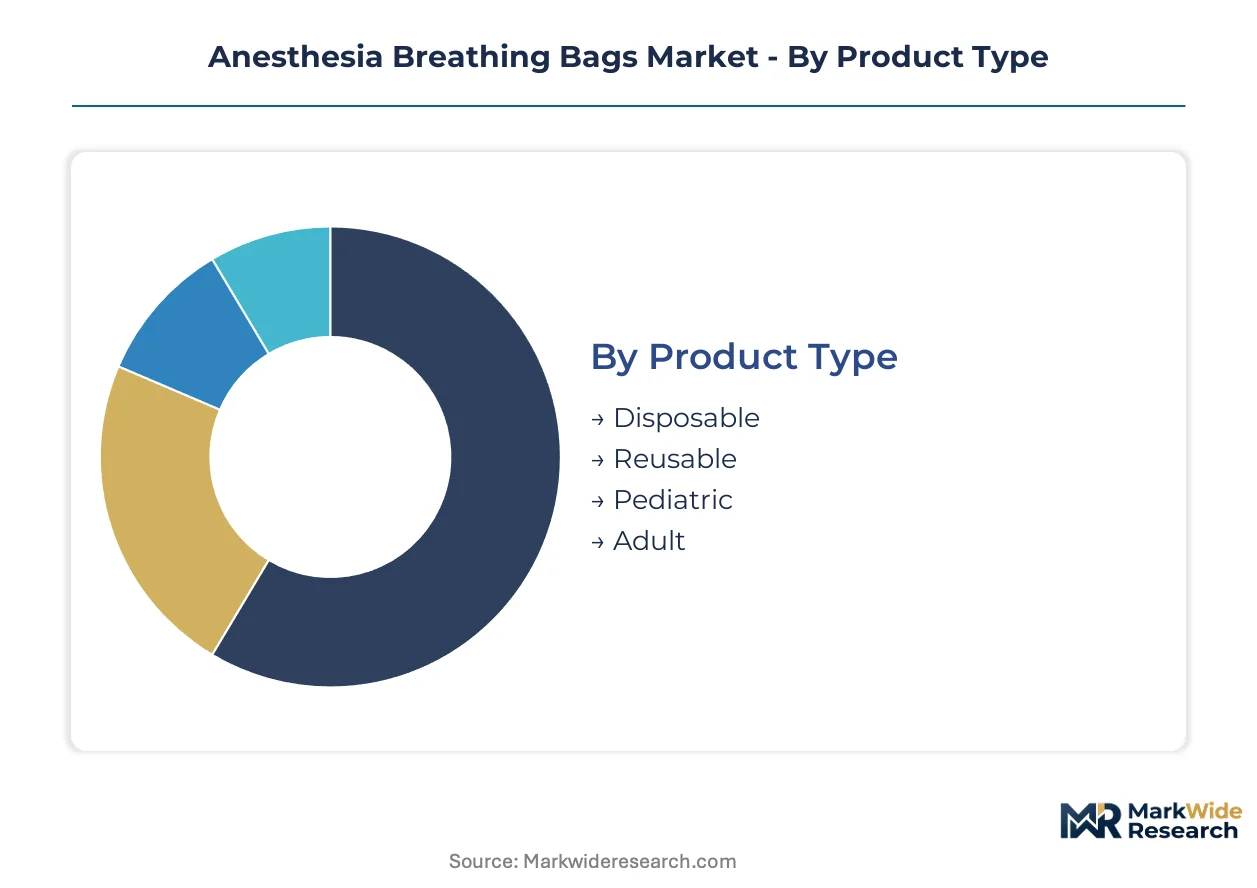
Segmentation in anesthesia breathing bags reveals how procurement committees balance infection control mandates against total cost-of-ownership calculations. Material selection and end-use channel determine pricing power more than bag size or configuration alone.
Product Type:
Capital intensity peaks in reusable programs requiring sterilization validation infrastructure and extended durability testing, while disposable lines demand automated packaging investment at scale.
- Disposable:Single-use polyvinyl chloride configurations eliminate reprocessing labor and documentation burdens. Ambulatory surgical centers in Texas and California health systems are consolidating procurement around these variants as same-day discharge protocols compress turnaround windows.
- Reusable:Medical-grade silicone systems withstand fifty-plus sterilization cycles but require centralized sterilization infrastructure and FDA validation documentation. Hospital consolidation is concentrating these programs within integrated delivery networks that can amortize equipment costs across multiple facilities.
- Pediatric:Neonatal and infant configurations demand dimensional tolerances that constrain batch sizes and elevate per-unit costs.
- Adult:Standard configurations dominate procurement volumes across hospital and ambulatory settings.
Most installed capacity flows through Disposable. Expansion is steepest in Pediatric.
Material:
Cost tier stratification separates premium silicone formulations from commodity polyvinyl chloride, with rubber occupying a narrowing middle ground constrained by latex sensitivity concerns.
- Polyvinyl Chloride:dominates volume production through automated extrusion and heat-sealing lines. REACH substance restrictions and phthalate content documentation are elevating batch-level traceability costs for European market entry.
- Silicone:commands premium positioning in reusable programs where sterilization cycles exceed fifty uses. Petrochemical feedstock volatility compresses margins unpredictably.
- Rubber:Latex formulations are retreating from pediatric and allergy-sensitive populations.
- Others:Experimental thermoplastic elastomers are entering niche applications.
Polyvinyl Chloride carries the heaviest throughput. Silicone is climbing the fastest.
Application:
Volume concentrates in scheduled surgical environments, though emergency care channels are opening direct-to-ambulance distribution models that bypass traditional hospital supply chains.
- Surgical Procedures:Operating room integration with anesthesia workstations drives bundled procurement decisions. Smiths Medical and Drägerwerk leverage ventilator relationships to lock in breathing bag specifications.
- Emergency Care:Pre-hospital deployment requires ruggedized packaging and rapid-deployment configurations. EMS expansion in the United States is creating procurement pathways separate from institutional purchasing committees.
- Anesthesia Delivery:Standard induction and maintenance protocols consume predictable volumes.
- Patient Transport:Mobile configurations prioritize compact packaging and connector compatibility.
Surgical Procedures absorbs the most units. Emergency Care is gaining share fastest.
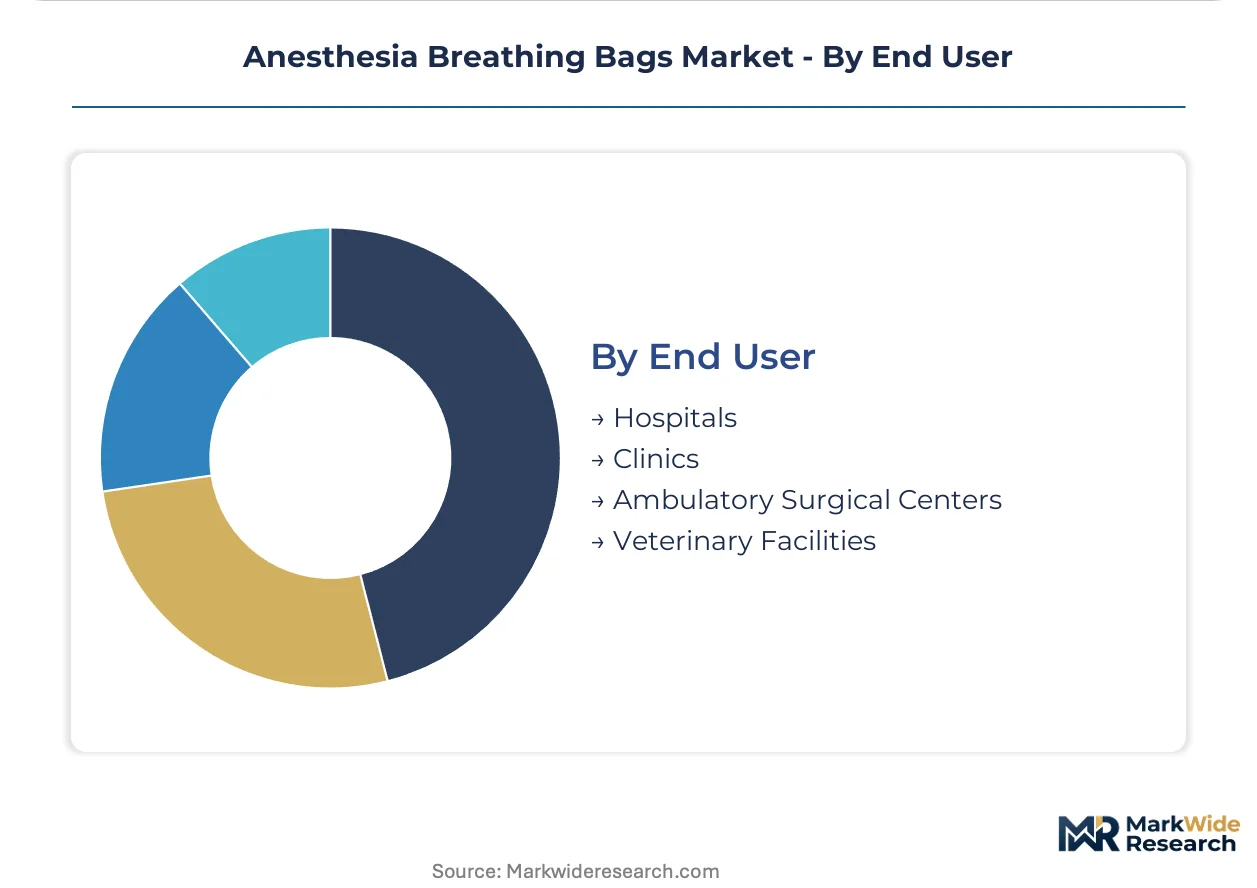
End User:
Customer type determines contract structure, with consolidated health systems extracting volume discounts while ambulatory surgical centers prioritize SKU reduction and just-in-time delivery.
- Hospitals:Integrated delivery networks in the United States are compressing vendor rosters into exclusive supply agreements. Standardization protocols override individual facility preferences for specialty configurations.
- Ambulatory Surgical Centers:Outpatient anesthesia volumes are scaling rapidly. These facilities favor disposable polyvinyl chloride variants to eliminate reprocessing windows entirely.
- Clinics:Lower procedure volumes drive spot purchasing rather than contracted supply.
- Veterinary Facilities:Specialized sizing and connector requirements fragment procurement into niche distributors.
Hospitals command the deepest contract penetration. Ambulatory Surgical Centers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as producers seek jurisdictions with streamlined medical device pathways. Cost-of-compliance gaps between the FDA's 510(k) process and the EU MDR's clinical evidence requirements are diverting capital toward North American production bases.
United States
Hospital consolidation across Texas and California health systems is compressing vendor rosters into exclusive supply agreements. The FDA's updated reprocessing guidelines for reusable medical devices are elevating compliance costs and tilting procurement toward single-use alternatives. Greater Boston and the Research Triangle anchor sterilization validation services for reusable silicone programs serving integrated delivery networks.
Germany
REACH substance restrictions and EU MDR post-market surveillance requirements are tightening material traceability obligations for breathing bag manufacturers. The EU Corporate Sustainability Reporting Directive is embedding environmental metrics into hospital purchasing evaluations, creating scoring advantages for reusable system vendors. Bavaria and Baden-Württemberg concentrate operating room infrastructure manufacturing where Drägerwerk anchors European supply relationships.
China
NMPA medical device registration pathways are streamlining for Class II respiratory accessories, attracting contract manufacturing investment from Western brands. Domestic hospital procurement centralization under volume-based purchasing is standardizing specifications across provincial health systems. The Yangtze River Delta clusters polyvinyl chloride extrusion capacity serving both domestic consumption and export markets.
India
CDSCO medical device rules are aligning with IMDRF guidelines, reducing regulatory friction for imported anesthesia accessories. The PLI scheme for medical devices is incentivizing domestic manufacturing of disposables to substitute imports in tier-2 and tier-3 hospitals. Maharashtra and Gujarat host contract sterilization services supporting reusable program economics for regional hospital chains.
Japan
PMDA quality management system inspections are extending lead times for foreign manufacturers seeking market entry, protecting domestic suppliers. METI's healthcare technology assessment frameworks are embedding total cost-of-ownership calculations into university hospital procurement. The Kansai region around Osaka maintains specialized silicone molding capacity for pediatric precision configurations.
Anesthesia Breathing Bags Market Vendor Landscape
Exclusive supply agreement concentration dominates the current landscape as integrated delivery networks compress vendor rosters. The vendor base stratifies across three tiers: diversified medical technology conglomerates with anesthesia workstation portfolios, disposable-focused specialists competing on latex-free formulations, and regional contract manufacturers serving price-sensitive procurement channels. Strategic archetypes include bundled equipment-consumable suppliers, single-use volume players, and precision pediatric specialists. M&A activity and capacity expansion in automated packaging lines represent the dominant competitive moves reshaping market structure.
Among diversified anesthesia technology suppliers, Smiths Medical and Drägerwerk exemplify the bundled portfolio archetype, leveraging integrated workstation relationships to lock in breathing bag specifications. Ambu occupies a distinct position within the disposable-focused tier, competing aggressively on latex-free formulations for outpatient settings. These three companies anchor the competitive landscape without exhausting its strategic diversity.
| Leading Market Players |
|---|
| Teleflex |
| Smiths Medical |
| Medline Industries |
| Flexicare Medical |
| GE Healthcare |
| Ambu |
| 3M |
| BOMImed |
| Drägerwerk |
| Others |
Supply Flow & Price Mechanics
Silicone molding specialists in the Kansai region anchor premium-tier production, with labor-cost differentials between Japanese precision manufacturers and Chinese extrusion operators creating spreads between reusable silicone systems and commodity polyvinyl chloride disposables. These workforce concentrations directly shape how procurement committees evaluate total cost-of-ownership across single-use and sterilizable programs.
Pricing Analysis
Distributor margin compression in ambulatory surgical center channels is narrowing price spreads between mid-tier and economy polyvinyl chloride configurations. Three-tier pricing structure across premium silicone, standard PVC, and economy latex alternatives separates segments by sterilization cycle tolerance and biocompatibility certification grade. Pricing pressure stems from hospital consolidation forcing volume discounts through exclusive supply agreements. Ambulatory surgical centers exhibit highest price sensitivity due to per-procedure margin constraints, while integrated delivery networks prioritize standardization over unit cost minimization.
Supply Chain Analysis
Returns and refurbishment flows for reusable silicone systems concentrate validation burden on centralized sterilization hubs in Germany and the United States. Raw material sourcing draws from Malaysian rubber plantations, Chinese petrochemical complexes for PVC resin, and Japanese silicone polymer production. Single-source vulnerability runs through German sterilization equipment manufacturers serving European reusable programs. Distribution runs through group purchasing organizations in consolidated US health systems and direct-to-facility contracts for ambulatory surgical center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between FDA 510(k) streamlined pathways and EU MDR clinical evidence requirements creates geographic cost differentials favoring North American production investment over European facility expansion.
For Market Incumbents: Anticipate procurement committee standardization mandates by securing exclusive supply agreements with Texas and California integrated delivery networks before competitor bundling strategies lock out secondary vendors. Backward integration into medical-grade silicone compounding mitigates petrochemical feedstock volatility threatening reusable program margins. Priority certification investment targets FDA reprocessing validation documentation to defend against single-use displacement.
For New Entrants and Emerging Players: Latex-free thermoplastic elastomer formulations offer technology-first wedge positioning in pediatric precision segments where dimensional tolerance requirements deter mass-market suppliers. Emergency medical services direct-to-ambulance distribution bypasses hospital purchasing committee gatekeeping. Underserved neonatal configurations in India and Southeast Asia present most penetrable geography-application intersection.
For Investors and Strategic Acquirers: Diversified anesthesia workstation manufacturers are the most active acquirer in this space, seeking consumable attach-rate expansion through breathing bag portfolio additions. Five-to-ten year viability hinges on reusable program economics surviving EU Corporate Sustainability Reporting Directive procurement scoring advantages. Watch FDA guidance updates on reprocessing validation timelines as inflection signal for single-use versus sterilizable demand shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements extend time-to-market for reusable silicone systems entering German hospital procurement. |
| Hospital System Partnership | Exclusive supply agreements with Texas integrated delivery networks compress competitor access to institutional purchasing pipelines. |
| Backward Integration | In-house PVC compounding insulates margin from petrochemical feedstock volatility affecting Chinese resin suppliers. |
| Pediatric Precision Launch | Neonatal dimensional tolerances command premium positioning in underserved segments avoided by volume manufacturers. |
| Sustainability Certification | EU CSRD procurement scoring advantages favor reusable system vendors in French and German hospital evaluations. |
Methodological Framework
Bottom-up ambulatory surgical center and hospital procurement modeling reconciled against top-down medical device manufacturer shipment tracking forms the analytical core of this study. Primary interviews with anesthesia department heads, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR registration databases, hospital procurement contract disclosures, and medical device trade flow records. Cross-referencing manufacturer-reported disposable versus reusable mix against facility sterilization capacity surveys enables demand-side triangulation.
Historical trendline analysis of procedure volume growth across surgical and emergency care channels anchors projection modeling. Segmentation dimensions span material type, product configuration, end-use channel, and geographic regulatory cluster. CAGRs derive from curve-fitting installed base replacement cycles against outpatient surgery expansion trajectories. Forecast inputs incorporate REACH substance restriction implementation timelines and FDA reprocessing guidance revision probabilities.
The model holds under stable regulatory pathway conditions; deviation in EU MDR enforcement stringency or FDA reprocessing guideline updates would shift reusable-single-use demand balance. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Anesthesiology
Global Anesthesia Endotracheal Tubes Market
Anesthesiology
Delirium Market
Anesthesiology
Anesthetics Market
Anesthesiology
Epinephrine Market
Anesthesiology
Anesthesia CO2 Absorbent Market
Anesthesiology
Aspirating System Market
Anesthesiology
Vasopressin for Vasoplegic Shock Market
Anesthesiology
Anesthesia Delivery Units Market
Anesthesiology
Anaesthesia Machines Market
Anesthesiology
Global Inhalation Anesthesia Market
Anesthesiology
Artificial Airway Holders Market
Anesthesiology
Global Anesthesia Delivery Systems Market
Anesthesiology
Airway Catheters Market
Anesthesiology
US Anesthesiology Service Market
Anesthesiology
Global Anesthesia and Respiratory Devices Market
Anesthesiology
Artificial Coma/Medically Induced Coma Market