
 Human Papillomavirus (HPV) Vaccine Market | 2026-2036
Human Papillomavirus (HPV) Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Human Papillomavirus (HPV) Vaccine Market Intelligence
The World Health Organization's Prequalification of Vaccines program is rotating market access dynamics toward manufacturers capable of meeting its stringent efficacy and safety criteria. Merck & Co., Inc. leverages its established Gardasil franchise to maintain a dominant position in developed markets. Meanwhile, Serum Institute of India Pvt Ltd competes on volume and cost-effectiveness for public health tenders. Walvax Biotechnology Co., Ltd. focuses on domestic demand within China.
Human Papillomavirus (HPV) vaccines are recombinant immunizations utilizing virus-like particles (VLPs) derived from the L1 major capsid protein. Their primary purpose is prophylactic immunization to prevent infections from specific HPV types linked to cervical, anal, and oropharyngeal cancers. The nonavalent product type is displacing older quadrivalent and bivalent versions due to its broader serotype coverage. Public health programs, particularly in middle-income countries, constitute the largest volume end-user segment.
Regulatory approvals from agencies like the US FDA, the European Medicines Agency (EMA), and China's NMPA dictate market entry and product labeling. These bodies' decisions on expanded age indications and alternative dosing schedules directly shape commercial strategies. Vaccine developers must now balance investment in therapeutic vaccine R&D against the immediate need to scale manufacturing for global prophylactic immunization goals.
Market Dynamics
The expansion of national immunization schedules into large, middle-income countries is the central force shaping the HPV vaccine market. This shift creates enormous, concentrated volume demand through public tenders, compelling a strategic focus on manufacturing scale and cost-efficiency.
Growth Catalysts
- Global Health Mandates:The World Health Organization's global strategy to eliminate cervical cancer provides a powerful framework, encouraging member states to adopt and fund HPV vaccination programs and setting clear targets for immunization coverage.
- Dosing Schedule Simplification:Research supporting the efficacy of single-dose regimens, accepted by bodies like the WHO's SAGE, lowers program costs and logistical complexity, making large-scale campaigns more feasible for public health end-users.
- Adolescent Health Programs:The integration of HPV vaccination into routine adolescent health platforms in populous countries, including India and Indonesia, substantially increases the addressable population and secures long-term volume demand.
Market Restraints
- Manufacturing Complexity:The production of virus-like particles (VLPs) is a complex, capital-intensive bioprocess with long lead times and few qualified manufacturing sites, creating potential supply bottlenecks and high unit costs.
- Vaccine Hesitancy:Persistent misinformation and cultural resistance in various global regions impede uptake, even in markets with available funding and supply, limiting the effectiveness of public health initiatives.
- Cold Chain Requirements:Strict temperature-control logistics from factory to patient are essential for vaccine efficacy. This presents a significant structural barrier in regions with underdeveloped infrastructure, increasing distribution costs and risk of wastage.
Strategic Opportunities
- Therapeutic Vaccine Development:A significant opportunity exists in research and development for therapeutic vaccines designed to treat existing HPV infections and pre-cancerous lesions, a distinct market from current prophylactic products.
- Male Population Immunization:Expanding vaccination programs to include adolescent boys to prevent HPV-related cancers, such as oropharyngeal and anal cancers, represents a major underpenetrated segment in many developed and developing countries. *Next-Generation Product R&D: Development of vaccines with coverage beyond the nine serotypes in current products, or those utilizing alternative platforms like mRNA, offers a path to clinical differentiation and market entry.
Industry Challenges
- Production Scaling:Meeting the WHO's ambitious global immunization targets requires an unprecedented ramp-up of VLP manufacturing capacity, a process that involves substantial capital expenditure and long construction and validation timelines.
- Equitable Global Allocation:Balancing supply between high-paying private markets in developed nations and large-volume, lower-price public tenders in developing countries creates a persistent operational challenge for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Papillomavirus (HPV) Vaccine Market |
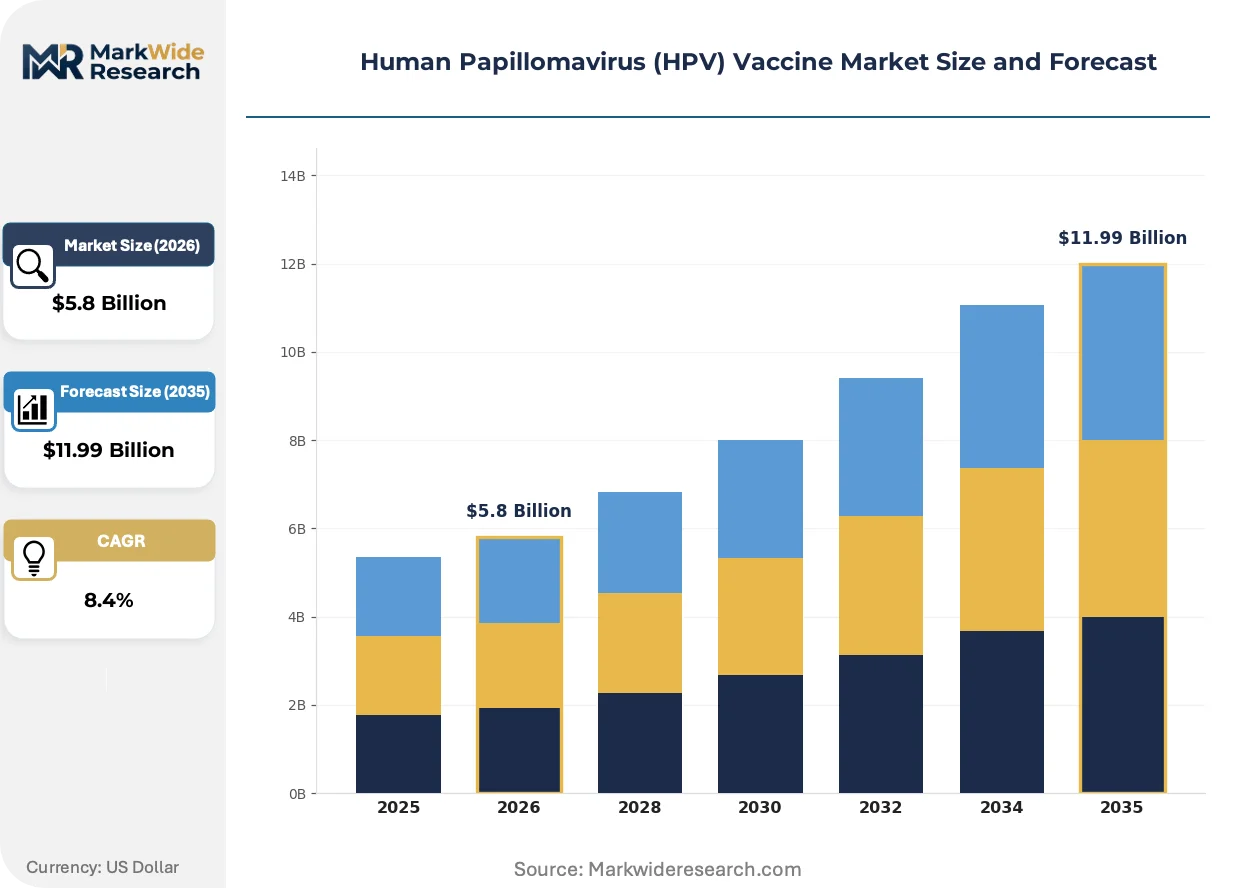
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bivalent, Quadrivalent, Nonavalent, Monovalent Application: Prophylactic Immunization, Therapeutic Vaccination, Adjuvant Therapy, Cancer Prevention End User: Pediatric Immunization Centers, Gynecologic Clinics, Public Health Programs, Family Planning Clinics Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Government Health Agencies |
| Companies Covered | Merck & Co., Inc., GlaxoSmithKline plc, Shanghai Zerun Biotech Co., Ltd., Walvax Biotechnology Co., Ltd., Xiamen Innovax Biotech, Wantai BioPharm, Serum Institute of India Pvt Ltd, Bharat Biotech, Sinovac Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Papillomavirus (HPV) Vaccine Market Strategic Shifts & Innovations
Innovation is oriented around expanding global access and affordability. The market's evolution is defined by the tension between advanced, broader-spectrum products and the logistical and economic realities of implementing mass immunization campaigns in diverse settings.
The nonavalent vaccine, which protects against nine distinct HPV serotypes, is the current technological standard. Public health programs and national immunization advisory committees are steadily adopting this product type. Consequently, the nonavalent version is displacing older bivalent and quadrivalent vaccines in government tenders and private markets due to its superior breadth of protection against cancer-causing HPV types.
Regulatory frameworks are adapting to accelerate access in underserved regions. The World Health Organization's Prequalification (PQ) program serves as a critical pathway for vaccines to be procured by UN agencies and Gavi. This process enables manufacturers from countries like India and China to access the global public health market, provided they meet stringent international standards for quality, safety, and efficacy.
Demand is concentrating within large-scale public health tenders rather than individual patient prescriptions. This shift alters purchasing criteria, prioritizing cost-effectiveness analysis, long-term supply reliability, and cold-chain suitability over individual physician or patient brand preference. This procurement pattern is most prominent in middle-income countries across Latin America and Southeast Asia, where national health systems are the primary buyers.
Human Papillomavirus (HPV) Vaccine Market Segmentation
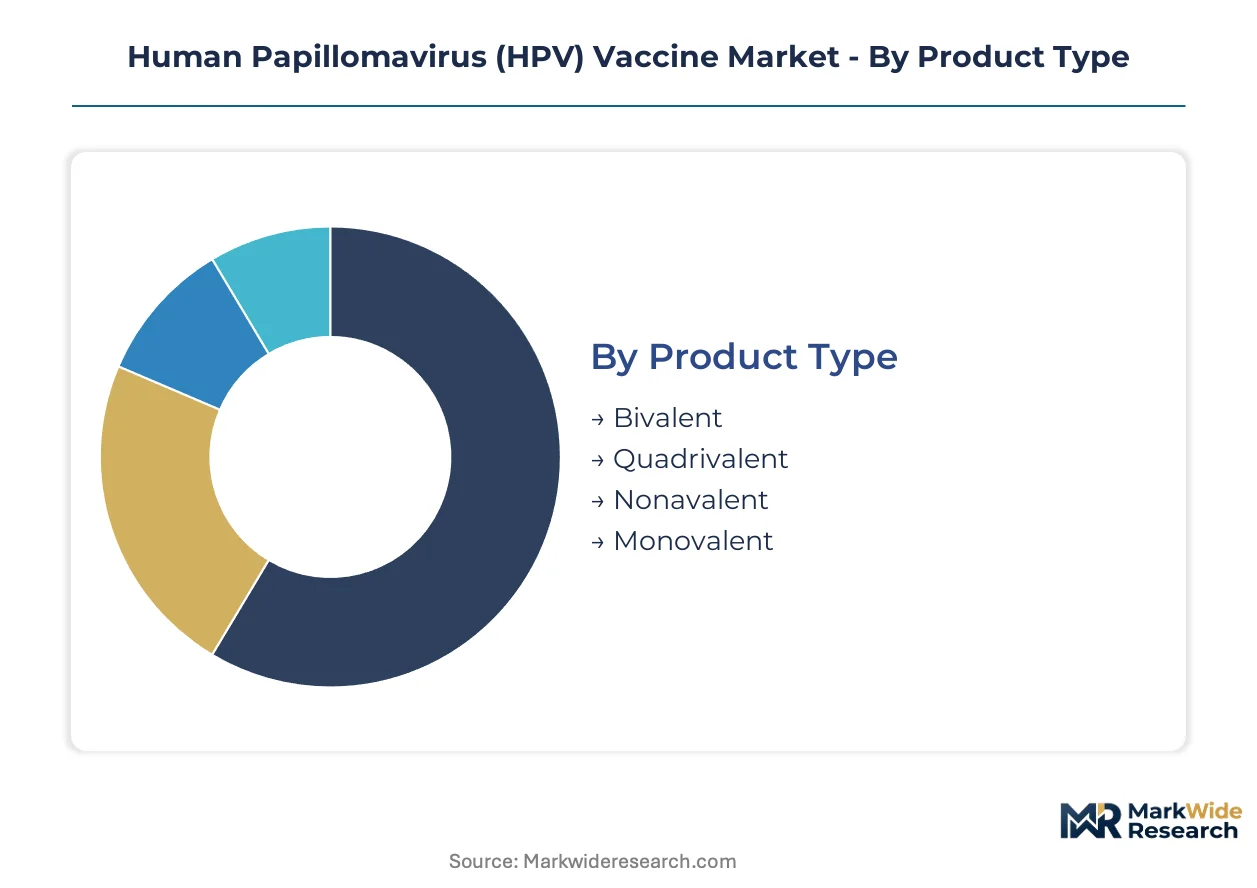
The Human Papillomavirus (HPV) vaccine market segments reflect the diverse product formulations, varied applications, and complex distribution networks essential for global immunization efforts. Understanding these segments is crucial for manufacturers to align product development with public health priorities and market access strategies.
Product Type:
The HPV vaccine market observes significant substitution pressure among product types as newer formulations offer expanded protection against a broader range of serotypes.
- Nonavalent:These vaccines protect against nine distinct HPV serotypes, including the seven high-risk types responsible for most cervical cancers and two low-risk types causing genital warts. Demand concentrates in developed markets and increasingly in public health programs in middle-income countries due to its superior breadth of protection.
- Quadrivalent:Quadrivalent vaccines target four HPV types, specifically HPV 6, 11, 16, and 18, offering protection against certain cancers and genital warts. Public health tenders in various middle-income countries still procure these versions due to established supply chains and cost-effectiveness.
- Bivalent:Bivalent vaccines protect against two high-risk HPV types, 16 and 18, which are major causes of cervical cancer.
- Monovalent:Monovalent vaccines target a single HPV type, making them less comprehensive than newer formulations.
Quadrivalent products anchor the current volume base while nonavalent versions gain share at the steepest rate.
Application:
Application segments are differentiated by their strategic cost implications and potential for long-term clinical impact within global health initiatives.
- Prophylactic Immunization:This application focuses on preventing initial HPV infections by administering vaccines before exposure to the virus, primarily targeting adolescents. Demand is concentrated in national immunization schedules across populous countries like India and Indonesia, driven by global cervical cancer elimination goals.
- Therapeutic Vaccination:Therapeutic vaccines aim to treat existing HPV infections or pre-cancerous lesions by stimulating an immune response in infected individuals. Significant R&D investment is channeled into this distinct market segment, offering a new treatment paradigm beyond prophylactic prevention.
- Adjuvant Therapy:Adjuvant therapy involves using substances to enhance the immune response to a vaccine, improving its efficacy.
- Cancer Prevention:This broad application encompasses all efforts to reduce the incidence of HPV-related cancers through vaccination and screening.
Prophylactic immunization remains the market's core function, yet therapeutic vaccination offers a distinct avenue for future clinical expansion.
End User:
End-user segments are defined by their distinct procurement patterns and target population volume, influencing vaccine distribution and accessibility.
- Public Health Programs:These programs involve large-scale, government-funded initiatives to vaccinate target populations, primarily adolescents, through national immunization schedules. Demand concentrates in middle-income countries, where bulk tenders prioritize cost-effectiveness and reliable supply for mass vaccination campaigns.
- Pediatric Immunization Centers:These centers provide routine vaccinations for children and adolescents, integrating HPV vaccination into broader pediatric health platforms. Their role is critical in ensuring high coverage rates for the recommended age groups within established healthcare systems.
- Gynecologic Clinics:Gynecologic clinics provide HPV vaccination services, particularly for young adult women and those seeking gynecological care.
- Family Planning Clinics:Family planning clinics offer HPV vaccination as part of comprehensive reproductive health services for eligible individuals.
Public health programs drive the largest volume demand, with pediatric immunization centers serving as critical points of care for adolescent vaccination.
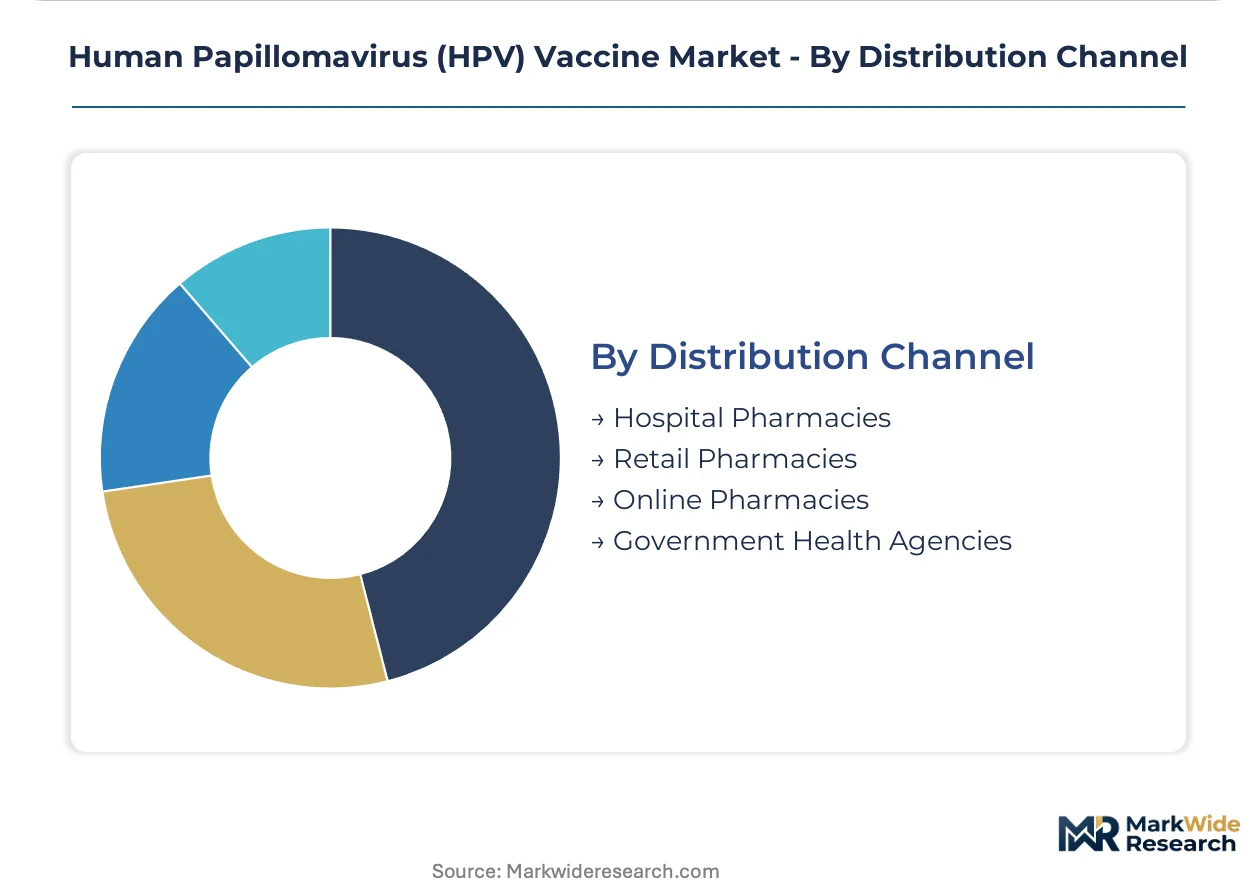
Distribution Channel:
Supply concentration within distribution channels directly influences vaccine accessibility and logistical efficiency for widespread immunization.
- Government Health Agencies:These agencies serve as primary procurement bodies for national immunization programs, managing large-volume tenders and ensuring equitable vaccine distribution across public health systems. Their purchasing decisions prioritize stringent quality standards and logistical feasibility for widespread deployment.
- Hospital Pharmacies:Hospital pharmacies are crucial access points for HPV vaccines, dispensing them for in-patient and out-patient administration within clinical settings. They maintain cold chain requirements and manage inventory for direct patient care, particularly for non-public program vaccinations.
- Retail Pharmacies:Retail pharmacies provide accessible points for individuals to obtain HPV vaccines, often requiring a prescription for administration.
- Online Pharmacies:Online pharmacies offer a convenient purchasing option for HPV vaccines, though administration typically requires a healthcare professional.
Government health agencies facilitate mass immunization campaigns, while hospital pharmacies ensure direct patient access within clinical settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Policy initiatives from the World Health Organization strongly influence HPV vaccine distribution across diverse regions. National immunization programs in populous middle-income countries drive substantial demand for prophylactic products. Regulatory bodies like the US FDA and EMA shape market access and product adoption in developed economies.
India
National immunization schedule expansion and adolescent health programs drive significant volume demand. India's CDSCO regulates vaccine approvals, enabling local production and procurement for mass campaigns. Serum Institute of India in Pune scales manufacturing for global public health tenders.
China
The NMPA's stringent regulatory framework supports domestic vaccine development and market entry for local players. A large domestic population and government-backed immunization initiatives create substantial internal demand. Walvax Biotechnology in Kunming focuses on meeting this significant national demand.
United States
Established public health recommendations and private market access sustain consistent demand for HPV vaccines. The US FDA approves expanded age indications and alternative dosing schedules, shaping commercial strategies. Merck & Co., Inc. in New Jersey maintains a dominant position with its Gardasil franchise.
Germany
European Medicines Agency (EMA) decisions influence vaccine uptake and market access across the continent. Robust public health infrastructure and high healthcare spending facilitate widespread vaccination programs. Berlin serves as a hub for pharmaceutical R&D, supporting vaccine innovation.
Brazil
Expanding national immunization schedules significantly increase the addressable population, particularly adolescents. ANVISA oversees vaccine registration and quality control for public procurement, ensuring product safety. Fiocruz in Rio de Janeiro collaborates on vaccine production and distribution for the public health system.
Human Papillomavirus (HPV) Vaccine Market Key Industry Players
Player mix skews toward established pharmaceutical giants and specialized vaccine manufacturers with robust R&D capabilities. The market demonstrates a tiered structure, featuring a few global leaders and several regional or domestic players focused on specific geographies. Strategic archetypes include innovation-driven multinationals, volume-focused public health suppliers, and domestic market champions. Geographic expansion into middle-income countries and significant capacity expansion for VLP production are dominant competitive moves.
Within the innovation-driven multinational tier, Merck & Co., Inc. exemplifies leadership in developed markets with its established Gardasil franchise. Serum Institute of India Pvt Ltd represents the volume-focused public health supplier archetype, competing on cost-effectiveness for large tenders in developing nations. Walvax Biotechnology Co., Ltd., a China-based manufacturer, anchors the domestic market champion archetype, focusing on meeting national demand. These companies collectively illustrate the diverse strategies employed across different market segments. Their operational models reflect distinct approaches to product development, regulatory navigation, and distribution network optimization.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| Shanghai Zerun Biotech Co., Ltd. |
| Walvax Biotechnology Co., Ltd. |
| Xiamen Innovax Biotech |
| Wantai BioPharm |
| Serum Institute of India Pvt Ltd |
| Bharat Biotech |
| Sinovac Biotech |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements for public health programs lock in both supply access and price visibility for HPV vaccine manufacturers. This market operates with distinct pricing tiers influenced by product complexity and procurement scale.
Pricing Analysis
Certification level (WHO Prequalification, US FDA approval) creates the primary spread in HPV vaccine pricing. Public health tenders primarily utilize a contract-based long-term offtake model, prioritizing cost-effectiveness and supply reliability. Price differentiation stems from volume scale and serotype coverage, with nonavalent versions commanding higher prices in private markets. Pricing softness for quadrivalent products reflects competition from broader-spectrum alternatives. Public health programs in middle-income countries exhibit the highest price sensitivity.
Supply Chain Analysis
Inbound logistics costs, particularly cold chain requirements, present significant challenges for HPV vaccine distribution. Geographic supply concentrates in India, China, and the United States, reflecting major manufacturing hubs. Raw material dependencies include specialized virus-like particles (VLPs) and proprietary adjuvants. A structural risk involves cold chain integrity, which is essential for vaccine efficacy and presents a logistics chokepoint in regions with underdeveloped infrastructure. Distribution runs through government health agencies for mass immunization campaigns and hospital pharmacies for direct patient access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HPV vaccine market requires a substitution defense, as incumbents must navigate the threat of next-generation prophylactic products and the emergence of therapeutic vaccine alternatives.
For Market Incumbents: Shield core prophylactic market share by scaling VLP manufacturing capacity, especially for nonavalent products, to meet global public health demand. Invest in R&D for therapeutic vaccines to address existing HPV infections, diversifying product portfolios beyond prevention. Secure expanded age indications from regulatory bodies like the US FDA to broaden addressable populations and sustain long-term volume. Control distribution channels in key developing markets to ensure product accessibility.
For New Entrants and Emerging Players: WHO Prequalification offers a certification fast-track for market entry into global public health tenders. Target underpenetrated segments like male population immunization or therapeutic vaccination, which represent distinct clinical opportunities. Develop cost-effective nonavalent alternatives or novel vaccine platforms (e.g., mRNA) to compete on price and broader serotype coverage. Focus initial market entry on large, middle-income countries with expanding national immunization schedules, leveraging volume-based procurement.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized VLP manufacturing capabilities or R&D firms focused on therapeutic HPV vaccines. Long-term viability rests on global cervical cancer elimination goals and expanding indications across patient demographics. Acquisition targets should include regional manufacturers with established public health tender access or companies developing next-generation vaccine platforms. A signal to watch is successful Phase 3 trial readouts for novel therapeutic HPV vaccine candidates.
| Strategic Initiative | Industry Significance |
|---|---|
| Scale VLP Manufacturing Capacity | Meeting global immunization targets depends on expanded production for nonavalent vaccines. |
| Invest in Therapeutic Vaccine R&D | Developing treatments for existing infections creates a distinct market segment beyond prophylaxis. |
| Secure Expanded Age Indications | Broadening eligible populations through regulatory approvals increases addressable market size. |
| Pursue WHO Prequalification | Accessing global public health tenders is critical for volume and market penetration in developing nations. |
| Develop Novel Vaccine Platforms | Alternative technologies like mRNA offer paths to broader serotype coverage and clinical differentiation. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews with industry stakeholders and rigorous secondary validation. This involved conversations with vaccine R&D executives, public health program managers, regulatory affairs leads, and procurement specialists. Secondary data sources included WHO reports, US FDA filings, EMA submissions, and national immunization program guidelines, triangulated to ensure robust market sizing and trend identification.
The analytical framework projected market dynamics across the analysis window, modeling segmentation dimensions such as product type, application, end-user, distribution channel, and regional regulatory clusters. Compound Annual Growth Rates were derived from historical trends, projected immunization coverage targets, and anticipated new vaccine approvals. This top-down and bottom-up approach integrated both macro-level drivers and granular market specifics.
Underlying assumptions cover current global health mandates and regulatory pathways, with deviation risk concentrated in unforeseen vaccine hesitancy or manufacturing bottlenecks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Genitourinary Drugs Market
Pharmaceuticals
SGLT2 Inhibitors Market
Pharmaceuticals
Global Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Global Zika Vaccines Market
Pharmaceuticals
Liquid Filled Hard Capsules Market
Pharmaceuticals
Global Dementia Drugs Market
Pharmaceuticals
Spain Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Global Combination Vaccine Market
Pharmaceuticals
Nefopam Hydrochloride Injection Market
Pharmaceuticals
Vascular Endothelial Growth Factor (VEGF) Inhibitors Market
Pharmaceuticals
Pharma 4.0 Market
Pharmaceuticals
Gardasil (HPV Vaccine) Market
Pharmaceuticals
Mild Laxatives Market
Pharmaceuticals
Global Doxorubicin Market
Pharmaceuticals
Nimodipine Market
Pharmaceuticals
United States Insulin Drugs and Delivery Devices Market