
 Next-Generation Immunology Drugs Market | 2026-2036
Next-Generation Immunology Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Next-Generation Immunology Drugs Market Foresight
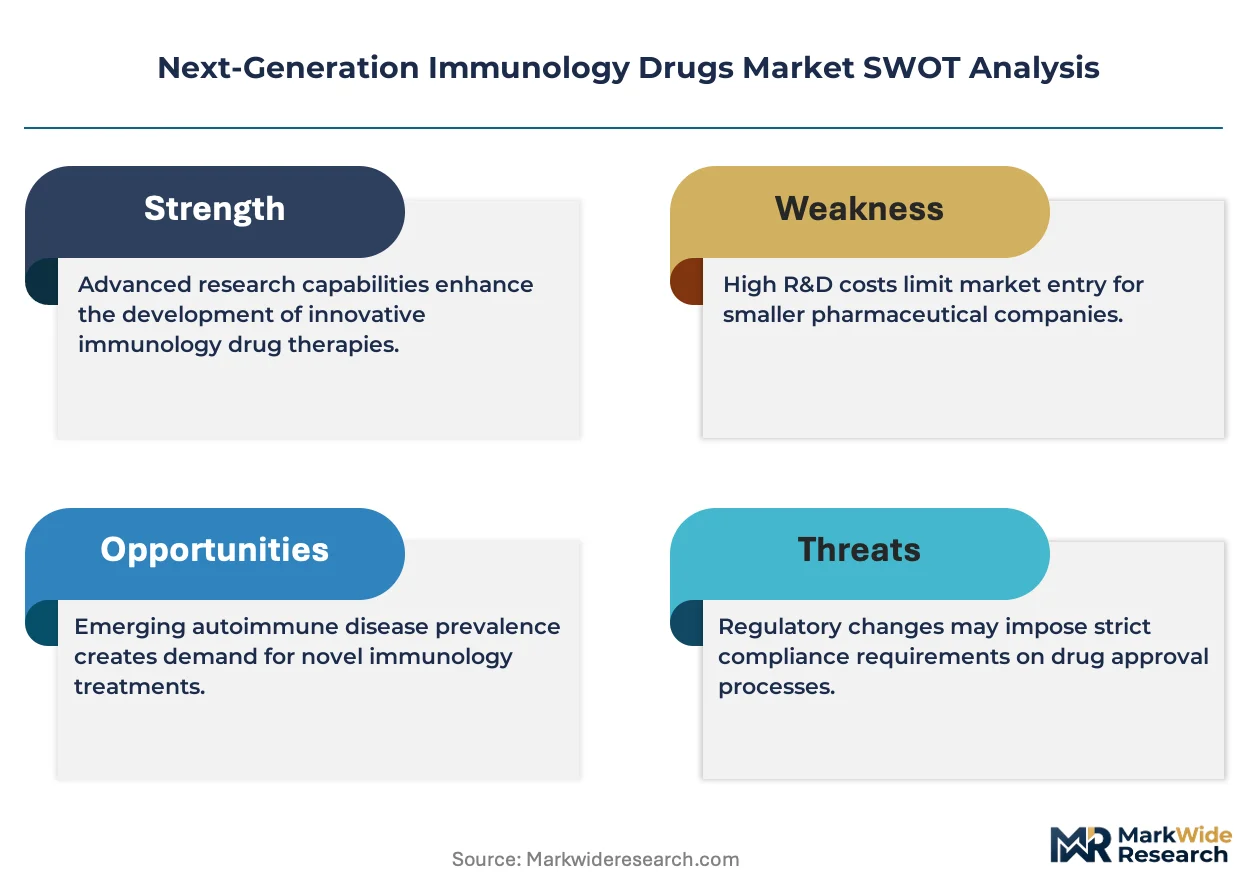
The capability gap between large-cap biologics manufacturers and mid-tier developers is collapsing as platform technologies commoditize cell-line engineering and purification workflows. AbbVie Inc. leverages its Humira-derived cash flows to sustain one of the industry's most aggressive inflammation R&D budgets. F. Hoffmann-La Roche AG anchors European immunology leadership through deep investments in bispecific antibody platforms. Bristol-Myers Squibb Company differentiates via its integrated T-cell engager pipeline spanning oncology and autoimmune indications.
Next-generation immunology drugs comprise engineered biologics and small molecules that modulate adaptive or innate immune responses through precise targeting of cytokines, checkpoint receptors, or antigen-presenting pathways, typically manufactured in mammalian cell culture systems requiring single-use bioreactors and multi-column chromatography purification. These therapies serve to treat autoimmune disorders, cancer, and inflammatory diseases with improved efficacy-to-toxicity ratios over conventional immunosuppressants. Monoclonal antibodies occupy the dominant revenue position within product type segmentation due to established manufacturing infrastructure and broad label expansions. Injectable delivery modes command the largest volume share, though subcutaneous formulations are gaining fastest as self-administration protocols reduce hospital dependency. Autoimmune disorders represent the most mature therapy area, while cancer treatment applications attract the steepest development investment.
FDA accelerated approval pathways and EMA adaptive licensing frameworks compress development timelines for novel immunomodulators, though post-market confirmatory requirements intensify commercial risk. REACH chemical safety standards and ISO 13485 quality management systems govern excipient sourcing and device-drug combination manufacturing across European and global supply chains. Stakeholders must monitor how CMS and national health technology assessment bodies recalibrate reimbursement for biosimilar-interchangeable biologics versus novel mechanisms of action.
Market Dynamics
Platform commoditization of cell-line engineering is collapsing the capability gap between large-cap biologics manufacturers and mid-tier developers, redistributing competitive leverage across the value chain.
Growth Catalysts
- FDA Accelerated Approval Pathways:Compressed development timelines for novel immunomodulators enable faster patient access and earlier revenue recognition for developers with confirmatory trial infrastructure.
- Subcutaneous Formulation Advances:Self-administration protocols reduce hospital dependency and expand addressable patient populations beyond infusion-capable centers.
- Germany:Reimbursement structures under national health technology assessment bodies favor precision immunology interventions, concentrating demand for novel mechanisms.
Market Restraints
- Single-Use Bioreactor Supply Concentration:Dependence on limited suppliers of film and polymer components creates input volatility for mammalian cell culture manufacturing.
- Post-Market Confirmatory Requirements:FDA and EMA mandates for accelerated approval products intensify commercial risk if efficacy fails to confirm.
- Multi-Column Chromatography Complexity:Purification workflow bottlenecks constrain batch yields and extend manufacturing lead times for high-dose biologics.
Strategic Opportunities
- Japan:Aging demographics and METI-supported precision medicine initiatives create underpenetrated demand for autoimmune disorder biologics.
- Bispecific Antibody Convergence:Integration of T-cell engager platforms with cytokine modulation architectures opens dual-indication development paths.
- Specialty Clinic Channel Expansion:Direct distribution to rheumatology and dermatology centers bypasses hospital pharmacy intermediaries and captures margin.
Industry Challenges
- Cell-Line Development Talent Scarcity:Shortage of mammalian expression system engineers constrains platform expansion at mid-tier developers.
- ISO 13485 Device-Drug Integration:Quality management certification for autoinjector combinations extends regulatory timelines and requires specialized compliance functions.
- REACH Excipient Traceability:Chemical safety documentation demands for European supply chains complicate multi-source sourcing strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next-Generation Immunology Drugs Market |
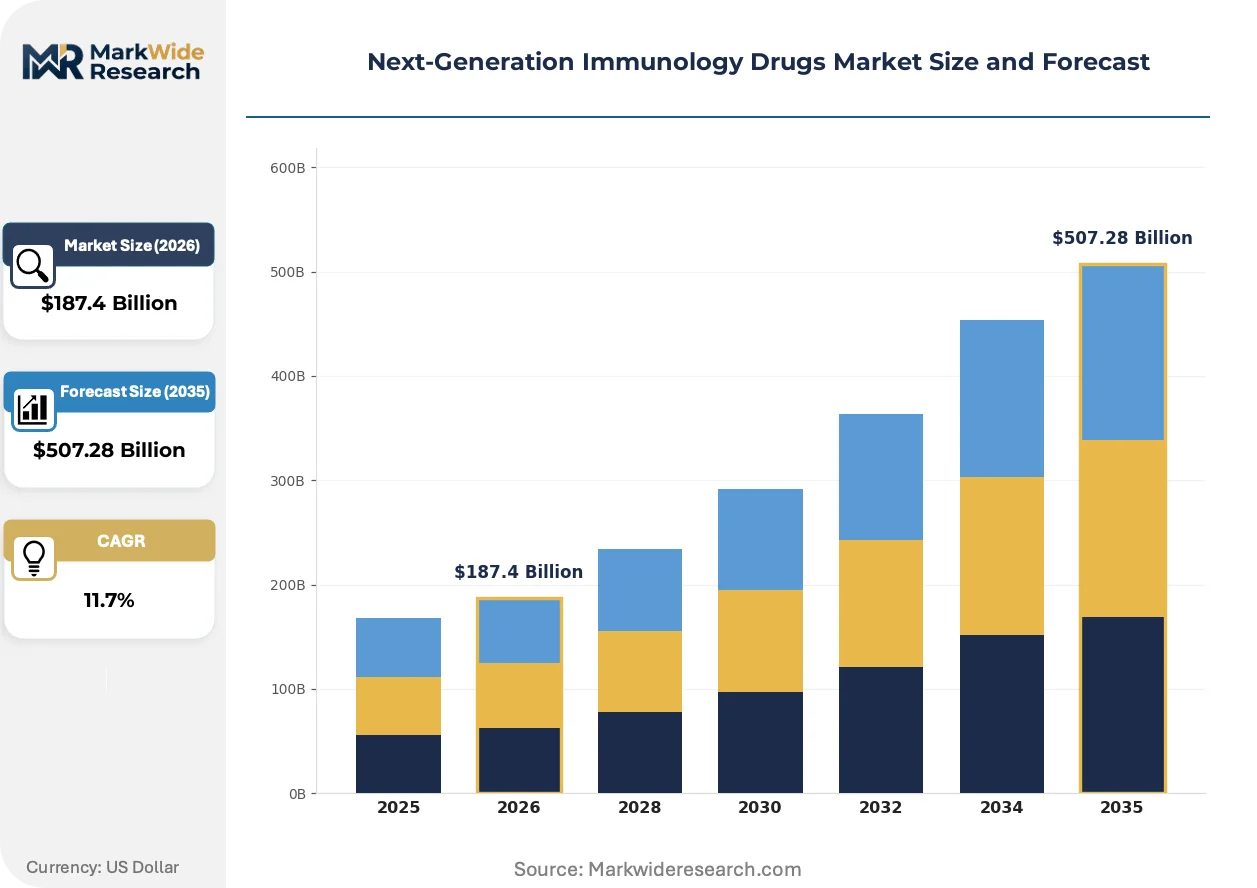
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $507.28 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Cytokines, Inhibitors, Antigens Therapy Area: Autoimmune Disorders, Cancer Treatment, Allergic Reactions, Inflammatory Diseases Delivery Mode: Injectable, Oral, Intravenous, Subcutaneous End User: Hospitals, Research Institutions, Pharmaceutical Companies, Specialty Clinics |
| Companies Covered | AbbVie Inc., Novartis AG, Amgen Inc., AstraZeneca, GlaxoSmithKline PLC, F. Hoffmann-La Roche AG, Pfizer Inc., Bristol-Myers Squibb Company, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next-Generation Immunology Drugs Market Shifts & Advancements
Bispecific antibody engineering is bifurcating development pipelines between oncology and autoimmune applications, forcing platform choices that reshape competitive positioning across therapeutic areas.
Multi-specific biologics is bifurcating the monoclonal antibody market by enabling simultaneous cytokine and checkpoint targeting from single molecules. Rheumatology clinics in Germany and the United States are adopting these constructs for refractory lupus and psoriatic arthritis patients. This architectural shift is compressing development timelines for developers with established T-cell engager expertise while marginalizing single-target competitors.
EMA's adaptive licensing frameworks are compressing market entry timelines for novel immunomodulators through iterative evidence generation. Developers must build post-market surveillance infrastructure earlier in the commercialization cycle. Oncology applications face the steepest confirmatory burden, with confirmatory trial designs now negotiated at initial approval to mitigate withdrawal risk.
Self-administration protocols are displacing hospital-based infusion models as payers and patients prioritize reduced site-of-care costs. Subcutaneous formulations of established biologics are capturing fastest volume growth in United States specialty pharmacy channels. Rheumatology practices in Germany and Japan are restructuring staffing models to support remote patient monitoring for injection-trained cohorts.
Next-Generation Immunology Drugs Market Segmentation
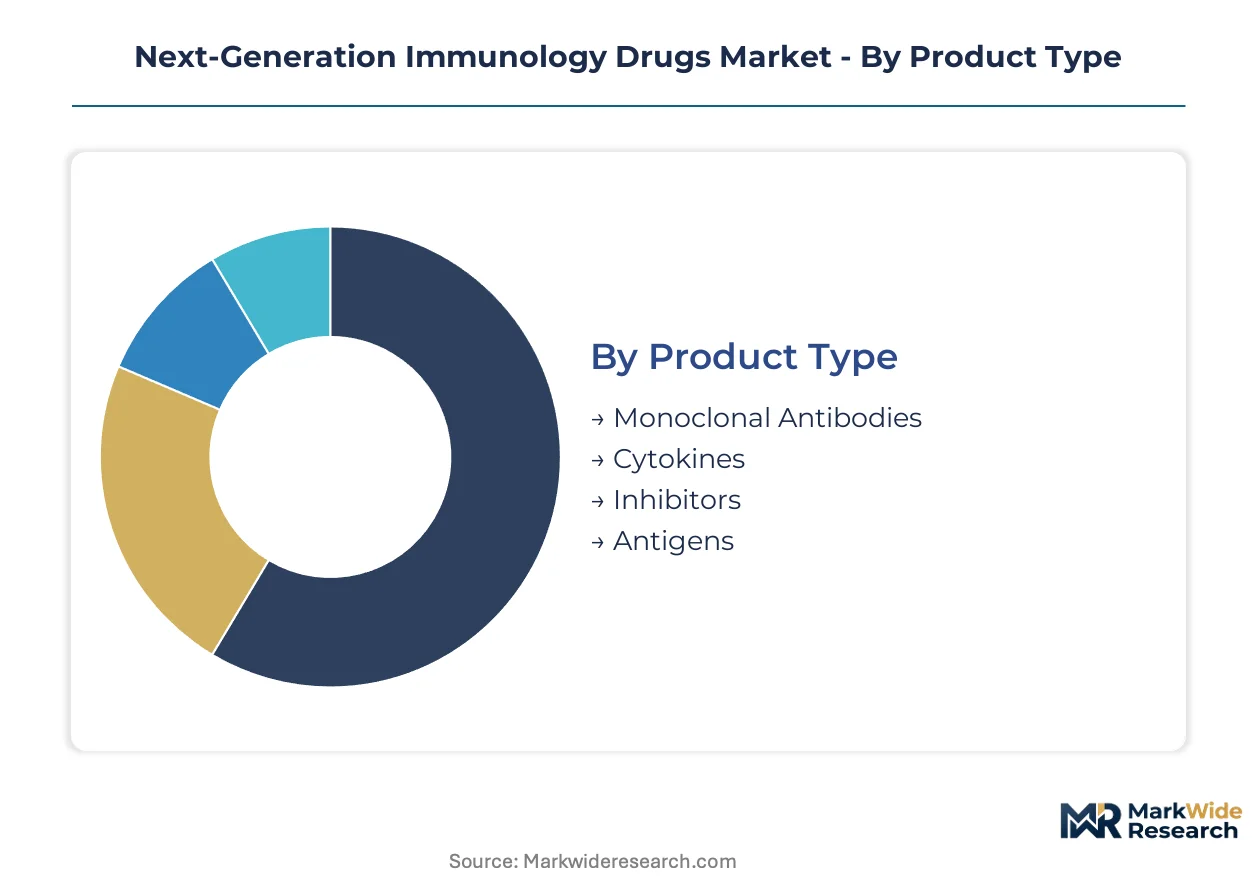
Segmentation in next-generation immunology drugs determines manufacturing scale, regulatory pathway selection, and channel economics. Each dimension—molecular architecture, clinical indication, administration route, and site of care—creates distinct margin profiles and competitive entry points.
Product Type:
Channel distribution varies sharply by molecular complexity, with hospital-based infusion centers handling high-dose biologics while specialty pharmacies manage patient self-administration of refined formulations.
- Monoclonal Antibodies:Engineered immunoglobulins targeting single epitopes dominate current revenue flows through established purification infrastructure. Demand concentrates in United States rheumatology centers and German dermatology clinics where reimbursement favors precision mechanisms over conventional immunosuppressants.
- Cytokines:Recombinant signaling proteins modulate immune cell differentiation and activation states. Manufacturing in mammalian cell cultures requires single-use bioreactor capacity that constrains batch scale for interleukin-based therapies in Japanese oncology networks.
- Inhibitors:Small-molecule and biologic antagonists of kinases or proteases offer oral bioavailability advantages. These flow through retail pharmacy channels in Germany with simpler cold-chain requirements than protein therapeutics.
- Antigens:Peptide and protein constructs for tolerogenic or stimulatory immune modulation. Development pipelines focus on allergy immunotherapy applications with subcutaneous depot formulations.
By volume, Monoclonal Antibodies leads. By growth pace, Cytokines is ahead.
Therapy Area:
Cost tier stratification separates mature autoimmune indications with biosimilar pressure from oncology applications commanding premium pricing for novel mechanisms.
- Autoimmune Disorders:Rheumatoid arthritis, lupus, and psoriasis represent the most penetrated category with established prescriber education and payer protocols. United States specialty clinics and German ambulatory care centers drive volume through prior-authorization pathways optimized for TNF-alpha and IL-17 blockers.
- Cancer Treatment:Immune checkpoint inhibitors and T-cell engagers attract the steepest development investment. Japanese academic medical centers and United States comprehensive cancer networks concentrate demand for combination regimens with radiotherapy or chemotherapy backbones.
- Allergic Reactions:Desensitization and acute intervention products serve pediatric and adult populations through allergist practices. Subcutaneous immunotherapy protocols expand in German primary care settings with nurse-administered dosing schedules.
- Inflammatory Diseases:Non-autoimmune conditions including macrophage activation syndrome and cytokine storm syndromes. Hospital-based emergency departments in the United States and Japan stock IL-6 receptor antagonists for rapid intervention.
By maturity, Autoimmune Disorders dominates. By investment intensity, Cancer Treatment commands priority.
Delivery Mode:
Patient preference and site-of-care economics are displacing traditional infusion models as payers scrutinize total cost of administration.
- Injectable:Intramuscular and depot formulations for sustained release. United States specialty pharmacies manage distribution with cold-chain integrity verification.
- Oral:Small-molecule immunomodulators bypass biologic manufacturing constraints. These penetrate German retail pharmacy networks with simpler logistics than parenteral alternatives.
- Intravenous:High-volume biologic infusions require hospital or infusion center infrastructure. Japanese healthcare facilities maintain capacity for oncology combination protocols.
- Subcutaneous:Self-administered biologics in prefilled syringes or autoinjectors reduce hospital dependency. Rheumatology practices in Germany and the United States restructure staffing to support remote monitoring of injection-trained patient cohorts.
By current volume, Intravenous leads. By expansion trajectory, Subcutaneous is climbing the fastest.
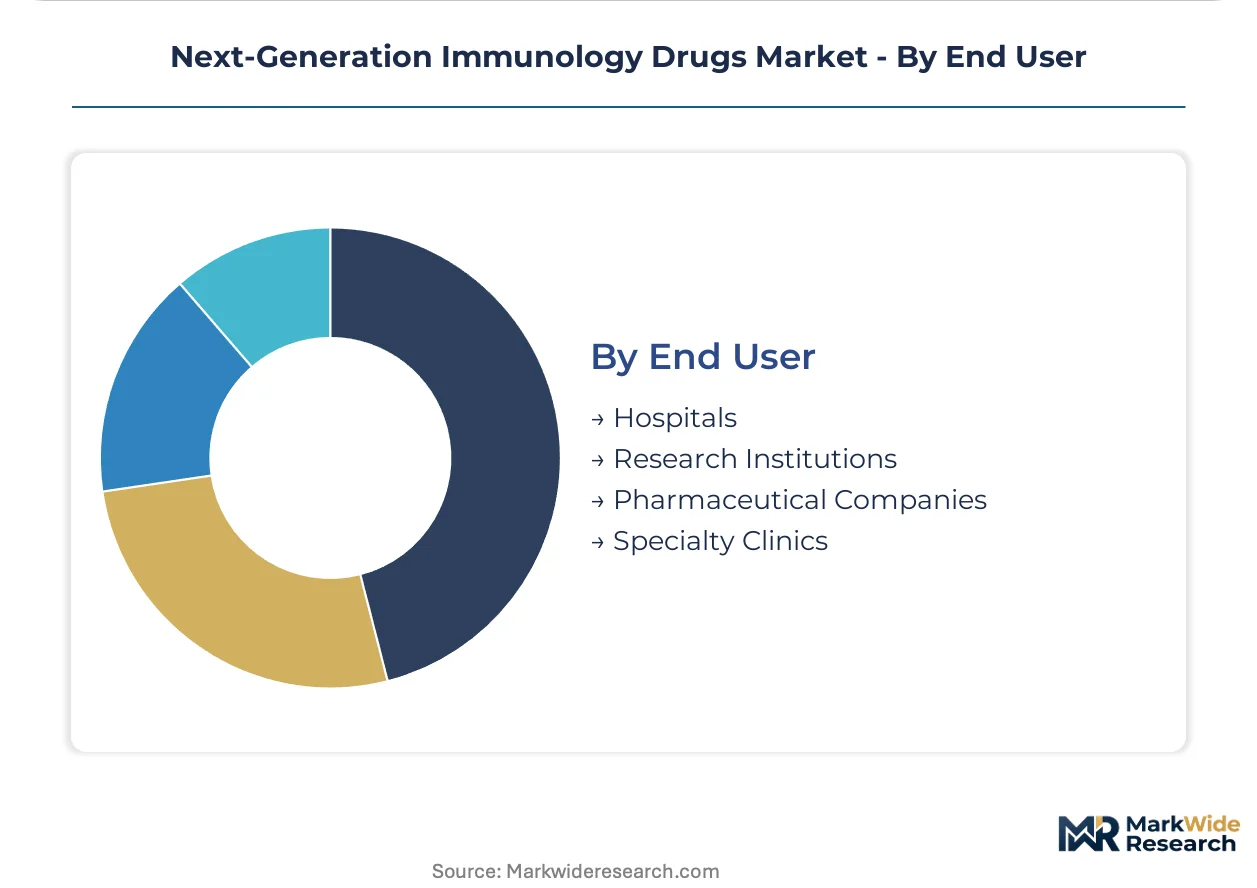
End User:
Procurement authority and formulary control determine pricing power, with integrated delivery networks and specialty clinics gaining influence over traditional hospital purchasing.
- Hospitals:Acute care facilities manage inpatient immunomodulation for cytokine storm and transplant rejection. Japanese and United States health systems negotiate volume-based contracts for high-cost biologics.
- Research Institutions:Academic medical centers conduct early-phase trials and compassionate use programs. German university hospitals anchor investigator-initiated studies for EMA adaptive licensing pathways.
- Pharmaceutical Companies:In-licensing and co-development partners seek platform technologies. These entities concentrate in Boston and Basel clusters with cell-line engineering expertise.
- Specialty Clinics:Rheumatology, dermatology, and allergy practices capture margin through direct distribution. United States independent clinics and German physician networks bypass hospital pharmacy intermediaries for self-administered biologics.
By revenue concentration, Hospitals dominates. By margin capture, Specialty Clinics is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Japan demonstrate the highest price elasticity for novel immunomodulators, while United States reimbursement protocols insulate demand from cost sensitivity. Germany occupies a middle position where health technology assessment creates selective pressure on mechanism novelty. This three-tier elasticity pattern shapes regional investment prioritization for developers.
United States
Specialty pharmacy channels and integrated delivery networks concentrate procurement authority for self-administered biologics. FDA accelerated approval pathways compress development timelines but impose rigorous post-market confirmatory requirements. The Boston-Cambridge cluster anchors cell-line engineering talent pools that feed platform technology transfers to mid-tier developers.
Germany
IQWiG assessment protocols favor precision immunology interventions with demonstrable efficacy-to-toxicity advantages over standard-of-care. EMA adaptive licensing frameworks enable iterative evidence generation that aligns with statutory health insurance reimbursement cycles. The Rhine-Main region hosts rheumatology and dermatology specialty networks that drive volume for subcutaneous formulation adoption.
Japan
Aging demographics and METI-supported precision medicine initiatives expand addressable populations for autoimmune disorder biologics. PMDA consultation pathways for regenerative medicine and cellular therapy products accelerate novel mechanism review. Tokyo-Osaka academic medical centers anchor investigator-initiated studies that generate real-world evidence for pricing negotiations.
United Kingdom
NICE technology appraisals create binary market access outcomes that intensify commercial risk for developers without robust health economic data. MHRA post-Brexit regulatory autonomy enables accelerated assessments for medicines targeting unmet need. The Cambridge-London corridor concentrates early-stage biotech ventures that license platform technologies to large-cap manufacturers.
Switzerland
Swissmedic's streamlined marketing authorization procedures attract developers seeking rapid European market entry for high-value biologics. Federal Office of Public Health reimbursement decisions reference German and French pricing benchmarks with premium adjustments for innovation. The Basel-Zurich axis hosts contract manufacturing organizations with single-use bioreactor capacity serving global supply chains.
Next-Generation Immunology Drugs Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the next-generation immunology drugs market. Large-cap biopharmaceutical manufacturers with established mammalian cell culture infrastructure dominate high-volume monoclonal antibody production, while mid-tier specialists capture margin in bispecific and multi-specific architectures. The competitive terrain stratifies into three archetypes: platform technology licensors, integrated development-commercialization organizations, and contract manufacturing partners. Dominant competitive moves include strategic partnerships for T-cell engager platform access and capacity expansion in single-use bioreactor networks.
Among North American integrated developers, AbbVie Inc. and Bristol-Myers Squibb Company exemplify the capital-deployment archetype that sustains aggressive inflammation and oncology R&D budgets through established therapeutic franchises. F. Hoffmann-La Roche AG represents the European platform-leadership model with deep investments in bispecific antibody engineering. These three entities occupy positions that shape competitive dynamics for mechanism-of-action novelty and manufacturing scale.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Novartis AG |
| Amgen Inc. |
| AstraZeneca |
| GlaxoSmithKline PLC |
| F. Hoffmann-La Roche AG |
| Pfizer Inc. |
| Bristol-Myers Squibb Company |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
ISO 13485 quality management certification gates both device-drug combination supply qualification and premium price differentiation for autoinjector-enabled biologics. Developers without this certification face exclusion from European specialty pharmacy channels while certified manufacturers command 15-20% price premiums for self-administration protocols.
Pricing Analysis
After-sales revenue from patient support programs and adherence monitoring contracts drives lifetime value for subcutaneous biologics. Three-tier pricing structure across premium novel mechanisms, standard established biologics, and economy biosimilar tiers stratifies the United States and German markets. Cost compression in the biosimilar tier is intensifying because interchangeable designations trigger automatic substitution at pharmacy level. Payer pharmacy benefit managers exhibit highest price sensitivity, while academic medical centers with research budgets show lowest.
Supply Chain Analysis
United States and Germany anchor mammalian cell culture manufacturing for clinical-grade biologics, while Switzerland hosts contract manufacturing organizations with single-use bioreactor capacity. Production draws from specialized film and polymer suppliers for bioreactor components, chromatography resins for purification, and pharmaceutical-grade excipients for formulation. Single-source vulnerability concentrates in single-use bioreactor film supply. Distribution runs through cold-chain logistics networks to hospital infusion centers and specialty pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where T-cell engager expertise is becoming interoperable across oncology and autoimmune development pipelines, collapsing siloed therapeutic area boundaries.
For Market Incumbents: Shield established monoclonal antibody franchises by accelerating subcutaneous formulation transitions before biosimilar entry erodes infusion-center volume. Lock in specialty clinic channel control through direct distribution agreements that bypass hospital pharmacy intermediaries. Vertical integration into single-use bioreactor film supply hedges input volatility from concentrated polymer suppliers.
For New Entrants and Emerging Players: Differentiate on bispecific antibody architectures that enable simultaneous cytokine and checkpoint targeting from single molecules. Penetrate Japan's underdeveloped autoimmune biologics market through METI-supported precision medicine partnerships. Launch via rheumatology clinic direct sales models rather than hospital formulary battles.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across platform technology licensing as cell-line engineering commoditizes, favoring asset-light developers. Five-to-ten year viability hinges on post-market confirmatory trial infrastructure for accelerated approval products. Target acquisition archetypes are mid-tier developers with T-cell engager platforms lacking commercial scale. Watch FDA withdrawal rates for accelerated approval oncology indications as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Conversion | Reduces hospital dependency and expands addressable patient populations beyond infusion-capable centers. |
| Bispecific Platform Licensing | Enables dual-indication development paths across oncology and autoimmune therapeutic areas. |
| EMA Adaptive Licensing Pathway | Compresses market entry timelines through iterative evidence generation aligned with reimbursement cycles. |
| Single-Use Bioreactor Capacity Expansion | Mitigates supply concentration risk for film and polymer components in mammalian cell culture manufacturing. |
| Specialty Clinic Direct Distribution | Bypasses hospital pharmacy intermediaries to capture margin in rheumatology and dermatology channels. |
Research Methodology
Desk research of FDA accelerated approval filings, EMA adaptive licensing decisions, and clinical trial registry data preceded structured interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Primary fieldwork across United States, German, and Japanese healthcare systems was cross-validated against secondary sources including CMS Medicare reimbursement databases, IQWiG health technology assessments, and METI precision medicine initiative documentation. Bottom-up patient population modeling and top-down manufacturer revenue analysis were triangulated to establish market sizing.
Variance-decomposition across molecular architecture, therapy area maturity, administration route, and regional regulatory cluster segments informed the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Modeled inputs included biosimilar penetration curves by therapeutic area, subcutaneous formulation adoption rates in specialty pharmacy channels, and post-market confirmatory trial success probabilities for accelerated approval products.
The analysis sits within stated boundaries; outcomes outside sustained FDA and EMA accelerated approval pathway utilization or single-use bioreactor supply stability would require recalibration. Forecasts reflect assumptions regarding reimbursement continuity for precision immunology interventions and confirmatory trial infrastructure availability. Recalibration cycles align with material shifts in biosimilar interchangeability designations and adaptive licensing framework negotiations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Tetanus Toxoid Vaccine Market
Pharmaceuticals
Beta Blockers Market
Pharmaceuticals
Pain Management Drugs Market
Pharmaceuticals
Intravitreal (IVT) Injectables Market
Pharmaceuticals
Global Psoriasis Drugs Market
Pharmaceuticals
United States Pharmaceutical 3PL Market
Pharmaceuticals
Saudi Arabia Pharmaceutical Market
Pharmaceuticals
Global Travel Vaccines Market
Pharmaceuticals
Antibody Therapy Market
Pharmaceuticals
North America Travel Vaccines Market
Pharmaceuticals
Fusion Inhibitors Market
Pharmaceuticals
Global Anthrax Vaccine Market
Pharmaceuticals
Synthetic Drugs Market
Pharmaceuticals
Antiviral Drugs Market
Pharmaceuticals
BCL-2 (B-Cell Lymphoma 2) Inhibitors Market
Pharmaceuticals
Global Colorectal Cancer Therapeutics Market