
 Cortisone Market | 2026-2036
Cortisone Market Size, Share, and Industry Trends Forecast 2026-2036
Cortisone Market Analysis
Dermatological treatment demand is expanding as atopic dermatitis and psoriasis protocols incorporate topical corticosteroids earlier in care pathways. Pfizer Inc. anchors North American hospital supply chains through its injectable corticosteroid portfolio. Novartis AG differentiates via ophthalmic cortisone formulations for post-surgical inflammation. Teva Pharmaceutical Industries Ltd. competes aggressively in oral generic prednisone across European retail pharmacies.
Cortisone denotes a class of glucocorticoid hormones synthesized from 17-hydroxyprogesterone through microbial biotransformation, typically administered at 25–300 mg dosages depending on indication severity to suppress immune response and reduce inflammation. Hydrocortisone dominates current volume flows due to its compatibility across oral, topical, and injectable delivery modes. Prednisone captures expanding share in autoimmune disorder protocols where longer half-life improves patient compliance. Injectable delivery commands the highest margin pool, constrained by cold-chain requirements and hospital accreditation standards.
The FDA oversees corticosteroid purity and labeling under New Drug Application pathways, while the EMA's Committee for Medicinal Products for Human Use evaluates cortisone-containing therapies for centralized EU market authorization. India's CDSCO mandates bioequivalence documentation for domestic corticosteroid manufacturers under its phased quality mandate. Stakeholders must monitor evolving pharmacovigilance requirements for long-term corticosteroid exposure as regulators link extended use to metabolic and ocular adverse events.
Market Dynamics
Hospital procurement consolidation and FDA purity mandates are compressing supplier margins while accelerating qualification barriers for compounded corticosteroid manufacturers. Injectable formulation demand is concentrating purchasing power among integrated health systems.
Growth Catalysts
- Outpatient autoimmune protocols:Rheumatology clinics in the United States are expanding supervised corticosteroid administration, pulling volume from inpatient settings into ambulatory surgical centers.
- REACH compliance alignment:European corticosteroid manufacturers achieving ECHA substance registration standards gain preferential access to centralized EU hospital tenders.
- Microbial biotransformation yield improvements:Fermentation-based 17-hydroxyprogesterone conversion is reducing raw material waste in active pharmaceutical ingredient production.
Market Restraints
- Cold-chain infrastructure gaps:Injectable corticosteroid distribution faces temperature excursion risks in regions lacking validated storage networks, limiting hospital accreditation.
- Prednisone bioequivalence documentation:India's CDSCO phased quality mandate requires domestic manufacturers to complete comparative pharmacokinetic studies, extending time-to-market.
- Metabolic adverse event surveillance:Long-term corticosteroid exposure monitoring requirements under FDA pharmacovigilance programs increase post-market compliance costs.
Strategic Opportunities
- Ophthalmic post-surgical protocols:Cataract and retinal surgery recovery pathways in Germany and France are incorporating cortisone drops earlier, expanding formulation demand.
- Topical atopic dermatitis first-line positioning:Pediatric dermatology guidelines in the United Kingdom are elevating hydrocortisone creams before systemic immunosuppressants.
- Compounded pharmacy specialization:503B outsourcing facilities meeting tightened FDA sterility standards capture hospital contracts for patient-specific dosing.
Industry Challenges
- Qualified personnel scarcity:Sterile injectable manufacturing requires operators trained in aseptic processing under EU GMP Annex 1 guidelines, constraining capacity expansion.
- Legacy ERP integration:Hospital procurement systems demand EDI connectivity for corticosteroid ordering, forcing smaller suppliers into expensive middleware upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cortisone Market |
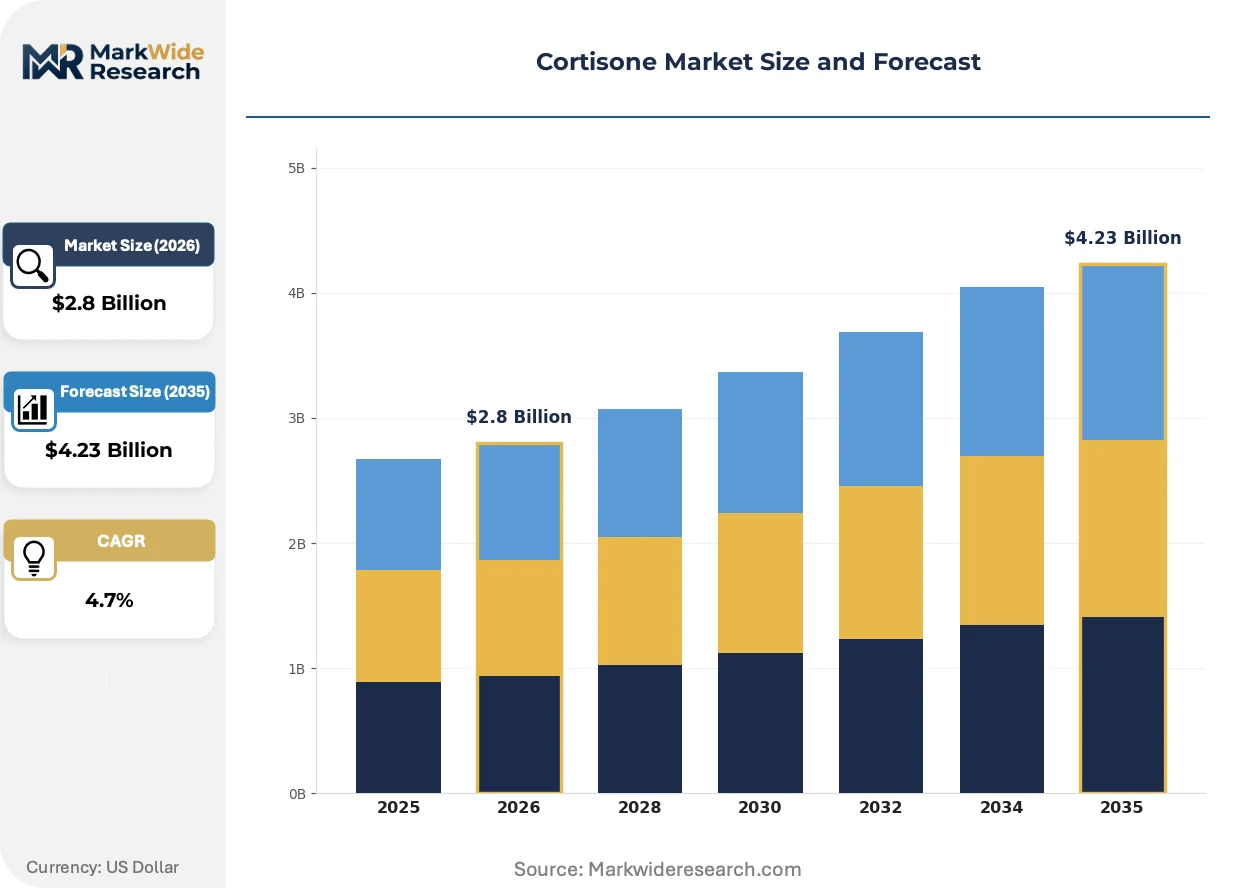
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cortisone Acetate, Hydrocortisone, Prednisone, Methylprednisolone Application: Autoimmune Disorders, Allergic Reactions, Inflammatory Conditions, Dermatological Treatments Delivery Mode: Oral, Injectable, Topical, Inhalation End User: Hospitals, Clinics, Homecare Settings, Pharmacies |
| Companies Covered | Pfizer Inc., Johnson & Johnson, Novartis AG, GlaxoSmithKline plc, Bayer AG, Merck & Co Inc, AbbVie Inc., Viatris Inc., Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cortisone Market Emerging Trajectories
Continuous manufacturing and real-time release testing are displacing batch processing in corticosteroid active pharmaceutical ingredient production. Regulatory alignment around quality metrics is compressing variation between branded and generic formulation performance.
Lyophilized corticosteroid vials are consolidating hospital pharmacy preference for injectable products, replacing liquid formulations with extended stability profiles. Integrated delivery networks in the United States are mandating these presentations for their cold-chain reliability. This consolidation is reducing wastage from expired stock while enabling centralized compounding operations.
The FDA's tightened purity standards for compounded corticosteroids are forcing 503A and 503B facilities to implement enhanced environmental monitoring and container closure integrity testing. Manufacturers failing these requirements face enforcement actions including warning letters and product recalls. Hospital procurement departments are responding by restricting vendor pools to facilities with demonstrated compliance histories.
Specialty pharmacy distribution is capturing oral corticosteroid volume from traditional retail channels as autoimmune patients seek coordinated care management. Rheumatology practices in the United States are directing prescriptions to pharmacies offering adherence monitoring and prior authorization support. This channel migration is most visible in Medicare Part D populations where medication therapy management programs intersect with corticosteroid tapering protocols.
Cortisone Market Segmentation
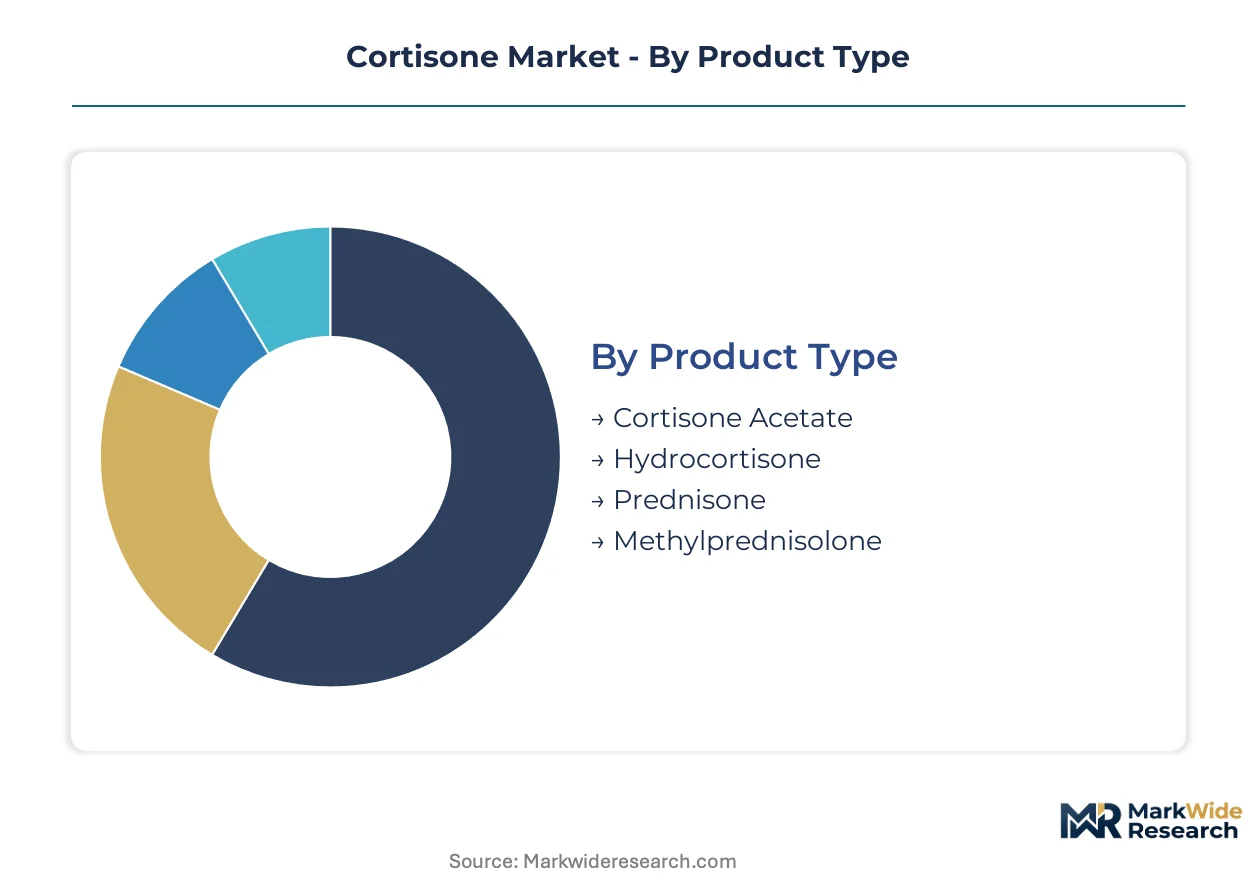
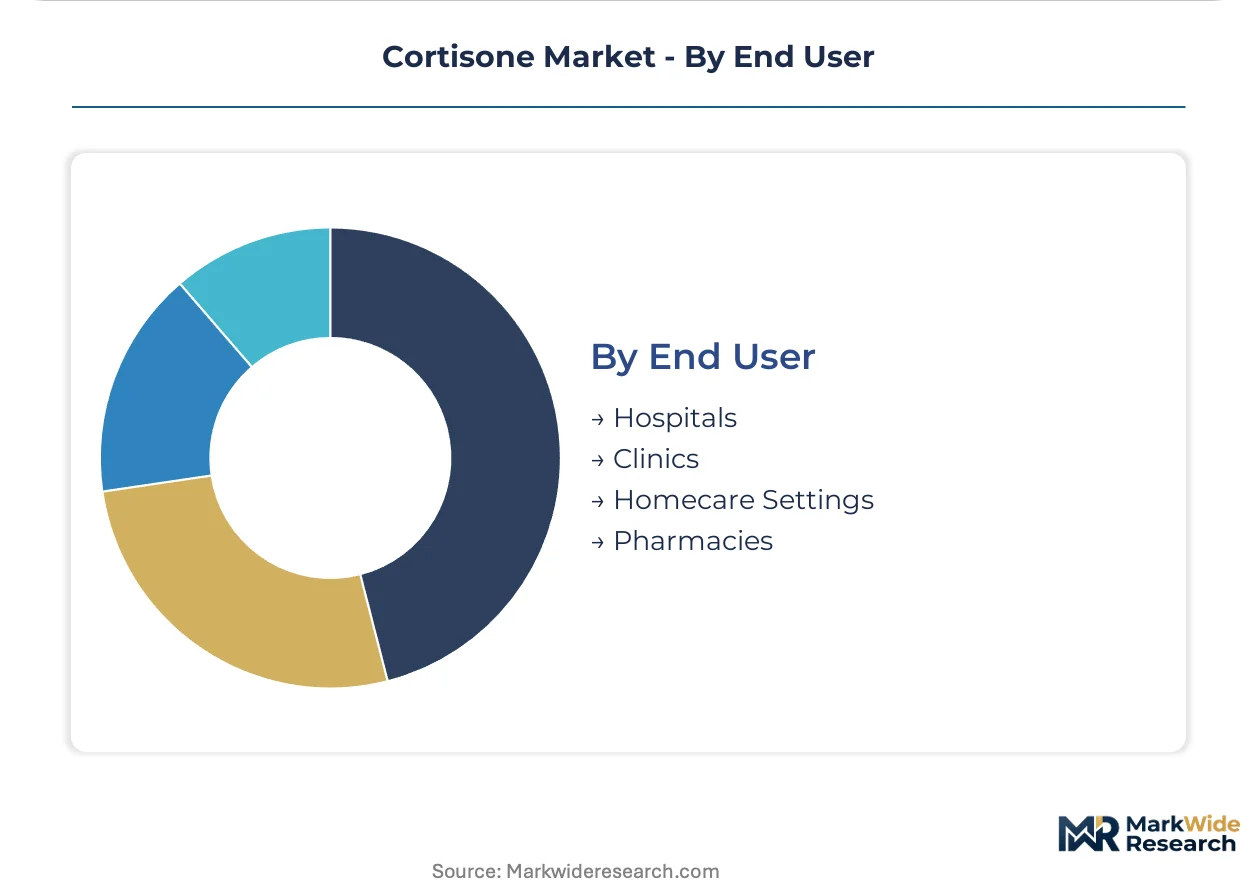
Cortisone market segmentation reveals distinct procurement patterns across molecular variants and care settings. Hospital formularies prioritize cold-chain reliability and bioequivalence documentation when selecting between hydrocortisone and prednisone alternatives. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume commoditizes.
Product Type:
Prescriber familiarity and half-life duration drive formulary placement decisions across glucocorticoid variants.
- Hydrocortisone:Short-acting corticosteroid with 8-12 hour biological half-life suitable for acute adrenal insufficiency and perioperative stress dosing. Demand concentrates in United States emergency departments and surgical suites where rapid titration protocols require predictable clearance kinetics.
- Prednisone:Intermediate-acting synthetic glucocorticoid converted hepatically to prednisolone, enabling once-daily oral administration in rheumatoid arthritis and lupus maintenance protocols. Rheumatology clinics in Germany and France favor this molecule for patient adherence programs.
- Cortisone Acetate:Pro-drug requiring enzymatic conversion to active cortisol, limited to niche adrenal replacement scenarios.
- Methylprednisolone:High-potency methylated derivative with minimal mineralocorticoid activity, preferred for neurosurgical edema and spinal cord injury protocols.
Volume sits with hydrocortisone; growth tilts toward prednisone.
Application:
Treatment protocol evolution is redrawing segment boundaries as dermatology and rheumatology guidelines shift corticosteroid positioning.
- Autoimmune Disorders:Systemic lupus erythematosus and multiple sclerosis flare management represent the largest addressable population for oral and injectable corticosteroids. United States Medicare Part D claims data shows concentration in specialty pharmacy dispensing for coordinated tapering support.
- Inflammatory Conditions:Acute gout, sarcoidosis, and inflammatory bowel disease protocols drive pulsed-dose methylprednisolone demand in hospital infusion centers.
- Allergic Reactions:Anaphylaxis and severe contact dermatitis emergency protocols favor epinephrine-corticosteroid combination therapy.
- Dermatological Treatments:Atopic dermatitis and psoriasis first-line positioning elevates hydrocortisone cream demand in United Kingdom pediatric practices.
Revenue concentrates in autoimmune applications; dermatological protocols are climbing fastest.
Delivery Mode:
Cold-chain infrastructure availability and administration setting accreditation determine feasible distribution pathways.
- Injectable:Lyophilized vials and pre-filled syringes command premium pricing in hospital settings where aseptic compounding requirements limit supplier pools. Integrated delivery networks mandate these presentations for centralized pharmacy operations.
- Oral:Tablet and solution formulations dominate retail and specialty pharmacy channels, with prednisone 5mg and 10mg strengths representing the highest prescription volumes.
- Topical:Cream, ointment, and lotion vehicles segment by potency classification, with mid-strength hydrocortisone capturing over-the-counter and prescription transitions.
- Inhalation:Metered-dose and dry-powder corticosteroids for asthma maintenance occupy a distinct regulatory pathway with separate bioequivalence requirements.
Margin pools favor injectable; oral volume sustains manufacturer base load.
End User:
Procurement sophistication and reimbursement density create tiered access requirements across care settings.
- Hospitals:Group purchasing organizations and integrated delivery networks concentrate purchasing power, demanding EDI connectivity and validated cold-chain documentation. FDA 503B outsourcing facility contracts are displacing traditional wholesaler relationships for patient-specific dosing.
- Clinics:Ambulatory surgical centers and rheumatology practices are expanding supervised corticosteroid administration, pulling volume from inpatient settings.
- Pharmacies:Specialty pharmacy distribution captures oral corticosteroid volume through adherence monitoring and prior authorization support programs.
- Homecare Settings:Self-administered oral tapering protocols and patient-managed topical applications operate outside institutional procurement frameworks.
Hospital procurement commands supplier attention; clinic expansion offers the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India and tax-advantaged manufacturing corridors in Ireland are concentrating corticosteroid active pharmaceutical ingredient production. These zones offer accelerated depreciation allowances and streamlined environmental clearances that reduce facility establishment timelines. The resulting geographic clustering shapes procurement patterns across hospital systems and pharmaceutical distribution networks.
United States
Chronic inflammatory disease prevalence and dense Medicare Part D reimbursement support premium corticosteroid formulation uptake. FDA tightened purity standards for compounded corticosteroids under 503B outsourcing facility rules, reshaping supplier qualification requirements. The Research Triangle Park corridor in North Carolina hosts sterile injectable manufacturing operations serving integrated delivery networks with validated cold-chain documentation.
Germany
Ophthalmic post-surgical protocols in cataract and retinal surgery recovery pathways are expanding cortisone drop demand. EMA Committee for Medicinal Products for Human Use evaluates centralized EU market authorization for cortisone-containing therapies. The Rhine-Main cluster around Frankfurt concentrates hospital procurement consolidation and group purchasing organization headquarters.
India
Domestic corticosteroid manufacturers face CDSCO phased quality mandates requiring bioequivalence documentation for prednisone products. Fermentation-based 17-hydroxyprogesterone conversion facilities in Hyderabad and Visakhapatnam are reducing raw material waste through microbial biotransformation yield improvements. The Pharmaceutical Export Promotion Council operates special economic zones offering duty exemptions on imported fermentation equipment.
United Kingdom
Pediatric dermatology guidelines are elevating hydrocortisone creams to first-line positioning before systemic immunosuppressants for atopic dermatitis. The Medicines and Healthcare products Regulatory Agency aligns with EMA pharmacovigilance requirements for long-term corticosteroid exposure monitoring. The Golden Triangle biotech corridor between London, Oxford, and Cambridge hosts specialty pharmacy distribution networks capturing oral corticosteroid volume through adherence monitoring programs.
France
Rheumatology clinics are expanding supervised corticosteroid administration, pulling volume from inpatient settings into ambulatory surgical centers. ANSM enforces post-market surveillance for metabolic and ocular adverse events linked to extended corticosteroid use. The Lyon-Grenoble pharmaceutical manufacturing belt concentrates sterile injectable capacity serving hospital procurement tenders across the EU.
Cortisone Market Vendor Landscape
Top-tier vendors anchor hospital supply chains through injectable corticosteroid portfolios, while mid-tier generic manufacturers compete aggressively in oral prednisone across retail pharmacy channels. The market structure reflects tiered supplier qualification barriers, with FDA 503B compliance histories determining vendor pool access for integrated delivery networks. Three strategic archetypes dominate: multinational pharmaceutical conglomerates with diversified glucocorticoid portfolios, regional generic specialists focusing on high-volume oral formulations, and 503B outsourcing facilities capturing patient-specific dosing contracts. Competitive moves concentrate on sterile manufacturing capacity expansion and specialty pharmacy distribution partnerships.
Among diversified pharmaceutical conglomerates, Pfizer Inc. and Novartis AG exemplify the hospital-centric archetype through their positioning in North American supply chains and ophthalmic formulation specialization respectively. Teva Pharmaceutical Industries Ltd. occupies the generic specialist tier, with its corporate structure reflecting Israeli origins and aggressive European retail pharmacy penetration. These three entities represent the competitive spectrum from premium branded injectables to commoditized oral tablets.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson |
| Novartis AG |
| GlaxoSmithKline plc |
| Bayer AG |
| Merck & Co Inc |
| AbbVie Inc. |
| Viatris Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Supply Flow & Price Mechanics
Aseptic processing specialists in the Rhine-Main corridor command wage premiums that compress margins for sterile injectable manufacturers while widening spreads between branded hospital formulations and commoditized oral generics. Labor-cost differentials between EU GMP-certified facilities and emerging-market API plants feed directly into pricing-tier stratification across corticosteroid portfolios.
Pricing Analysis
Short-lead-time premiums attach to lyophilized vial presentations where hospital formularies demand validated cold-chain documentation within 48-hour windows. Spot inventory of oral prednisone trades at discounts reflecting generic saturation in European retail channels. Three-tier pricing structure across premium, standard, and economy levels separates FDA 503B outsourcing contracts from wholesaler agreements and direct-to-hospital tenders. Cost compression in oral generics intensifies as Indian CDSCO bioequivalence mandates extend time-to-market for domestic manufacturers. Specialty pharmacy dispensing exhibits lowest price sensitivity due to bundled adherence monitoring services.
Supply Chain Analysis
Single-source vulnerability sits with fermentation-based 17-hydroxyprogesterone conversion capacity concentrated in Hyderabad and Visakhapatnam special economic zones. Active pharmaceutical ingredient production draws from Indian microbial biotransformation facilities, Chinese chemical intermediate plants, and Irish tax-advantaged formulation corridors. Raw material dependencies span fermentation substrates, sterile vial components, and cold-chain packaging. Tariff exposure on imported fermentation equipment threatens capacity expansion timelines. Distribution runs through integrated delivery networks mandating EDI connectivity for hospital procurement systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where FDA purity mandates and hospital procurement qualification barriers are forcing sub-scale compounders toward exit or acquisition. Margin compression in oral generics accelerates shakeout timelines for undifferentiated manufacturers.
For Market Incumbents: Deepen sterile manufacturing capacity in Research Triangle Park corridor to capture 503B outsourcing facility contracts displacing traditional wholesaler relationships. Expand backward integration into fermentation-based API production to hedge against Indian import tariff volatility. Secure EMA centralized market authorization pathways ahead of EU hospital tender consolidation.
For New Entrants and Emerging Players: Ambulatory surgical centers represent the most penetrable buyer archetype as rheumatology clinics expand supervised corticosteroid administration outside inpatient settings. Target ophthalmic post-surgical protocols in German and French cataract recovery pathways where cortisone drop demand outpaces incumbent supply. Pursue 503A compounding specialization with patient-specific dosing capabilities as the primary go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with EU GMP-certified sterile injectable specialists given REACH compliance alignment and preferential access to centralized hospital tenders. Five-to-ten-year viability favors manufacturers with demonstrated FDA pharmacovigilance compliance histories and cold-chain infrastructure ownership. Monitor CDSCO enforcement actions against non-compliant Indian API producers as the inflection indicator for supply-side restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 503B Outsourcing Facility Qualification | Hospital procurement departments restrict vendor pools to facilities with demonstrated compliance histories and validated sterility protocols. |
| Microbial Biotransformation Yield Improvement | Fermentation-based 17-hydroxyprogesterone conversion in Hyderabad special economic zones reduces raw material waste in API production. |
| Lyophilized Vial Presentation Expansion | Integrated delivery networks mandate cold-chain-stable formulations for centralized pharmacy operations and reduced wastage. |
| Specialty Pharmacy Distribution Partnership | Rheumatology practices direct Medicare Part D prescriptions to pharmacies offering adherence monitoring and prior authorization support. |
| EMA Centralized Market Authorization Pathway | Committee for Medicinal Products for Human Use evaluation enables preferential access to EU hospital procurement tenders. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this corticosteroid market assessment. Primary interviews with hospital procurement managers, 503B facility operators, formulary directors, and CDSCO regulatory affairs leads combined with FDA warning letter databases, EMA submission portals, and Indian Pharmaceutical Export Promotion Council trade statistics. Bottom-up patient population modeling and top-down pharmaceutical spending analysis provided triangulation checks across volume and value estimates.
Granularity-level framing applied molecular variant splits for hydrocortisone, prednisone, and methylprednisolone; delivery mode disaggregation across injectable, oral, topical, and inhalation; and end-user segmentation across hospitals, clinics, pharmacies, and homecare settings across the analysis window. CAGRs derived from treatment protocol adoption curves, autoimmune disorder prevalence trajectories, and reimbursement density projections. Forecast inputs incorporated FDA pharmacovigilance program expansion timelines and ECHA substance registration compliance trajectories.
Revisions become necessary when CDSCO enforcement intensity against domestic bioequivalence non-compliance accelerates, or when cold-chain infrastructure investment in target markets stalls. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Loratadine Market
Pharmaceuticals
Betahistine Mesilate Market
Pharmaceuticals
Dyslipidemia Therapeutics Market
Pharmaceuticals
Normal Saline for Parenteral Use Market
Pharmaceuticals
APAC Pharmaceutical Warehousing Market
Pharmaceuticals
Eperisone Hcl Market
Pharmaceuticals
Asia-Pacific GLP 1 Agonist Market
Pharmaceuticals
Germany Pharmaceutical 3PL Market
Pharmaceuticals
Ophthalmic Drugs Market
Pharmaceuticals
Intelligent Pills Market
Pharmaceuticals
Pharmaceutical Water Market
Pharmaceuticals
Asia-Pacific Fatty Bases for Suppositories Market
Pharmaceuticals
Global RFID in Pharmaceuticals Market
Pharmaceuticals
Hyoscine Market
Pharmaceuticals
Zimbabwe Pharmaceutical Market
Pharmaceuticals
Global Bispecific Antibody Therapeutics Market