
 Asia-Pacific MEMS and Sensors Market | 2026-2036
Asia-Pacific MEMS and Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific MEMS and Sensors Market Outlook
Silicon-on-insulator wafers are repositioning cost structures for high-precision inertial sensors across the Asia-Pacific. Robert Bosch GmbH leverages captive MEMS foundry capacity in Reutlingen to supply Asian automotive Tier-1s with gyroscope modules. STMicroelectronics anchors its Singapore packaging hub as the primary launch point for consumer-grade accelerometers bound for Chinese smartphone OEMs. Texas Instruments competes through integrated signal-conditioning ASICs that reduce board-level component counts for industrial automation customers.
Micro-electromechanical systems integrate mechanical elements, sensors, actuators, and electronics on a common silicon substrate through micromachining processes, typically operating at micron-scale dimensions with resonant frequencies from kilohertz to megahertz. These devices transduce physical quantities—acceleration, pressure, angular rate, acoustic waves—into electrical signals for real-time monitoring and control in safety-critical and consumer applications. Pressure sensors lead the product type category due to their ubiquity in automotive tire monitoring and medical infusion pumps, while gyroscopes represent the fastest-growing segment as vehicle dynamics control and optical image stabilization expand. Within application segments, automotive generates the deepest margin pools because of AEC-Q100 qualification requirements and multi-year supplier validation cycles that limit new entrants.
Japan's METI enforces JIS standards for automotive sensor reliability, while China's MIIT coordinates GB standards development for domestic MEMS supply chain localization under national technology self-sufficiency directives. South Korea's MFDS and KATS frameworks govern medical device sensor certifications, creating parallel compliance pathways for healthcare applications. Stakeholders must monitor how divergence between Chinese GB standards and international IEC specifications affects cross-border component qualification timelines and aftermarket access.
Market Dynamics
China's dual carbon goals and MIIT sensor-industry development plans are accelerating domestic MEMS foundry investments, compressing the historical reliance on imported wafers and repositioning supply-side power toward the Yangtze River Delta electronics manufacturing cluster.
Growth Catalysts
- Automotive electrification mandates:Japan and South Korea enforce stringent emissions targets that expand sensor deployment for electric powertrains and battery management systems.
- MIIT localization directives:China's GB standards development under national technology self-sufficiency directives accelerates domestic MEMS supply chain qualification timelines.
- Wafer-level packaging scaling:Foundry investments in Suzhou and Shanghai reduce die-level processing costs for consumer-grade accelerometers.
Market Restraints
- Silicon-on-insulator wafer cost volatility:SOI substrate prices fluctuate with 300mm semiconductor capacity constraints, squeezing gross margins for high-precision inertial sensor manufacturers.
- Captive foundry concentration:Robert Bosch GmbH's Reutlingen facility and STMicroelectronics' internal capacity limit accessible merchant supply for Asian automotive Tier-1s.
- AEC-Q100 qualification timelines:Multi-year supplier validation cycles for automotive-grade sensors delay revenue recognition for new entrants.
Strategic Opportunities
- Medical device sensor expansion:South Korea's MFDS and KATS frameworks create parallel certification pathways for healthcare applications beyond automotive saturation.
- Optical image stabilization convergence:Gyroscope-accelerometer fusion in smartphone camera modules opens premium tier positioning for Chinese OEMs.
- Industrial automation retrofit demand:Signal-conditioning ASIC integration reduces board-level component counts for factory automation customers seeking legacy system upgrades.
Industry Challenges
- Micromachining talent scarcity:Deep reactive-ion etching and wafer bonding expertise concentrates in legacy Japanese and German engineering pools, constraining Asian foundry scale-up.
- Cross-border standard divergence:Misalignment between Chinese GB specifications and IEC international standards fragments component qualification protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific MEMS and Sensors Market |
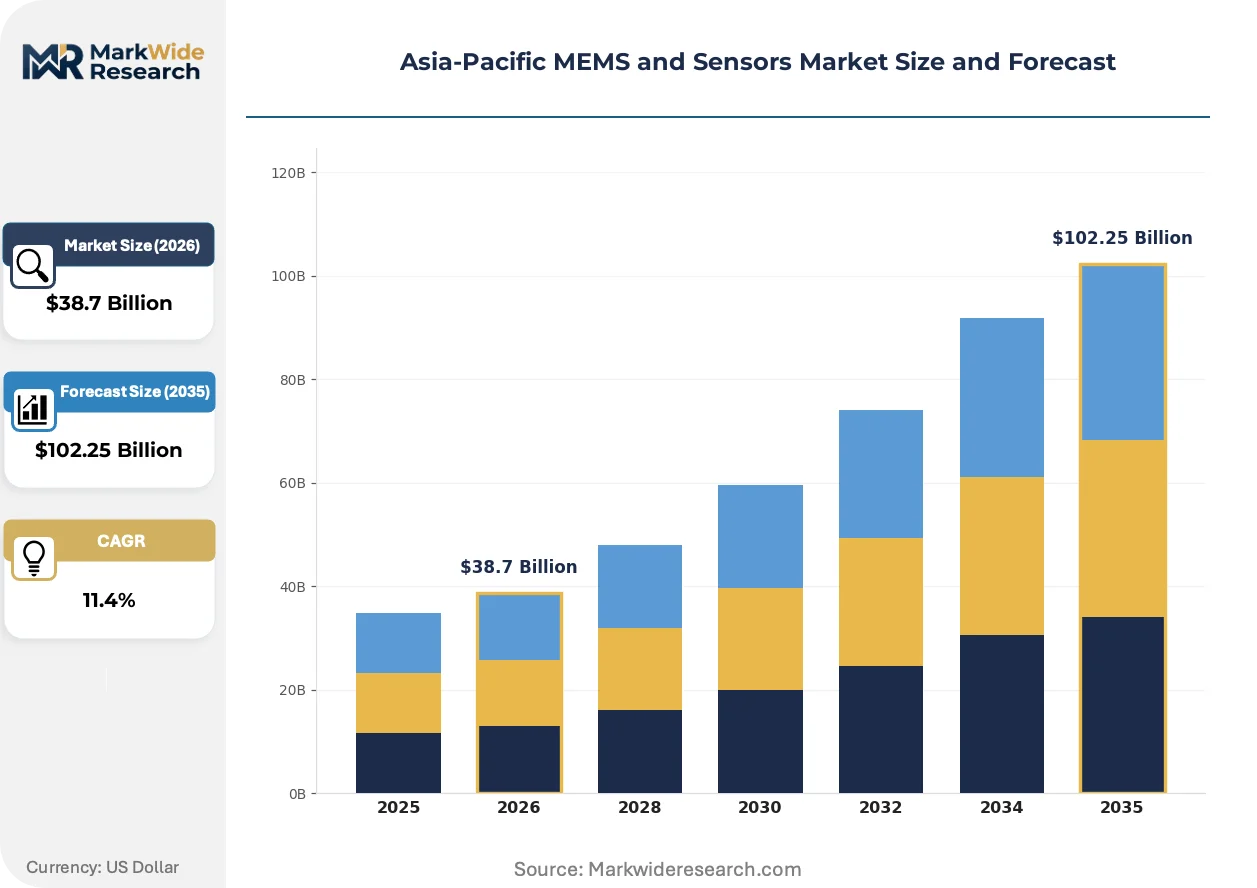
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Accelerometers, Pressure Sensors, Gyroscopes, Microphones Application: Consumer Electronics, Automotive, Healthcare, Industrial Automation Technology: MEMS, Nanotechnology, Analog, Digital End User: OEMs, Aftermarket Providers, Research Institutions, Transportation |
| Companies Covered | STMicroelectronics, Robert Bosch GmbH, Texas Instruments, NXP Semiconductors, Analog Devices, Honeywell International, Rockwell Automation, Panasonic Corporation, Denso Corp, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific MEMS and Sensors Market Strategic Shifts
Silicon photonics integration, regulatory harmonization pressures, and buyer consolidation are compressing traditional MEMS value chain structures across the Asia-Pacific region.
Silicon-on-insulator wafers is electrifying cost structures for high-precision inertial sensors by enabling thinner device layers with superior thermal isolation. Automotive Tier-1 suppliers in Japan and South Korea are accelerating qualification of SOI-based gyroscopes for vehicle dynamics control. This substrate transition is compressing the performance gap between consumer-grade and automotive-grade resonant devices.
Japan's METI enforces JIS standards for automotive sensor reliability that exceed baseline IEC specifications, creating technical barriers for non-domestic suppliers. Manufacturers must maintain parallel qualification streams to serve both Japanese OEMs and export markets. The medical device segment faces additional layering from South Korea's MFDS and KATS frameworks governing healthcare sensor certifications.
Chinese smartphone OEMs are consolidating accelerometer procurement around wafer-level packaged die from Singapore-based hubs, displacing traditional chip-scale packaging vendors. This channel compression favors suppliers with captive backend capacity. The Yangtze River Delta electronics cluster exhibits the most pronounced buyer concentration, with tier-one handset manufacturers negotiating direct foundry relationships.
Asia-Pacific MEMS and Sensors Market Segmentation
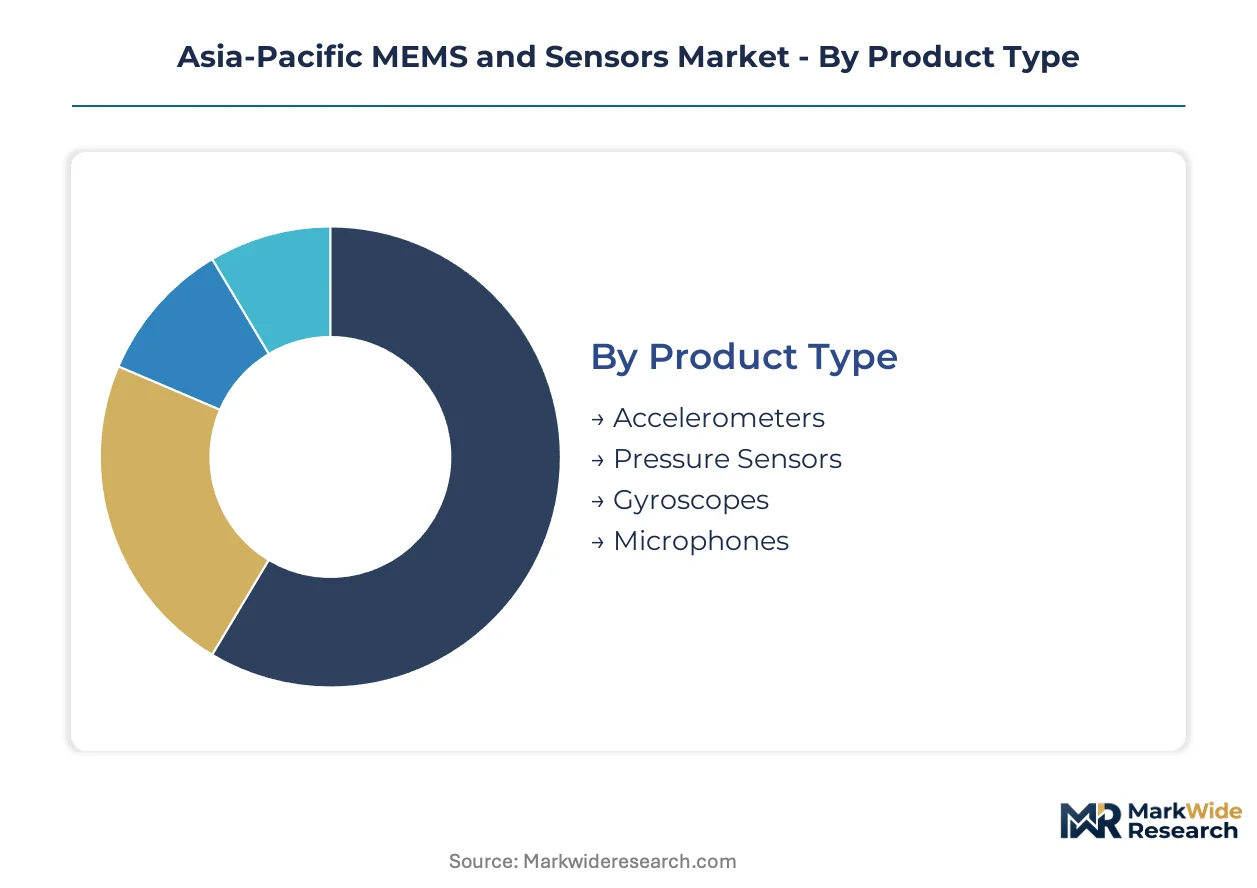
MEMS and sensors in Asia-Pacific exhibit divergent margin profiles across product architectures and end-use certifications. Automotive-grade devices command qualification premiums while consumer-grade components scale through wafer-level packaging efficiencies in China's Yangtze River Delta cluster.
Product Type:
Pressure sensors dominate unit volumes through automotive tire monitoring and medical infusion pump deployments, while gyroscopes capture expanding premium tiers through optical image stabilization convergence.
- Pressure Sensors:Piezoresistive and capacitive transduction elements convert mechanical stress into electrical signals for fluid dynamics monitoring. Demand concentrates in Japan's automotive Tier-1 supplier base, where AEC-Q100 qualification requirements sustain multi-year validation cycles that limit competitive entry.
- Gyroscopes:Coriolis-force resonant structures measure angular velocity with precision sufficient for vehicle dynamics control and camera module stabilization. China's smartphone OEMs in the Yangtze River Delta are consolidating procurement around fused gyroscope-accelerometer die for premium tier positioning.
- Accelerometers:Capacitive sensing elements detect linear acceleration across consumer electronics and automotive safety systems. Singapore-based packaging hubs serve as the primary launch point for Chinese handset manufacturers.
- Microphones:Capacitive MEMS acoustic transducers capture sound pressure variations for voice interfaces and noise cancellation. South Korea's consumer electronics OEMs drive specifications for ultra-low power consumption in wearable form factors.
Today's leader: Pressure Sensors. Tomorrow's challenger: Gyroscopes.
Application:
Automotive applications generate the deepest margin pools through safety-critical certification requirements, while consumer electronics scales through volume concentration in Chinese manufacturing clusters.
- Automotive:Powertrain monitoring, chassis dynamics control, and autonomous driving perception systems require AEC-Q100 qualified devices with extended temperature ranges. Japan's METI enforces JIS reliability standards that exceed baseline IEC specifications, creating technical barriers for non-domestic suppliers serving Japanese OEMs.
- Consumer Electronics:Smartphones, wearables, and hearables integrate motion sensing, environmental monitoring, and acoustic capture for user interface enhancement. Procurement concentrates around wafer-level packaged die from Singapore-based hubs, displacing traditional chip-scale packaging vendors through cost compression.
- Healthcare:Patient monitoring, diagnostic imaging, and drug delivery systems demand biocompatible packaging and sterilization tolerance. South Korea's MFDS and KATS frameworks govern certification pathways parallel to automotive saturation.
- Industrial Automation:Predictive maintenance, process control, and robotics guidance utilize ruggedized sensors with integrated signal-conditioning ASICs. Texas Instruments competes through board-level component count reduction for factory automation retrofit demand.
Automotive commands margin premiums today. Consumer electronics volume expansion is climbing the fastest.
Technology:
MEMS fabrication dominates commercial deployment through established foundry infrastructure, while nanotechnology approaches target performance thresholds beyond conventional micromachining limits.
- MEMS:Bulk and surface micromachining processes etch mechanical structures into silicon substrates with micron-scale precision. China's MIIT sensor-industry development plans accelerate domestic foundry investments, compressing historical reliance on imported wafers.
- Nanotechnology:Carbon nanotube and graphene-based transduction elements enable sensitivity improvements for specialized detection applications. Research institutions in Japan and South Korea anchor exploratory development programs.
- Analog:Continuous signal processing architectures preserve measurement fidelity for high-precision inertial sensing. Silicon-on-insulator wafers enable thinner device layers with superior thermal isolation for resonant devices.
- Digital:Integrated ADC and DSP cores enable software-configurable sensor parameters and edge computing capabilities. OEMs in China's electronics manufacturing cluster specify digital interfaces for system integration efficiency.
MEMS holds manufacturing scale today. Nanotechnology approaches are gaining share fastest in specialized detection tiers.
End User:
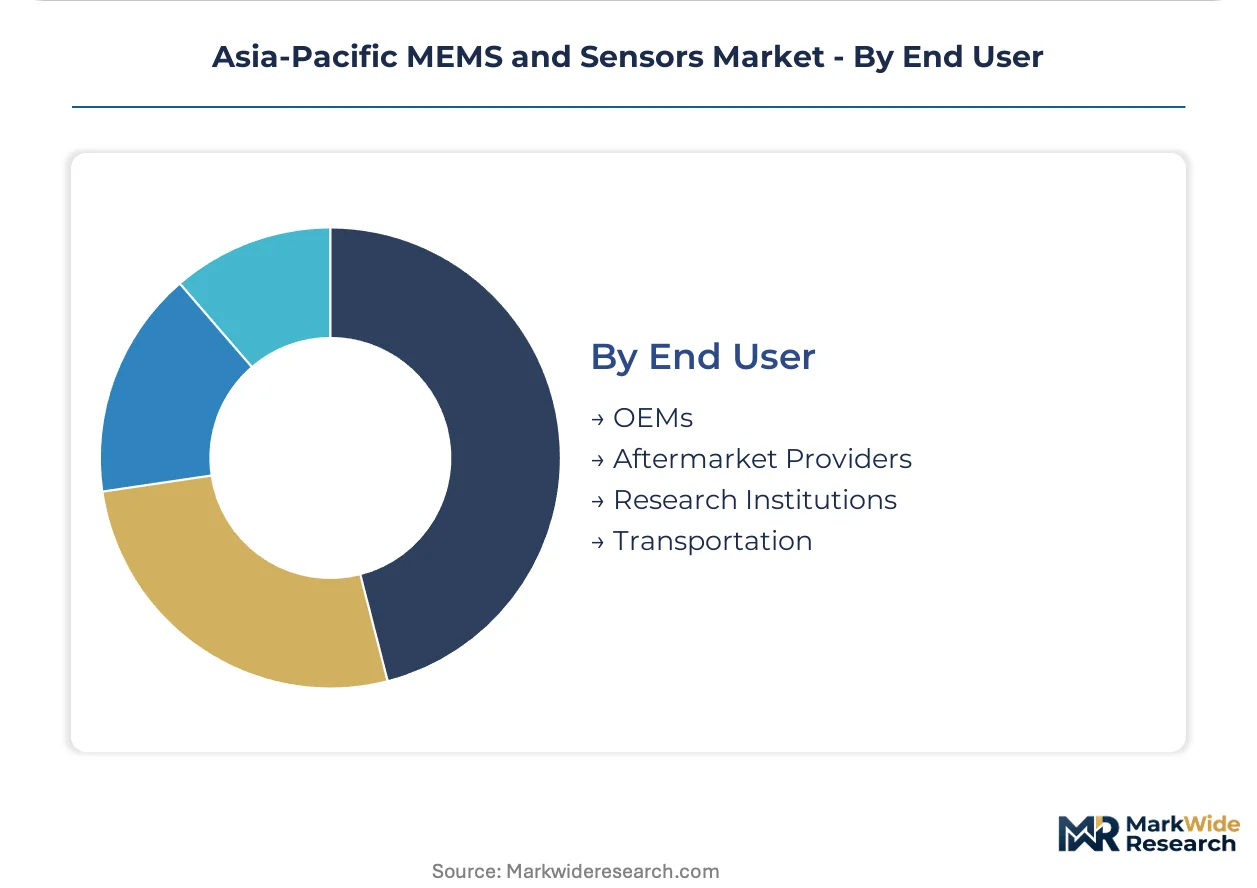
OEMs dominate procurement through direct foundry relationships, while aftermarket providers serve replacement demand with reduced qualification burdens.
- OEMs:Original equipment manufacturers in automotive, consumer electronics, and medical device sectors specify custom sensor parameters and captive supply arrangements. Chinese smartphone OEMs negotiate direct foundry relationships in the Yangtze River Delta, consolidating procurement around wafer-level packaged die.
- Aftermarket Providers:Replacement sensor modules for automotive service and industrial maintenance bypass multi-year validation cycles. Distribution runs through regional distributors serving repair networks across Southeast Asian markets.
- Research Institutions:Universities and national laboratories prototype novel transduction mechanisms and packaging approaches. Japan's METI and China's MIIT coordinate funding for domestic MEMS supply chain localization under technology self-sufficiency directives.
- Transportation:Fleet operators and logistics providers deploy telematics sensors for asset tracking and condition monitoring. South Korea's commercial vehicle mandates expand tire pressure and cargo sensing requirements.
OEMs control premium procurement today. Aftermarket channels are expanding most quickly in Southeast Asian service networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta electronics manufacturing cluster anchors Asia-Pacific MEMS demand through wafer-level packaging scale-up and direct OEM-foundry relationships. China's MIIT sensor-industry directives and Japan's METI JIS reliability frameworks create divergent qualification pathways across the region. South Korea's automotive electrification mandates and medical device certification frameworks add parallel demand vectors.
China
Domestic MEMS foundry investments accelerate under dual carbon goals and technology self-sufficiency directives. MIIT coordinates GB standards development that compresses cross-border component qualification timelines. Suzhou and Shanghai wafer-level packaging capabilities scale rapidly, consolidating procurement for smartphone OEMs in the Yangtze River Delta cluster.
Japan
Automotive Tier-1 suppliers expand sensor deployment for electric powertrains and autonomous driving perception systems. METI enforces JIS reliability standards that exceed baseline IEC specifications, creating technical barriers for non-domestic suppliers. Kanto and Kansai industrial corridors concentrate captive foundry relationships and multi-year supplier validation cycles.
South Korea
Battery management system sensor demand surges alongside emissions reduction mandates for commercial vehicle fleets. MFDS and KATS frameworks govern parallel certification pathways for medical device sensors beyond automotive saturation. Seoul Capital Area and Busan-Ulsan corridors anchor healthcare and automotive Tier-1 procurement concentration.
Singapore
Packaging hubs serve as the primary launch point for consumer-grade accelerometers bound for Chinese smartphone OEMs. Foundry backend capacity favors suppliers with captive integration over traditional chip-scale packaging vendors. The city-state's logistics infrastructure enables rapid die shipment to Yangtze River Delta manufacturing clusters.
Taiwan
Semiconductor foundry ecosystems extend into MEMS process development for fabless sensor designers. TSMC-adjacent packaging capabilities support wafer-level integration for premium tier smartphone modules. Hsinchu Science Park concentration enables co-location of design houses and backend processing facilities.
Asia-Pacific MEMS and Sensors Market Competitive Environment
Global majors compete with regional champions across captive foundry access and automotive qualification depth. The vendor base stratifies into three tiers: integrated device manufacturers with captive MEMS capacity, fabless specialists dependent on merchant foundry access, and packaging-centric assemblers competing on backend efficiency. Dominant competitive moves include backward integration into wafer-level packaging and strategic partnerships to secure AEC-Q100 qualification pathways.
Within the integrated device manufacturer tier, Robert Bosch GmbH and STMicroelectronics exemplify archetypes of captive foundry control. Texas Instruments anchors a position emphasizing signal-conditioning integration for industrial automation retrofit demand. These three entities represent contrasting strategic postures: German automotive-grade captive production, Singapore-packaged consumer-grade scale, and ASIC-integrated industrial solutions.
| Leading Market Players |
|---|
| STMicroelectronics |
| Robert Bosch GmbH |
| Texas Instruments |
| NXP Semiconductors |
| Analog Devices |
| Honeywell International |
| Rockwell Automation |
| Panasonic Corporation |
| Denso Corp |
| Others |
Value Chain & Pricing Dynamics
Chinese smartphone OEM procurement concentration in the Yangtze River Delta anchors a three-tier pricing structure across premium, standard, and economy levels, where wafer-level packaging scale determines supplier selection and cost compression cascades through tiered die specifications.
Pricing Analysis
Silicon-on-insulator wafer cost volatility passes through to high-precision inertial sensor margins, with 300mm semiconductor capacity constraints squeezing gross margins for automotive-grade gyroscope manufacturers. Price differentiation hinges on AEC-Q100 certification depth and wafer-level packaging integration, with Japanese automotive Tier-1s least sensitive and Chinese consumer electronics OEMs most responsive to per-unit die costs. Cost compression in consumer-grade accelerometers is intensifying because Singapore-based packaging hubs consolidate procurement around captive backend suppliers.
Supply Chain Analysis
Reverse-logistics flows for automotive sensor modules remain underdeveloped across Asia-Pacific, with refurbishment limited to industrial automation retrofits and medical device recalibration services. Supply concentrates in China, Japan, and South Korea, with the Yangtze River Delta electronics cluster feeding from silicon wafer inputs, specialized etching equipment, and AEC-Q100 qualification expertise. Single-source vulnerability around SOI substrate supply creates exposure for resonant device manufacturers. Distribution runs through direct OEM-foundry relationships in automotive and Singapore-based packaging hubs for consumer electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with China's MIIT sensor-industry directives and dual carbon goals accelerating domestic foundry investments that reshape competitive positioning across the region.
For Market Incumbents: Acquire captive wafer-level packaging capacity in the Yangtze River Delta to defend against Chinese smartphone OEM direct-foundry negotiations. Secure AEC-Q100 qualification pathways ahead of Japanese METI JIS reliability standard updates that exceed baseline IEC specifications. Backward integration into SOI substrate sourcing reduces exposure to 300mm semiconductor capacity constraints. For New Entrants and Emerging Players: Nanotechnology-based transduction elements offer a technology-first wedge into specialized detection tiers beyond conventional micromachining limits. Target South Korea's medical device sensor segment under MFDS and KATS frameworks, where parallel certification pathways bypass automotive saturation. Lead with signal-conditioning ASIC integration for industrial automation retrofit demand. For Investors and Strategic Acquirers: Automotive Tier-1 suppliers are the most active acquirer in this space, seeking to secure sensor supply amid electrification mandates. Long-term viability centers on qualification depth rather than volume scale, with fabless specialists possessing AEC-Q100 pathways representing prime acquisition targets. Monitor divergence between Chinese GB standards and IEC specifications as an inflection indicator for cross-border component access.| Strategic Initiative | Industry Significance |
|---|---|
| Wafer-Level Packaging Scale-Up | Suzhou and Shanghai foundry investments reduce die-level processing costs for Chinese smartphone OEMs. |
| AEC-Q100 Qualification Pathway | Multi-year supplier validation cycles with Japanese METI JIS standards sustain margin premiums for automotive Tier-1s. |
| Silicon-on-Insulator Substrate Transition | Thinner device layers with superior thermal isolation compress the consumer-automotive performance gap for resonant gyroscopes. |
| GB Standards Localization | MIIT-coordinated domestic supply chain qualification accelerates foundry access under technology self-sufficiency directives. |
| Signal-Conditioning ASIC Integration | Texas Instruments competes through board-level component count reduction for factory automation retrofit customers. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with MEMS foundry operations managers, automotive Tier-1 procurement directors, smartphone OEM supply chain leads, and medical device regulatory affairs specialists with secondary validation against MIIT policy documents, METI JIS standard filings, MFDS certification databases, and semiconductor trade flow records. Bottom-up die shipment analysis and top-down electronics manufacturing cluster revenue triangulation anchored market sizing.
Historical reference periods established baseline penetration rates for pressure sensors in automotive tire monitoring and gyroscopes in optical image stabilization modules, with projections calibrated across the analysis window by product architecture, end-use certification tier, and regional manufacturing cluster. Modeled dimensions included sensor transduction mechanism, AEC-Q100 qualification depth, wafer-level packaging integration, and OEM-direct versus distributor procurement channel. CAGRs derived from segment-level shipment growth and average selling price trajectory analysis, with SOI substrate cost curves and foundry capacity buildout schedules as key inputs.
The model holds under continued MIIT localization support and stable SOI supply; deviation in cross-border standard harmonization or 300mm semiconductor capacity allocation would shift competitive positioning. Forecasts reflect documented assumptions about qualification timeline compression and packaging technology transition. Practitioners should monitor GB-IEC specification divergence and Yangtze River Delta foundry utilization rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Insulation Monitoring Devices (IMD) Market
Sensors and Controls
Multi-Function Timer Market
Sensors and Controls
Actigraphy Sensors Market
Sensors and Controls
Timing Device Market
Sensors and Controls
Wireless Temperature Sensor Market
Sensors and Controls
Smart Flow Meter Market
Sensors and Controls
Asia-Pacific Industrial Control System Market
Sensors and Controls
High Purity Flow Meter Market
Sensors and Controls
Global Pressure Calibrators Market
Sensors and Controls
Inertial Measurement Unit (IMU) Market
Sensors and Controls
Room Pressure Monitor Market
Sensors and Controls
Turbomachinery Control Systems Market
Sensors and Controls
ASEAN Safety Sensors and Switches Market
Sensors and Controls
Europe Pressure Transmitter Market
Sensors and Controls
Virtual Sensors Market
Sensors and Controls
Light Detection and Ranging (Lidar) Market