
 Inkjet Printhead Market | 2026-2036
Inkjet Printhead Market Size, Share, and Industry Trends Forecast 2026-2036
Inkjet Printhead Market Foresight
EU REACH regulation is hardening compliance thresholds for volatile organic compounds in industrial printing, raising capital requirements for ink formulation and printhead material compatibility. Epson sustains leadership through captive MEMS fabrication facilities in Japan. Fujifilm anchors its position with proprietary UV-curable ink chemistries that lock in recurring demand for matched printhead architectures.
An inkjet printhead is a precision microfluidic device that ejects picoliter-scale droplets through thermally actuated or piezoelectrically driven nozzles, typically fabricated via silicon MEMS processes with nozzle densities exceeding 300 per inch. Its primary purpose is to deposit controlled patterns of ink onto substrates ranging from paper and film to ceramics and printed circuit boards. Piezoelectric printheads dominate industrial segments where fluid versatility and substrate compatibility command premium positioning. Drop-on-Demand architectures are displacing Continuous Inkjet in packaging and textile applications where material waste reduction directly improves unit economics.
The US EPA enforces National Emission Standards for Hazardous Air Pollutants that constrain solvent-based inkjet operations in commercial print facilities. Japan's METI promotes next-generation manufacturing standards that subsidize domestic producers advancing high-resolution printhead integration for electronics fabrication. China's MEE implements dual carbon goals that pressure provincial printing clusters to phase out energy-intensive thermal drying processes. Stakeholders must monitor how divergent chemical compliance regimes fragment inkjet platform standardization and force region-specific product line architectures.
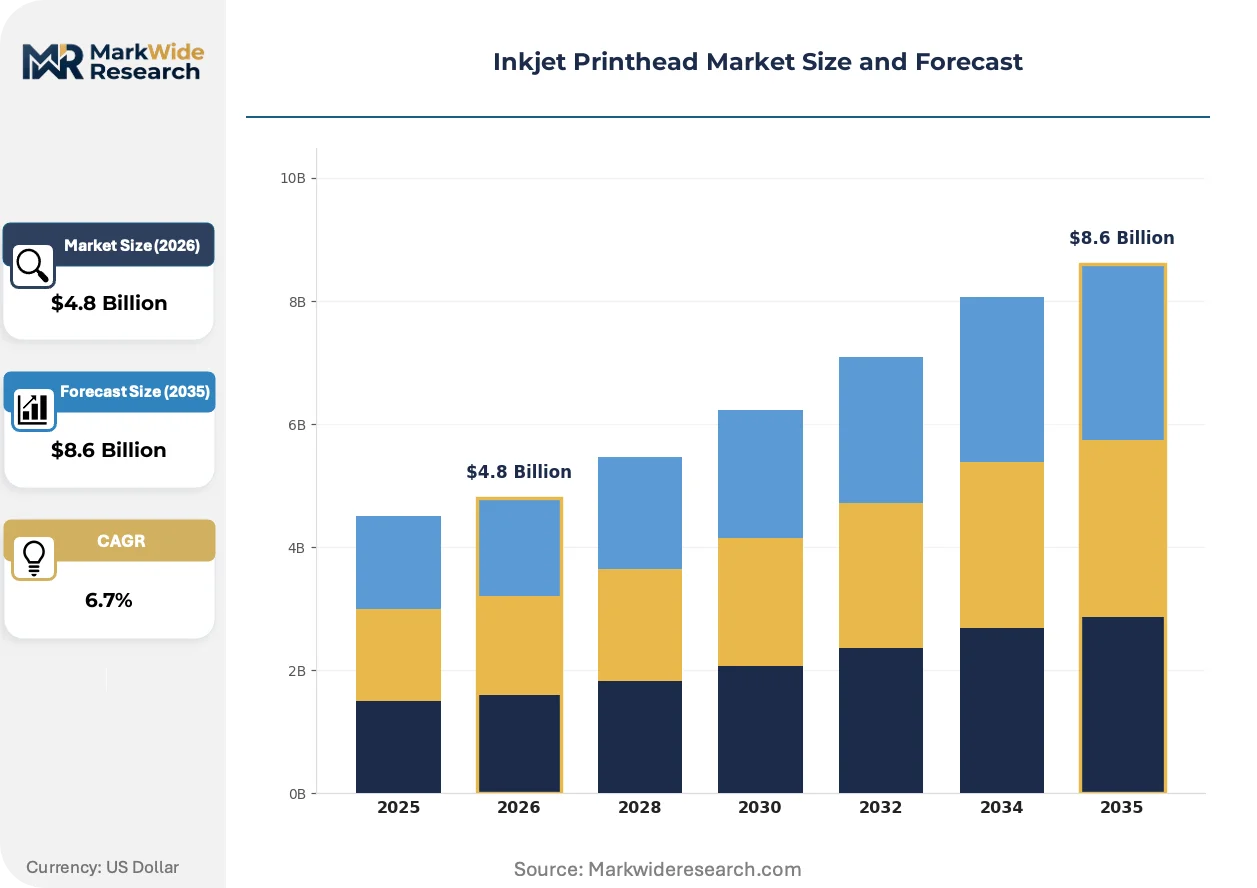
Market Dynamics
REACH chemical restrictions on solvent-based inks are redirecting R&D spending toward aqueous and UV-curable formulations, forcing printhead manufacturers to redesign nozzle architectures for lower-viscosity chemistries.
Growth Catalysts
- EU REACH compliance deadlines:Packaging converters across Germany, France, and Italy are retrofitting solvent-based lines with aqueous-capable printheads to meet volatile organic compound thresholds. This hardware refresh cycle sustains replacement demand.
- Short-run corrugated packaging:E-commerce fulfillment centers in Japan and coastal China are adopting single-pass inkjet for variable-data box printing, compressing minimum order quantities from thousands to hundreds of units.
- Piezoelectric MEMS fabrication:Advances in silicon micromachining from Japanese and German equipment suppliers are extending printhead lifespans beyond 5 billion drops per nozzle, reducing total cost of ownership for 24/7 industrial operations.
Market Restraints
- Precious metal input volatility:Platinum and palladium electrodes in piezoelectric actuators face price swings tied to South African mining output, squeezing gross margins on industrial printhead assemblies.
- Nozzle plate supply concentration:Electroformed nickel aperture plates with sub-20-micron precision concentrate among three Japanese specialty metalwork suppliers, creating single-source vulnerability for high-resolution architectures.
- Thermal drying energy intensity:China's dual carbon goals pressure provincial printing clusters to phase out gas-fired drying tunnels, stranding capital in legacy aqueous inkjet lines that require extended dwell time.
Strategic Opportunities
- Printed electronics integration:Conductive inkjet deposition for flexible circuit boards and antenna traces is absorbing MEMS printhead designs originally developed for graphics, opening semiconductor-adjacent revenue pools.
- India packaging modernization:Food and pharmaceutical labeling regulations from FSSAI and CDSCO are mandating serialized track-and-trace codes, creating first-time demand for industrial inkjet in a market historically dominated by analog flexography.
- UV-LED curing convergence:Wavelength-tuned UV-LED systems matched to photoinitiator chemistry are enabling instant curing on heat-sensitive films, unlocking flexible packaging applications previously blocked by thermal substrate damage.
Industry Challenges
- MEMS process engineering talent scarcity:Cleanroom fabrication expertise for piezoelectric thin-film deposition concentrates among veterans of Japanese and German semiconductor tool suppliers, constraining new entrant capacity expansion.
- Ink-printhead certification timelines:Each new ink chemistry requires 12-18 months of nozzle compatibility testing and waveform optimization, delaying product launches and locking in matched-supplier relationships that resist substitution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inkjet Printhead Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal, Piezoelectric, Continuous Inkjet, Drop-on-Demand Technology: UV-Curable, Solvent-Based, Aqueous, Dye-Based End User: Commercial Printing, Packaging, Textile, Electronic Manufacturing Application: Labeling, Signage, 3D Printing, Decorating |
| Companies Covered | Epson, Kyocera, Fujifilm, Canon, Toshiba Tec, Konica Minolta, Ricoh, SII Printek, Xaar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inkjet Printhead Market Shifts & Advancements
Silicon MEMS processes are migrating from graphics toward functional deposition, while regulatory chemical restrictions and buyer consolidation are compressing supplier margins and forcing architectural unification across regional product lines.
Drop-on-Demand piezoelectric printheads with variable droplet volume control are absorbing thermal inkjet's historical cost advantage in office and light production environments. Commercial print facilities in the United States facing EPA National Emission Standards for Hazardous Air Pollutants are migrating thermal systems to piezoelectric architectures to eliminate volatile organic compound exposure from heated nozzle plates. This technology transition is compressing the addressable market for thermal actuation outside consumer photo printing.
Japan's METI next-generation manufacturing standards are subsidizing domestic producers advancing 1,200-dpi printhead integration for printed circuit board fabrication. These subsidies accelerate depreciation schedules for capital equipment purchases, lowering effective investment hurdles for electronics manufacturers qualifying inkjet for solder mask and legend printing. Korean and Taiwanese PCB fabricators are responding by qualifying Japanese printhead platforms to maintain export eligibility under Japan-origin supply chain requirements.
Brand owners in cosmetics and premium food are unbundling printhead service contracts from hardware procurement, forcing OEMs to compete on per-print operational expenditure rather than upfront capital cost. European packaging converters now benchmark total cost per thousand impressions across competing architectures, compressing supplier pricing power and accelerating third-party ink compatibility verification. This buying pattern shift is most visible in German and Benelux folding carton operations where short-run personalization has become standard.
Inkjet Printhead Market Segmentation
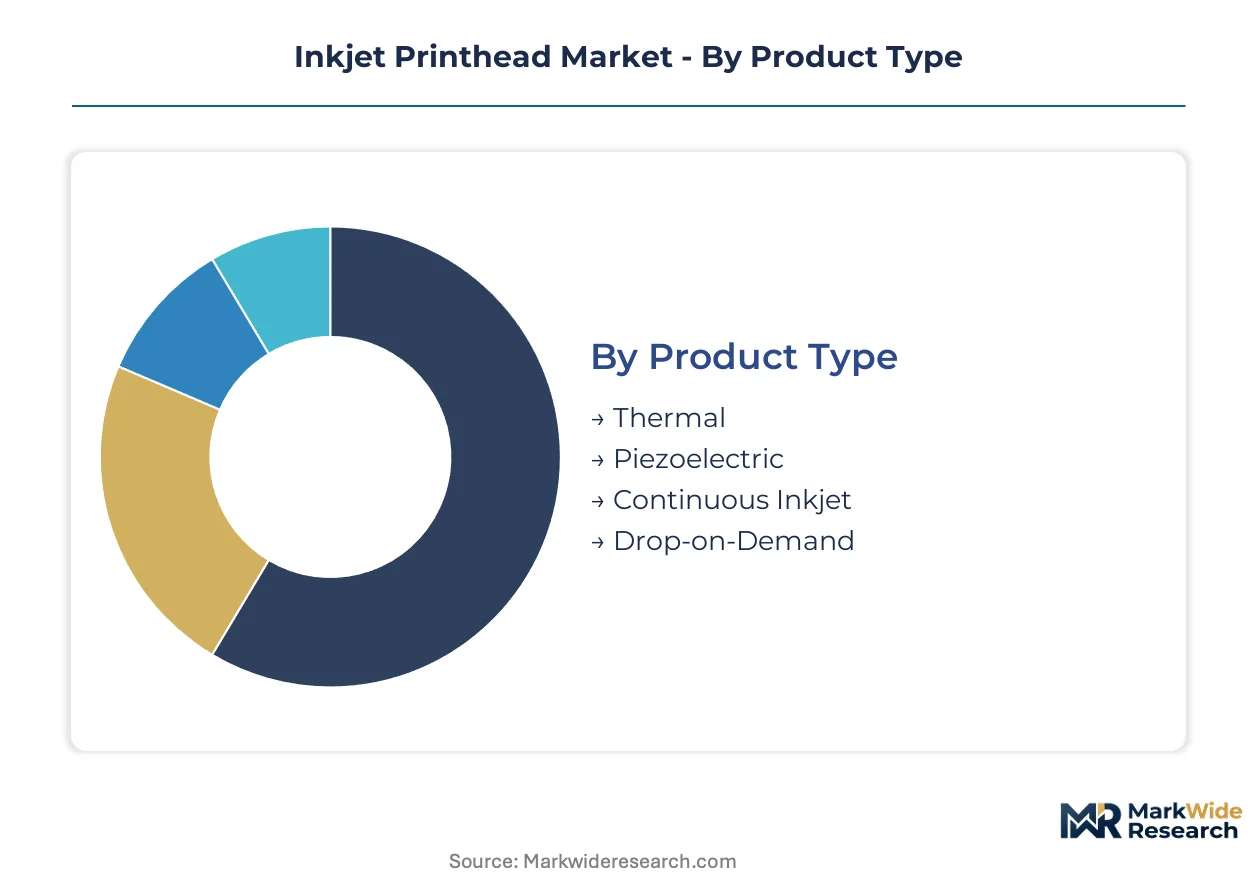
Inkjet printhead architectures diverge sharply across fluid chemistry, actuation physics, and duty-cycle intensity. Segment boundaries determine which suppliers control nozzle design, waveform electronics, and recurring ink revenue streams.
Product Type:
Customization intensity spans from commodity thermal cartridges to application-specific piezoelectric assemblies with proprietary MEMS stacks.
- Thermal:Resistive heating elements vaporize ink to generate bubble pressure, constraining fluid choice to aqueous formulations with precise thermal properties. Demand concentrates in consumer photo printing and low-volume office environments where cartridge economics override nozzle longevity concerns.
- Piezoelectric:Ceramic actuators deform under electric field to eject droplets without thermal stress, accommodating UV-curable, solvent, and high-viscosity functional inks. Japanese and German industrial clusters drive specification requirements for 24/7 corrugated and ceramic decoration lines.
- Continuous Inkjet:Pressurized recirculating loops enable high-speed marking on irregular surfaces. Demand persists in beverage bottling and cable coding where throw distance matters more than resolution.
- Drop-on-Demand:Valve-actuated or piezoelectric firing eliminates continuous recirculation, cutting fluid waste in short-run packaging and textile workflows.
Most installed capacity flows through Piezoelectric architectures. Expansion is steepest in Drop-on-Demand as packaging converters retrofit solvent lines for aqueous and UV-curable compliance.
Technology:
Cost tier stratification separates premium UV-curable systems from economy aqueous alternatives, with solvent formulations caught in regulatory transition.
- UV-Curable:Photoinitiator chemistry enables instant polymerization under LED arrays, eliminating thermal drying tunnels. Premium flexible packaging lines in Germany and coastal China specify matched printhead-LED systems for heat-sensitive films.
- Solvent-Based:Aggressive organic carriers penetrate uncoated vinyl and banner substrates. REACH and EPA National Emission Standards for Hazardous Air Pollutants are forcing capital retirement across European and US wide-format operations.
- Aqueous:Water-based pigments and dyes serve coated papers and corrugated boards with minimal ventilation requirements. German folding carton converters favor aqueous-capable hardware to preempt ECHA enforcement actions.
- Dye-Based:Molecular colorants dissolve completely in carrier fluid, delivering gamut breadth for photographic reproduction and proofing applications.
UV-Curable commands the highest unit economics per printhead. Aqueous is gaining share fastest as regulatory deadlines accelerate hardware replacement cycles.
End User:
Application maturity separates established commercial print from emerging electronics fabrication, with packaging serving as the volume bridge.
- Commercial Printing:Transactional documents, marketing collateral, and book production. German and Japanese print service providers consolidate onto single-pass inkjet to compress turnaround times against digital competition.
- Packaging:Corrugated boxes, flexible films, and folding cartons with variable-data serialization. E-commerce fulfillment centers in Japan and coastal China drive single-pass adoption for lot-size-one production.
- Textile:Direct-to-garment and roll-to-roll fabric printing. Digital displacement of rotary screen printing accelerates in Italian and Turkish fashion manufacturing clusters.
- Electronic Manufacturing:Solder mask deposition, legend printing, and conductive trace patterning. Japanese PCB fabricators qualify 1,200-dpi printheads under METI subsidy programs for next-generation manufacturing standards.
Packaging absorbs the greatest installed base. Electronic Manufacturing is climbing the fastest as semiconductor-adjacent deposition techniques migrate inkjet into functional materials.
Application:
Volume concentration versus margin opportunity divides high-throughput labeling from developmental 3D deposition.
- Labeling:Pressure-sensitive, shrink-sleeve, and in-mold labels with serialized track-and-trace codes. Indian pharmaceutical and food packaging modernization under CDSCO and FSSAI mandates is creating first-time industrial inkjet demand.
- Signage:Wide-format graphics for retail, events, and transportation. UV-curable flatbed systems dominate German and Benelux point-of-purchase production.
- 3D Printing:Binder jetting and material jetting for sand casting molds and polymer prototypes. Build-chamber scale and powder handling complexity constrain printhead supplier participation.
- Decorating:Direct-to-shape ceramic, glass, and wood surface ornamentation. Italian ceramic tile manufacturers specify piezoelectric arrays for glaze patterning at kiln-feed speeds.
Labeling carries the heaviest throughput volume. 3D Printing is expanding most quickly as binder jetting scales toward production metal casting applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEMS fabrication veterans cluster in Japanese and German semiconductor tool corridors, anchoring regional competitive advantage through cleanroom expertise concentration.
Germany
Folding carton converters in Baden-Württemberg and Bavaria retrofit aqueous-capable printheads to preempt ECHA REACH enforcement on volatile organic compounds. The KBA enforces stringent emission thresholds for commercial print facilities. Stuttgart and Mannheim industrial zones concentrate hardware refresh demand from packaging modernization programs.
Japan
PCB fabricators in Kanto and Kansai qualify 1,200-dpi printheads for solder mask deposition under METI next-generation manufacturing subsidies. METI accelerates depreciation schedules for capital equipment purchases. Nagoya and Osaka industrial corridors anchor domestic demand for high-resolution electronics fabrication integration.
China
Coastal manufacturing zones in Guangdong and Jiangsu provinces phase out gas-fired drying tunnels under MEE dual carbon goals. The MEE pressures provincial printing clusters to abandon energy-intensive thermal processes. Shenzhen and Suzhou fulfillment centers adopt single-pass inkjet for variable-data corrugated packaging at e-commerce scale.
United States
Commercial print facilities migrate thermal systems to piezoelectric architectures to eliminate volatile organic compound exposure from EPA National Emission Standards for Hazardous Air Pollutants. The EPA constrains solvent-based inkjet operations in wide-format and commercial environments. Midwestern and Northeastern print service provider consolidation drives single-pass adoption for transactional document compression.
India
Pharmaceutical and food packaging modernization under CDSCO and FSSAI serialized track-and-trace mandates creates first-time industrial inkjet demand. FSSAI labeling regulations mandate lot-level coding for domestic and export markets. Maharashtra and Gujarat pharmaceutical clusters drive qualification of drop-on-demand systems for primary packaging lines.
Inkjet Printhead Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across printhead architectures. Japanese and German equipment suppliers dominate piezoelectric MEMS fabrication through captive cleanroom capacity. Three strategic archetypes prevail: diversified imaging conglomerates with captive semiconductor fabrication, specialized MEMS foundries serving external printhead designers, and UV-curable ink formulators with matched hardware strategies. Competitive intensity centers on waveform electronics integration and geographic expansion into Indian and Southeast Asian packaging markets.
Among diversified imaging conglomerates, Epson and Canon exemplify archetypes with vertical control over MEMS fabrication and end-system integration. Fujifilm occupies a distinct position bridging proprietary UV-curable chemistry with matched printhead architectures. Xaar represents the specialist MEMS foundry model, supplying nozzle assemblies to system integrators without downstream equipment competition. Each anchors different competitive vectors: captive fabrication scale, chemistry-hardware lock-in, or modular component supply flexibility.
| Leading Market Players |
|---|
| Epson |
| Kyocera |
| Fujifilm |
| Canon |
| Toshiba Tec |
| Konica Minolta |
| Ricoh |
| SII Printek |
| Xaar |
| Others |
Supply & Pricing Matrix
Packaging converters in Germany and coastal China concentrate procurement volume for aqueous and UV-curable printhead systems, anchoring contract-based long-term offtake pricing with embedded service bundling. Their consolidated buying power compresses supplier margins while favoring vendors offering waveform optimization and preventive maintenance as recurring revenue streams.
Pricing Analysis
Bundled hardware-service contracts dominate premium flexible packaging lines, while unbundled transactional procurement persists in standard corrugated retrofit applications. Three-tier pricing structure across premium, standard, and economy levels separates matched ink-printhead systems from third-party compatible alternatives and commodity thermal cartridges. Cost compression in the standard tier intensifies because European REACH compliance deadlines accelerate hardware replacement cycles. Price-sensitive mid-volume packaging converters in Italy and Poland benchmark total cost per thousand impressions, while least-sensitive electronics fabricators in Japan absorb premium positioning for 1,200-dpi MEMS integration.
Supply Chain Analysis
Cleanroom fabrication expertise concentrates in Nagoya-Osaka corridors and Stuttgart-Mannheim industrial zones, constraining capacity expansion for piezoelectric thin-film deposition. Electroformed nickel aperture plates draw from three Japanese specialty metalwork suppliers, while platinum and palladium electrodes hinge on South African mining output. Single-source vulnerability for sub-20-micron precision nozzle plates creates structural risk across high-resolution architectures. Distribution runs through captive OEM channels for integrated systems and authorized component distributors for modular assemblies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU REACH volatile organic compound thresholds and China's MEE dual carbon goals force sustained capital redeployment into compliant aqueous and UV-curable hardware platforms.
For Market Incumbents: Lock in recurring revenue through ink-printhead certification programs that extend waveform optimization lock-in periods beyond standard 12-18 month testing cycles. Deepen backward integration into MEMS fabrication capacity in Japanese and German cleanroom corridors to defend against emerging MEMS foundry competitors from Taiwan and South Korea.
For New Entrants and Emerging Players: Capture first-time industrial inkjet demand in Indian pharmaceutical and food packaging clusters where CDSCO and FSSAI serialized track-and-trace mandates outpace domestic supplier qualification. Target modular piezoelectric nozzle assemblies for system integrators seeking alternatives to captive OEM supply, leveraging 18-month certification timelines as a competitive moat against faster-follower replication.
For Investors and Strategic Acquirers: Diversified imaging conglomerates with captive semiconductor fabrication represent the most active acquirer in this space, seeking waveform electronics integration capabilities. Long-term viability centers on chemistry-hardware lock-in durability and geographic expansion into Southeast Asian packaging markets. Monitor Indian regulatory enforcement intensity on pharmaceutical serialization as an inflection indicator for regional demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Fabrication Capacity Expansion | Captive cleanroom investment in Nagoya and Stuttgart secures nozzle supply continuity for 24/7 industrial lines. |
| UV-Curable Ink Chemistry Lock-In | Proprietary photoinitiator formulations matched to LED wavelength specifications create recurring revenue streams. |
| Indian Market Qualification Push | Early certification under CDSCO and FSSAI mandates establishes first-mover position in pharmaceutical serialization. |
| Waveform Electronics Integration | Embedded drive electronics differentiation separates premium piezoelectric architectures from commodity alternatives. |
| Service Contract Unbundling Response | Operational expenditure pricing models align vendor incentives with converter total cost per impression metrics. |
Research Methodology
Direct dialogue with MEMS fabrication engineers, packaging converter procurement directors, ink formulation chemists, and electronics manufacturing equipment planners grounded qualitative assessment. Secondary validation drew from EPA National Emission Standards filings, ECHA REACH substance restriction updates, METI subsidy program disclosures, and customs records of electroformed nickel aperture plate trade flows. Bottom-up printhead shipment estimates and top-down packaging capital expenditure analysis were triangulated against regional regulatory deadline calendars.
Bottom-up modeling aggregated nozzle assembly volumes by actuation physics and fluid chemistry across German, Japanese, Chinese, and Indian industrial clusters. Segmentation dimensions spanned product type, technology tier, end-use vertical, and application maturity. Growth trajectories were derived from replacement cycle timing tied to named regulatory enforcement windows and from electronics fabrication adoption curves for printed circuit board deposition. Forecast inputs incorporated precious metal price volatility coefficients and cleanroom fabrication labor availability indices.
Underlying measurement precision varies by segment; established commercial print and packaging applications carry tighter precision than emerging electronics manufacturing and 3D printing deposition. Forecasts reflect assumptions regarding regulatory enforcement consistency and MEMS process engineering talent mobility. Practitioners should monitor ECHA substance restriction expansion proposals and MEE provincial carbon intensity audits for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Automated Document Inserter (ADI) Market
Printing Technology
Nordic Commercial Printing Market
Printing Technology
Digital Presses Market
Printing Technology
Global Cloud Printing Services Market
Printing Technology
Photo Printing Market
Printing Technology
Global Barcode Printer Market
Printing Technology
Digital Printing on Wood Market
Printing Technology
Digital Paper System Market
Printing Technology
Commercial Printing Outsourcing Market
Printing Technology
Industrial Inkjet Printer Market
Printing Technology
Print Equipment Market
Printing Technology
Europe Commercial Printing Market
Printing Technology
Digital Franking Machine Market
Printing Technology
Book Printing Service Market
Printing Technology
Print on Demand Market
Printing Technology
Cloud Print Market