
 Video Converter Software Market | 2026-2036
Video Converter Software Market Size, Share, and Industry Trends Forecast 2026-2036
Video Converter Software Market Analytics
Enterprise procurement among streaming platforms and broadcast networks is restructuring buyer concentration in the video converter software space. Adobe Media Encoder leverages deep integration with creative cloud workflows to sustain enterprise retention. Wondershare UniConverter anchors its position through aggressive localization across Asian markets. FFmpeg competes as the open-source backbone that powers commercial derivatives across the industry.
Video converter software encompasses applications that transcode digital video between container formats and codecs, typically supporting H.264, H.265, AV1, and ProRes with bitrates adjustable from sub-1 Mbps streaming profiles to uncompressed master outputs for professional post-production pipelines. Desktop software dominates current revenue pools due to codec breadth and offline processing reliability, while cloud-based deployment represents the fastest-expanding segment as studios distribute rendering across remote teams. Subscription-based licensing captures recurring value from content creators who require continuous format updates, though on-premise installations retain stronghold status in media enterprises handling sensitive pre-release assets.
The FCC governs broadcast standards that shape format requirements for US terrestrial and cable distribution, while the EU AI Act imposes algorithmic transparency obligations on AI-enhanced upscaling and frame interpolation features. ISO/IEC 23008 and MPEG standards further constrain codec interoperability, creating compliance costs that favor established vendors with dedicated certification resources. Stakeholders must monitor whether emerging royalty-free codecs like AV1 displace licensed alternatives and how sovereign data localization rules reshape cloud conversion architectures.
Market Dynamics
The video converter software market is being fundamentally restructured by the mandatory integration of AI-enhanced upscaling and frame interpolation capabilities, which now require algorithmic transparency under the EU AI Act and are forcing vendors to rebuild their processing pipelines from the codec layer upward.
Growth Catalysts
- EU AI Act transparency mandates:The regulation's algorithmic disclosure requirements are accelerating vendor investment in explainable AI features for upscaling workflows, creating competitive differentiation for compliant products.
- Content creator procurement:Independent creators operating across YouTube, TikTok, and streaming platforms are driving subscription licensing volume through continuous format update demands.
- AV1 codec maturation:Royalty-free encoding is reducing licensing friction for streaming platforms and enabling broader deployment of high-efficiency compression without H.265 patent pool obligations.
Market Restraints
- Codec patent concentration:H.265 and VVC licensing through Access Advance and MPEG LA creates recurring cost uncertainty for commercial vendors, particularly affecting mid-tier software providers.
- Cloud infrastructure dependency:Rendering workload migration to AWS, Azure, and Google Cloud platforms concentrates vendor margin pressure in three hyperscaler ecosystems.
- GDPR data localization:Cross-border video processing for EU clients requires regional cloud instance deployment, adding fixed cost overhead for SaaS providers.
Strategic Opportunities
- India post-production expansion:Mumbai and Hyderabad studio clusters are scaling outsourced conversion services for Hollywood and streaming clients, creating demand for localized enterprise licensing.
- AI-codec convergence:Neural network-based compression combined with traditional block coding is opening new efficiency tiers for 8K streaming workflows.
- FCC broadcast modernization:NextGen TV (ATSC 3.0) rollout is mandating new format support for US terrestrial distributors, requiring converter software updates.
Industry Challenges
- Interoperability certification backlog:ISO/IEC 23008 compliance testing for new codecs faces laboratory capacity constraints, delaying product release timelines.
- Legacy hardware codec lock-in:Post-production facilities with substantial ProRes and DNxHD infrastructure resist migration to newer encoding pipelines despite efficiency gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Converter Software Market |
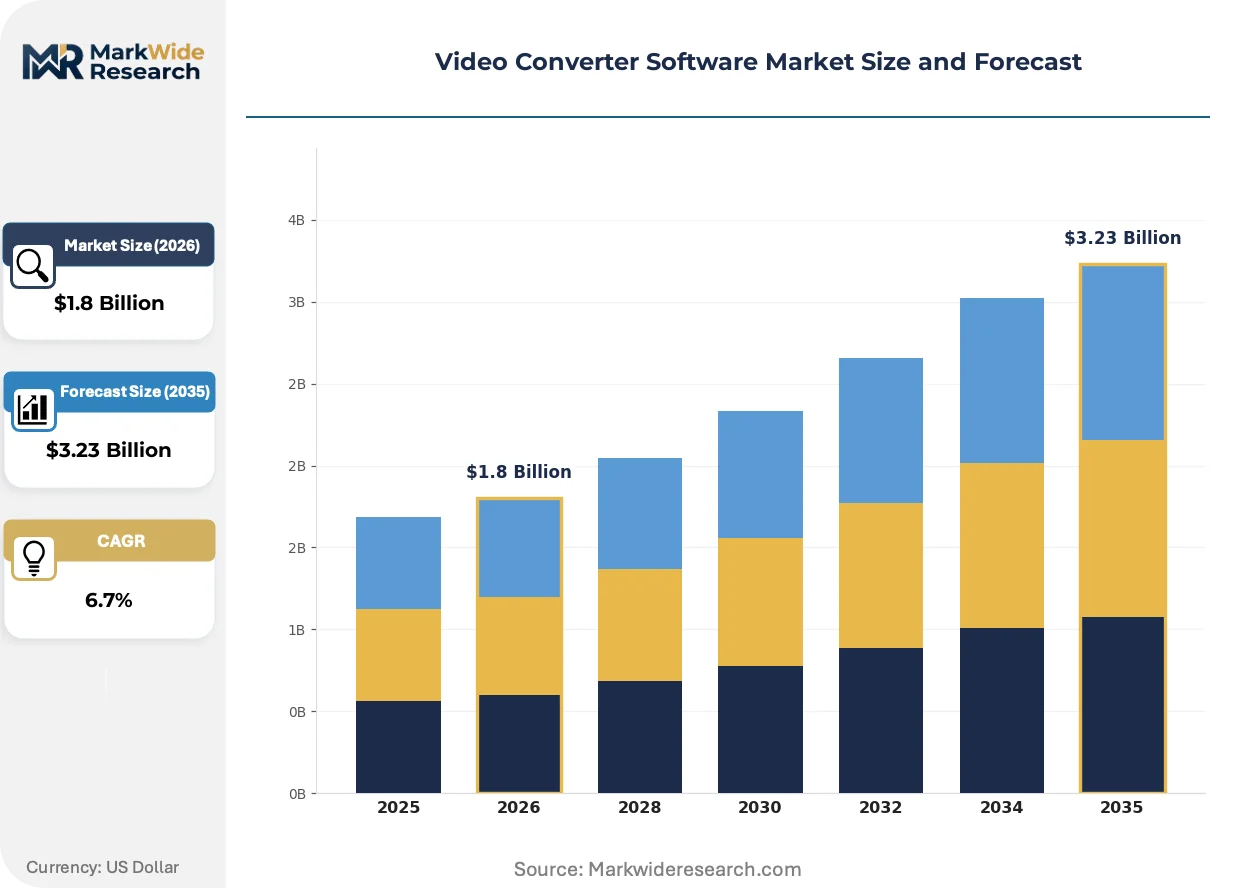
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Software, Online Tools, Mobile Applications, Plugin Extensions End User: Individual Users, Content Creators, Enterprises, Educational Institutions Deployment Type: On-Premise, Cloud-Based, Hybrid, Subscription-Based Features: File Format Support, Batch Conversion, Editing Tools, Compression Options |
| Companies Covered | Winxvideo AI, Aiseesoft Video Converter Ultimate, HandBrake, WaveSpeed Video Converter, Adobe Media Encoder, FFmpeg, VideoProc Converter AI, Zamzar, Wondershare UniConverter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Converter Software Market Evolving Landscape
Codec evolution and regulatory compliance are converging to reshape product architecture, with vendors racing to embed transparent AI processing while navigating patent and data governance obligations.
AV1 encoding is overtaking H.265 in streaming platform roadmaps due to royalty-free distribution economics. Netflix, YouTube, and Disney+ have deployed AV1 for mobile and 4K tiers, compressing the addressable premium for licensed codec vendors and forcing HEVC-focused providers to diversify their value propositions toward professional color grading and mastering features.
The EU AI Act's algorithmic transparency obligations are restructuring how vendors develop upscaling modules. Software providers must now document training data provenance and decision logic for frame interpolation, increasing development overhead but creating compliance-based switching costs that favor established vendors with dedicated legal and certification resources over emerging competitors.
Subscription fatigue among independent creators is fragmenting licensing models across the United States. Perpetual license demand is resurging among YouTubers and podcasters who process episodic content in batch cycles rather than continuous workflows, compressing recurring revenue predictability for vendors and forcing hybrid pricing experiments that unbundle codec updates from core conversion functionality.
Video Converter Software Market Segmentation
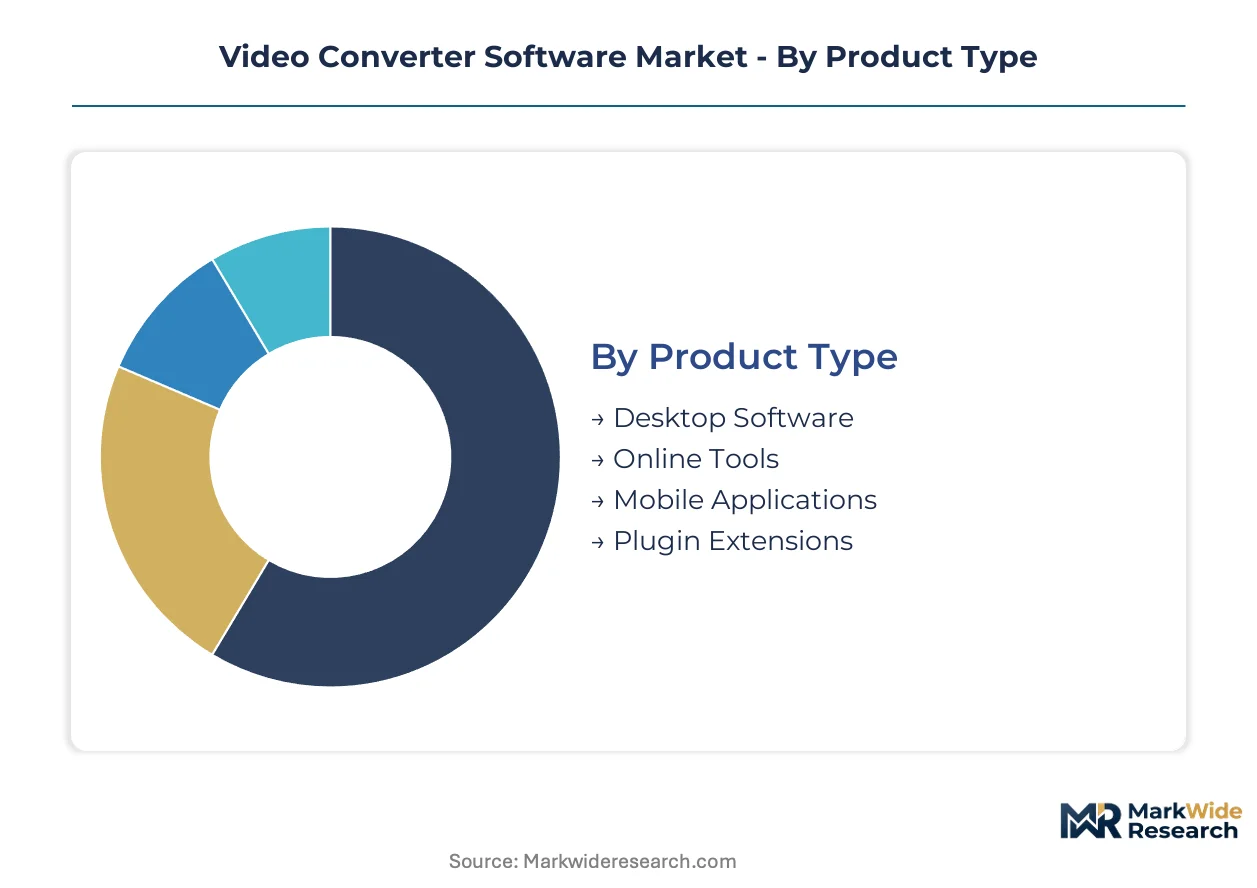
Video converter software procurement cycles vary sharply across deployment modes and user sophistication tiers. Upgrade decisions hinge on codec roadmap alignment, AI feature maturation, and regulatory compliance mandates rather than simple version increments.
Product Type:
Replacement cycles diverge dramatically between installed desktop suites and ephemeral online tools, with plugin architectures forcing the most frequent compatibility-driven upgrades.
- Desktop Software:Full-featured applications installed on local workstations with direct hardware acceleration access. Post-production studios in the United States and Germany anchor demand here, constrained by proprietary codec licensing costs and the need for offline processing reliability with sensitive pre-release assets.
- Online Tools:Browser-based conversion services requiring no local installation. Content creators across TikTok and YouTube ecosystems in Japan drive fastest uptake, though GDPR data localization requirements in Europe compress margin structures for SaaS providers operating cross-border.
- Mobile Applications:Native iOS and Android converters optimized for on-device processing. Social media native creators in India represent concentrated demand.
- Plugin Extensions:Integration modules for Adobe Creative Cloud, DaVinci Resolve, and Final Cut Pro. Broadcast network technical departments in the United States mandate these for workflow continuity.
Desktop Software sits at the top of the volume ranking, with Online Tools climbing the fastest.
End User:
Customer type determines pricing tolerance and feature depth requirements more than any other segmentation axis, with procurement authority residing in fundamentally different organizational functions.
- Individual Users:Occasional converters handling personal media archives and device compatibility fixes. Price sensitivity here is extreme, with perpetual license preference over subscription models.
- Content Creators:Professional YouTubers, podcasters, and streamers requiring continuous format updates. This segment in the United States and Japan exhibits highest subscription renewal rates but growing fatigue with recurring fees.
- Enterprises:Streaming platforms, broadcast networks, and post-production facilities. Netflix, Disney+, and terrestrial distributors in Germany demand enterprise licensing with dedicated support tiers and custom codec pipelines.
- Educational Institutions:Universities and technical colleges training next-generation editors. Volume licensing in India and Japan concentrates here, constrained by budget procurement cycles.
Enterprises command the highest revenue per seat, with Content Creators expanding most quickly.
Deployment Type:
Architecture decisions now pivot on data sovereignty obligations and rendering workload distribution rather than simple capex-opex tradeoffs.
- On-Premise:Local server installations with complete data control. Media enterprises in Germany and Japan handling pre-release theatrical content mandate this architecture due to leak risk intolerance.
- Cloud-Based:Fully managed SaaS conversion with elastic compute scaling. AWS, Azure, and Google Cloud infrastructure dependency creates margin pressure for vendors, though Indian post-production outsourcers in Mumbai and Hyderabad drive fastest adoption.
- Hybrid:Split processing with sensitive operations local and burst rendering cloud-distributed. This architecture gains traction among mid-tier studios in the United States seeking compliance-performance balance.
- Subscription-Based:Recurring license models with continuous feature updates. Content creators dominate this segment, though per-episode batch processors increasingly resist the model.
On-Premise retains highest absolute revenue, with Cloud-Based gaining share fastest.
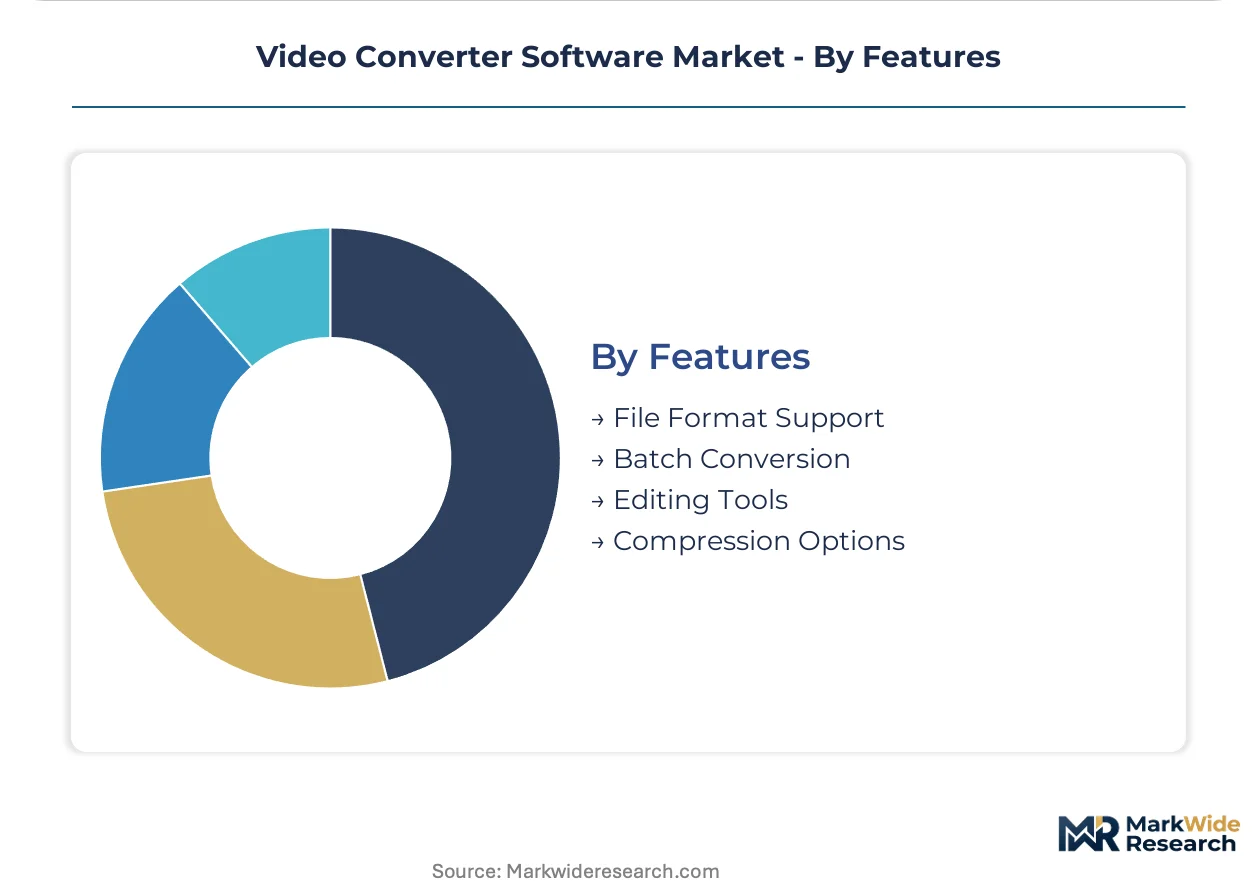
Features:
Capability bundling now separates professional-grade offerings from consumer tools, with AI-enhanced functions commanding premium positioning.
- File Format Support:Breadth of container and codec compatibility from legacy AVI to emerging AV1. AV1 maturation is displacing H.265 in streaming platform roadmaps, compressing value for licensed codec vendors.
- Batch Conversion:Automated queue processing for high-volume workflows. Post-production facilities with ProRes infrastructure in the United States depend on this for dailies and proxy generation.
- Editing Tools:Integrated trimming, color correction, and audio synchronization. Educational institutions in India prioritize these features for curriculum integration.
- Compression Options:Bitrate control and quality optimization algorithms. EU AI Act transparency mandates now apply to AI-enhanced compression modules, forcing documentation of training data provenance.
File Format Support anchors procurement decisions, with Compression Options climbing the fastest due to AI-codec convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States enterprise licensing dwarfs German procurement volume, yet Tokyo-based content creators sustain higher per-seat renewal rates than either market. Geographic demand patterns diverge sharply between studio-heavy metros and distributed creator economies.
United States
Netflix and Disney+ anchor enterprise demand for custom codec pipelines and dedicated support tiers. FCC NextGen TV mandates reshape format requirements for terrestrial distributors. Los Angeles post-production clusters drive concentrated licensing for ProRes and DNxHD workflows.
Germany
Broadcast networks and streaming platforms anchor enterprise procurement with leak-risk intolerance for pre-release assets. EU AI Act algorithmic transparency obligations force documentation of training data provenance for upscaling modules. Berlin and Munich studio clusters mandate on-premise installations for sensitive theatrical content.
Japan
TikTok and YouTube native creators sustain highest subscription renewal rates through continuous format update demands. METI standards influence codec interoperability requirements for domestic distribution. Tokyo's Shibuya and Shinjuku creator districts concentrate mobile application uptake.
India
Mumbai and Hyderabad post-production outsourcers scale conversion services for Hollywood clients, driving cloud-based deployment adoption. TRAI regulations shape data localization requirements for cross-border processing. Bangalore educational institutions anchor volume licensing for curriculum-integrated editing tools.
United Kingdom
Independent production houses and streaming platform technical departments split procurement between subscription and perpetual models. GDPR compliance costs compress margin structures for SaaS providers operating EU-UK data flows. London's Soho post-production district retains installed desktop suite preference for offline reliability.
Video Converter Software Market Competitive Landscape
United States vendors anchor the premium enterprise tier; Chinese specialists hold the mass-market conversion segment through aggressive localization. Market structure tilts toward consolidation at the top with fragmented mid-tier competition. Three archetypes dominate: creative cloud-integrated suites, open-source derivation engines, and mobile-first creator tools. Competitive moves concentrate on workflow integration partnerships and geographic expansion through language localization.
Within the creative cloud-integrated tier, Adobe Media Encoder exemplifies enterprise retention through deep workflow embedding. Wondershare UniConverter occupies a position among Asian-market specialists with aggressive localization strategies. FFmpeg represents the open-source archetype that powers commercial derivatives across the industry without direct licensing revenue.
| Leading Market Players |
|---|
| Winxvideo AI |
| Aiseesoft Video Converter Ultimate |
| HandBrake |
| WaveSpeed Video Converter |
| Adobe Media Encoder |
| FFmpeg |
| VideoProc Converter AI |
| Zamzar |
| Wondershare UniConverter |
| Others |
Value Network & Pricing Analysis
Enterprise streaming platforms and broadcast networks in the United States anchor procurement volume and compress vendor margins through volume-based SaaS tiering. Their concentrated buying power forces subscription pricing stratification across premium enterprise, standard professional, and economy creator tiers.
Pricing Analysis
Capacity additions in cloud infrastructure regions are reshaping price floors for SaaS conversion tiers. Three-tier pricing structure across premium enterprise, standard professional, and economy creator levels dominates, with differentiation driven by AI feature depth and dedicated support tiers. Pricing pressure stems from hyperscaler compute cost pass-throughs. Individual creators exhibit highest price sensitivity, while German broadcast networks show lowest due to leak-risk intolerance.
Supply Chain Analysis
Software engineering talent availability in India, Poland, and Vietnam shapes development cost structures for vendor R&D centers. Codec licensing draws from Access Advance and MPEG LA patent pools in the United States and Europe, while cloud compute rests on AWS, Azure, and Google Cloud infrastructure. Single-source vulnerability concentrates in hyperscaler dependency. Distribution runs through direct enterprise sales and app marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory complexity into competitive advantage, with the EU AI Act's algorithmic transparency mandates forcing vendor investment in explainable AI pipelines.
For Market Incumbents: Deepen workflow integration with Adobe Creative Cloud and DaVinci Resolve to defend against open-source FFmpeg derivatives eroding mid-market share. Invest in ISO/IEC 23008 certification resources to exploit compliance-based switching costs under EU AI Act mandates. For New Entrants and Emerging Players: Capture India's Mumbai and Hyderabad post-production outsourcers with localized cloud pricing and TRAI-compliant data architectures. Target mobile-first creators in Japan's Shibuya district through TikTok-native format presets and METI-aligned codec support. For Investors and Strategic Acquirers: Creative cloud platform operators are the most active acquirer in this space, seeking conversion modules to deepen workflow embedding. Long-term viability favors vendors with dedicated legal resources for patent pool navigation. Watch AV1 codec adoption rates across Netflix and Disney+ roadmaps as inflection signal for HEVC premium compression value erosion.| Strategic Initiative | Industry Significance |
|---|---|
| AI Transparency Module Development | EU AI Act compliance creates defensible switching costs against unresourced competitors. |
| AV1 Codec Pipeline Integration | Royalty-free encoding reduces Access Advance licensing friction for streaming platform clients. |
| India Cloud Region Expansion | TRAI data localization requirements favor regional instance deployment for post-production outsourcers. |
| Adobe Creative Cloud Partnership | Plugin architecture embedding captures broadcast network technical department procurement authority. |
| Perpetual License Hybrid Launch | Subscription fatigue among YouTube batch processors demands unbundled codec update pricing. |
Research Methodology
Direct dialogue with CTOs at streaming platforms, post-production facility technical directors, IT procurement officers at broadcast networks, and software integration specialists grounded qualitative findings. Secondary validation drew from SEC filings of listed creative software vendors, hyperscaler capex disclosures, FCC regulatory dockets, and EU AI Act implementation guidance. Bottom-up deployment modeling and top-down market sizing triangulated volume estimates.
Segment-level outputs across desktop, online, mobile, and plugin deployment modes, organization size tiers, and regional adoption patterns structured the analytical framework. CAGRs derived from codec roadmap alignment, AI feature penetration curves, and enterprise licensing renewal elasticity. AV1 adoption velocity and EU AI Act compliance cost trajectories fed industry-specific forecast inputs throughout the projection horizon.
Codec patent pool reconfiguration, hyperscaler pricing volatility, and sovereign data localization rule expansion are the dominant revision risks to modeled assumptions. Material deviation in named triggers warrants pause and re-evaluation of vendor margin and competitive positioning projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Product Lifecycle Management Software Market
Software & Services
Performance Management Software Market
Software & Services
Job Description Management Software Market
Software & Services
Construction Equipment Fleet Management Software Market
Software & Services
Global Demand Planning Software Market
Software & Services
Global Architect Software Market
Software & Services
Remote Browser Market
Software & Services
Avionics Software Market
Software & Services
Europe Yacht Management Software Market
Software & Services
Automotive Hypervisor Market
Software & Services
Service Resource Planning (SRP) Saas Solutions Market
Software & Services
Global Data Integration and Integrity Software Market
Software & Services
Exercise and Weight Loss Apps Market
Software & Services
Workstation Software Market
Software & Services
Enterprise Content Management Software Market
Software & Services
Warranty Management Software Market