
 Battery Equalizer Market | 2026-2036
Battery Equalizer Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Equalizer Market Insights
A widening R&D spend gap between semiconductor majors and specialty vendors is reorganizing competitive tiers in battery equalization. Texas Instruments leverages its analog foundry scale to integrate balancing logic with battery management SoCs at wafer level. Nuvation Engineering anchors its position through firmware-intensive architectures tailored to grid-scale storage. Analog Devices competes by extending precision measurement IP from industrial automation into automotive-grade cell monitoring.
A battery equalizer is an electronic circuit or embedded system that redistributes charge among series-connected cells to prevent voltage divergence and capacity fade, typically operating through switched-capacitor networks, inductor-based converters, or dissipative resistor arrays with balancing currents ranging from milliamps to several amps. Its primary purpose is maximizing usable energy throughput and cycle life in multi-cell battery packs. Active equalizers command premium pricing in electric vehicle and stationary storage deployments where efficiency losses from passive dissipation are economically prohibitive. Passive equalizers still occupy substantial volume in cost-constrained consumer electronics where cell counts remain low. Hybrid architectures that blend both approaches are gaining traction in industrial applications requiring configurable trade-offs between speed and energy recovery.
The EU Battery Regulation and ECE R100 type-approval requirements are mandating cell-level state monitoring in traction batteries sold across Europe, directly expanding addressable hardware demand. China's NMPA and GB/T standards enforce thermal runaway propagation testing that presumes functional balancing systems in certified packs. India's BIS adoption of IEC 62660 test protocols for lithium cells is creating compliance-driven pull in emerging manufacturing hubs. Stakeholders must track how evolving UN 38.3 transport rules and regional recycling mandates reshape equalizer durability and material disclosure requirements.
Market Dynamics
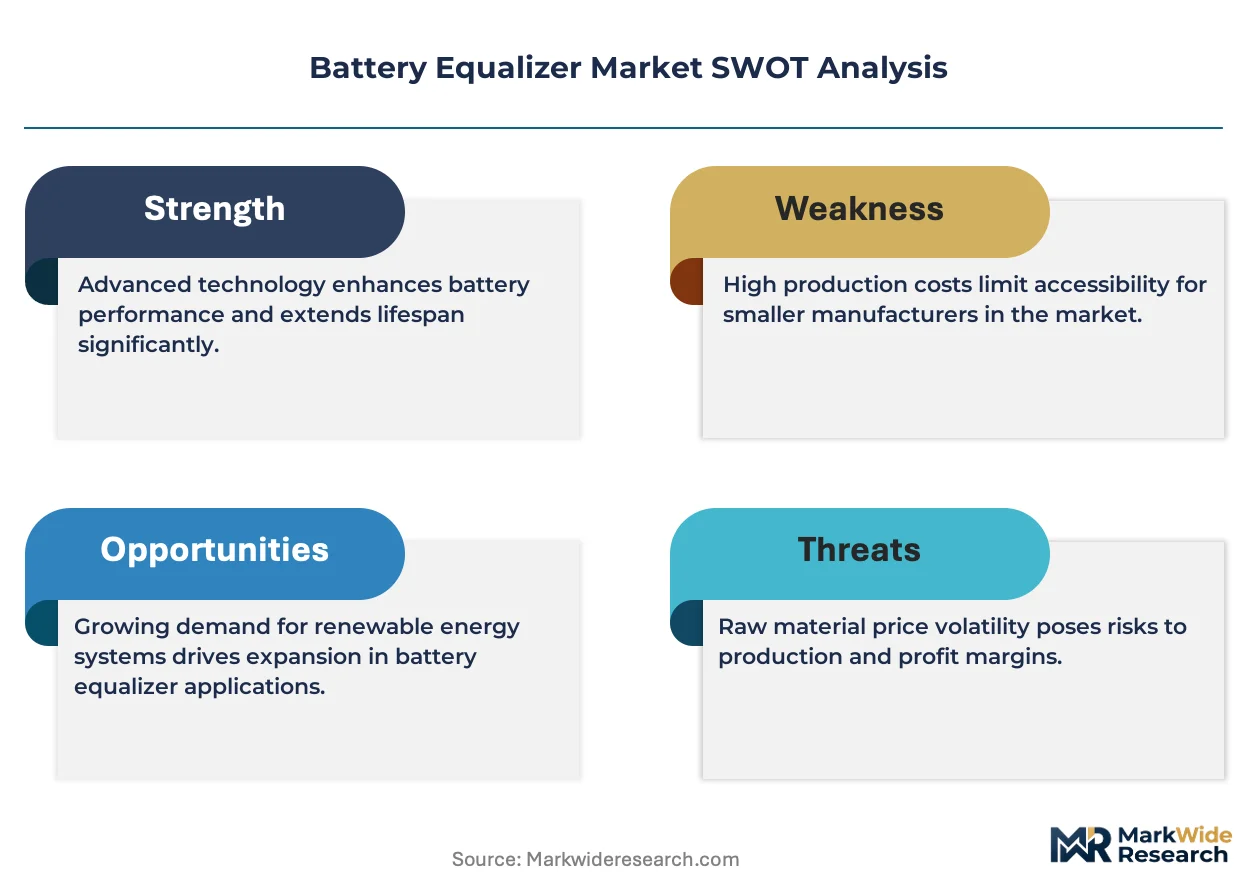
Active balancing architectures are displacing passive resistor-based designs across high-value battery deployments, driven by efficiency mandates and cell-level monitoring requirements embedded in automotive type-approval frameworks.
Growth Catalysts
- EU Battery Regulation cell-monitoring mandates:ECE R100 type-approval requirements for traction batteries sold across Europe are expanding hardware demand for embedded equalization circuits in electric vehicle packs.
- China's GB/T thermal runaway standards:NMPA enforcement of propagation testing protocols presumes functional balancing systems, compelling pack integrators to certify active architectures.
- Stationary storage scale-up:Grid-scale lithium-ion deployments for renewable firming are accelerating adoption of inductor-based converter topologies that recover energy during cell redistribution.
Market Restraints
- Silicon carbide MOSFET supply concentration:Foundry capacity for wide-bandgap semiconductors enabling high-frequency balancing converters remains concentrated among Taiwanese and Korean suppliers.
- Passive equalizer cost floor:Dissipative resistor arrays maintain substantial volume in consumer electronics where cell counts stay low and efficiency losses are economically tolerable.
- UN 38.3 transport certification friction:Evolving lithium battery shipping rules are extending qualification timelines for equalizer-integrated pack designs destined for air freight.
Strategic Opportunities
- India BIS IEC 62660 adoption:India's alignment with international lithium cell test protocols is creating compliance-driven demand in emerging manufacturing hubs around Chennai and Pune.
- Hybrid architecture convergence:Configurable systems blending switched-capacitor speed with inductor-based energy recovery are penetrating industrial applications requiring tunable speed-efficiency trade-offs.
- Second-life battery repurposing:End-of-life electric vehicle packs diverted to stationary storage are driving retrofit equalizer demand for mismatched cell populations.
Industry Challenges
- Firmware-architecture skill scarcity:Battery management SoC programming for predictive balancing algorithms requires embedded systems expertise concentrated among semiconductor vendors and tier-1 automotive suppliers.
- Multi-standard certification timelines:Pack manufacturers must sequence GB/T, ECE R100, and UN 38.3 approvals, compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Equalizer Market |
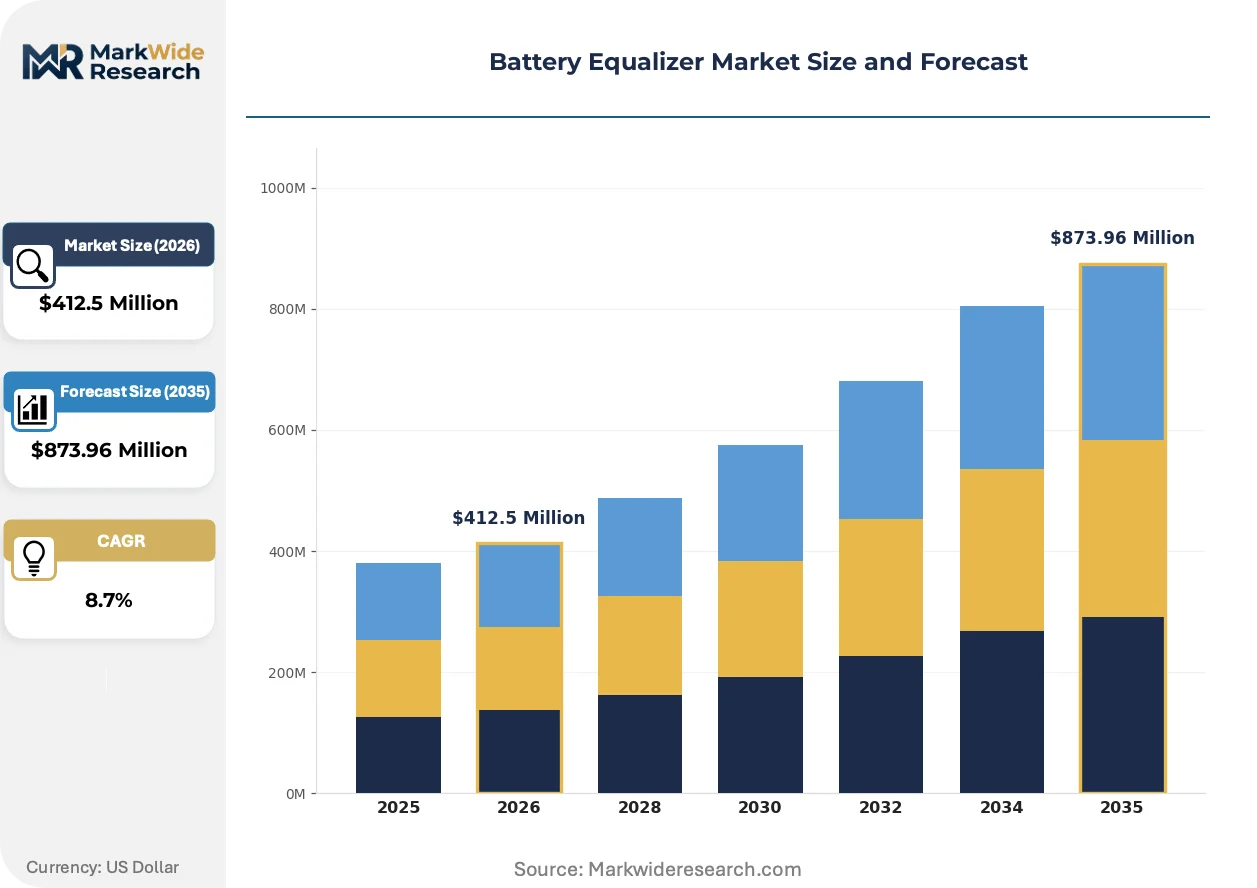
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Equalizers, Passive Equalizers, Hybrid Equalizers, Digital Equalizers End User: Electric Vehicles, Renewable Energy Systems, Consumer Electronics, Industrial Applications Technology: Voltage Balancing, Current Sharing, State of Charge Monitoring, Power Management Distribution Channel: Direct Sales, Wholesalers, Online Retailers, Distributors |
| Companies Covered | Texas Instruments, Nuvation Engineering, Analog Devices, Renesas Electronics, Balancer Tech, PowerSmart Innovations, Fluke Corporation, Megger Group Limited, Cadex Electronics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Equalizer Market Trends and Innovations
Wafer-level integration of balancing logic with precision analog front-ends is compressing board area and component count, while regulatory pressure on cell monitoring is hardening hardware requirements across automotive and stationary storage verticals.
Magnetics-integrated gallium nitride power stages are miniaturizing inductor-based active equalizer footprints. Electric vehicle inverters and onboard chargers are adopting these compact converter cells to embed balancing functions within existing thermal management envelopes. This integration is compressing the discrete component supply chain for standalone equalizer modules.
REACH substance disclosure requirements and EU Battery Regulation carbon footprint rules are mandating material traceability through equalizer supply chains. Cell-level state-of-health reporting obligations are forcing semiconductor vendors to document silicon provenance and packaging chemistry. Automotive pack manufacturers are responding by qualifying alternative molding compounds and substrate materials.
Fleet operators and utility-scale storage developers are consolidating procurement around vertically integrated battery management system suppliers. Discrete equalizer vendors are losing socket position to subsystem providers offering cell monitoring, balancing, and thermal management in unified architectures. This concentration is most visible in German automotive supplier corridors and Chinese vertically integrated cell-to-pack facilities.
Battery Equalizer Market Segmentation
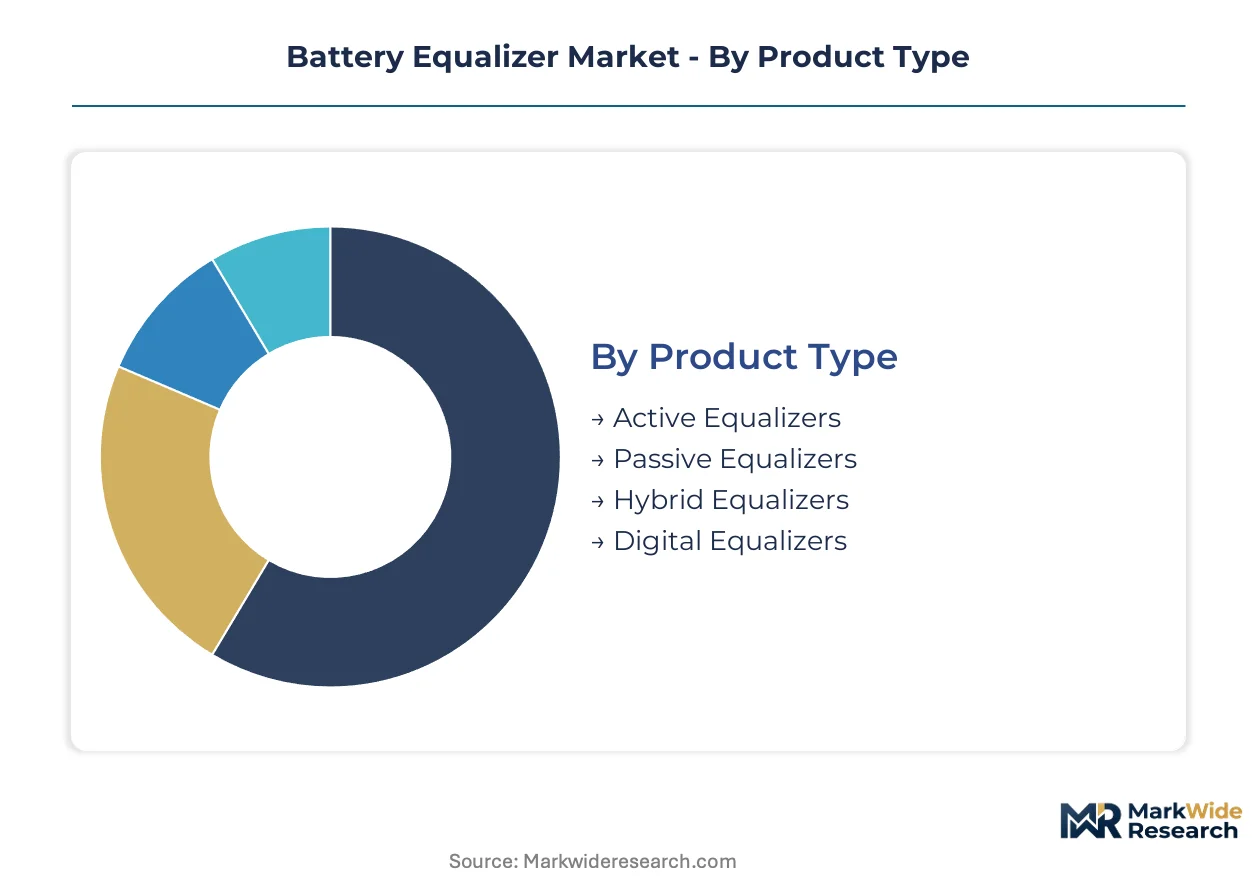
Battery equalizer architectures diverge sharply across deployment contexts, with automotive type-approval frameworks and grid-scale efficiency mandates dictating hardware selection. Segmentation reveals how regulatory tiering concentrates value in active topologies while cost floors sustain passive alternatives.
Product Type:
ECE R100 and GB/T thermal runaway standards create divergent compliance burdens across equalizer categories.
- Active Equalizers:Inductor-based converter and switched-capacitor architectures recover energy during cell redistribution. Demand concentrates in Germany's automotive supplier corridor around Stuttgart, driven by EU Battery Regulation cell-monitoring mandates for traction batteries.
- Passive Equalizers:Dissipative resistor arrays shunt excess charge as heat through simple voltage comparison circuits. Volume persists in consumer electronics manufacturing hubs where cell counts remain low and efficiency losses are economically tolerable.
- Hybrid Equalizers:Configurable systems blend switched-capitor speed with inductor-based energy recovery for tunable performance.
- Digital Equalizers:Firmware-intensive architectures integrate predictive algorithms through embedded battery management SoCs.
Established volume favors passive architectures; emerging adoption favors active equalizers.
End User:
Application-specific duty cycles and safety criticality determine balancing topology selection and integration depth.
- Electric Vehicles:Onboard systems must survive vibration, thermal cycling, and electromagnetic interference across 8-15 year service lives. Pack integrators in Wolfsburg and Stuttgart anchor procurement for inductor-based active architectures meeting ECE R100 type-approval.
- Renewable Energy Systems:Grid-scale lithium-ion deployments for renewable firming require continuous balancing across thousands of cells. Utility developers favor energy-recovering topologies where efficiency losses compound at scale.
- Consumer Electronics:Low cell counts and compressed product lifecycles sustain resistor-based dissipation.
- Industrial Applications:Forklifts, material handling equipment, and backup power systems demand configurable trade-offs between balancing speed and cost.
Procurement scale concentrates in electric vehicles; margin expansion favors renewable energy systems.
Technology:
Precision measurement IP and power stage integration define competitive differentiation across technical approaches.
- Voltage Balancing:Direct cell-to-cell comparison circuits remain the foundational approach, with analog front-end precision determining accuracy.
- Current Sharing:Active architectures redistribute charge through controlled current paths, enabling energy recovery rather than dissipation.
- State of Charge Monitoring:Coulomb counting and impedance spectroscopy integration enables predictive balancing algorithms. Semiconductor vendors leverage industrial automation measurement IP to capture automotive-grade cell monitoring sockets.
- Power Management:Integration of balancing logic with thermal management and charging control compresses board area.
Design-in frequency favors state of charge monitoring; bill-of-materials reduction favors power management integration.
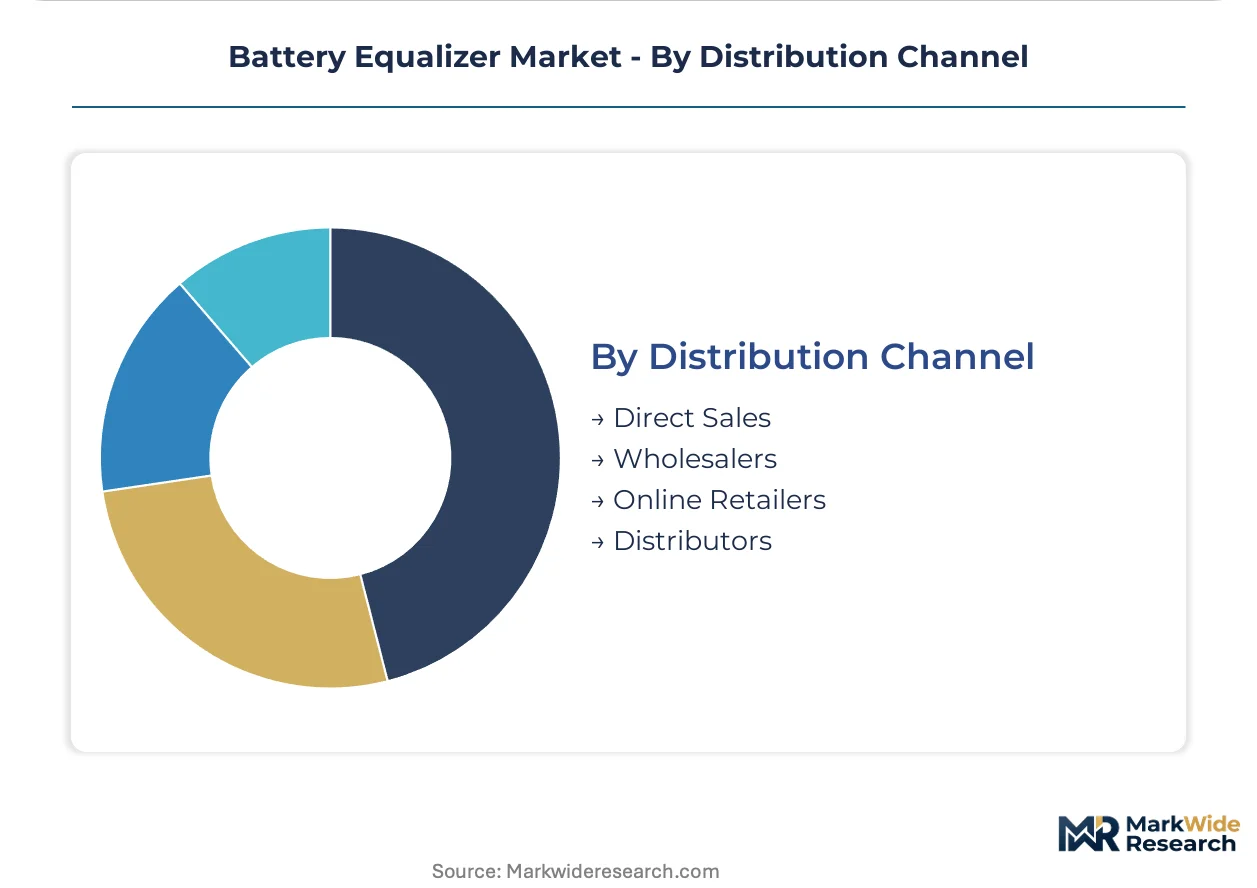
Distribution Channel:
Customer scale and technical support requirements fragment procurement pathways across supplier tiers.
- Direct Sales:Tier-1 automotive suppliers and utility-scale storage developers negotiate directly with semiconductor vendors for battery management SoC volumes.
- Wholesalers:Regional electronics distributors aggregate demand from mid-sized industrial customers.
- Online Retailers:Developer kits and evaluation modules reach prototyping engineers through specialized electronics marketplaces.
- Distributors:Authorized channels provide technical support and local inventory for qualified pack manufacturers.
Contract value concentrates in direct sales; geographic reach favors distributor networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's automotive supplier corridor while cost-sensitive procurement dominates China's cell-to-pack manufacturing zones. This asymmetry drives divergent technology adoption across major battery equalizer demand centers.
Germany
Stuttgart and Wolfsburg anchor procurement for inductor-based active equalizers serving premium electric vehicle programs. ECE R100 type-approval requirements under the EU Battery Regulation mandate cell-level monitoring hardware in all traction batteries sold across Europe. Pack integrators in Baden-Württemberg and Lower Saxony qualify active architectures from semiconductor vendors for 8-15 year service lives.
China
Vertically integrated cell-to-pack facilities in Shenzhen and Ningbo drive volume demand for cost-optimized balancing solutions. NMPA enforcement of GB/T thermal runaway propagation testing presumes functional equalization systems in certified lithium-ion packs. Domestic semiconductor vendors compete with multinational analog suppliers for sockets in electric vehicle platforms targeting both domestic and export markets.
United States
Silicon Valley and Austin design centers specify precision battery management SoCs for grid-scale storage and electric vehicle applications. NHTSA safety investigations into battery thermal events reinforce demand for embedded cell monitoring. Texas-based analog foundries supply wafer-level integration of balancing logic for automotive-grade deployments.
India
Chennai and Pune manufacturing hubs generate compliance-driven demand following BIS adoption of IEC 62660 test protocols for lithium cells. The country's national automotive regulator mandates enhanced battery safety assessments for electric two-wheelers and passenger vehicles. Industrial battery pack assemblers in Tamil Nadu and Maharashtra source hybrid equalizer architectures for material handling equipment.
Japan
Kanto region engineering centers develop firmware-intensive predictive balancing algorithms for premium electric vehicle platforms. METI technology roadmaps prioritize battery longevity metrics that favor active energy recovery topologies. Precision measurement specialists in Tokyo and Yokohama supply analog front-end IP for state-of-health monitoring integration.
Battery Equalizer Market Competitive Landscape
Concentration sits with diversified semiconductor majors possessing analog foundry scale and precision measurement IP portfolios. Specialty battery management vendors occupy mid-tier positions through firmware-intensive architectures. The competitive terrain organizes around three archetypes: diversified analog semiconductor suppliers, dedicated battery management system developers, and test equipment manufacturers extending into embedded monitoring. Dominant competitive moves include wafer-level integration of balancing functions and strategic partnerships between semiconductor vendors and tier-1 automotive suppliers.
Within the diversified semiconductor tier, Texas Instruments and Analog Devices exemplify scale-driven positioning through analog foundry integration and precision measurement IP extension. Nuvation Engineering occupies a specialist position representing firmware-architecture differentiation. These three anchors illustrate how competitive positioning diverges between capital-intensive wafer-level integration and embedded systems expertise.
| Leading Market Players |
|---|
| Texas Instruments |
| Nuvation Engineering |
| Analog Devices |
| Renesas Electronics |
| Balancer Tech |
| PowerSmart Innovations |
| Fluke Corporation |
| Megger Group Limited |
| Cadex Electronics Inc. |
| Others |
Pricing and Supply Chain Analysis
Forty-five to sixty days of inventory for silicon carbide MOSFETs and precision analog front-ends concentrates pricing power with Taiwanese foundry operators and German automotive suppliers, compressing margins for pack integrators unable to secure long-term offtake agreements. This lead-time band forces buyers into premium pricing for configured-to-order active equalizer modules while standard passive architectures trade at commodity levels.
Pricing Analysis
Configured-to-order active equalizer modules command a 3-5x premium over standard passive resistor arrays, with pricing stratifying across automotive-grade certification tiers, volume scale, and firmware customization depth. ECE R100 and GB/T compliance testing costs are intensifying cost compression in the passive tier as consumer electronics manufacturers absorb efficiency losses to avoid active architecture premiums. Tier-1 automotive suppliers in Stuttgart and Wolfsburg exhibit the lowest price sensitivity, while industrial pack assemblers in India and Southeast Asia drive the hardest volume negotiations.
Supply Chain Analysis
Inventory accumulation at 60-90 days for gallium nitride power stages and battery management SoCs reflects supply concentration in Taiwan, South Korea, and the United States, with analog wafer fabrication anchored in Texas and analog front-end packaging concentrated in Penang and Shenzhen. The supply chain draws from silicon carbide substrate suppliers in Japan and Germany, precision magnetics from China and Vietnam, and automotive-grade molding compounds from Belgium and South Korea. Single-source vulnerability for wide-bandgap semiconductor foundry capacity creates tariff exposure risk as trade restrictions on advanced node equipment expand. Distribution runs through authorized semiconductor distributors serving qualified pack manufacturers, with direct sales dominating automotive and utility-scale procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware update subscriptions and predictive maintenance service layers are expanding faster than hardware shipments, transforming battery equalizer procurement from capital expenditure into operational technology service contracts. This service-attach dynamic rewards vendors who embed continuous monitoring capabilities at the point of hardware sale.
For Market Incumbents: Fortify socket position in German automotive corridors by deepening backward integration into gallium nitride power stage design, while accelerating certification investment for India's BIS IEC 62660 protocols ahead of competitor qualification timelines. The threat of vertically integrated cell-to-pack manufacturers in China internalizing balancing functions demands channel control through exclusive firmware licensing agreements with tier-1 suppliers.
For New Entrants and Emerging Players: Firmware customization gaps in second-life battery repurposing applications offer white-space entry, with Chennai and Pune pack assemblers under-served by incumbent predictive algorithm offerings. Target industrial forklift and material handling equipment segments where hybrid architecture demand outstrips specialist vendor capacity. A go-to-market angle anchored in rapid deployment kits for retrofit equalizer installation bypasses lengthy automotive qualification cycles.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because ECE R100, GB/T, and evolving UN 38.3 mandates harden certification barriers faster than new entrants can achieve compliance breadth. Acquisition targets should exhibit firmware-architecture differentiation paired with existing automotive qualification footprints. The signal to watch is BIS enforcement timelines in India, where accelerated adoption of IEC 62660 protocols would compress qualification windows and strand non-compliant hardware inventory.
| Strategic Initiative | Industry Significance |
|---|---|
| Wafer-Level Integration | Texas Instruments and Analog Devices compress board area by embedding balancing logic with precision measurement IP at the analog foundry. |
| Regulatory Pre-Certification | Early alignment with ECE R100, GB/T, and BIS IEC 62660 protocols secures socket position before competitor qualification completion. |
| Firmware-Intensive Architecture Development | Nuvation Engineering's predictive algorithm approach captures grid-scale storage demand for state-of-health monitoring integration. |
| Second-Life Battery Service Layer | Retrofit equalizer demand from end-of-life electric vehicle packs diverted to stationary storage creates recurring revenue attachment. |
| Gallium Nitride Power Stage Adoption | Magnetics-integrated GaN converters miniaturize active equalizer footprints for embedding within existing thermal management envelopes. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with battery pack integration engineers, semiconductor vendor product managers, automotive OEM platform architects, and utility-scale storage procurement directors. Secondary validation drew from ECE R100 type-approval documentation, NMPA GB/T certification filings, BIS adoption circulars for IEC 62660, SEC 10-K disclosures from analog semiconductor suppliers, and IHS Markit electric vehicle production databases. Bottom-up cell-level demand estimates were triangulated against top-down battery management system market sizing.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation by equalizer architecture type, end-use application duty cycle, and regional regulatory cluster, with additional dimensioning by certification tier and integration depth. CAGRs were derived from fitted growth curves applied to battery pack shipment projections, with cross-reference to analog semiconductor revenue disclosure patterns and automotive platform electrification timelines. Industry-specific inputs included silicon carbide MOSFET supply elasticity assumptions and firmware development cost curves for predictive balancing algorithms.
Forecasts assume regulatory continuity in EU Battery Regulation enforcement, NMPA GB/T thermal runaway testing protocols, and BIS IEC 62660 adoption timelines; material policy shifts in any of these regimes would require re-modeling with adjusted compliance cost assumptions and qualification delay factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
North America Telecom Power Systems Market
Power Systems
Electric Vehicle Power Inverter Market
Power Systems
Photovoltaic Inverters Market
Power Systems
EV Power Module Market
Power Systems
Battery Balancer Market
Power Systems
Asia-Pacific Uninterruptible Power Supply (UPS) Market
Power Systems
Thyristor Market
Power Systems
Asia-Pacific DC Distribution Networks Market
Power Systems
AC Voltage Transducer Market
Power Systems
Grid Tie Inverter Market
Power Systems
Global Power Discrete and Modules Market
Power Systems
Global Inverter Market
Power Systems
Power Semiconductor Market
Power Systems
Low Voltage DC Circuit Breaker Market
Power Systems
Bypass Thyristor Market
Power Systems
Battery Pack High-Voltage Wiring System Components Market