

ADC & DAC In Quantum Computing Market Size, Share, and Industry Trends Forecast 2026-2036
ADC & DAC In Quantum Computing Market Insights
Buyer concentration among cloud quantum providers is rebalancing as government labs and research institutes fragment procurement across multiple converter suppliers. IBM leverages captive cryogenic design capabilities to anchor its superconducting roadmap. Analog Devices sustains leadership in precision mixed-signal hardware for dilution-refrigerator environments. D-Wave Quantum specializes in annealing-specific converter architectures that differentiate its hardware stack.
Analog-to-digital converters and digital-to-analog converters in quantum computing are precision mixed-signal devices engineered to operate below 4 Kelvin, translating fragile qubit readout voltages into classical digital data and applying control pulses with sub-microsecond latency. Their primary purpose is to preserve quantum coherence during the interface between quantum processors and room-temperature classical control electronics. Cryogenic CMOS technology leads component adoption because it integrates natively with existing semiconductor fabrication, while superconducting converter designs capture the fastest growth as they match the operating regime of leading qubit modalities. Quantum error correction applications command the deepest engineering investment among application segments, since fault-tolerant architectures demand orders of magnitude more converter channels than noisy intermediate-scale quantum systems.
NIST in the United States shapes converter requirements through its quantum-resistant cryptography migration timelines, while the EU AI Act and GDPR in Europe impose data-handling standards on quantum cloud interfaces that incorporate ADC and DAC subsystems. Japan's METI funds cryogenic electronics consortia that directly steer domestic converter R&D priorities. Stakeholders must monitor how national quantum initiatives in Germany, Japan, and the United States allocate sovereign funding toward domestic converter supply chains versus imported components.
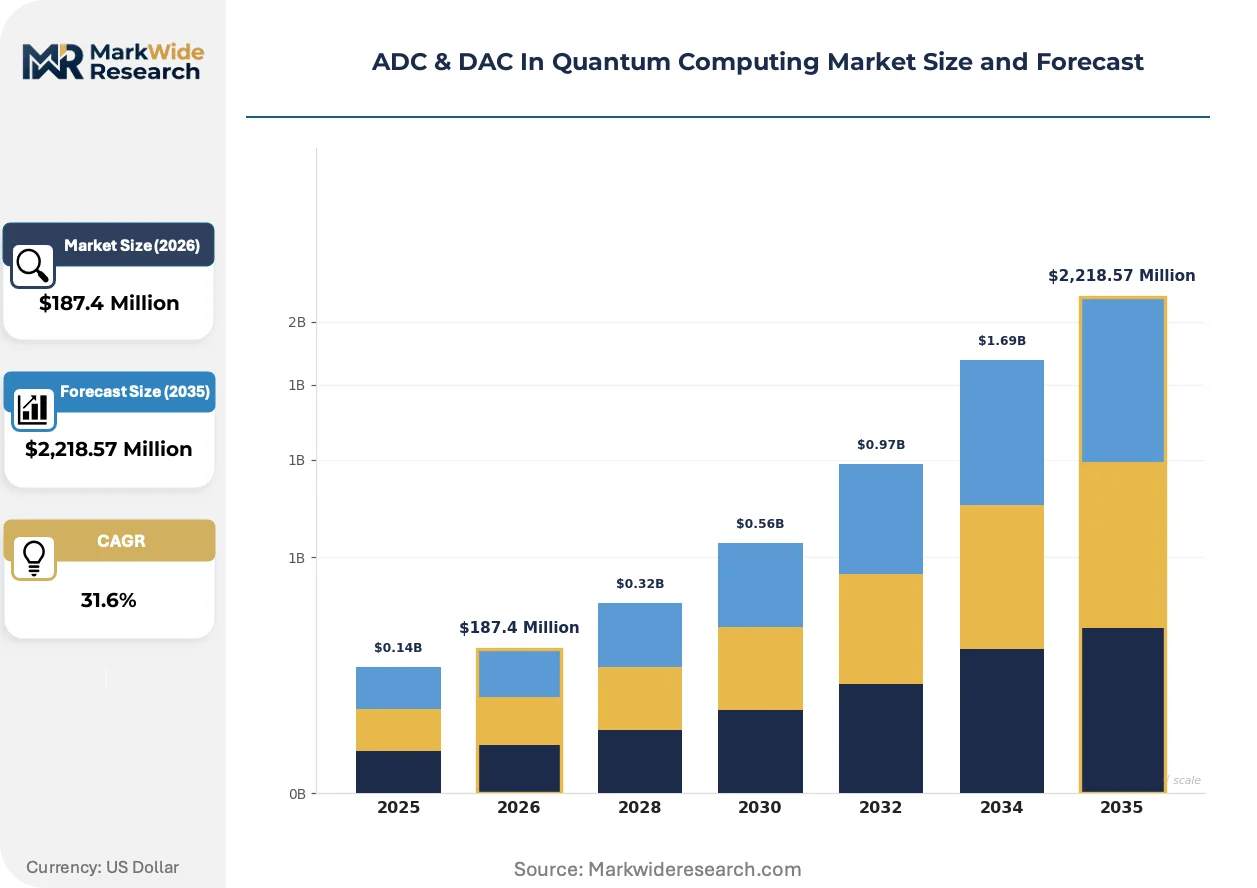
Market Dynamics
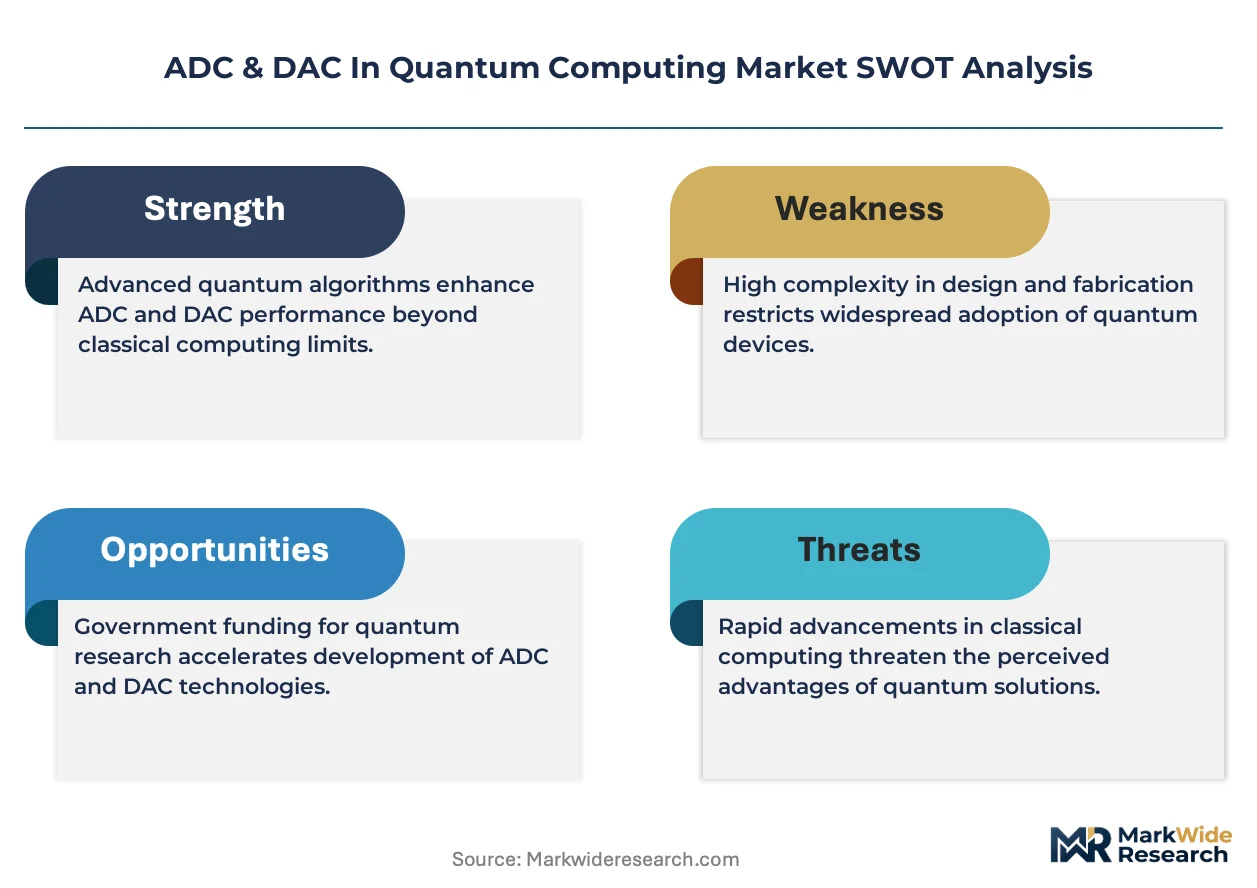
The central structural force reshaping the ADC and DAC in quantum computing market is the migration from noisy intermediate-scale quantum systems toward fault-tolerant architectures requiring massive parallelization of cryogenic control channels. This shift is compressing supplier margins while expanding total addressable converter volume.
Growth Catalysts
- NIST Post-Quantum Cryptography Standards:The United States standards body mandates quantum-resistant algorithm deployment timelines that accelerate superconducting qubit testbed construction and associated converter procurement cycles.
- Superconducting Qubit Roadmaps:Leading hardware programs in Germany, Japan, and the United States specify thousand-plus qubit arrays that each demand dedicated cryogenic ADC and DAC channels for individual qubit control.
- Cryogenic CMOS Maturation:Semiconductor fabrication nodes below 28 nanometers now yield operational transistors at millikelvin temperatures, enabling single-chip integration of multi-channel converters previously requiring discrete assemblies.
Market Restraints
- Dilution Refrigerator Bottlenecks:Cryostat manufacturing concentrates among three specialized suppliers in Finland, the United States, and the United Kingdom, constraining the physical installation base for converter deployment.
- Helium-3 Supply Concentration:The rare isotope essential for sub-100 millikelvin cooling originates primarily from Russian and United States nuclear stockpile downblending, exposing converter test schedules to geopolitical supply interruptions.
- Thermal Load Constraints:Each added converter channel introduces parasitic heat dissipation that competes with qubit coherence preservation, forcing hard trade-offs between control bandwidth and quantum processor fidelity.
Strategic Opportunities
- Photonic Qubit Integration:Silicon photonics platforms at room temperature eliminate cryogenic converter requirements for certain quantum computing modalities, opening adjacent markets for high-speed optical-electrical conversion hardware.
- EU Quantum Flagship Procurement:The European Union's billion-euro research program channels sovereign funding toward domestic converter supply chain development, favoring local design houses over imported components.
- Quantum Error Correction Commercialization:Surface code implementations demand real-time decoder hardware with microsecond latency requirements that favor specialized ADC-DAC architectures over general-purpose instrumentation.
Industry Challenges
- Cryogenic Packaging Expertise Gap:The intersection of microwave engineering, semiconductor design, and dilution refrigerator operation requires rare hybrid skill sets that universities in Germany, Japan, and the United States struggle to produce at sufficient scale.
- Multi-Temperature Interface Standardization:Absence of unified electrical and thermal interface specifications between converter modules and qubit chips forces custom engineering on every new hardware platform, extending development timelines.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ADC & DAC In Quantum Computing Market Trends and Innovations
Cryogenic mixed-signal integration is actively compressing the physical footprint and power dissipation of quantum control electronics. Three converging developments are restructuring how converter hardware interfaces with quantum processors.
Cryogenic CMOS is consolidating multi-channel ADC and DAC functions onto single die implementations that operate at 4 Kelvin without external heating. IBM and government laboratories in the United States are deploying these integrated circuits in thousand-channel configurations for superconducting qubit control. The technology is consolidating what previously required racks of room-temperature instrumentation into palm-sized modules that sit adjacent to quantum processors inside cryostats.
The EU AI Act imposes algorithmic transparency requirements on quantum cloud services that incorporate ADC and DAC subsystems for remote qubit access. European quantum computing providers must document data handling across the classical-quantum interface, affecting converter firmware architectures and audit trail capabilities. German and French hardware developers are responding by embedding hardware security modules within cryogenic control stacks to satisfy GDPR-aligned data governance.
Buyer aggregation around cloud-accessible quantum computers is fragmenting procurement authority away from captive hardware divisions. Research groups in Japan and the United States now specify converter performance through service-level agreements with quantum cloud providers rather than direct component sourcing. This behavioral shift is compressing the addressable market for standalone converter vendors while expanding integrated system suppliers.
ADC & DAC In Quantum Computing Market Segmentation
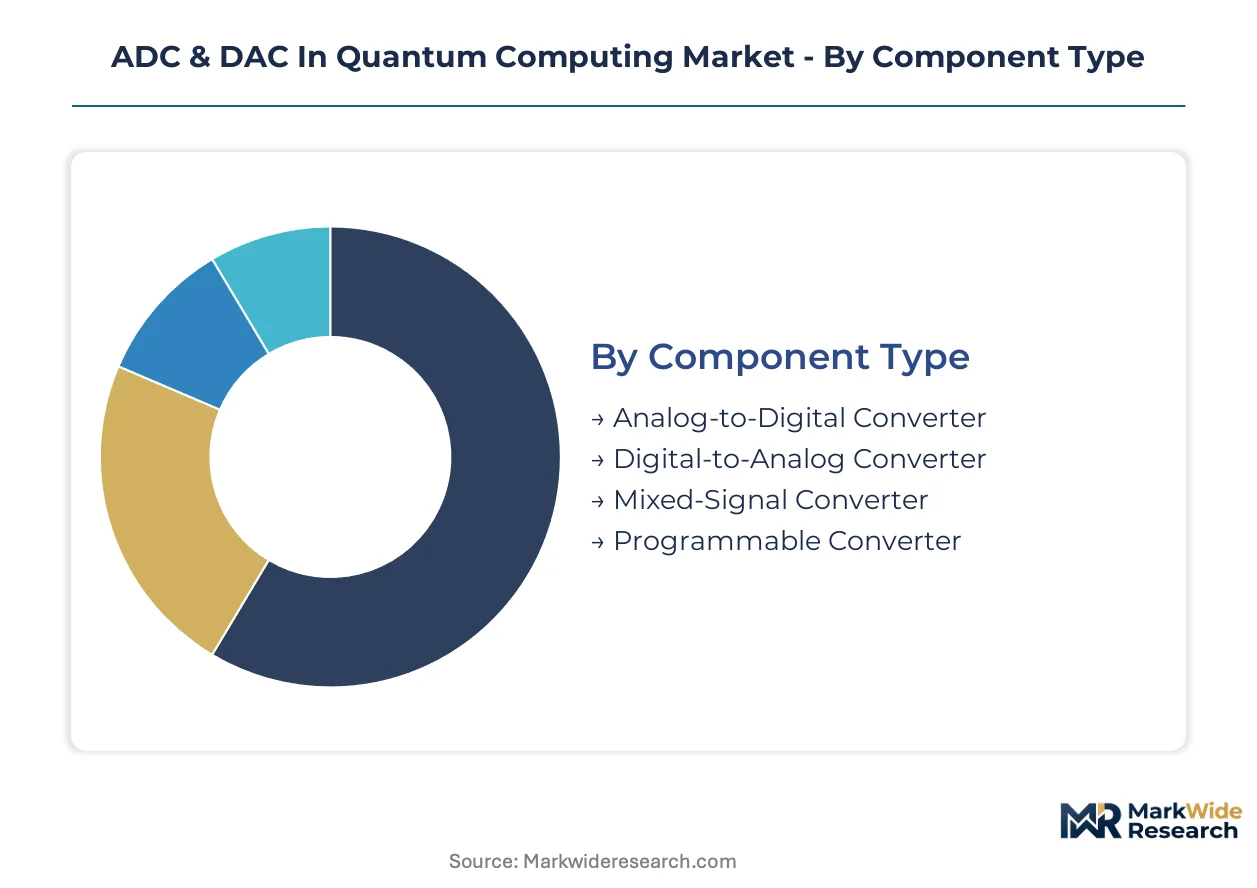
ADC and DAC segmentation in quantum computing reveals how control electronics integrate at varying depths within cryogenic stacks. Component positioning—whether standalone modules or embedded die-level functions—directly shapes thermal budgets, channel density, and procurement economics across superconducting and photonic platforms.
Component Type:
Integration depth separates standalone rack-mounted units from embedded multi-channel dies that sit millimeters from qubit chips inside dilution refrigerators.
- Analog-to-Digital Converter:Cryogenic ADCs translate nanovolt-level qubit readout signals into digital bitstreams with sub-microsecond latency. IBM and government laboratories in the United States deploy thousand-channel configurations for superconducting qubit arrays, with NIST post-quantum cryptography timelines accelerating procurement cycles.
- Digital-to-Analog Converter:Precision DACs generate control pulses with amplitude resolution below 100 microvolts to preserve qubit coherence. Demand concentrates in Germany and Japan where superconducting qubit roadmaps specify dedicated DAC channels per qubit, constrained by parasitic heat dissipation trade-offs.
- Mixed-Signal Converter:Single-die integration of ADC and DAC functions reduces cryostat wiring density.
- Programmable Converter:Firmware-reconfigurable architectures adapt to varying qubit control protocols.
Mixed-signal converters lead volumes today; programmable variants are gaining share fastest.
Technology:
Cost tier alignment separates mature semiconductor fabrication from emerging superconducting designs requiring specialized foundry access.
- Superconducting:Josephson-junction-based converters operate natively at millikelvin temperatures, eliminating thermal interface losses. METI-funded consortia in Japan steer domestic R&D priorities toward superconducting integration, matching the operating regime of leading transmon qubit modalities.
- Cryogenic CMOS:Sub-28-nanometer CMOS nodes now yield operational transistors at 4 Kelvin, enabling single-chip multi-channel integration. Analog Devices and IBM in the United States anchor production roadmaps around cryogenic CMOS for dilution-refrigerator environments.
- Photonic:Room-temperature optical-electrical conversion eliminates cryogenic constraints for certain quantum computing architectures.
- Spintronic:Spin-based devices promise ultra-low power dissipation at cryogenic temperatures.
- Silicon Qubit:Silicon quantum dot systems leverage existing semiconductor fabrication infrastructure.
Cryogenic CMOS dominates installed base; superconducting designs show steepest expansion trajectory.
Application:
Application maturity correlates with channel count requirements—fault-tolerant architectures demand orders of magnitude more converter channels than early-stage systems.
- Quantum Error Correction:Surface code implementations require real-time decoder hardware with microsecond latency. The EU Quantum Flagship channels sovereign funding toward specialized ADC-DAC architectures for error correction, favoring local European design houses.
- Quantum Algorithms:NIST post-quantum cryptography standards in the United States mandate quantum-resistant algorithm testbeds that accelerate converter procurement for algorithm development.
- Quantum Simulation:Analog quantum simulators reduce digital control overhead compared to gate-based systems.
- Quantum Cryptography:Quantum key distribution systems prioritize timing precision over channel density.
- Quantum Sensing:Atomic and solid-state sensors demand high-dynamic-range conversion for weak signal extraction.
Quantum algorithms anchor current demand; error correction is climbing the fastest.
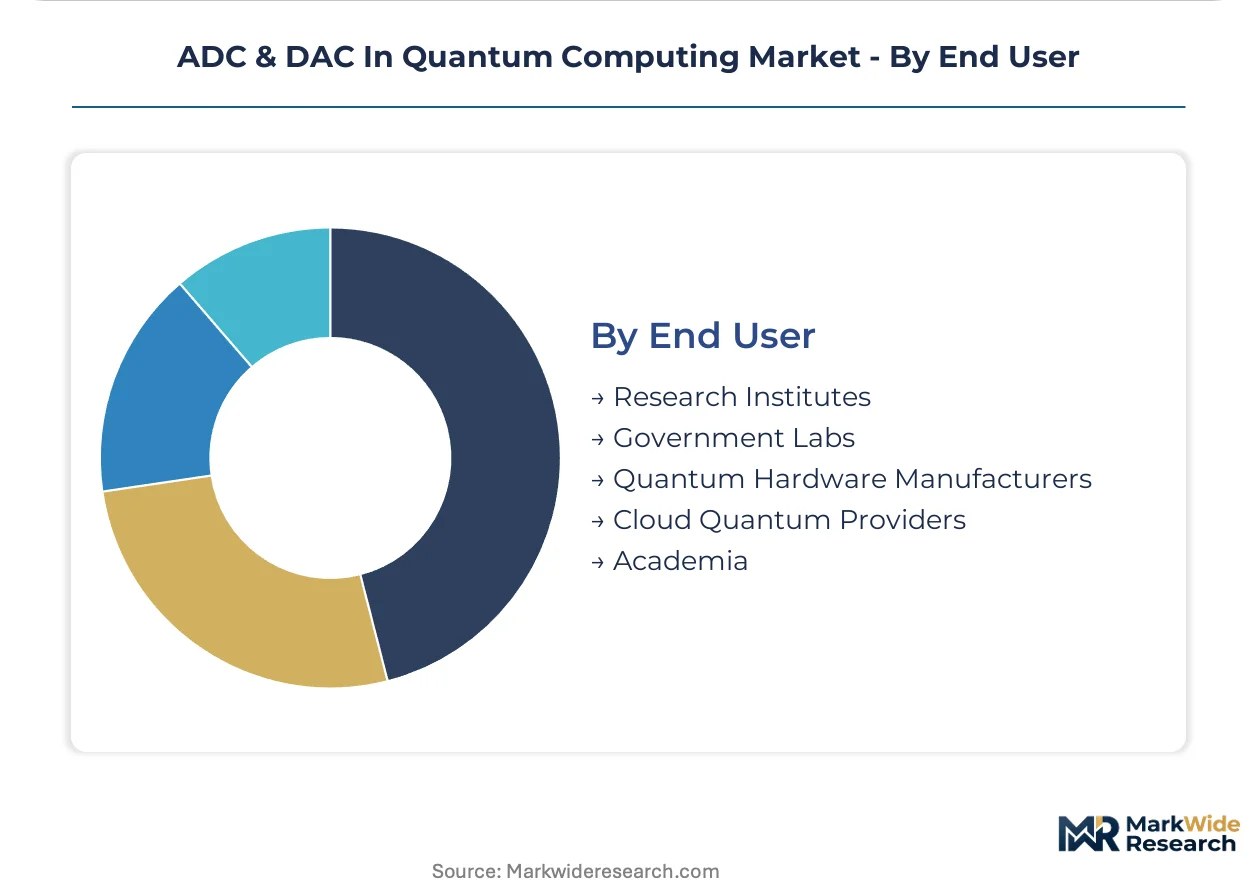
End User:
Customer type determines procurement authority—captive hardware divisions versus fragmented research institute sourcing.
- Cloud Quantum Providers:Buyer aggregation around IBM, Amazon, and Google services fragments procurement authority away from standalone converter vendors. Service-level agreements now specify converter performance, compressing addressable markets for component suppliers while expanding integrated system revenues.
- Quantum Hardware Manufacturers:Captive design capabilities at IBM and D-Wave anchor internal converter development roadmaps. These manufacturers in the United States and Canada specify thousand-plus qubit arrays demanding dedicated cryogenic control channels.
- Research Institutes:German and Japanese national laboratories fragment procurement across multiple converter suppliers, rebalancing concentration away from cloud providers.
- Government Labs:NIST and Department of Energy facilities in the United States shape converter requirements through quantum testbed construction timelines.
- Academia:University groups in Germany, Japan, and the United States access quantum hardware through cloud service agreements rather than direct component sourcing.
Cloud providers command volume leadership today; research institutes are expanding procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates superconducting qubit converter procurement more heavily than Japan fragments its sourcing across METI-funded consortia. Both nations anchor European and Asian demand respectively, while the United States dominates cloud provider aggregation.
United States
NIST post-quantum cryptography timelines accelerate superconducting qubit testbed construction across Department of Energy facilities. The CHIPS and Science Act channels sovereign funding toward domestic cryogenic CMOS fabrication capabilities. IBM in New York and government laboratories in California anchor thousand-channel converter deployments for fault-tolerant architectures.
Germany
Superconducting qubit roadmaps from Munich and Karlsruhe institutes specify dedicated cryogenic control channels per qubit. The EU Quantum Flagship directs billion-euro procurement toward local converter design houses over imported components. Bavarian research clusters fragment procurement authority across multiple specialized suppliers, rebalancing concentration away from single-vendor dependence.
Japan
METI-funded cryogenic electronics consortia steer domestic R&D priorities toward superconducting converter integration matching transmon qubit modalities. National laboratories in Tsukuba and Osaka specify converter performance through collaborative procurement frameworks. Tokyo-based hardware developers embed hardware security modules within cryogenic stacks to satisfy emerging data governance requirements.
United Kingdom
Oxford and Cambridge quantum hardware spinouts drive demand for dilution-refrigerator-compatible mixed-signal components. The country's national quantum computing program allocates sovereign funding toward domestic converter supply chain development. London-based cloud quantum providers aggregate procurement authority, compressing addressable markets for standalone component vendors.
Canada
D-Wave Quantum in British Columbia anchors annealing-specific converter architectures that differentiate its hardware stack from gate-based competitors. Federal quantum strategy documents prioritize cryogenic control electronics for photonic and superconducting platforms. Toronto-Waterloo corridor research institutes access quantum hardware through cloud service agreements rather than direct component sourcing.
ADC & DAC In Quantum Computing Market Competitive Landscape
United States producers anchor the integrated-system tier; European specialists hold the component-design tier. The market structure concentrates around captive hardware divisions at cloud providers while fragmenting across research institute procurement. Three archetypes dominate: vertically integrated quantum hardware manufacturers, precision mixed-signal semiconductor suppliers, and cryogenic packaging specialists. Competitive moves center on strategic partnerships for dilution refrigerator integration and portfolio diversification toward photonic qubit modalities.
Within the captive-integration tier, IBM and D-Wave Quantum occupy positions exemplifying divergent strategic paths—IBM around superconducting gate-based systems and D-Wave around quantum annealing architectures. Analog Devices sits within the precision mixed-signal supplier archetype, representing semiconductor fabrication capabilities adapted for millikelvin environments. These three entities anchor the competitive topology without exhausting the vendor landscape.
| Leading Market Players |
|---|
| IBM |
| Alphabet |
| Microsoft |
| Amazon |
| D-Wave Quantum |
| IonQ |
| Quantinuum |
| Rigetti Computing |
| Analog Devices |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed producers in Japan, Germany, and the United States anchor cryogenic converter manufacturing, channeling state quantum initiative funding into captive supply chains that compress margins for standalone component vendors while insulating strategic buyers from spot-market volatility.
Pricing Analysis
Capacity additions in the United States are reshaping price floors for cryogenic CMOS converters as CHIPS Act subsidies expand domestic fabrication. Pricing stratifies across radiation-hardened premium tiers for space-qualified deployments, standard commercial grades for laboratory testbeds, and economy tiers for educational cloud access. Cost compression in standard-grade channels is intensifying because Analog Devices and IBM are internalizing multi-channel die production. Research institutes in Germany exhibit highest price sensitivity due to fragmented procurement budgets, while cloud quantum providers in the United States absorb premium pricing through service-level agreement structures.
Supply Chain Analysis
Specialized microwave engineering talent scarcity in Finland, the United Kingdom, and the United States constrains dilution refrigerator integration throughput for converter modules. Cryogenic CMOS fabrication draws from sub-28-nanometer foundry capacity concentrated in Taiwan and South Korea, while superconducting Josephson junction processing rests on dedicated niobium-aluminum oxide foundry access in Japan and the Netherlands. Single-source vulnerability around helium-3 isotope supply from Russian and United States nuclear stockpiles threatens sub-100 millikelvin cooling schedules. Distribution runs through direct OEM partnerships for captive hardware divisions and specialized scientific distributors for research institute procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NIST post-quantum cryptography standardization timelines compound regulatory demand for cryogenic control electronics, creating procurement windows that favor suppliers with pre-qualified converter architectures.
For Market Incumbents: Deepen cryogenic packaging expertise capture through targeted hiring in Germany and Japan where university pipeline gaps are most acute. Anchor defensive positioning against photonic qubit substitution by accelerating mixed-signal integration roadmaps that preserve superconducting modality lock-in. Prioritize certification investment for EU Quantum Flagship compliance to maintain access to billion-euro procurement channels. For New Entrants and Emerging Players: Government laboratories in the United States represent the most underserved buyer archetype for specialized quantum error correction converter architectures. Penetrate this segment through NIST testbed partnership frameworks rather than direct cloud provider competition. Position around real-time decoder hardware latency specifications that differentiate from general-purpose instrumentation incumbents. For Investors and Strategic Acquirers: Cloud quantum providers are the most active acquirer in this space, consolidating converter supply through captive integration rather than component vendor partnerships. Frame long-term viability around five-to-ten year fault-tolerant architecture deployment horizons. Target cryogenic packaging specialists with hybrid microwave-semiconductor skill sets. Watch helium-3 supply stabilization agreements as the critical inflection signal for sub-100 millikelvin converter test schedule reliability.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic CMOS Foundry Partnership | Secures sub-28-nanometer capacity at TSMC or Samsung for 4 Kelvin operational transistor production. |
| Helium-3 Supply Diversification | Reduces Russian and United States nuclear stockpile dependency for sub-100 millikelvin cooling infrastructure. |
| EU Quantum Flagship Certification | Unlocks billion-euro sovereign procurement channels for German and French converter design houses. |
| Photonic Qubit Platform Expansion | Captures adjacent optical-electrical conversion markets as silicon photonics eliminates cryogenic requirements. |
| Hardware Security Module Integration | Satisfies GDPR-aligned data governance for EU AI Act compliance in cryogenic control stacks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cryogenic electronics engineers, dilution refrigerator procurement leads, quantum hardware program managers, and NIST standards committee participants with secondary validation against SEC filings from Analog Devices and IBM, Department of Energy quantum testbed budget disclosures, METI-funded consortium progress reports, and EU Quantum Flagship procurement databases. Bottom-up channel counts and top-down sovereign funding allocations were cross-referenced to anchor volume estimates.
The forecast window anchored historical reference periods through cryogenic CMOS node maturation milestones and superconducting qubit array scaling roadmaps from IBM, Google, and government laboratories. Segmentation modeling spanned component integration depth, technology modality, application maturity from algorithms through error correction, and end-user procurement authority concentration. CAGRs were derived from installed base expansion rates constrained by dilution refrigerator manufacturing capacity and thermal load budgets per qubit.
Inputs from NIST, METI, and EU Quantum Flagship program offices were available through the study window; gaps in classified defense quantum computing procurement introduce uncertainty bands around government laboratory demand estimates. Forecasts reflect assumptions regarding helium-3 supply continuity, cryogenic CMOS yield maturation, and fault-tolerant architecture timeline acceleration. Material deviation in NIST post-quantum cryptography deployment schedules or CHIPS Act funding continuity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.