
 Vaneometer Market | 2026-2036
Vaneometer Market Size, Share, and Industry Trends Forecast 2026-2036
Vaneometer Market Analytics
Chinese sensor manufacturers is expanding production capacity for magnetic and ultrasonic vaneometer cores, tightening component availability for downstream instrument builders. Vaisala leverages its Nordic R&D base to sustain premium positioning in environmental monitoring applications. Campbell Scientific anchors North American demand through specialized data-logging integration. Siemens AG competes across European industrial automation channels with embedded airflow solutions.
A vaneometer measures air velocity and flow rate using a rotating vane or impeller whose rotational speed correlates with wind speed, typically calibrated in meters per second or cubic feet per minute for HVAC, laboratory, and industrial process applications. Digital vaneometers with magnetic sensing technology now dominate commercial procurement due to superior accuracy and datalogging capability. Rotary technology segments remain mature in basic ventilation testing, while ultrasonic technology represents the fastest-growing architecture for cleanroom and pharmaceutical applications where non-contact measurement eliminates contamination risk. Portable vaneometers command margin concentration in field service and commissioning workflows.
EPA ventilation standards and OSHA confined-space airflow requirements shape product certification demands in the United States, while the EU Green Deal and F-Gas Regulation in Europe mandate tighter building energy audits that drive instrument replacement cycles. ISO 17025 calibration protocols and CE marking requirements further filter market access for non-compliant suppliers. Stakeholders must monitor evolving particulate filtration standards in healthcare and semiconductor cleanrooms, as these specifications will determine which sensing technologies gain specification in high-value procurement channels.
Market Dynamics
Magnetic sensing technology is modularizing vaneometer architectures, compressing component counts while EPA ventilation standards and F-Gas Regulation compliance timelines force simultaneous instrument replacement cycles across commercial building portfolios.
Growth Catalysts
- EPA ventilation standards:Commercial building retrofits in the United States now mandate calibrated airflow verification, forcing HVAC contractors to replace legacy rotary instruments with digital vaneometers featuring data-logging capability.
- Cleanroom particulate filtration:Semiconductor fabrication and pharmaceutical manufacturing facilities specify non-contact ultrasonic vaneometers to eliminate contamination risk from rotating mechanical components.
- Germany industrial automation:The F-Gas Regulation and building energy codes accelerate replacement of legacy airflow instruments in industrial facilities, concentrating procurement volume in German-speaking markets.
Market Restraints
- Sensor core supply concentration:Chinese manufacturers dominate magnetic and ultrasonic vaneometer core production, creating component availability bottlenecks for downstream instrument builders in North America and Europe.
- Calibration infrastructure cost:ISO 17025 certification requirements demand capital-intensive metrology laboratories, filtering market access for smaller regional suppliers unable to absorb fixed compliance costs.
- Ultrasonic price premium:Non-contact sensing architectures carry manufacturing cost multiples over rotary alternatives, limiting penetration in basic ventilation testing segments where accuracy tolerance is wider.
Strategic Opportunities
- Embedded automation integration:Industrial control systems now specify vaneometers with native data-logging integration, opening specification channels through automation distributors rather than traditional test-equipment channels.
- Healthcare HVAC upgrades:Evolving particulate filtration standards in hospital surgical suites and isolation rooms create specification pull for certified instruments with documented traceability chains.
- Retrofit service bundling:Field service contractors are unbundling after-sales calibration from initial instrument sale, creating recurring revenue streams and tighter customer lock-in.
Industry Challenges
- Metrology talent scarcity:ISO 17025 calibration protocols require specialized airflow metrology expertise that concentrates in national standards laboratories and a handful of commercial facilities, constraining certification throughput.
- Legacy system integration:Building management systems in older commercial portfolios use proprietary communication protocols, forcing vaneometer suppliers to maintain multiple interface variants and fragmenting engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vaneometer Market |
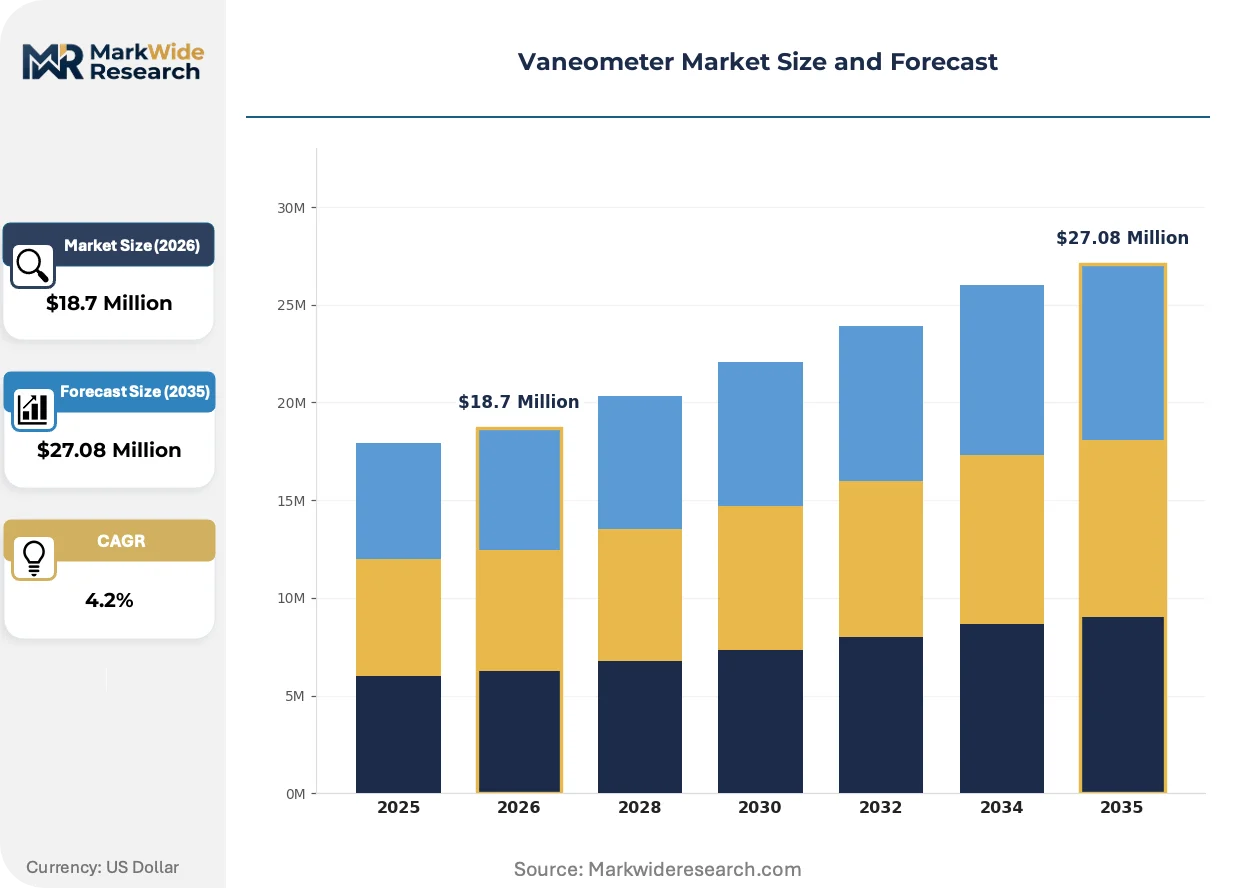
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $27.08 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Vaneometers, Digital Vaneometers, Portable Vaneometers, Bench-top Vaneometers End User: Laboratories, Manufacturing Facilities, HVAC Companies, Research Institutions Technology: Rotary Technology, Magnetic Technology, Optical Technology, Ultrasonic Technology Application: Air Flow Measurement, Ventilation Testing, Industrial Process Control, Environmental Monitoring |
| Companies Covered | Vaisala, Gill Instruments, FT Technologies, PCE Instruments, OMEGA Engineering, Siemens AG, Campbell Scientific, Thies Clima, NRG Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vaneometer Market Evolving Landscape
Digital vaneometer architectures are compressing around solid-state sensing cores while regulatory compliance timelines and procurement model evolution reshape competitive positioning across commercial and industrial channels.
Ultrasonic sensing technology is modularizing cleanroom instrumentation design. Pharmaceutical manufacturers and semiconductor fabricators specify non-contact airflow measurement to eliminate particle generation from mechanical rotation. This architecture is modularizing instrument enclosures, enabling sealed housings that reduce cleaning protocols and extend calibration intervals in contamination-critical environments.
The EU Green Deal and F-Gas Regulation are tightening building energy audit mandates across European member states. Industrial facility operators must now document airflow efficiency with calibrated instruments at defined intervals, accelerating replacement cycles for uncalibrated legacy devices. German industrial automation channels show the strongest compliance-driven procurement compression, with facility managers prioritizing instruments with embedded CE marking and traceable calibration certificates.
Facility managers are consolidating vendor relationships around full-service airflow verification contracts. Single-source procurement now bundles instrument supply, installation commissioning, and recurring calibration under multi-year agreements, displacing transactional spot purchases. This pattern concentrates most visibly in United States commercial building portfolios where EPA ventilation standards and OSHA confined-space requirements create dual compliance pressure.
Vaneometer Market Segmentation
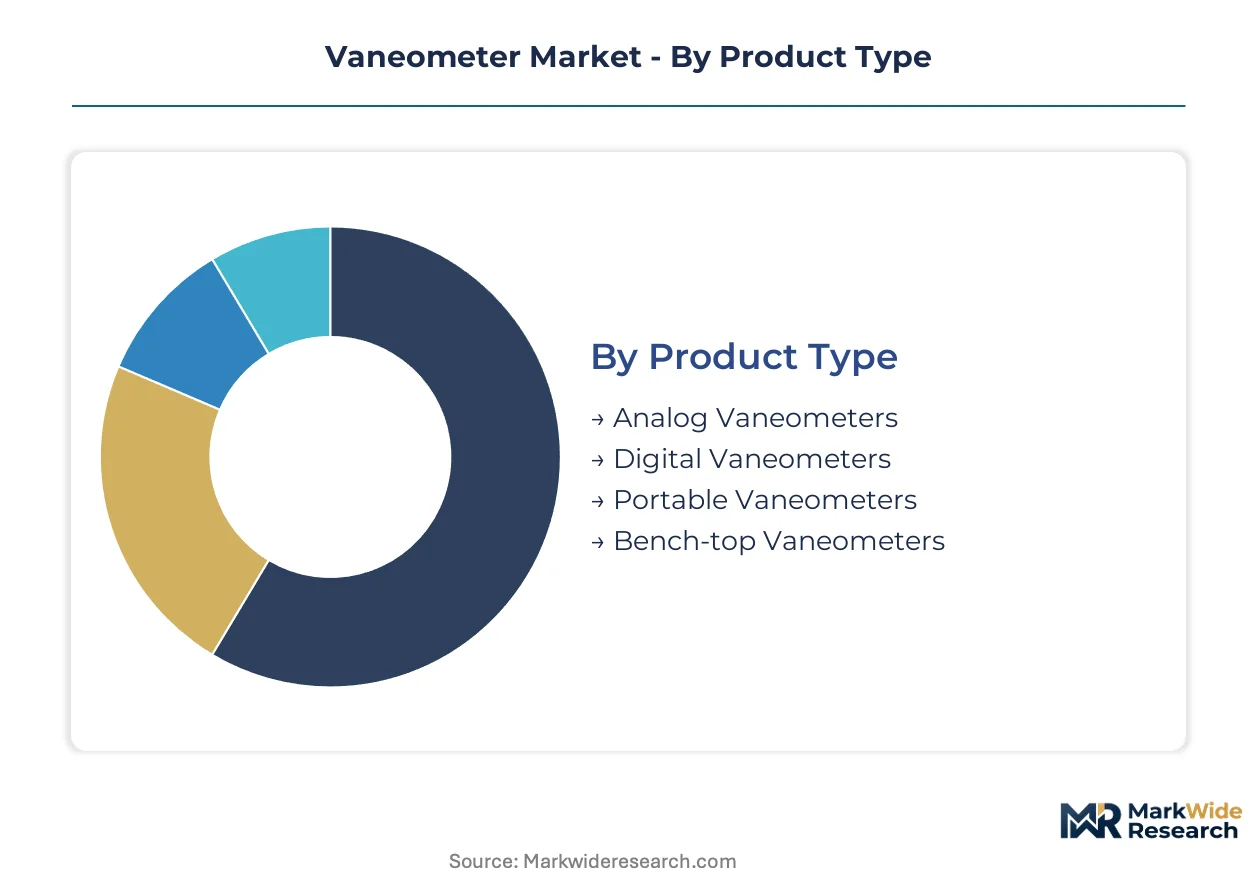
Vaneometer procurement patterns diverge sharply across product architectures, end-use environments, and sensing technologies. Understanding these fault lines clarifies where specification power concentrates and which segments command margin premiums.
Product Type:
Customization demands scale inversely with portability across this category, from field-service simplicity to laboratory-grade complexity.
- Digital Vaneometers:Solid-state magnetic sensing cores enable data-logging integration with building automation systems. HVAC contractors in the United States specify these for EPA ventilation compliance documentation, displacing legacy rotary instruments in commercial retrofit portfolios.
- Portable Vaneometers:Battery-powered handheld units dominate field commissioning and maintenance workflows. German facility managers bundle these with recurring calibration contracts under F-Gas Regulation audit requirements, creating vendor lock-in through service attachments.
- Analog Vaneometers:Mechanical dial displays persist in basic ventilation testing where capital constraints override accuracy requirements.
- Bench-top Vaneometers:Laboratory-grade precision instruments serve metrology reference applications and ISO 17025 calibration laboratories.
Most installed capacity flows through Digital Vaneometers. Expansion is steepest in Portable Vaneometers.
End User:
Procurement sophistication correlates with regulatory exposure and calibration infrastructure investment across customer types.
- HVAC Companies:Service contractors purchase portable digital units in volume for ventilation verification mandates. United States commercial building retrofits under EPA standards compress replacement cycles, while German energy audit rules accelerate instrument turnover.
- Manufacturing Facilities:Industrial automation channels specify embedded airflow sensors with native data-logging integration. Semiconductor fabricators and pharmaceutical plants drive ultrasonic adoption for contamination elimination.
- Laboratories:Research and quality-control facilities demand traceable calibration chains and ISO 17025 certification documentation.
- Research Institutions:Academic and government laboratories prioritize measurement uncertainty specifications over cost optimization.
Procurement volume concentrates in HVAC Companies. Specification value is climbing fastest in Manufacturing Facilities.
Technology:
Architecture selection hinges on contact-versus-non-contact measurement requirements and contamination sensitivity.
- Ultrasonic Technology:Non-contact sensing eliminates particle generation from mechanical rotation. Semiconductor cleanrooms and pharmaceutical isolators specify these architectures to satisfy particulate filtration standards without calibration downtime.
- Magnetic Technology:Solid-state magnetic encoders replace mechanical linkages in digital vaneometers. Chinese sensor manufacturers dominate core production, tightening availability for downstream instrument assemblers.
- Rotary Technology:Mechanical vane-and-impeller designs serve basic airflow verification with minimal cost overhead.
- Optical Technology:Laser-based particle tracking enables high-precision velocity profiling in research and metrology applications.
Magnetic Technology carries the largest installed base. Ultrasonic Technology is gaining share fastest in contamination-critical specifications.
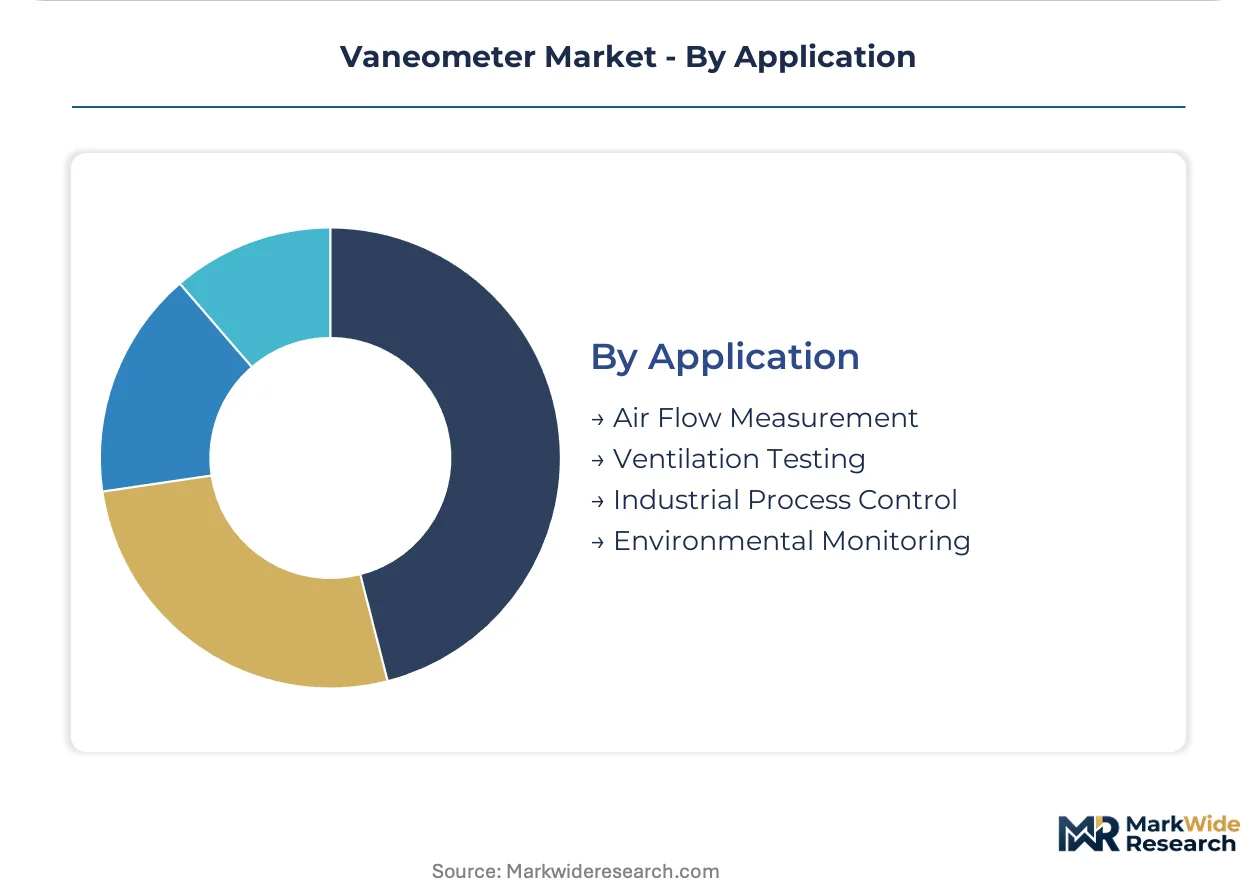
Application:
Use-case segmentation reflects divergent accuracy tolerances, certification requirements, and integration complexity.
- Industrial Process Control:Embedded airflow monitoring stabilizes combustion, drying, and coating operations. Siemens AG and automation distributors specify integrated sensor packages over standalone instruments.
- Ventilation Testing:Commercial building commissioning and OSHA confined-space verification drive portable instrument turnover. United States contractors face dual compliance pressure from EPA and OSHA timelines.
- Environmental Monitoring:Weather stations and ambient air quality networks demand long-term stability and remote data transmission capability.
- Air Flow Measurement:General-purpose velocity profiling spans HVAC balancing, fume hood certification, and filter testing applications.
Volume flows through Ventilation Testing. Value expansion is steepest in Industrial Process Control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates procurement volume under F-Gas Regulation timelines, while the United States compresses replacement cycles through EPA ventilation mandates and OSHA confined-space requirements.
United States
HVAC contractors face dual compliance pressure from EPA ventilation standards and OSHA confined-space airflow rules. Commercial building retrofits in major metropolitan areas mandate calibrated airflow verification with documented traceability. Field service contractors in Texas and California are bundling instrument procurement with multi-year calibration contracts.
Germany
Industrial facility managers prioritize instruments with embedded CE marking and traceable calibration certificates under the EU Green Deal and F-Gas Regulation. Building energy codes in Bavaria and North Rhine-Westphalia accelerate replacement of legacy airflow instruments. Automation distributors in Stuttgart and Munich specify embedded sensor packages over standalone instruments.
China
Domestic sensor manufacturers dominate magnetic and ultrasonic vaneometer core production, tightening component availability for downstream instrument builders. Yangtze River Delta and Pearl River Delta clusters supply sensing cores to global instrument assemblers. Local production capacity expansion is compressing lead times for magnetic encoder modules.
Japan
Metrology-grade instrument demand concentrates in research institutions and semiconductor fabrication facilities under METI industrial standards. Kanto and Kansai regions specify high-precision velocity profiling for cleanroom applications. Domestic manufacturers maintain captive production of optical sensing cores for laboratory reference instruments.
United Kingdom
Building energy audit mandates under evolving carbon reduction frameworks drive instrument turnover in commercial portfolios. London and Southeast England concentrate HVAC service contractor procurement of portable digital units. Calibration infrastructure investment lags continental Europe, creating service bundling opportunities for continental suppliers.
Vaneometer Market Competitive Landscape
European producers anchor one tier; Asian component specialists hold upstream control over sensing core supply. The vendor base stratifies across three tiers: diversified industrial automation conglomerates with embedded airflow portfolios, environmental instrumentation specialists with Nordic R&D positioning, and regional test-equipment distributors with service bundling capabilities. Competitive moves concentrate on vertical integration into sensing core production and geographic expansion through automation channel partnerships.
Among environmental instrumentation specialists, Vaisala and Campbell Scientific occupy positions at opposite ends of the integration spectrum. Vaisala exemplifies the premium-tier archetype with Nordic R&D-based positioning in environmental monitoring applications. Campbell Scientific anchors North American demand through specialized data-logging integration. Siemens AG sits within the industrial automation conglomerate tier, competing across European channels with embedded airflow solutions rather than standalone instruments.
| Leading Market Players |
|---|
| Vaisala |
| Gill Instruments |
| FT Technologies |
| PCE Instruments |
| OMEGA Engineering |
| Siemens AG |
| Campbell Scientific |
| Thies Clima |
| NRG Systems |
| Others |
Value Network & Pricing Analysis
HVAC contractors in the United States commercial retrofit segment anchor procurement volume and compress pricing power toward bundled service contracts. This buyer concentration forces instrument assemblers to absorb magnetic encoder cost volatility while competing on calibration attachment rates.
Pricing Analysis
Capacity additions in China are reshaping price floors for magnetic sensing cores while ultrasonic modules retain premium positioning in pharmaceutical specifications. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17025-certified laboratory instruments from field-service portable units and basic analog dial models. Price differentiation hinges on calibration traceability documentation and CE marking compliance. Cost compression in rotary instrument tiers intensifies because Chinese manufacturers flood magnetic encoder supply. HVAC contractors show highest price sensitivity; semiconductor cleanroom operators show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for embedded automation integration while traditional test-equipment distributors serve fragmented field-service procurement. Component supply concentrates in China, Germany, and Japan for magnetic encoders, precision machining, and optical reference cores respectively. Downstream instrument assembly draws from neodymium magnet supply, ultrasonic transducer ceramics, and calibrated impeller castings. Single-source vulnerability concentrates in Yangtze River Delta magnetic sensor foundries. Distribution runs through automation distributors in Stuttgart and Munich, plus HVAC service contractor networks in Texas and California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vaneometer market functions as a geographic-arbitrage play where German F-Gas Regulation compliance costs exceed United States EPA ventilation mandates by a factor that rewards multi-region certification strategies.
For Market Incumbents: Hedge against Chinese magnetic encoder supply concentration by cultivating secondary sourcing relationships with Japanese optical core manufacturers or captive production partnerships in South Korea. Defend specification channels in German industrial automation by accelerating CE marking documentation and embedded data-logging integration. Threat of ultrasonic technology displacement in cleanroom segments demands R&D investment in sealed-housing architectures. For New Entrants and Emerging Players: Launch via calibration-service bundling models targeting United Kingdom commercial building portfolios where infrastructure investment lags continental Europe. White-space concentrates in healthcare HVAC upgrades for hospital surgical suites under evolving particulate filtration standards. Most penetrable segment: portable digital units for OSHA confined-space verification in Texas and California field-service markets. Go-to-market angle: multi-year calibration contracts with documented traceability chains. For Investors and Strategic Acquirers: Industrial automation conglomerates with embedded sensor portfolios are the most active acquirer in this space. Long-term viability over a five-to-ten year window rests on backward integration into magnetic or ultrasonic core production. Acquisition target archetype: regional test-equipment distributors with captive calibration laboratories and HVAC contractor relationships. Signal to watch: EPA ventilation standard enforcement intensity in United States commercial building retrofits as volume inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensing Cores | Captive magnetic encoder production insulates margin from Chinese supply volatility. |
| CE Marking and Calibration Certification Investment | German F-Gas Regulation compliance creates specification barrier for uncertified competitors. |
| Embedded Automation Integration | Siemens AG and Stuttgart distributors specify native data-logging over standalone instruments. |
| Healthcare HVAC Service Bundling | Hospital surgical suite upgrades demand documented traceability chains under filtration standards. |
| Ultrasonic Cleanroom Architecture Development | Semiconductor fabricators in Kanto and Bavaria specify non-contact measurement for contamination elimination. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary research incorporated interviews with HVAC contractor procurement managers, industrial automation distributor technical directors, calibration laboratory metrologists, and semiconductor facility engineering leads. Secondary sources included EPA ventilation standard filings, EU F-Gas Regulation implementation documents, ISO 17025 accreditation databases, and customs trade data for magnetic encoder imports. Bottom-up instrument shipment analysis triangulated against top-down building retrofit spending estimates.
Granularity-level framing applied product architecture, end-use vertical, sensing technology, and geographic regulatory cluster as core segmentation dimensions. Value projections across the analysis window modeled unit shipments against average selling price trajectories for digital, portable, analog, and bench-top categories. CAGRs derived from regression analysis of historical replacement cycles and regulatory compliance timeline acceleration. Industry-specific forecast inputs included F-Gas Regulation audit frequency assumptions and EPA ventilation standard enforcement intensity indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under tariff escalation scenarios for Chinese magnetic components or accelerated ultrasonic technology substitution in pharmaceutical cleanrooms. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Oil Drain Valves Market
Valves
Global Valve Positioners Market
Valves
Pipeline Pigging Valves Market
Valves
Global Fluid Management Systems Market
Valves
Fluid Handling Systems Market
Valves
Global Plug Valve Market
Valves
Backflow Preventers Market
Valves
Tank Hydrogen Valve Market
Valves
Diaphragm Valve Market
Valves
Valve Seat Inserts Market
Valves
Battery Safety Valve Market
Valves
Naval Actuators and Valves Market
Valves
Large Bore Vacuum Insulated Pipe Market
Valves
Safety Valve Test Benches Market
Valves
Chemical Injection Skid Market
Valves
Global Check Valve Market