
 Europe Industrial Valves Market | 2026-2036
Europe Industrial Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Industrial Valves Market Foresight
Power generation is broadening its share of European valve procurement as utilities retrofit combined-cycle gas turbine plants and expand hydrogen-ready infrastructure. IMI leverages its position in severe-service valve solutions for thermal power stations across the United Kingdom and Scandinavia. KSB anchors its competitiveness through deep vertical integration in pump-valve system integration for water and energy utilities. Emerson Electric Co. differentiates via digital valve positioning and predictive maintenance platforms deployed across German chemical complexes.
Industrial valves are mechanical devices engineered to control, regulate, or isolate fluid flow in pipelines and process systems, typically constructed with pressure ratings up to PN 640 and temperature tolerances spanning cryogenic to superheated conditions. Ball valves deliver tight shutoff with quarter-turn actuation, while gate valves dominate high-pressure steam lines in power generation due to straight-through flow paths and minimal pressure drop. Stainless steel commands premium positioning in corrosive chemical and pharmaceutical environments, whereas cast iron sustains volume leadership in municipal water distribution networks where cost efficiency outweighs exotic material requirements.
The EU Pressure Equipment Directive and ATEX standards mandate certified material traceability and explosion-proof actuation for valves deployed in hazardous process environments, elevating compliance costs for non-integrated suppliers. ECHA's REACH restrictions on lead and chromium compounds are accelerating material substitution toward low-lead bronze alloys and engineered plastic trim components. Stakeholders must monitor how the EU Carbon Border Adjustment Mechanism reshapes sourcing economics for cast and forged valve bodies imported from outside the trading bloc.
Market Dynamics
The EU F-Gas Regulation and Industrial Emissions Directive are compressing acceptable leakage thresholds, forcing wholesale replacement of legacy valve populations across chemical processing, power generation, and hydrogen infrastructure.
Growth Catalysts
- Water infrastructure renewal:Germany, France, and Italy are executing multi-year pipeline modernization programs that specify stainless steel and cast iron valve assemblies for municipal distribution networks.
- REACH material substitution:ECHA restrictions on lead and chromium compounds are accelerating demand for low-lead bronze alloys and engineered plastic trim components in potable water and food processing applications.
- Hydrogen-ready infrastructure:Utilities across the Netherlands and Denmark are specifying high-pressure ball valves and metal-seated gate valves for blending and pure hydrogen transmission systems.
Market Restraints
- Alloy input volatility:Nickel and molybdenum price swings compress margin stability for stainless steel valve fabricators serving corrosive process environments.
- Foundry concentration:Cast iron valve body production concentrates in eastern European and Turkish facilities, exposing buyers to energy cost pass-throughs and logistics bottlenecks.
- Certification friction:The Pressure Equipment Directive and ATEX standards impose multi-month approval timelines for explosion-proof actuation systems, delaying project commissioning.
Strategic Opportunities
- Carbon Border Adjustment Mechanism positioning:The EU CBAM creates sourcing advantages for valve producers with captive European foundry capacity versus importers of cast and forged bodies from outside the trading bloc.
- Predictive maintenance convergence:Digital valve positioning systems combined with cloud-based analytics platforms are opening service revenue streams among German chemical complexes and Scandinavian pulp mills.
- Polish industrial cluster expansion:Petrochemical investment in Płock and Gdańsk is generating demand for severe-service valves in refinery expansion and LNG terminal projects.
Industry Challenges
- Welding certification scarcity:Qualified orbital welders for high-purity pharmaceutical and semiconductor valve systems command premium wages and extended recruitment cycles.
- Legacy system integration:Retrofitting smart valve actuators into existing DCS architectures requires custom protocol gateways that extend commissioning timelines and inflate project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Industrial Valves Market |
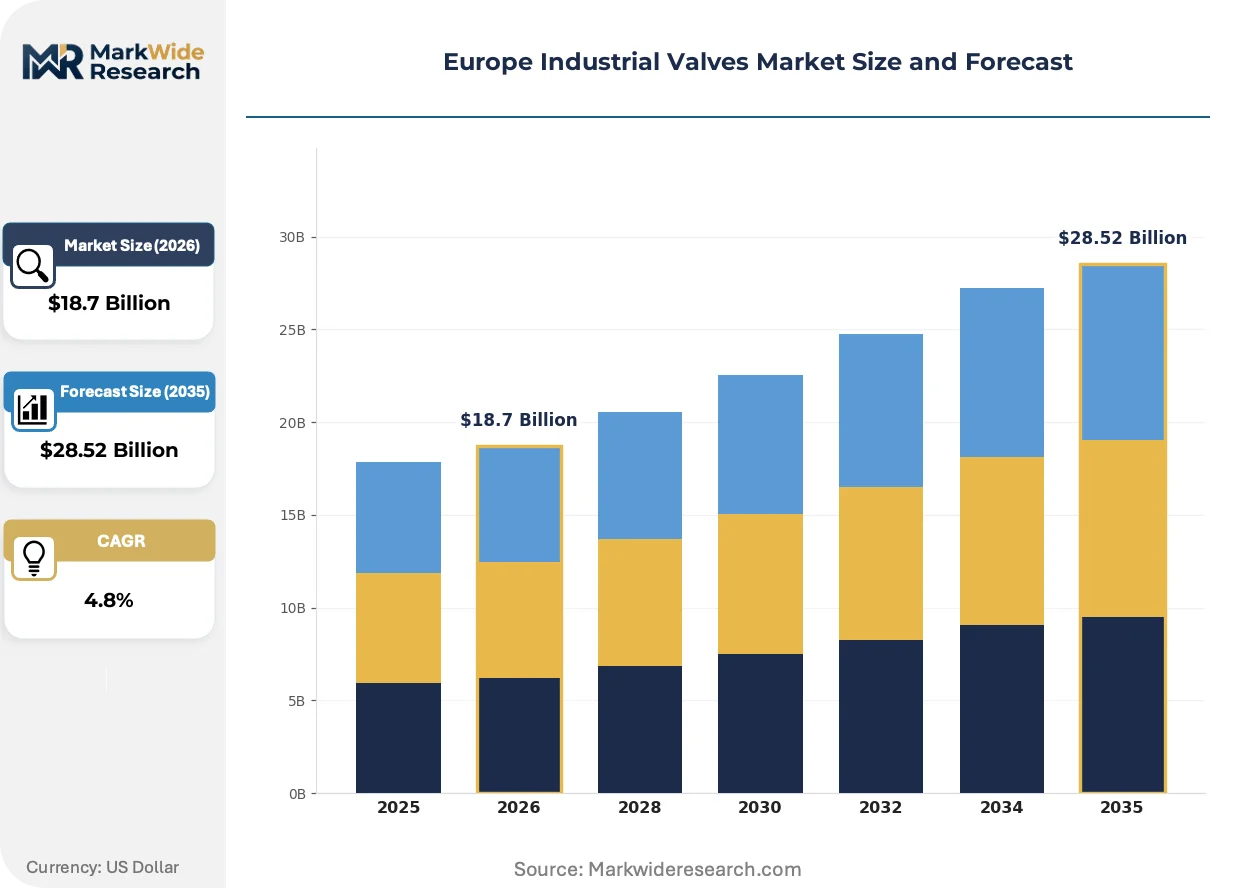
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Ball Valve, Gate Valve, Globe Valve, Check Valve Material: Stainless Steel, Cast Iron, Bronze, Plastic Application: Oil & Gas, Water Treatment, Power Generation, HVAC End User: Manufacturing, Construction, Energy, Chemicals |
| Companies Covered | IMI, AVK Holding A/S, Metso, Emerson Electric Co., Flowserve Corporation, Crane Company, Alfa Laval Corporate AB, KSB, Danfoss, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Industrial Valves Market Shifts & Advancements
Digital instrumentation, material science advances, and procurement model evolution are restructuring how European valve buyers specify, source, and maintain flow control assets across process industries.
Smart valve positioning systems with embedded pressure and temperature sensors are integrating edge computing capabilities for real-time diagnostics. German chemical complexes and UK power utilities are deploying these systems at scale to compress unplanned outage frequency. The technology is integrating predictive maintenance workflows that shift service revenue from reactive repair to subscription-based performance contracts.
The EU F-Gas Regulation is tightening leakage-rate thresholds for valves deployed in refrigeration and air conditioning systems. Manufacturers must now certify products to EN 378 and ISO 14903 testing protocols, elevating R&D spend for seal and packing innovations. Italian and Spanish HVAC contractors are responding by consolidating procurement around suppliers with pre-certified low-emission valve portfolios.
Asset-as-a-service contracting is displacing traditional capital purchase models among water utilities facing budget constraints. French and Belgian municipal operators are leasing valve and pump assemblies with bundled maintenance, transferring lifecycle risk to OEM service organizations. This restructuring concentrates procurement authority at regional utility holding companies, reducing the addressable vendor base for standalone valve suppliers.
Europe Industrial Valves Market Segmentation
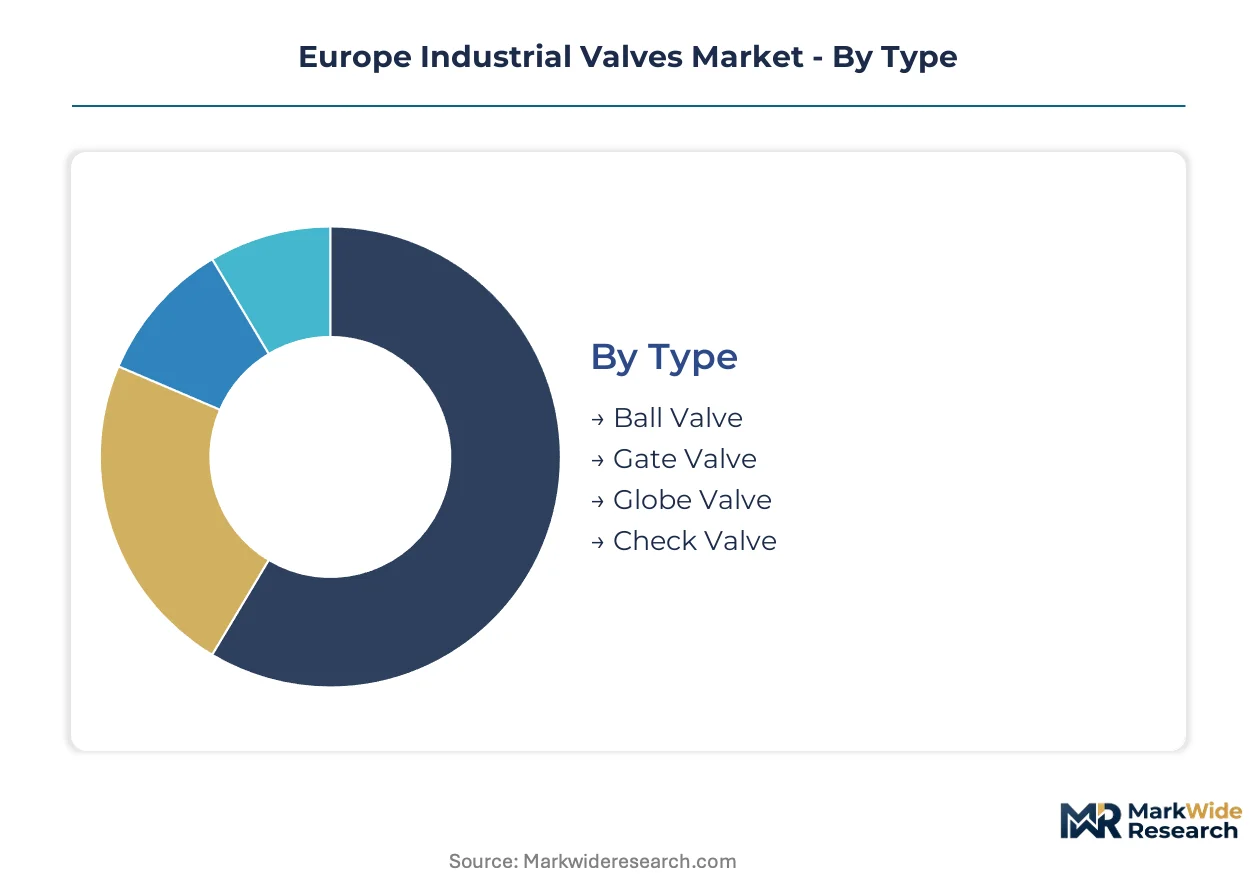
Valve specification across Europe hinges on matching pressure-temperature ratings to specific process hazards while navigating divergent material certification requirements under the Pressure Equipment Directive. Procurement patterns reveal a split between standardized commodity valves for municipal infrastructure and engineered-to-order assemblies for severe-service chemical and power applications.
Type:
The customization-standardization spectrum spans from mass-produced quarter-turn valves to fully engineered multi-turn configurations requiring application-specific trim design.
- Ball Valve:Quarter-turn actuation delivers bubble-tight shutoff through floating or trunnion-mounted ball configurations. German chemical complexes and Dutch hydrogen blending stations are specifying metal-seated variants rated for 100-bar-plus pressures as energy infrastructure pivots toward hydrogen readiness.
- Gate Valve:Straight-through flow paths with minimal pressure drop dominate high-pressure steam lines in combined-cycle gas turbine plants across the United Kingdom and Italy. Rising-stem designs facilitate visual position indication for safety-critical isolation duties in power generation.
- Globe Valve:Throttling precision suits flow modulation in pharmaceutical and fine chemical processing where pressure drop tolerance exists.
- Check Valve:Passive backflow prevention concentrates in water distribution networks and pump discharge protection across French and Belgian municipal systems.
Most installed capacity flows through Gate Valve configurations in legacy thermal power infrastructure. Expansion is steepest in Ball Valve demand driven by hydrogen transmission and chemical process intensification.
Material:
Cost tier stratification separates premium corrosion-resistant alloys from commodity cast grades serving budget-constrained municipal buyers.
- Stainless Steel:Austenitic and duplex grades withstand chloride attack in offshore oil and gas, desalination, and aggressive chemical environments. Norwegian North Sea platforms and Spanish petrochemical complexes specify super-duplex 2507 for seawater and acid gas service where failure costs dwarf material premiums.
- Cast Iron:Ductile iron bodies with epoxy coating dominate volume procurement in German, French, and Italian water distribution renewal programs where burial life exceeds fifty years at minimal capital cost.
- Bronze:Lead-free alloys satisfy ECHA REACH restrictions in potable water and food processing applications across the European Union.
- Plastic:PVC and PVDF constructions serve corrosive chemical handling in semiconductor fabrication and electroplating facilities where metal contamination is prohibitive.
Cast Iron retains the largest installed base across municipal infrastructure. Stainless Steel is climbing the fastest as process industries tighten corrosion allowances and extend maintenance intervals.
Application:
Customer type differentiation separates project-driven capital expenditure from recurring maintenance procurement with divergent vendor relationship models.
- Oil & Gas:Exploration, production, and refining operations demand API-certified valves for wellhead, pipeline, and process isolation. Norwegian continental shelf developments and Polish refinery expansions in Płock are driving severe-service metal-seated requirements.
- Water Treatment:Municipal distribution, wastewater, and desalination facilities specify resilient-seated valves for bi-directional sealing. German Ruhr region utilities are consolidating procurement around integrated pump-valve packages with predictive maintenance telemetry.
- Power Generation:Combined-cycle, nuclear, and emerging hydrogen-ready turbine plants require high-integrity isolation for steam, feedwater, and fuel gas systems.
- HVAC:Commercial building climate control concentrates demand for compact bronze and brass valves with low-lead certification under evolving ECHA restrictions.
Water Treatment channels the greatest valve volume through municipal renewal programs. Power Generation is expanding most quickly as hydrogen-ready turbine retrofits accelerate across the Netherlands and Denmark.
End User:
Supply concentration varies sharply between fragmented construction project procurement and concentrated utility fleet standardization.
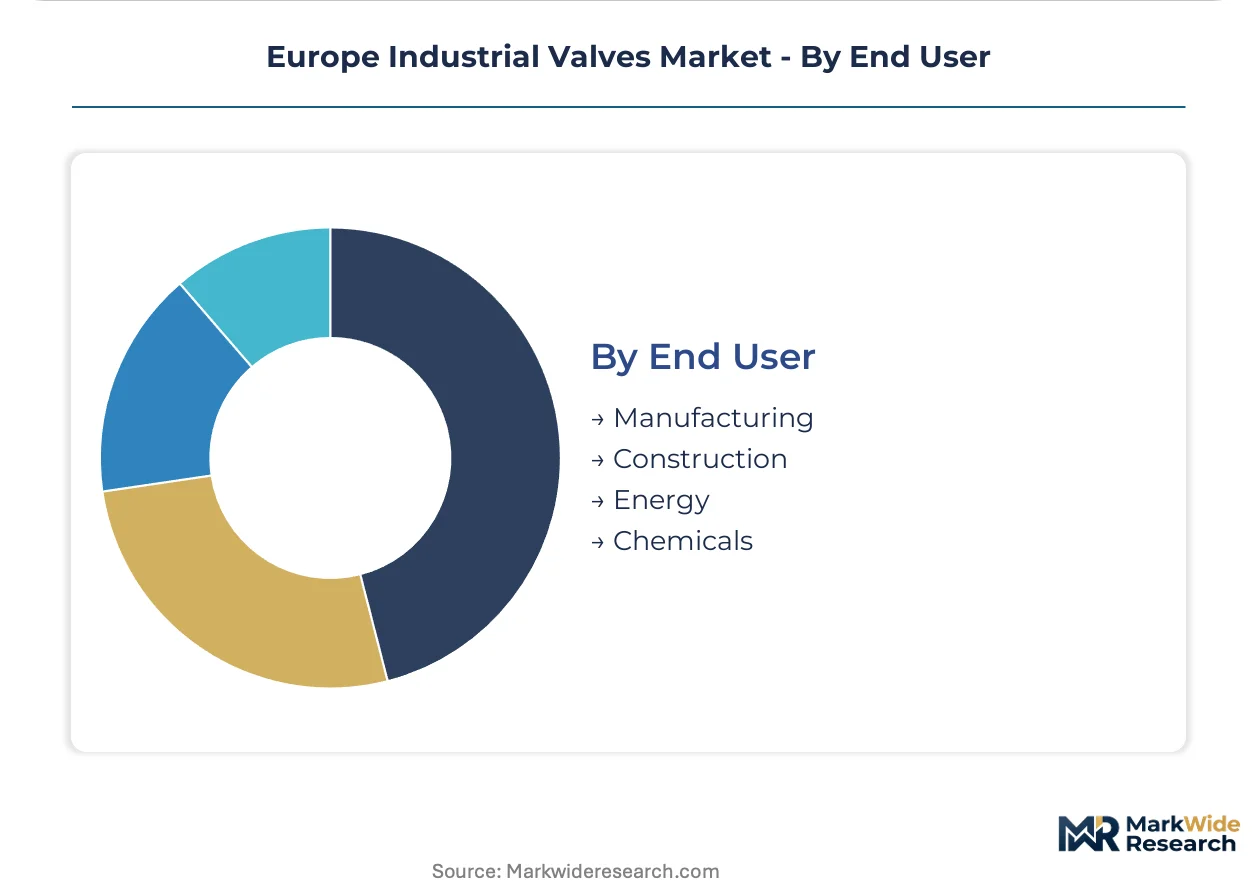
- Manufacturing:Process industries including automotive, food and beverage, and pharmaceuticals specify hygienic and sanitary valve configurations. Italian and Spanish packaging machinery OEMs drive demand for compact pneumatic actuation.
- Construction:Building services and infrastructure projects procure through contractor channels with price-sensitive tender processes. French and Belgian commercial developments are shifting toward asset-as-a-service leasing models that concentrate vendor selection.
- Energy:Integrated oil companies and utilities maintain approved manufacturer lists with stringent qualification protocols for critical service.
- Chemicals:BASF, Bayer, and specialty chemical clusters in Germany's Rhine corridor specify severe-service valves with full material traceability and digital position monitoring.
Energy sector procurement represents the largest committed spend through long-term frame agreements. Chemicals is gaining share fastest as process intensification and digitalization investments concentrate flow control upgrade budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as foundry economics diverge across compliance-cost boundaries within the European trading bloc. Producers with captive European melting capacity gain structural advantage under the EU Carbon Border Adjustment Mechanism, while importers of cast and forged valve bodies face escalating tariff-equivalent charges.
Germany
The Ruhr industrial cluster sustains dense demand for severe-service valves in petrochemical maintenance and power generation retrofit cycles. The EU F-Gas Regulation compresses leakage thresholds for refrigeration and air conditioning systems, forcing wholesale replacement of legacy valve populations. BASF and Bayer facilities in the Rhine corridor specify full material traceability and digital position monitoring for process intensification projects.
United Kingdom
Combined-cycle gas turbine plant retrofits and hydrogen-ready infrastructure expansion are concentrating valve procurement among utility fleet operators. The UK Environment Agency enforces emissions performance standards that accelerate replacement schedules in thermal power stations. IMI leverages its position in severe-service solutions across power generation assets in Scotland and northern England.
France
Municipal water distribution renewal programs specify stainless steel and cast iron valve assemblies for pipeline modernization spanning multiple decades. ECHA REACH restrictions on lead and chromium compounds drive material substitution toward low-lead bronze alloys in potable water applications. French municipal operators are consolidating procurement around asset-as-a-service leasing models that transfer lifecycle risk to OEM service organizations.
Netherlands
Utilities are specifying high-pressure ball valves and metal-seated gate valves for hydrogen blending and pure hydrogen transmission infrastructure. The Dutch Emissions Authority enforces Industrial Emissions Directive compliance timelines that compress project commissioning windows. Port of Rotterdam hydrogen hub development is generating demand for cryogenic-rated isolation valves in import terminal construction.
Poland
Petrochemical investment in Płock and LNG terminal projects in Gdańsk are generating severe-service valve demand in refinery expansion and gas infrastructure. The Polish Office of Competition and Consumer Protection monitors procurement concentration effects as utility holding companies consolidate vendor selection. Silesian industrial zones are experiencing accelerated replacement cycles as EU cohesion funds finance environmental compliance upgrades.
Europe Industrial Valves Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated OEMs commanding premium positioning in severe-service applications while foundry-dependent fabricators compete on cost in municipal infrastructure. The vendor base organizes into three tiers: global diversified industrials with full lifecycle service capabilities, regional specialists with deep vertical integration in pump-valve system integration, and commodity producers serving price-sensitive tender processes. Dominant competitive moves include backward integration into captive foundry capacity and predictive maintenance platform deployment to capture recurring service revenue.
Among diversified European industrials, IMI plc and KSB SE anchor premium-tier positioning through severe-service specialization and system integration capabilities respectively. Emerson Electric Co. occupies a position at the convergence of digital instrumentation and process control, exemplifying the predictive maintenance archetype. AVK Holding A/S represents the municipal infrastructure specialist model with concentrated exposure to water distribution renewal programs.
| Leading Market Players |
|---|
| IMI |
| AVK Holding A/S |
| Metso |
| Emerson Electric Co. |
| Flowserve Corporation |
| Crane Company |
| Alfa Laval Corporate AB |
| KSB |
| Danfoss |
| Others |
Supply & Pricing Matrix
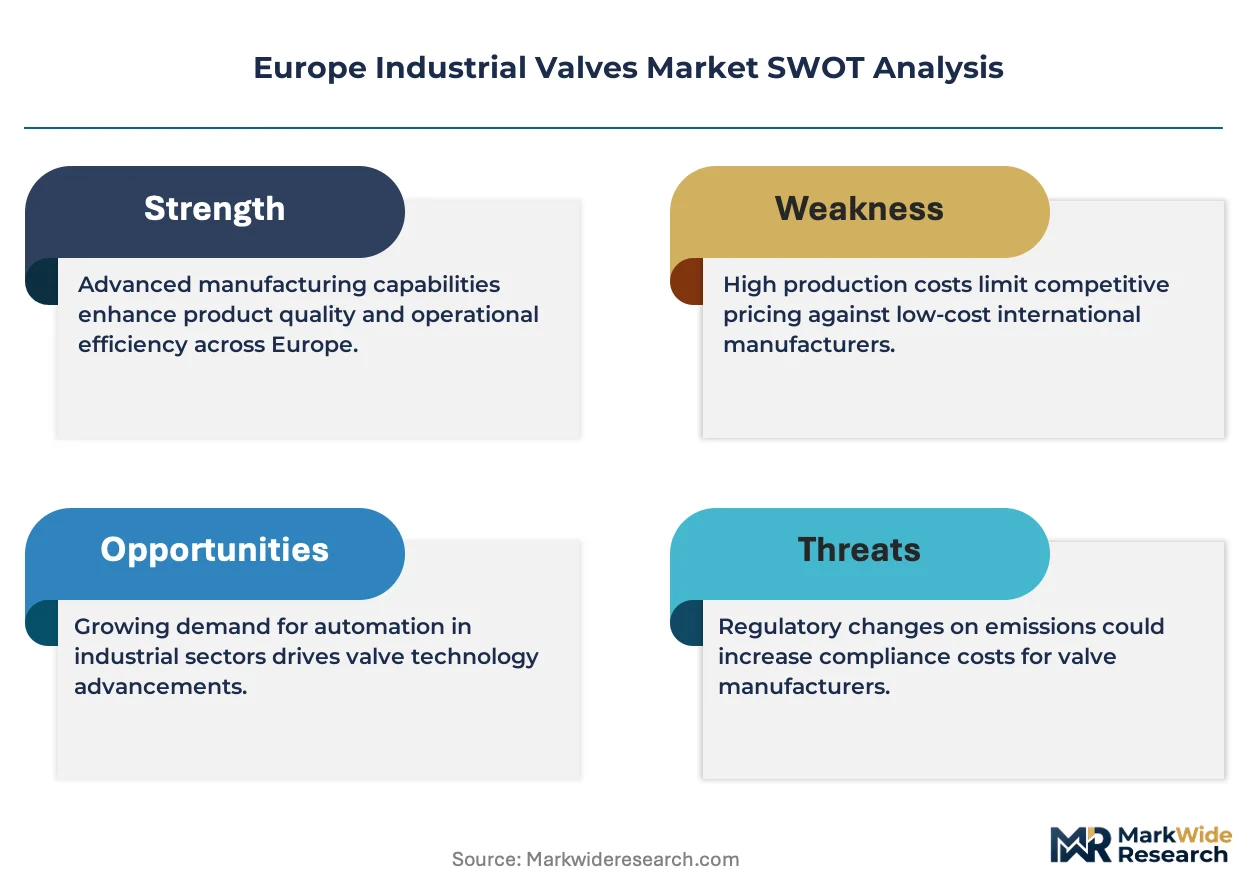
Family-owned mid-cap valve fabricators across Germany and northern Italy anchor supply discipline through generational capital structures that resist short-term margin compression, translating into stable pricing for stainless steel severe-service assemblies even as commodity cast iron fluctuates with energy input costs. Their patient ownership models sustain multi-year supplier relationships with Ruhr basin foundries and Scandinavian forging houses, insulating premium-tier procurement from spot-market volatility that destabilizes tender-driven municipal buyers.
Pricing Analysis
Distributor margins of 18-25 percent on engineered-to-order valves separate project-based pricing for chemical and power applications from direct-to-OEM discounts that water utilities extract through consolidated frame agreements. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade under the Pressure Equipment Directive and ATEX standards, with explosion-proof actuation commanding substantial premiums. Cost compression in cast iron municipal valves is intensifying because Turkish and eastern European foundries pass through energy cost volatility, while German chemical complexes show least price sensitivity for super-duplex stainless steel where failure costs dominate lifecycle economics.
Supply Chain Analysis
Qualified orbital welders for high-purity pharmaceutical valve systems concentrate in Germany's Rhine corridor and Switzerland's precision manufacturing belt, constraining capacity expansion for severe-service fabricators serving BASF and Novartis specifications. Valve body supply concentrates in Germany, Italy, and Poland for forged stainless steel, while cast iron production draws from Turkey and eastern European facilities. Nickel and molybdenum price volatility creates commodity cost risk that amplifies margin instability for duplex alloy producers. Distribution runs through authorized distributor networks for engineered valves and direct tender channels for municipal water infrastructure procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Industrial Valves Market functions as a geographic-arbitrage play where captive foundry capacity in Germany and Italy captures structural advantage under the EU Carbon Border Adjustment Mechanism against importers of cast bodies from Turkish and Asian facilities facing escalating tariff-equivalent charges.
For Market Incumbents: Deepen backward integration into captive European melting capacity to defend margin position against CBAM-adjusted import competition, while accelerating predictive maintenance platform deployment to capture recurring service revenue from German chemical complexes and Scandinavian pulp mills. The threat of asset-as-a-service contracting displacing capital sales demands counter-positioning through lifecycle performance guarantees. For New Entrants and Emerging Players: The EU F-Gas Regulation in the Netherlands and Denmark opens a window for specialized low-emission valve portfolios targeting hydrogen blending infrastructure, where incumbent certification lags create penetrable white space. Focus initial market entry on Polish petrochemical expansion in Płock and Gdańsk LNG terminals, leveraging severe-service metal-seated expertise as a beachhead for broader chemical sector qualification. For Investors and Strategic Acquirers: Valuations sit cheapest among foundry-dependent fabricators exposed to energy cost pass-throughs and CBAM tariff risk, suggesting distressed acquisition opportunities as margin compression forces consolidation. Target mid-cap specialists with captive forging capacity and established Pressure Equipment Directive certification infrastructure. The signal to watch is CBAM implementation pace and Turkish foundry export pricing responses as inflection indicators for sourcing economics restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Foundry Capacity | CBAM compliance advantages accrue to producers with in-house European melting operations versus import-dependent competitors. |
| Predictive Maintenance Platform Deployment | Emerson Electric Co. exemplifies digital valve positioning convergence that shifts revenue from reactive repair to subscription contracts. |
| Hydrogen-Ready Certification Investment | Metal-seated ball valve qualification for 100-bar hydrogen service addresses Dutch and Danish utility procurement specifications. |
| Asset-as-a-Service Contracting Capability | French and Belgian municipal operators are consolidating procurement around leasing models that transfer lifecycle risk to OEM service organizations. |
| REACH-Compliant Material Substitution | Low-lead bronze alloy and engineered plastic trim development satisfies ECHA restrictions in potable water and food processing applications. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study, combining structured interviews with maintenance directors at German chemical complexes, plant engineers in the Ruhr industrial cluster, OEM procurement teams at water utilities, and aftermarket service heads at power generation operators. Secondary validation draws from customs and trade data, Cefic chemical industry reports, SEC 10-K filings of listed valve manufacturers, and project development databases for hydrogen infrastructure. Triangulation between demand-side consumption patterns and supply-side production capacity ensures consistency across volume and value estimates.
Historical trendline analysis of replacement cycle frequencies, infrastructure investment patterns, and regulatory compliance deadlines establishes baseline growth trajectories across the projection horizon. Segmentation modeling spans valve type, material grade, application sector, and end-user concentration, with CAGRs derived from regression analysis against industrial production indices and energy transition investment flows. Forecast inputs incorporate hydrogen-ready infrastructure buildout timelines, EU cohesion fund disbursement patterns for environmental upgrades, and foundry capacity utilization rates as industry-specific demand drivers.
Revisions become necessary when CBAM tariff implementation accelerates, nickel and molybdenum price volatility exceeds historical bands, or welding certification scarcity constrains severe-service valve delivery timelines. Material deviation in these named triggers warrants pause and re-evaluation of sourcing economics and capacity expansion assumptions embedded in the analysis.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Backflow Preventers Market
Valves
Liner Regulators Market
Valves
Hybrid Valve Market
Valves
Top Drive Systems Market
Valves
Butterfly Valves Market
Valves
Degassing Valves Market
Valves
Valve Driver Market
Valves
Europe Electro Hydraulic Servo Valve Market
Valves
Cathodic Protection Market
Valves
Electro Pneumatic Positioner Market
Valves
Aerospace Valves Market
Valves
Industrial Hydraulic Filters Market
Valves
GCC and MENA Valves Market
Valves
Global Level Gauge Market
Valves
Subsea Control System Market
Valves
Curb Valves Market