
 Global Pipette Tips Market | 2026-2036
Global Pipette Tips Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pipette Tips Market Foresight
The EU Medical Device Regulation is recalibrating the cost-of-entry calculus for pipette tip manufacturers serving European clinical labs. Thermo Fisher Scientific leverages its vertically integrated polymer supply chain to sustain margin stability under these compliance burdens. Eppendorf anchors its position through precision molding expertise developed at its Hamburg manufacturing base. Sartorius competes by specializing in low-retention surface technologies that command premium positioning in pharmaceutical QC workflows.
Pipette tips are precision-molded polymer cones, typically manufactured from medical-grade polypropylene via high-cavitation injection molding with tolerances below 0.1 millimeters, designed to create sealed air-displacement interfaces for accurate microliter-volume liquid transfer in quantitative laboratory procedures. Filter tips now lead product type value generation due to cross-contamination liability in diagnostic settings, while low retention variants represent the fastest-expanding margin pool as peptide and antibody workflows proliferate. Molecular biology applications command the largest application share, though clinical diagnostics is displacing traditional research volume as hospital labs automate high-throughput testing protocols.
FDA quality system regulations, EU MDR technical documentation requirements, and ISO 13485 medical device quality management standards collectively shape product validation burdens and OEM access strategies across major markets. The EPA's emerging per- and polyfluoroalkyl substance scrutiny is beginning to constrain fluoropolymer tip formulations in environmental testing applications. Stakeholders must monitor regulatory divergence between FDA's risk-based device classification approach and EMA's expanding IVDR scope to determine whether to maintain unified product platforms or pursue region-specific certification pathways.
Market Dynamics
The pipette tips market faces a structural compression between EU MDR compliance documentation burdens and the automation-driven volume consolidation among diagnostic laboratory networks.
Growth Catalysts
- IVDR scope expansion:The EU In Vitro Diagnostic Regulation mandates enhanced traceability for consumables used in clinical testing, accelerating filter tip replacement cycles in hospital laboratories across Germany and France.
- Peptide therapeutics manufacturing:Contract development organizations in Switzerland and Massachusetts are scaling low-retention tip consumption for high-value biologic workflows.
- Automated liquid handling:Robotic integration in Japanese and South Korean genomic screening facilities is standardizing tip format specifications and locking in volume commitments.
Market Restraints
- Medical-grade polypropylene supply concentration:Polymer feedstock availability tightens around Saudi Aramco and LyondellBasell production hubs, exposing molders to input cost volatility.
- Fluoropolymer formulation constraints:EPA scrutiny of per- and polyfluoroalkyl substances limits low-retention surface chemistry options for environmental testing applications.
- High-cavitation tooling barriers:Precision mold fabrication requires specialized equipment from German and Japanese machine builders, creating capital access bottlenecks for new entrants.
Strategic Opportunities
- Indian diagnostic infrastructure buildout:CDSCO streamlined medical device registration creates entry pathways for CE-marked tip suppliers targeting government hospital tenders.
- Cell therapy manufacturing:GMP-grade sterile tip demand from CAR-T production facilities in Maryland and Singapore outpaces specialized supply.
- Sustainability mandates:EU Green Deal packaging requirements favor bio-based polypropylene development and closed-loop recycling partnerships with clinical waste processors.
Industry Challenges
- ISO 13485 certification timelines:Quality management system audits for medical device classification stretch 12-18 months, delaying market access for reformulated products.
- Legacy LIMS integration:Automated tip handling systems must interface with entrenched laboratory information management platforms from multiple vendors.
- Cross-platform format standardization:Proprietary tip cone geometries from dominant pipettor manufacturers fragment procurement and inflate switching costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pipette Tips Market |
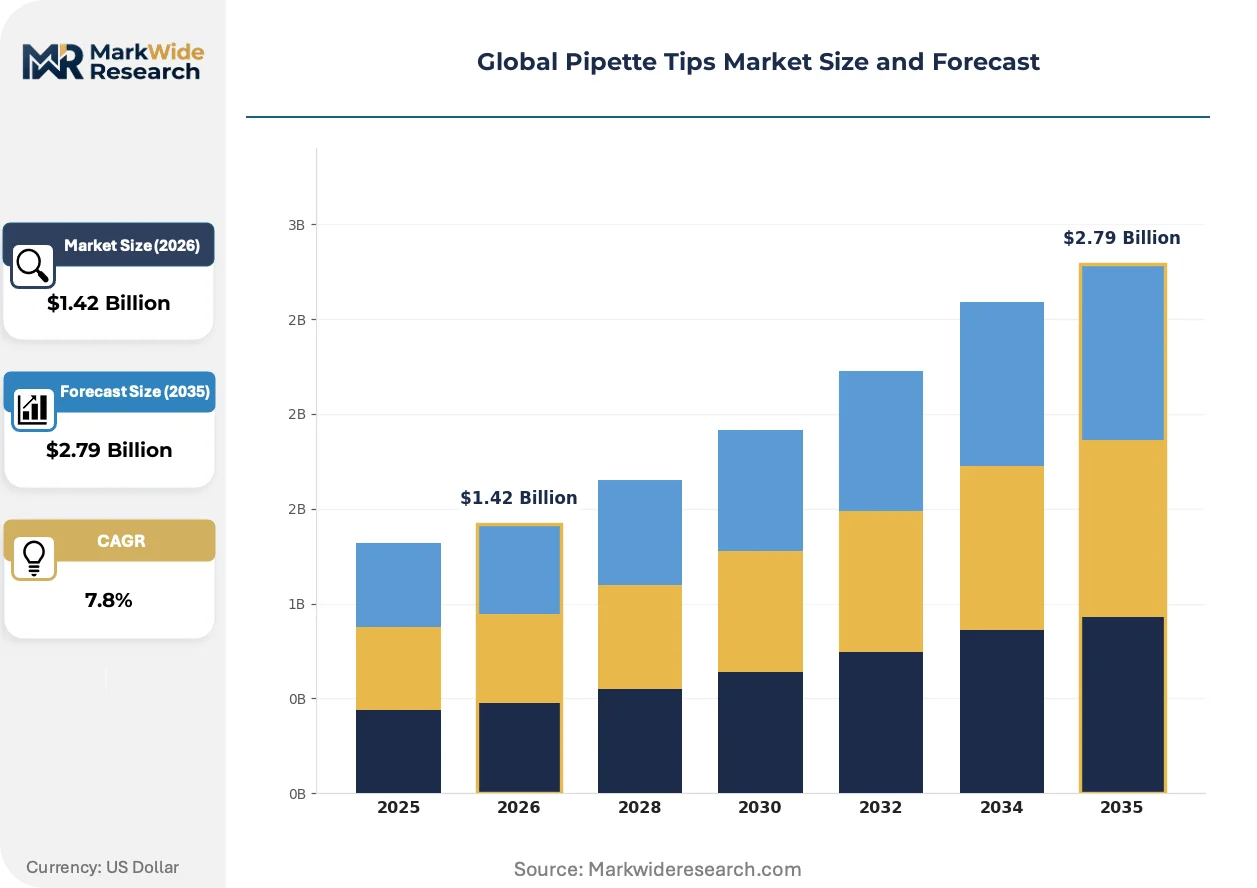
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.79 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polypropylene, Polyethylene, Polystyrene, Silicone, Fluoropolymer Product Type: Filter Tips, Standard Tips, Low Retention Tips, Sterile Tips, Graduated Tips Application: Molecular Biology, Clinical Diagnostics, Pharmaceutical R&D, Environmental Testing, Food Safety End User: Biotechnology Firms, Research Laboratories, Diagnostic Centers, Academic Institutions |
| Companies Covered | Thermo Fisher Scientific, Eppendorf, Sartorius, Corning, Mettler Toledo, Biotix, Sarstedt, Greiner Group AG, Brand GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pipette Tips Market Shifts & Advancements
Automation compatibility and regulatory traceability are compressing product development cycles while surface chemistry innovations unlock premium positioning in biologic workflows.
Conductive polypropylene formulations is unifying electrostatic discharge protection with standard tip geometry, eliminating separate conductive tip SKUs. Pharmaceutical quality control laboratories in Basel and Boston are adopting these materials for sensitive protein assays. The convergence is unifying inventory management and reducing format fragmentation across multi-site manufacturing networks.
REACH substance restriction proposals are tightening scrutiny of slip agents and colorants in medical-grade polymers, forcing reformulation of legacy product lines. Molders serving European clinical diagnostics must resubmit technical documentation under revised chemical safety dossier requirements. Filter tip categories face the steepest compliance burden due to their direct patient-sample contact classification.
Consolidated procurement through group purchasing organizations is compressing distributor margins and favoring direct manufacturer relationships with hospital networks. Diagnostic laboratory chains in Germany and the Netherlands are unbundling tip supply from instrument service contracts. This restructuring is most pronounced in high-throughput COVID-19 testing infrastructure now repurposed for routine clinical chemistry.
Global Pipette Tips Market Segmentation
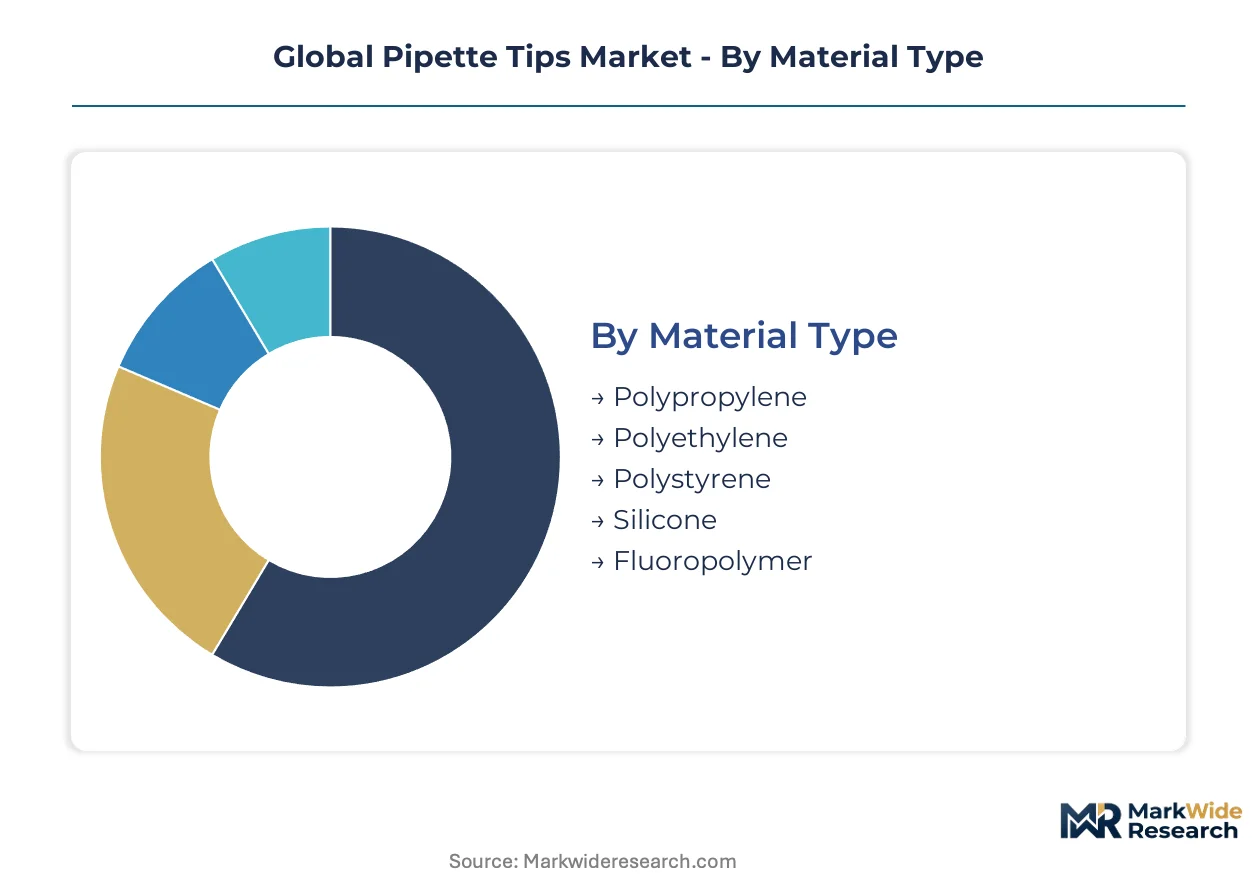
Pipette tip procurement splits across material specifications, contamination control tiers, and workflow integration requirements. Buyers weight sterility assurance, liquid handling precision, and regulatory documentation differently depending on end-use criticality.
Material Type:
Polymer selection hinges on chemical compatibility, surface energy properties, and downstream sterilization protocols.
- Polypropylene:Medical-grade homopolymer dominates injection-molded tip production due to thermal stability and autoclave resilience. Diagnostic laboratories in Germany and the United States specify this material for high-throughput screening workflows where lot-to-lot consistency reduces calibration drift.
- Fluoropolymer:Perfluoroalkoxy formulations enable ultra-low surface energy for viscous liquid handling in peptide synthesis. Massachusetts-based contract development organizations specify these tips for antibody-drug conjugate workflows despite EPA scrutiny constraining formulation options.
- Polyethylene:Lower density variant serves cost-sensitive educational markets and non-sterile research applications.
- Polystyrene:Transparent amorphous polymer finds niche use in optical density measurement protocols requiring visual meniscus confirmation.
- Silicone:Elastomeric formulations enable specialized sealing applications in automated liquid handling manifolds.
Volume sits with polypropylene; growth tilts toward fluoropolymer as biologic drug manufacturing expands.
Product Type:
Contamination liability and liquid retention characteristics drive tiered pricing across product categories.
- Filter Tips:Hydrophobic membrane barriers prevent aerosol cross-contamination in PCR and diagnostic workflows. EU IVDR traceability mandates are accelerating replacement cycles in French and German hospital laboratories.
- Low Retention Tips:Hydrophobic surface coatings minimize sample loss in protein and nucleic acid protocols. Swiss pharmaceutical quality control facilities are adopting these for high-value reagent conservation.
- Standard Tips:Unfiltered general-purpose format serves bulk research consumption with minimal specification overhead.
- Sterile Tips:Gamma-irradiated or ethylene oxide-treated variants meet GMP requirements for cell therapy manufacturing in Maryland and Singapore.
- Graduated Tips:Volume-marked variants support visual confirmation in manual pipetting protocols without integrated liquid level sensing.
Filter tips command the largest revenue pool; low retention variants are climbing the fastest as biologic workflows proliferate.
Application:
Workflow automation intensity and regulatory classification determine specification stringency across use cases.
- Clinical Diagnostics:Automated immunoassay and molecular testing platforms in Japanese and South Korean genomic screening facilities standardize on conductive polypropylene formats with barcode traceability.
- Molecular Biology:PCR, cloning, and sequencing workflows constitute the largest consumption base across academic and biotechnology research settings.
- Pharmaceutical R&D:High-throughput screening and compound management operations in Basel and Boston require low-retention surface chemistry for DMSO-based library handling.
- Environmental Testing:PFAS analysis protocols face EPA method constraints that limit fluoropolymer tip compatibility in water quality laboratories.
- Food Safety:Pathogen detection workflows in regulatory and industrial laboratories specify sterile filter tips for Listeria and Salmonella protocols.
Clinical diagnostics is displacing molecular biology as the primary volume driver; pharmaceutical R&D shows the steepest margin expansion.
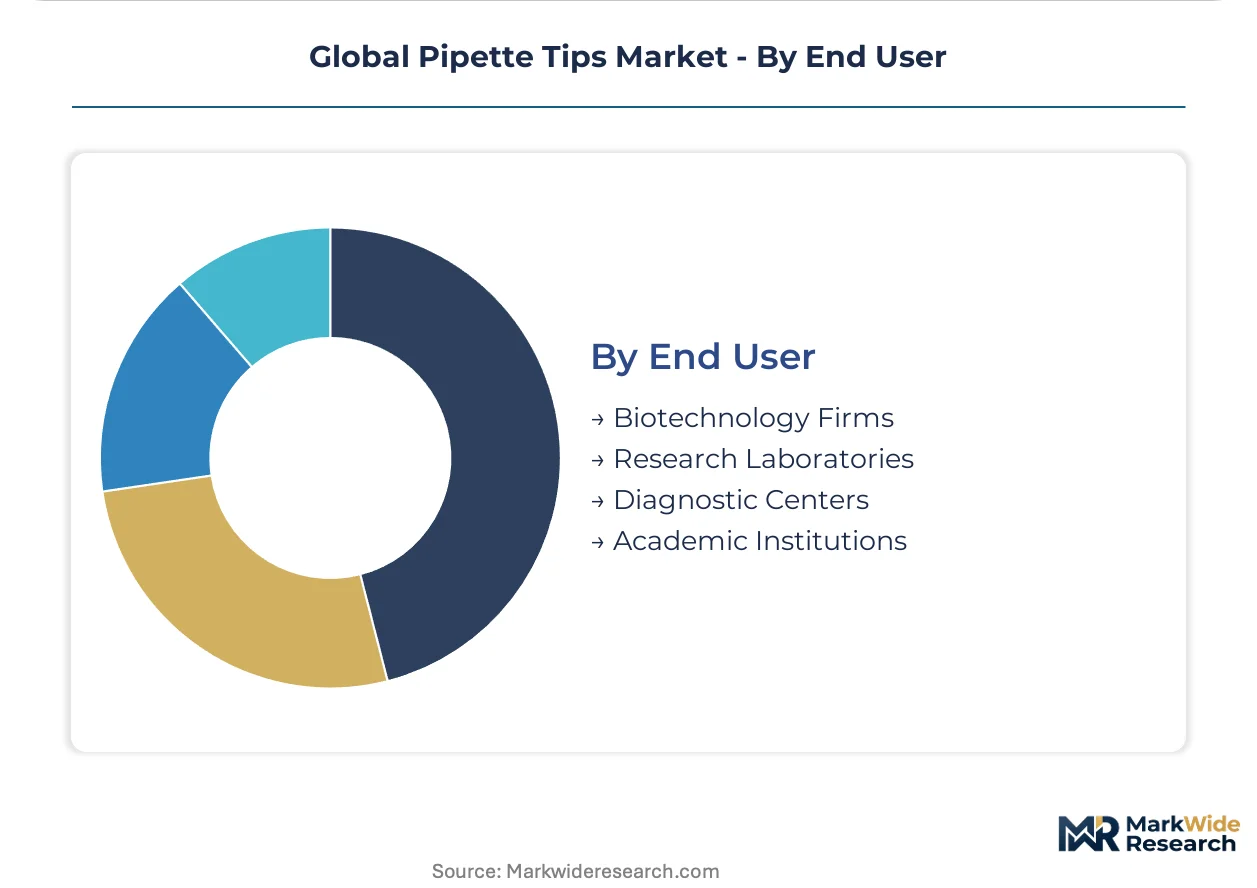
End User:
Procurement centralization and quality system certification requirements fragment buying behavior across customer types.
- Diagnostic Centers:Hospital network consolidation in the Netherlands and Germany is unbundling tip supply from instrument service contracts, favoring direct manufacturer relationships.
- Biotechnology Firms:CAR-T manufacturing facilities in Singapore and Maryland are outstripping GMP-grade sterile tip supply, creating qualification bottlenecks for new vendors.
- Research Laboratories:Academic and government institutions face budget constraints that sustain demand for standard non-sterile formats.
- Academic Institutions:Teaching and training operations prioritize cost efficiency over performance specifications in high-consumption educational settings.
Diagnostic centers concentrate procurement volume; biotechnology firms are gaining share fastest as cell therapy manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's BioRN cluster and Switzerland's Health Valley create concentrated demand nodes for precision consumables. Special economic zones in Singapore and Maryland accelerate cell therapy manufacturing infrastructure. Tax incentives in Massachusetts and Basel-Stadt canton attract biologic drug development operations.
United States
CAR-T manufacturing facilities in Maryland and Massachusetts drive GMP-grade sterile tip consumption. FDA quality system regulations mandate ISO 13485 certification for clinical diagnostic suppliers. The Greater Boston biotech corridor concentrates peptide therapeutic development and automated liquid handling adoption.
Germany
Hospital network consolidation in Bavaria and North Rhine-Westphalia unbundles tip procurement from instrument service contracts. EU MDR technical documentation requirements tighten quality dossier standards for filter tip classifications. The Munich-Heidelberg biotech corridor anchors precision molding expertise and diagnostic laboratory automation.
Switzerland
Contract development organizations in Basel and Zurich scale low-retention tip consumption for antibody-drug conjugate workflows. Swissmedic medical device oversight aligns with EU MDR recognition agreements for streamlined market access. The Health Valley cluster around Basel dominates pharmaceutical quality control and biologic manufacturing.
Japan
Genomic screening facilities in Kanto and Kansai regions standardize conductive polypropylene formats with barcode traceability. PMDA medical device regulations require local quality management system audits for imported consumables. The Tokyo-Yokohama metropolitan area concentrates automated liquid handling integration in diagnostic networks.
Singapore
Cell therapy manufacturing zones in Tuas Biomedical Park outstrip specialized sterile tip supply. The national pharmaceutical regulator streamlines GMP-grade consumable qualification for regional export hubs. Bioprocessing infrastructure investments attract CAR-T production facilities serving Asia-Pacific markets.
Global Pipette Tips Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three distinct capability tiers. Vertically integrated life science conglomerates leverage captive polymer supply chains and instrument installed bases to lock in consumable pull-through. Precision molding specialists compete on surface chemistry innovation and regulatory documentation depth. Regional fabricators serve cost-sensitive educational and research segments through standardized polypropylene formats. Capacity expansion and strategic partnerships constitute the dominant competitive moves as compliance burdens reshape scale economics.
Among Germany-based precision specialists, Eppendorf and Brand GmbH exemplify the molding-expertise archetype anchored in Hamburg and Wertheim respectively. Thermo Fisher Scientific represents the diversified conglomerate model with backward integration into polymer feedstock and diagnostic instrumentation. Sartorius occupies a position within the surface-chemistry specialist tier, competing through low-retention technology development for pharmaceutical quality control applications.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Eppendorf |
| Sartorius |
| Corning |
| Mettler Toledo |
| Biotix |
| Sarstedt |
| Greiner Group AG |
| Brand GmbH |
| Others |
Supply & Pricing Matrix
A three-tier pricing structure across premium, standard, and economy levels bifurcates procurement patterns in the pipette tips market, with EU MDR-certified filter tips commanding sustained premiums while non-sterile research-grade volumes face compression from group purchasing organization consolidation. This certification ladder manifests in supply chain configurations where Hamburg and Wertheim-based molders anchor premium production with captive polymer compounding, while Asian fabricators feed cost-sensitive educational segments through standardized export channels.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement negotiations, with diagnostic laboratory networks in Germany and the Netherlands paying premiums for four-week delivery guarantees on GMP-grade sterile formats while spot inventory of standard polypropylene tips trades at discounts in research surplus markets. Price differentiation rests on ISO 13485 certification tier and conductive polypropylene formulation grade, with IVDR-traceable filter tips resisting downward pressure from automation-driven volume consolidation. Cost compression in the research-grade tier intensifies because distributor margins are collapsing under consolidated procurement mandates. Academic institutions exhibit the highest price sensitivity, while CAR-T manufacturing facilities in Maryland and Singapore demonstrate minimal elasticity for qualified sterile supply.
Supply Chain Analysis
Domestic-content mandates in India's CDSCO streamlined registration pathway are reshaping sourcing strategies for CE-marked suppliers targeting government hospital tenders, accelerating localized molding investments. Geographic supply concentration centers on Germany, the United States, and China, with precision mold fabrication capabilities anchored in Hamburg and Japanese machine builder partnerships. Raw material dependencies draw from Saudi Aramco and LyondellBasell medical-grade polypropylene hubs, with fluoropolymer formulations facing EPA per- and polyfluoroalkyl substance scrutiny. Single-source vulnerability concentrates in high-cavitation tooling from German and Japanese equipment builders. Distribution runs through direct manufacturer relationships with diagnostic networks and group purchasing organization channels serving consolidated hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pipette tips market functions as a cost-of-compliance arena where EU MDR technical documentation burdens erect barrier-to-entry moats favoring incumbents with established quality management systems and regulatory dossier depth.
For Market Incumbents: Hedge against fluoropolymer formulation constraints by accelerating bio-based polypropylene development partnerships with clinical waste processors ahead of EU Green Deal packaging mandates. Expand precision molding capacity in Singapore's Tuas Biomedical Park to capture GMP-grade sterile tip demand from CAR-T manufacturing facilities outpacing regional supply. Backward integration into conductive polypropylene compounding secures margin stability under polymer feedstock volatility from Saudi Aramco and LyondellBasell production hubs. For New Entrants and Emerging Players: Begin with India's CDSCO streamlined registration pathway for CE-marked filter tips targeting government diagnostic infrastructure tenders, the most penetrable geography given unmet demand from hospital network expansion. Specialize in low-retention surface technologies for peptide therapeutic contract development organizations in Switzerland and Massachusetts, where premium positioning offsets compliance investment burdens. Pursue direct procurement relationships with automated liquid handling integrators in Japanese genomic screening facilities to bypass entrenched distributor channels. For Investors and Strategic Acquirers: Re-rating potential sits with precision molding specialists possessing ISO 13485 certification and Hamburg-based manufacturing footprints given IVDR scope expansion accelerating replacement cycles in French and German hospital laboratories. Long-term viability over a multi-year horizon favors targets with demonstrated surface chemistry innovation pipelines and regulatory documentation depth rather than commodity research-grade exposure. Watch for inflection signals in group purchasing organization unbundling trends separating tip supply from instrument service contracts in Dutch and German diagnostic networks.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | Accelerates IVDR-compliant filter tip access to German and French hospital laboratory networks. |
| Backward Integration into Polymer Compounding | Captive medical-grade polypropylene supply shields margins from LyondellBasell feedstock volatility. |
| Hospital System Partnership | Direct relationships with Bavaria consolidated networks bypass collapsing distributor margins. |
| Surface Chemistry R&D Expansion | Low-retention coatings for Basel antibody-drug conjugate workflows command premium positioning. |
| Sustainability Certification Program | Bio-based polypropylene alignment with EU Green Deal packaging requirements opens procurement channels. |
Research Methodology
Multi-period observation of automated liquid handling adoption rates, EU MDR certification timelines, and filter tip replacement cycles in German hospital laboratories anchored the trend analysis, supplemented by interviews with diagnostic laboratory procurement managers, precision molding operations directors, regulatory affairs specialists at polymer compounders, and GPO contracts managers. Secondary validation drew from FDA quality system guidance documents, EMA IVDR implementation reports, ISO 13485 audit disclosure patterns, and customs trade data on medical-grade polypropylene flows. Bottom-up demand modeling from end-use segment consumption patterns triangulated against top-down market sizing from manufacturer capacity disclosures.
Input-output matrix framing structured the analytical framework across the projection horizon, with segmentation dimensions spanning material type, contamination control tier, application workflow, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to automation penetration rates and clinical diagnostics infrastructure buildout trajectories. Forecast inputs incorporated PMDA medical device registration timelines for Japanese market access and CDSCO streamlined pathway uptake rates for Indian government tender participation.
Underlying measurement precision varies by segment; clinical diagnostics and pharmaceutical R&D applications carry tighter precision than educational and research settings due to documented procurement system transparency. Forecasts reflect assumptions regarding EU MDR implementation consistency, polymer feedstock price stability, and automated liquid handling platform standardization that regulatory divergence or supply disruption could revise. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Global Pipettes and Pipettors Market
Laboratory Equipment
Laboratory Glassware and Plasticware Market
Laboratory Equipment
Platelet Shaker Market
Laboratory Equipment
South Korea Pipette Tips Market
Laboratory Equipment
Global Laboratory Washers Market
Laboratory Equipment
Microplate Washer Market
Laboratory Equipment
Blood Testing Equipment Market
Laboratory Equipment
Lab Accessories Market
Laboratory Equipment
Western Blotting Processors Market
Laboratory Equipment
Glycohemoglobin Analyzers Market
Laboratory Equipment
Europe Laboratory Hoods and Enclosure Market
Laboratory Equipment
UK Pipette Tips Market
Laboratory Equipment
Muffle Laboratory Furnaces Market
Laboratory Equipment
Laboratory Freezers Market
Laboratory Equipment
Multi Channel Hotplate Magnetic Stirrers Market
Laboratory Equipment
Global Laboratory Equipment Services Market