
 Global Microplate System Market | 2026-2036
Global Microplate System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microplate System Market Foresight
The EU AI Act is decoupling compliance costs from traditional hardware pricing, forcing manufacturers to embed algorithmic audit trails into reader software. Thermo Fisher Scientific leverages its LIMS integration depth to sustain premium positioning across European academic laboratories. Danaher Corporation anchors its competitive stance through Beckman Coulter Life Sciences' automated liquid handling compatibility. Agilent Technologies differentiates via open-architecture APIs that let pharmaceutical clients customize fluorescence protocols.
A microplate system comprises a standardized array of cylindrical wells—typically 96, 384, or 1536 configurations—fabricated from polystyrene, polypropylene, or cyclic olefin copolymer, designed for parallel quantitative analysis of biological or chemical reactions in volumes ranging from microliters to milliliters. These systems integrate liquid handlers, detectors, and software to automate enzyme kinetics, cell viability, and nucleic acid quantification at throughputs impossible with manual methods. Fluorescence technology leads in drug discovery applications due to its sensitivity for receptor-ligand binding assays, while luminescence captures the fastest growth in genomics research driven by CRISPR screening expansion. Assay plates command the steepest margin pools where specialized surface chemistries for cell culture and protein binding reduce supplier substitutability.
The FDA enforces 21 CFR Part 11 for electronic records integrity in GMP environments, compelling vendors to validate software audit trails. EMA's In Vitro Diagnostic Regulation and ISO 13485 quality management standards shape product design for clinical diagnostic microplate readers entering European markets. China's NMPA medical device classification rules for automated diagnostic equipment create distinct registration pathways for imported systems. Stakeholders must monitor how divergent software validation requirements across FDA, EMA, and NMPA jurisdictions fragment development roadmaps and inflate regional SKU complexity.
Market Dynamics
The FDA's 21 CFR Part 11 electronic records mandate is compressing software validation timelines across pharmaceutical procurement, forcing microplate reader vendors to rebuild audit trail architectures or forfeit GMP-qualified sales channels.
Growth Catalysts
- High-throughput screening expansion:Pharmaceutical laboratories in the United States, Germany, and China are scaling automated workflows for receptor-ligand binding assays, driving 96-well to 1536-well plate upgrades.
- EMA In Vitro Diagnostic Regulation:Clinical diagnostic microplate readers entering European markets must meet ISO 13485 quality management standards, creating certified product premiums for compliant vendors.
- CRISPR screening proliferation:Genomics research facilities are adopting luminescence detection platforms for gene editing validation, accelerating replacement cycles for legacy fluorescence-only systems.
Market Restraints
- Cyclic olefin copolymer supply concentration:Specialty polymer feedstock for high-optical-clarity assay plates concentrates among Japanese and German chemical suppliers, exposing margins to input volatility.
- NMPA registration pathway complexity:China's medical device classification rules for automated diagnostic equipment impose extended timelines on imported microplate systems, delaying market entry.
- Manual method substitution persistence:Academic laboratories with constrained capital budgets continue using single-channel pipettes for low-throughput assays, capping penetration in price-sensitive segments.
Strategic Opportunities
- EU AI Act algorithmic audit trail mandate:Compliance requirements for embedded software are decoupling from hardware pricing, enabling service revenue streams for validation documentation and algorithmic transparency tools.
- Biotech cluster procurement consolidation:Boston, Basel, and Shanghai are centralizing shared instrument facilities, creating multi-system contract opportunities with standardized LIMS integration requirements.
- Cell culture surface chemistry specialization:Assay plates with protein-binding or 3D cell culture coatings command reduced supplier substitutability, supporting margin expansion for proprietary surface treatment technologies.
Industry Challenges
- Cross-jurisdictional software validation:Divergent FDA, EMA, and NMPA requirements for electronic records integrity fragment development roadmaps and inflate regional SKU complexity.
- LIMS integration technical debt:Pharmaceutical clients demand open-architecture APIs for custom fluorescence protocols, stretching engineering resources across incompatible legacy data management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microplate System Market |
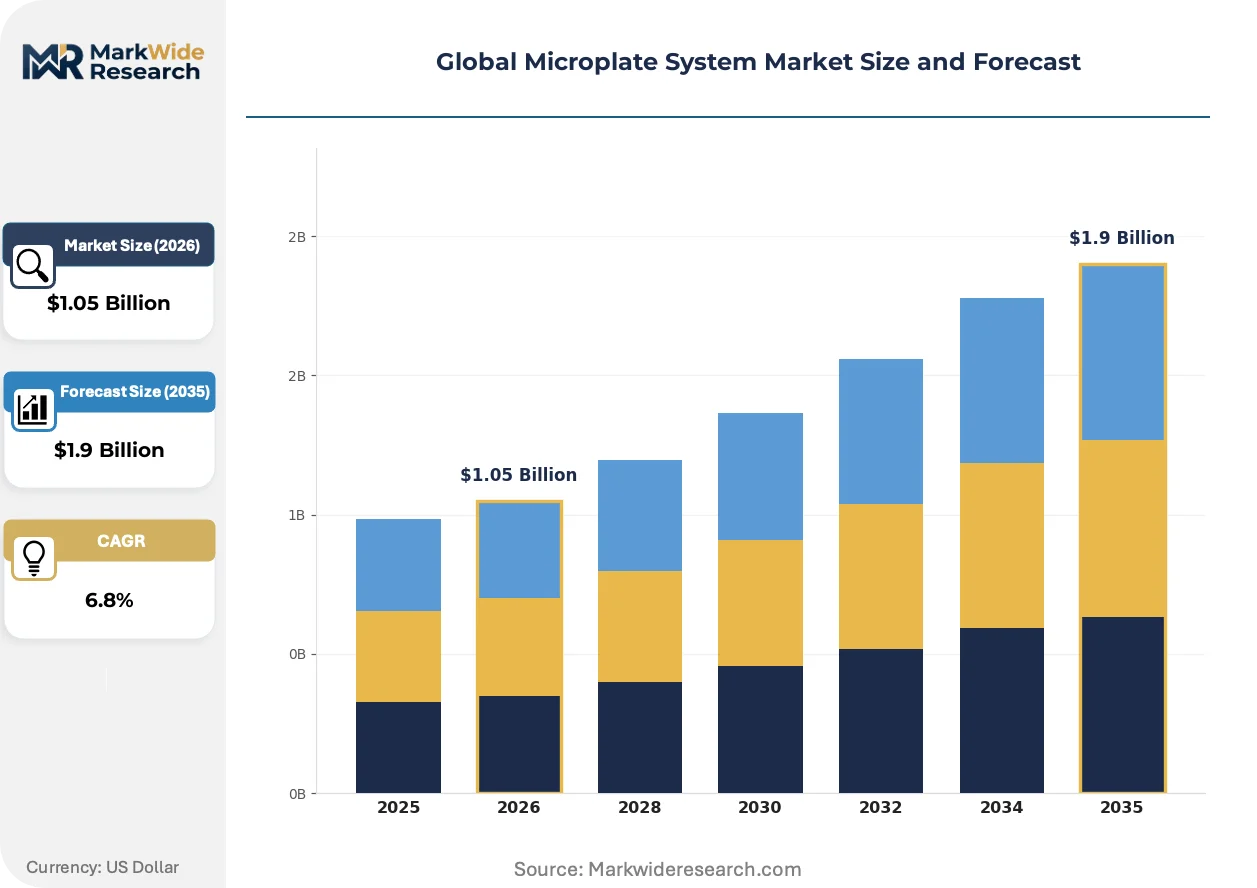
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.9 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 96-Well Plates, 384-Well Plates, Deep Well Plates, Assay Plates, Reservoir Plates Technology: Fluorescence, Luminescence, Absorbance, Time-Resolved Fluorescence, AlphaScreen Application: Drug Discovery, Genomics Research, Proteomics Analysis, Biochemical Assays, Enzyme-Linked Immunosorbent Assay End User: Pharmaceutical Companies, Research Institutes, Biotechnology Firms, Contract Research Organizations, Academic Laboratories |
| Companies Covered | Thermo Fisher Scientific, Danaher Corporation, Agilent Technologies, PerkinElmer, Bio-Rad Laboratories, Tecan Group, BMG LABTECH, Corning Incorporated, Promega Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microplate System Market Shifts & Advancements
Microplate system architecture is bifurcating between closed, validated platforms for regulated pharmaceutical environments and modular, API-accessible systems for research flexibility, with software audit capabilities becoming the primary competitive wedge.
Multimodal detection technology is expanding into consolidated reader platforms that combine absorbance, fluorescence, and luminescence capabilities within single instruments. Biopharmaceutical contract research organizations in the United States are adopting these systems to reduce benchtop footprint and consolidate assay workflows. This convergence is expanding into mid-tier academic laboratories previously served by single-mode devices, compressing the addressable market for standalone absorbance readers.
The EU AI Act's risk-based classification for medical device software is mandating algorithmic audit trails in microplate reader firmware. European manufacturers must embed documentation of decision logic for well-level data processing, increasing development overhead but creating compliance differentiation against non-EU imports. Clinical diagnostic segments in Germany and France are prioritizing CE-marked systems with pre-validated algorithmic transparency packages.
Service contract unbundling is separating instrument hardware sales from validation support and preventive maintenance. Pharmaceutical procurement teams in Switzerland and the United Kingdom are negotiating multi-year performance agreements independent of initial capital purchases, shifting vendor relationships toward outcome-based uptime guarantees rather than transactional equipment sales.
Global Microplate System Market Segmentation
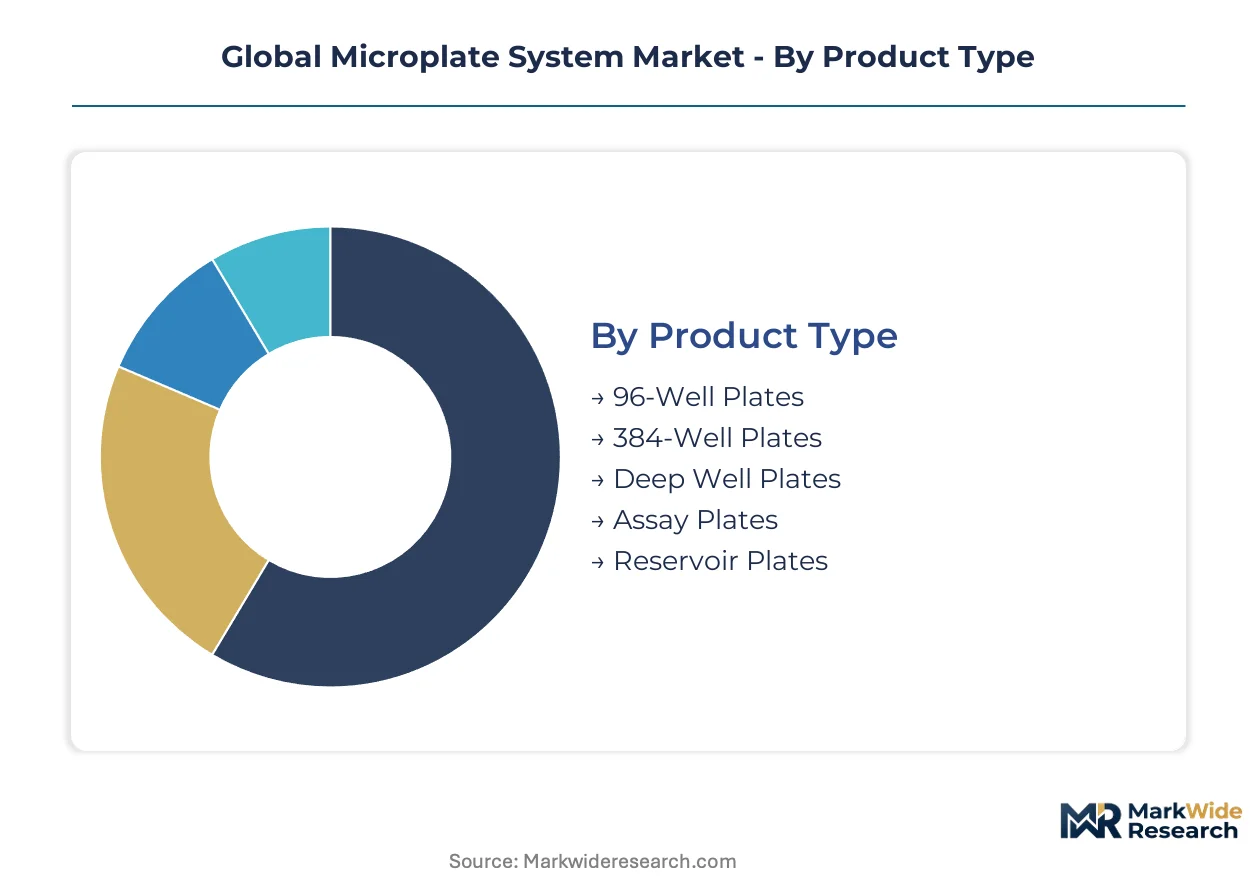
Microplate system procurement patterns diverge sharply across product formats, detection modalities, and institutional settings. Capital allocation priorities in pharmaceutical environments favor high-density configurations and multimodal detection platforms, while academic budgets constrain adoption to standardized formats.
Product Type:
Capital intensity peaks with specialized surface chemistries and optical-grade polymers, where proprietary coatings and molding precision command premium tooling investments.
- Assay Plates:Engineered with protein-binding, cell culture, or 3D scaffold surface treatments that eliminate supplier substitutability. Demand concentrates among Boston and Basel pharmaceutical clusters running high-content screening workflows, where surface consistency directly impacts assay reproducibility.
- 384-Well Plates:High-density polystyrene configurations balancing throughput with liquid handling precision. Genomics facilities in Shanghai and San Diego are standardizing on this format for CRISPR validation pipelines, driving replacement of legacy 96-well infrastructure.
- 96-Well Plates:The workhorse format for academic and clinical diagnostic settings with established automation protocols.
- Deep Well Plates:Extended-height polypropylene wells designed for sample storage and compound library management.
- Reservoir Plates:Single-compartment vessels for bulk reagent distribution in automated liquid handling systems.
Most installed capacity flows through 96-Well Plates. Expansion is steepest in Assay Plates.
Technology:
Detection modality selection tracks application sensitivity requirements and capital depreciation cycles, with multimodal consolidation reshaping procurement roadmaps.
- Fluorescence:Excitation-emission detection architectures leveraging filter-based or monochromator optics for receptor-ligand binding quantification. Drug discovery laboratories in the United States and Germany maintain this as the default screening modality, though single-mode fluorescence-only systems face displacement pressure.
- Luminescence:Photon-counting detection without excitation source, eliminating autofluorescence interference. Genomics research facilities expanding CRISPR screening operations in China and the United Kingdom are adopting dedicated luminescence platforms for reporter gene assays.
- Absorbance:UV-Vis spectrophotometric detection for ELISA and colorimetric assays, now commonly bundled into multimodal configurations.
- Time-Resolved Fluorescence:Delayed-gated detection separating signal from background autofluorescence in complex biological matrices.
- AlphaScreen:Bead-based proximity assay technology for homogeneous high-throughput screening of protein-protein interactions.
Fluorescence retains the largest installed base. Luminescence is climbing the fastest.
Application:
Workflow complexity and regulatory scrutiny intensity vary dramatically across use cases, shaping validation requirements and service contract structures.
- Drug Discovery:High-throughput screening of compound libraries against molecular targets, requiring 21 CFR Part 11 compliant audit trails. Pharmaceutical companies in Switzerland and the United States are consolidating multimodal readers to compress screening timelines.
- Genomics Research:Nucleic acid quantification, CRISPR editing validation, and next-generation sequencing sample preparation. Research institutes in Germany and China are scaling luminescence-based reporter systems for gene function studies.
- Proteomics Analysis:Protein quantification, interaction mapping, and post-translational modification detection.
- Biochemical Assays:Enzyme kinetics and substrate conversion measurements in metabolic research.
- Enzyme-Linked Immunosorbent Assay:Colorimetric and chemiluminescent immunoassay protocols for diagnostic and research applications.
Drug Discovery commands the highest average selling prices. Genomics Research is gaining share fastest.
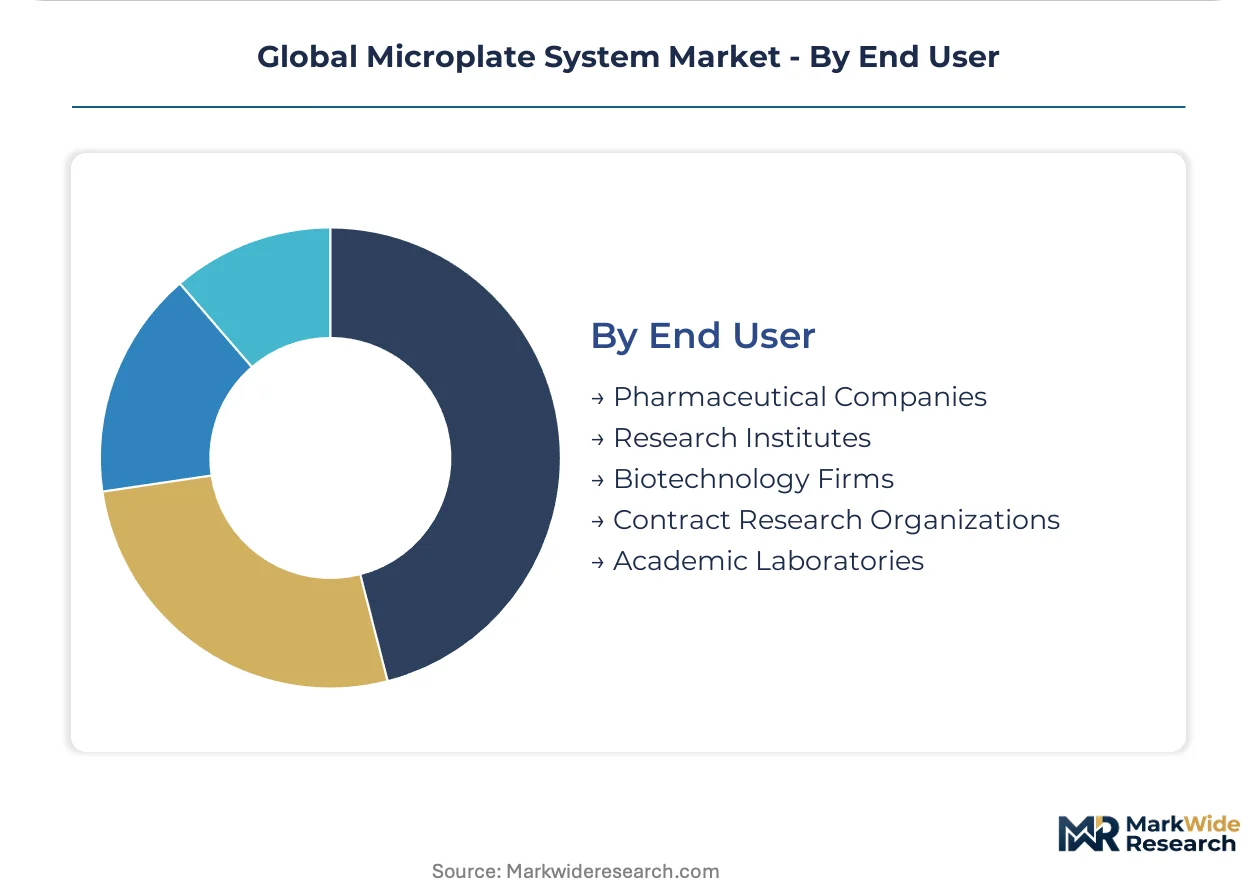
End User:
Purchasing authority and budget flexibility determine whether procurement emphasizes validated GMP platforms or modular research instruments.
- Pharmaceutical Companies:Regulated manufacturing and quality control environments mandating IQ/OQ/PQ validation documentation. Facilities in the United States and Germany are unbundling hardware purchases from multi-year performance-based service agreements.
- Contract Research Organizations:Fee-for-service screening operations requiring rapid assay reconfiguration and open-architecture software. CROs in Boston and Shanghai are prioritizing API-accessible readers for client-specific protocol customization.
- Biotechnology Firms:Venture-funded development stage companies balancing throughput needs against capital constraints.
- Research Institutes:Government-funded academic centers with cyclical grant-dependent procurement cycles.
- Academic Laboratories:Individual principal investigator labs with limited capital budgets and persistent manual method substitution.
Pharmaceutical Companies absorb the majority of premium system shipments. Contract Research Organizations are expanding most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical engineering talent pools in Boston, Basel, and Shanghai anchor procurement gravity for high-throughput screening infrastructure. These clusters concentrate pharmaceutical R&D spending and drive instrument validation requirements that ripple through supplier specifications worldwide.
United States
FDA's 21 CFR Part 11 enforcement compresses software validation timelines for GMP-qualified microplate readers. Pharmaceutical procurement teams in Massachusetts and New Jersey unbundle hardware purchases from multi-year performance agreements. The Greater Boston biotech corridor sustains premium instrument demand for high-content screening workflows.
Germany
EMA's In Vitro Diagnostic Regulation and ISO 13485 standards shape clinical diagnostic reader specifications entering European markets. The EU AI Act mandates algorithmic audit trails in reader firmware, increasing development overhead for manufacturers. The Rhine-Main and Upper Bavaria clusters prioritize CE-marked systems with pre-validated transparency packages.
China
NMPA medical device classification rules for automated diagnostic equipment impose extended registration timelines on imported microplate systems. Genomics facilities in Shanghai and Shenzhen scale luminescence platforms for CRISPR validation pipelines. Domestic biotech clusters accelerate replacement of legacy fluorescence-only infrastructure.
Switzerland
Swissmedic requirements for clinical diagnostic equipment align with EU MDR standards while maintaining distinct quality system expectations. Basel's pharmaceutical headquarters concentrate multimodal reader procurement for consolidated screening operations. Service contract unbundling shifts vendor relationships toward outcome-based uptime guarantees.
United Kingdom
Post-Brexit regulatory divergence from EU MDR creates parallel conformity assessment pathways for diagnostic microplate readers. Research institutes in Cambridge and Oxford balance capital constraints against CRISPR screening expansion needs. Academic procurement cycles remain grant-dependent with persistent manual method substitution in price-sensitive segments.
Global Microplate System Market Competitive Landscape
The competitive structure tilts toward diversified life science conglomerates with deep LIMS integration capabilities. Three to five integrated technology holding companies dominate premium-tier pharmaceutical procurement, while specialized detection technology firms capture genomics research niches. Strategic moves concentrate on algorithmic audit trail certification for EU AI Act compliance and API-accessible architecture development for CRO flexibility requirements.
Among diversified life science technology conglomerates, Thermo Fisher Scientific, Danaher Corporation, and Agilent Technologies occupy positions spanning instrument hardware, consumables, and software integration layers. These entities exemplify the consolidated tier where LIMS depth and automated liquid handling compatibility anchor competitive differentiation. Specialized detection technology firms such as Tecan Group and BMG LABTECH represent the modular research-flexibility vector, emphasizing open-architecture platforms for assay reconfiguration. Corning Incorporated anchors the consumables specialization archetype through engineered surface chemistry capabilities that reduce supplier substitutability in cell culture applications.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Danaher Corporation |
| Agilent Technologies |
| PerkinElmer |
| Bio-Rad Laboratories |
| Tecan Group |
| BMG LABTECH |
| Corning Incorporated |
| Promega Corporation |
| Others |
Supply & Pricing Matrix
Cyclic olefin copolymer resin costs cascade downstream through three distinct pricing tiers, with optical-grade polymer premiums compressing margins for assay plate manufacturers serving pharmaceutical GMP environments while academic buyers absorb standard polystyrene pricing.
Pricing Analysis
Bundled hardware-service contracts are unbundling into standalone instrument sales with separate validation support agreements, creating three-tier pricing structure across premium, standard, and economy levels differentiated by 21 CFR Part 11 certification depth and LIMS integration scope. Price differentiation hinges on software audit trail sophistication and automated liquid handling compatibility. Pricing pressure stems from CRO procurement teams negotiating outcome-based uptime guarantees rather than capital purchases. Academic laboratories exhibit highest price sensitivity, while Swiss and German pharmaceutical clusters absorb premium validated system pricing.
Supply Chain Analysis
Photoresist-grade cyclic olefin copolymer supply rests on Japanese and German specialty chemical producers, with polystyrene and polypropylene feedstock drawing from broader petrochemical networks in China and the United States. Raw material dependencies concentrate on optical-grade polymers, precision molding equipment, and surface chemistry reagents. Single-source vulnerability in high-clarity copolymer supply exposes margins to input volatility. Distribution runs through direct sales forces for pharmaceutical accounts and distributor networks serving academic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Microplate System Market compounds steadily as CRISPR screening proliferation and regulatory audit trail mandates sustain replacement cycle momentum across biopharmaceutical infrastructure.
For Market Incumbents: Anticipate displacement pressure from modular API-accessible platforms by embedding algorithmic transparency documentation into firmware ahead of EU AI Act enforcement waves, while securing backward integration into specialty surface chemistry coatings to defend margin pools in cell culture applications. For New Entrants and Emerging Players: Launch via luminescence-only detection platforms targeting genomics research institutes in China and the United Kingdom, where CRISPR validation workflows outpace incumbent fluorescence-centric portfolios and price sensitivity permits aggressive penetration without full multimodal capability. For Investors and Strategic Acquirers: Consolidation pressure builds where LIMS integration depth and validation documentation capabilities fragment across mid-tier detection technology specialists, with long-term viability favoring targets possessing CE-marked algorithmic audit packages; watch NMPA registration timeline compression as inflection signal for China market entry acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Audit Trail Certification | EU AI Act compliance creates service revenue separation from hardware pricing for European pharmaceutical procurement. |
| API-Accessible Platform Development | Open-architecture fluorescence protocol customization captures CRO contract opportunities in Boston and Shanghai clusters. |
| Surface Chemistry Specialization | Proprietary 3D cell culture coatings reduce supplier substitutability and sustain margin expansion in assay plate segments. |
| LIMS Integration Depth Expansion | Deep data management connectivity anchors premium positioning across academic laboratories and pharmaceutical quality control. |
| Multimodal Detection Consolidation | Single-instrument absorbance-fluorescence-luminescence platforms compress benchtop footprint for contract research organizations. |
Research Methodology
Direct dialogue with pharmaceutical procurement managers, regulatory affairs specialists, biomedical engineers at research institutes, and automated liquid handling system integrators combined with secondary validation against FDA 21 CFR Part 11 guidance documents, EMA In Vitro Diagnostic Regulation filings, NMPA medical device classification records, and ISO 13485 quality management standards. Bottom-up and top-down triangulation cross-checked instrument shipment data against consumables procurement patterns.
Segment-level value outputs trace product type, detection technology, application workflow, and end-user institutional category across the analysis window, with CAGRs derived from replacement cycle timing and regulatory compliance-driven upgrade elasticity. Forecast inputs incorporated CRISPR screening facility expansion rates and software validation timeline compression under divergent FDA, EMA, and NMPA jurisdictions.
Several conditions sit outside the modeled scope, including raw material price shocks in specialty polymer feedstock and unanticipated regulatory harmonization across jurisdictions. Forecasts embed assumptions around sustained biopharmaceutical R&D spending concentration in Boston, Basel, and Shanghai clusters. A small set of named triggers warrants ongoing watch: EU AI Act enforcement intensity, NMPA registration pathway streamlining, and cyclic olefin copolymer supply consolidation events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Global Laboratory Equipment Services Market
Laboratory Equipment
Multi Channel Hotplate Magnetic Stirrers Market
Laboratory Equipment
Microplate Reader Market
Laboratory Equipment
Blood Bank Analyzers Market
Laboratory Equipment
Global Pipette Tips Market
Laboratory Equipment
Automated Nucleic Acid Extraction Systems Market
Laboratory Equipment
Global Hematology Instruments and Reagents Market
Laboratory Equipment
Asia-Pacific Laboratory Hoods and Enclosure Market
Laboratory Equipment
Test Tube Market
Laboratory Equipment
United States Pipette Tips Market
Laboratory Equipment
Western Blotting Processors Market
Laboratory Equipment
Global Laboratory Hoods and Enclosure Market
Laboratory Equipment
Capillary Blood Collection Tubes Market
Laboratory Equipment
Platelet Shaker Market
Laboratory Equipment
Microplate Luminometer Market
Laboratory Equipment
Histopathology Testing Equipment Market