
 Topical Dispenser Market | 2026-2036
Topical Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Topical Dispenser Market Intelligence
Skilled biomedical engineering talent is redrawing competitive boundaries in topical dispenser manufacturing. Johnson & Johnson Services, Inc. leverages its clinical heritage to dominate hospital procurement channels for precision dosing systems. Porex Corporation specializes in porous polymer components that anchor premium nozzle assemblies for regulated pharmaceutical clients. DoseLogix competes through electronic delivery platforms that extend programmable functionality into home care environments.
A topical dispenser is a mechanical or electromechanical device engineered to meter and apply semisolid or liquid formulations onto skin or mucosal surfaces, typically incorporating piston pumps, peristaltic mechanisms, or pressurized valve systems with dosing tolerances measured in microliters. Its primary commercial purpose is to ensure repeatable therapeutic dosing, minimize contamination risk, and improve patient compliance across dermatology, wound management, and transdermal drug delivery applications. Cream and gel formats lead product type demand due to established compatibility with conventional pump architectures, while foam systems represent the fastest-growing category as aerated formulations expand in psoriasis and corticosteroid therapies. Manual delivery mode still occupies the largest installed base, though electronic systems capture expanding margin pools in specialty pharmacy and institutional settings where dose tracking carries reimbursement significance.
The FDA regulates topical dispensers as combination products when packaged with drug formulations, requiring rigorous human factors validation and 510(k) or PMA pathways that shape development timelines and commercialization costs. EPA guidelines on volatile organic compounds influence propellant selection in spray formats, while ISO 13485 quality management standards govern contract manufacturers serving European and North American markets. Stakeholders must monitor evolving FDA guidance on human factors engineering as the agency tightens expectations for patient-use error mitigation in home care electronic dispensers.
Market Dynamics
Precision dosing requirements from FDA combination product regulations are compressing development timelines and forcing manufacturers to revalidate entire device architectures for human factors compliance.
Growth Catalysts
- Home Care Migration:Post-acute care settings in the United States are absorbing hospital-discharge patients who require portable electronic dispensers for chronic wound management.
- REACH Compliance:European chemical safety standards are accelerating replacement of solvent-based propellants with aqueous foam systems in dermatology applications.
- Peristaltic Pump Miniaturization:Advances in stepper motor precision are enabling microliter dosing tolerances previously achievable only in institutional settings.
Market Restraints
- Polymer Feedstock Volatility:Medical-grade polypropylene and silicone elastomer prices fluctuate with petrochemical indices, squeezing margin on disposable nozzle assemblies.
- Contract Manufacturer Concentration:ISO 13485-certified injection molding capacity clusters in southern China and Bavaria, creating geographic supply risk.
- 510(k) Pathway Friction:FDA predicate device requirements for electronic dispensers lack clear comparators, extending regulatory review cycles.
Strategic Opportunities
- Pediatric Dermatology:Underpenetrated dosing formats for corticosteroid creams in children ages 2-12 present formulation-device co-development potential.
- Telehealth Integration:Bluetooth-enabled dispensers with dose-logging APIs align with remote patient monitoring reimbursement codes in Medicare Advantage plans.
- Biologic Compatibility:Cold-chain stable foam systems for monoclonal antibody topicals address stability gaps in existing pump architectures.
Industry Challenges
- Human Factors Engineering Talent:Scarcity of specialists who can execute FDA-mandated use-error analysis for home care electronic devices extends validation timelines.
- Legacy System Integration:Enterprise resource planning platforms at specialty pharmacies require custom API development to ingest dispenser telemetry data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Topical Dispenser Market |
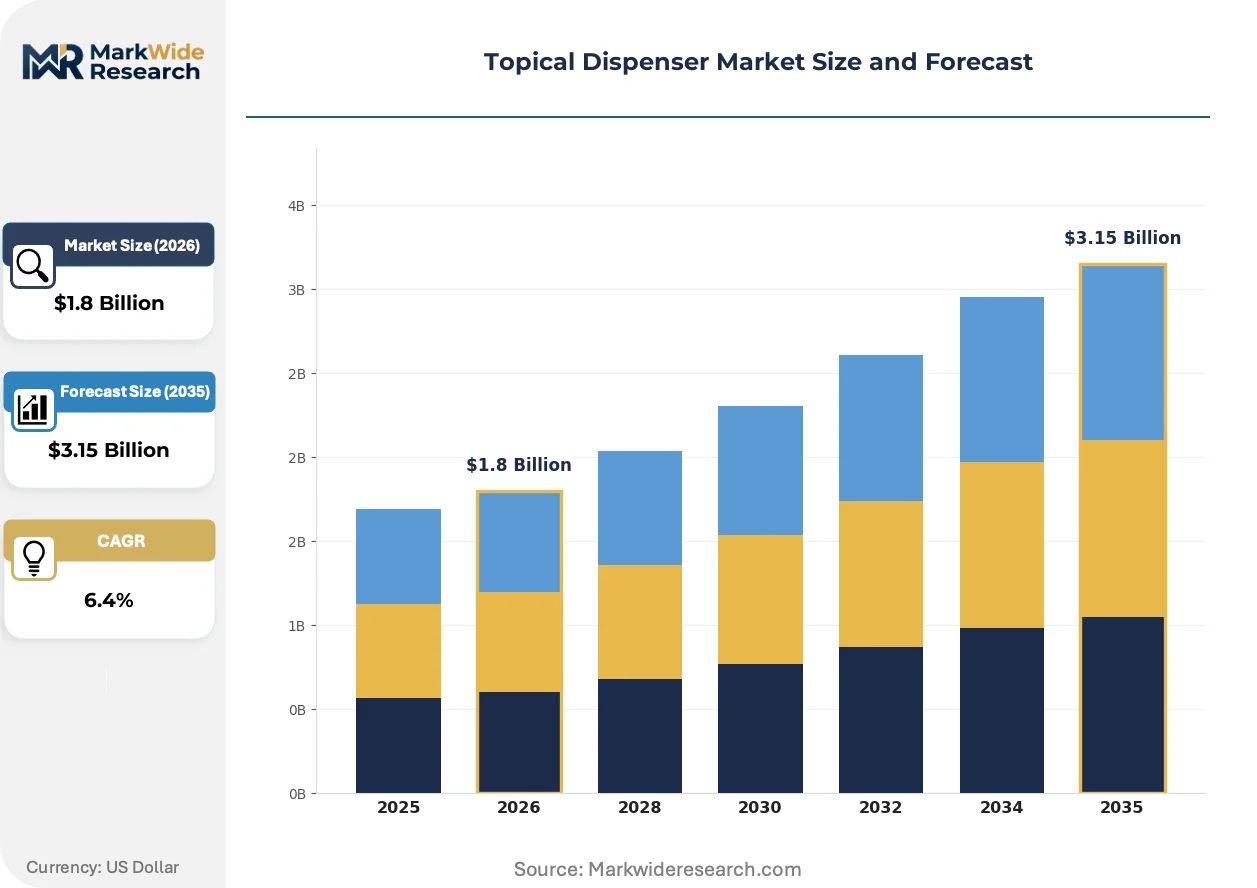
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cream, Gel, Spray, Foam End User: Pharmacies, Hospitals, Clinics, Home Care Delivery Mode: Manual, Electronic, Semi-Automatic, Portable Component: Nozzle, Container, Pump, Cap |
| Companies Covered | Johnson & Johnson Services, Inc., Super Brush LLC, DoseLogix, Simcro, Volumetric, Inc., Biosrx, Porex Corporation, SpecializedRx Products, LLC, Puritan Medical Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Topical Dispenser Market Strategic Shifts & Innovations
Connected device architectures and aerated formulation science are rewriting performance benchmarks for topical delivery systems across institutional and home care channels.
Microporous polymer nozzles with controlled pore-size distribution are displacing conventional mechanical atomizers in spray-format dispensers. Hospital outpatient clinics in Germany and the United States are piloting these components for corticosteroid applications where droplet size uniformity affects therapeutic index. The shift is compressing addressable market share for legacy pressurized valve systems that rely on hydrocarbon propellants.
EMA's evolving Medical Device Regulation (MDR) classification rules are redefining borderline determinations for dispensers with integrated drug reservoirs. Manufacturers must now submit technical documentation under Annex VIII criteria that previously fell under medicinal product frameworks. Wound care combination products face the steepest compliance burden, with notified body queue times extending certification cycles.
Specialty pharmacy buyers are consolidating supplier relationships around vendors who bundle device provisioning with adherence analytics. Three-year sole-source agreements are replacing transactional procurement for electronic dispensers in psoriasis and atopic dermatitis therapeutic categories. This concentration is most pronounced in United States Medicare Part D channels where star-rating incentives reward measurable compliance outcomes.
Topical Dispenser Market Segmentation
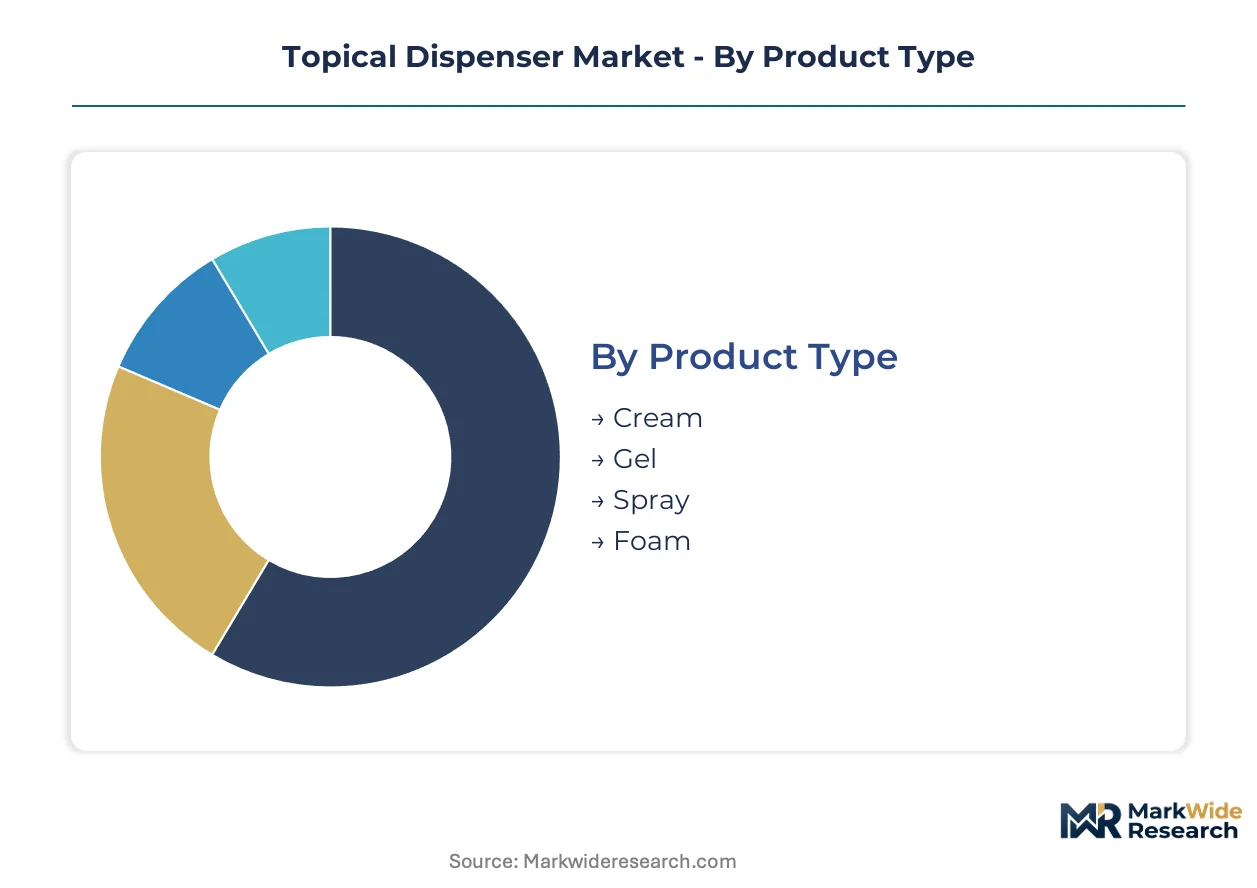
Topical dispenser procurement patterns diverge sharply across formulation physics, care settings, and automation levels. Manufacturers must align component architectures with distinct regulatory burdens and dosing precision requirements that vary by segment.
Product Type:
Substitution pressure from aerated formulations is eroding legacy pump compatibility for viscous semisolids, forcing architecture redesigns across the category.
- Cream:Viscous oil-in-water emulsions with rheology calibrated for piston pump shear tolerance. Hospital outpatient departments in Germany specify cream-compatible dispensers for corticosteroid protocols where dose uniformity affects therapeutic index.
- Gel:Hydrophilic polymer matrices requiring lower actuation force than cream formats. Specialty pharmacies in the United States consolidate procurement around gel-optimized peristaltic systems for retinoid therapies.
- Spray:Atomized delivery through pressurized valve or mechanical pump systems. EPA volatile organic compound limits constrain propellant selection.
- Foam:Aerated formulations with biocompatible surfactant stabilizers. Cold-chain requirements for biologic compatibility are accelerating nozzle redesign.
Cream anchors the volume base while foam gains share at the steepest rate.
End User:
Cost tier stratification separates institutional procurement with reimbursement coding requirements from cash-pay retail channels with price elasticity.
- Pharmacies:Retail and specialty dispensers with adherence tracking for Medicare Advantage star-rating optimization. United States independent pharmacies favor Bluetooth-enabled units with dose-logging APIs.
- Hospitals:Sterile single-use nozzle assemblies for inpatient wound care. ISO 13485-certified contract manufacturers cluster procurement in Bavaria and southern China.
- Clinics:Outpatient dermatology practices with mid-volume throughput. German hospital outpatient clinics pilot microporous polymer nozzles for droplet size uniformity.
- Home Care:Portable electronic dispensers for post-acute chronic wound management. FDA human factors validation requirements extend development timelines for programmable home units.
Hospitals anchor the volume base while home care climbs the fastest as post-acute migration accelerates.
Delivery Mode:
Application intensity separates chronic condition management requiring dose logging from acute episodic use where mechanical simplicity dominates.
- Manual:Spring-loaded piston or squeeze-actuated mechanisms with no power dependency. Largest installed base in retail pharmacy channels with lowest unit cost.
- Electronic:Stepper motor-driven peristaltic pumps with microliter precision. Medicare Part D star-rating incentives drive specialty pharmacy consolidation around vendors bundling adherence analytics.
- Semi-Automatic:Battery-assisted actuation reducing hand-force requirements for geriatric users. Emerging category bridging manual and electronic price points.
- Portable:Compact rechargeable units for travel and workplace dosing. Bluetooth telemetry integration aligns with remote patient monitoring reimbursement codes.
Manual delivery anchors the volume base while electronic systems capture expanding margin pools in institutional and specialty channels.
Component:
Supply concentration in medical-grade polymer feedstock creates margin pressure on disposable subassemblies versus reusable precision mechanisms.
- Nozzle:Microporous polymer or precision-molded orifice controlling droplet size distribution. Porex Corporation anchors premium nozzle supply for regulated pharmaceutical clients.
- Container:Polypropylene or glass reservoirs with barrier properties for oxygen-sensitive formulations. REACH compliance accelerates aqueous system migration.
- Pump:Piston, peristaltic, or pressurized valve mechanisms with dosing tolerance specifications. Stepper motor miniaturization enables microliter precision previously institutional-only.
- Cap:Child-resistant and tamper-evident closures with ergonomic actuation surfaces. Human factors engineering talent scarcity extends validation timelines.
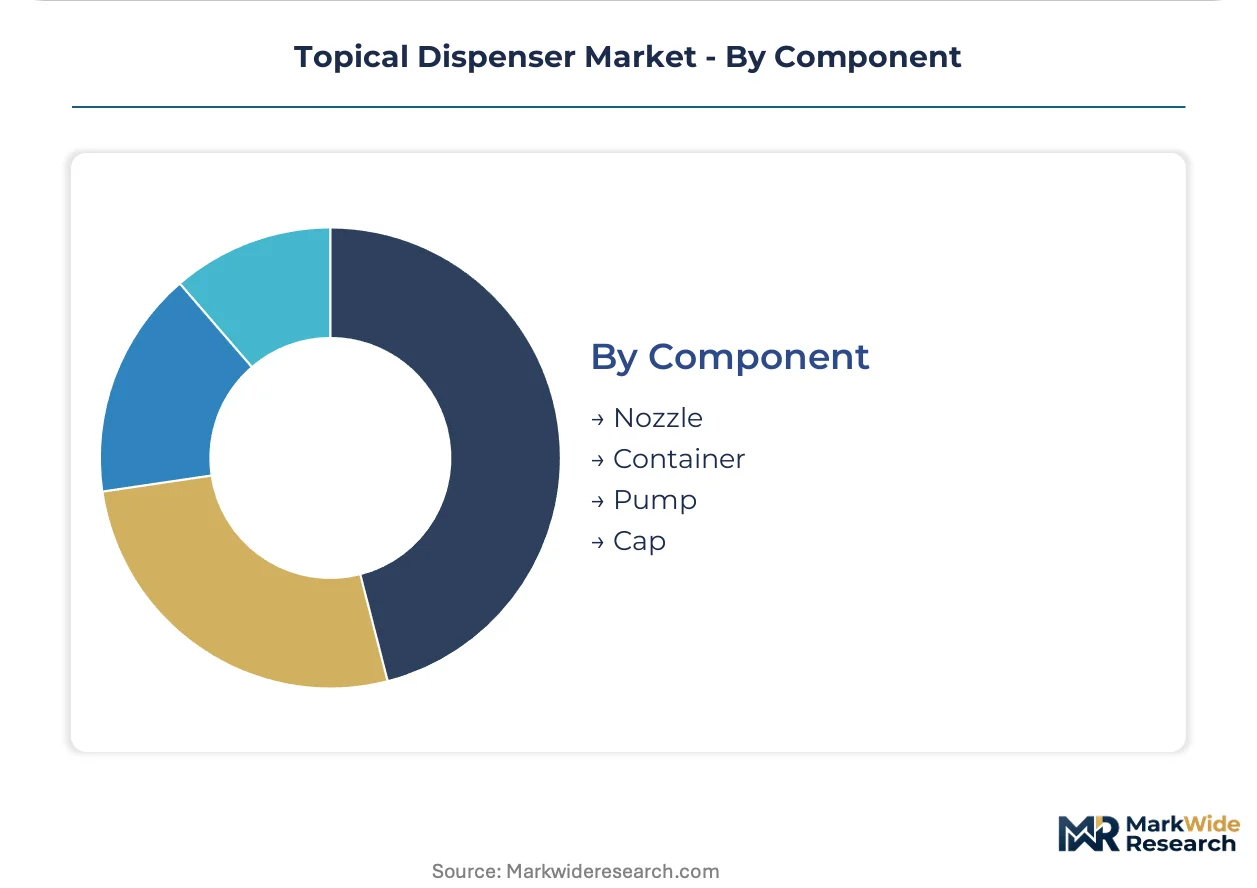
Pump mechanisms anchor the volume base while nozzle assemblies show the steepest technology-driven value migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA combination product regulations in the United States compress development timelines for electronic dispensers while REACH compliance in Europe accelerates aqueous foam system adoption. German hospital outpatient clinics pilot microporous polymer nozzles. Contract manufacturing clusters in Bavaria and southern China concentrate ISO 13485-certified capacity.
United States
Post-acute care settings absorb hospital-discharge patients requiring portable electronic dispensers for chronic wound management. Medicare Part D star-rating incentives reward measurable compliance outcomes from Bluetooth-enabled units. Specialty pharmacy buyers in the Northeast corridor consolidate supplier relationships around adherence analytics bundling.
Germany
Hospital outpatient clinics specify cream-compatible dispensers for corticosteroid protocols where dose uniformity affects therapeutic index. EMA Medical Device Regulation reclassifies wound care combination products under Annex VIII criteria. Bavaria hosts concentrated ISO 13485-certified injection molding capacity serving regulated pharmaceutical clients.
China
NMPA evolving classification rules for combination products reshape design validation requirements for domestic manufacturers. Dual carbon goals accelerate solvent-based propellant replacement in aerosol formats. Southern China clusters contract manufacturing capacity for disposable nozzle assemblies.
Japan
PMDA quality management standards govern precision dosing system imports for dermatology applications. METI supports peristaltic pump miniaturization through advanced manufacturing subsidies. Kanto region pharmaceutical device fabricators specialize in stepper motor integration for microliter tolerances.
India
CDSCO streamlined approval pathways for Class B medical devices attract contract manufacturing investment from multinational pharmaceutical firms. PLI scheme incentives target precision plastic component production for export markets. Gujarat and Maharashtra states develop specialty chemical compatibility testing infrastructure for foam formulation stability.
Topical Dispenser Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics. Consolidated procurement channels in United States specialty pharmacy favor vendors bundling adherence analytics, while fragmented retail pharmacy channels reward unit cost minimization. Three archetypes dominate: diversified healthcare conglomerates with clinical heritage, porous polymer component specialists, and electronic delivery platform innovators. Competitive moves center on geographic expansion into Medicare Advantage channels and portfolio diversification toward biologic-compatible cold-chain systems.
Within the diversified healthcare tier, Johnson & Johnson Services, Inc. occupies a position exemplifying hospital procurement channel dominance through clinical heritage leverage. Porex Corporation anchors the porous polymer specialist archetype, representing premium nozzle assembly supply for regulated pharmaceutical clients. DoseLogix sits within the electronic delivery platform tier, exemplifying programmable functionality extension into home care reimbursement environments. These three players collectively illustrate how FDA compliance capability, materials science specialization, and connected device architecture define separable competitive vectors in this market.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Super Brush LLC |
| DoseLogix |
| Simcro |
| Volumetric, Inc. |
| Biosrx |
| Porex Corporation |
| SpecializedRx Products, LLC |
| Puritan Medical Products |
| Others |
Cost & Logistics Intelligence
Three-year sole-source agreements with adherence analytics bundling lock in supply access and price visibility for United States specialty pharmacy buyers of electronic dispensers. FDA combination product regulations compress development timelines, forcing manufacturers to absorb validation costs into contract pricing while REACH compliance in Europe accelerates aqueous foam system migration.
Pricing Analysis
United States Medicare Part D channels command 40-60% premiums over retail pharmacy pricing for Bluetooth-enabled dispensers with dose-logging APIs. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated combination products from CE-marked devices and unregulated cosmetic applicators. Cost compression in economy-tier manual dispensers is intensifying because southern Chinese contract manufacturers compete on polypropylene nozzle assembly volume. Cash-pay retail channels exhibit highest price sensitivity; institutional procurement through GPO contracts shows lowest elasticity due to reimbursement coding requirements.
Supply Chain Analysis
Medical-grade polypropylene inventory cycles extend 12-16 weeks for ISO 13485-certified injection molders in Bavaria and southern China. Feedstock supply concentrates in Germany, China, and the United States for stepper motor-driven peristaltic pump mechanisms. Silicone elastomer and precision-machined polymer components draw from petrochemical indices and specialized polymer compounders. Single-source vulnerability concentrates in southern China's disposable nozzle assembly capacity. Distribution runs through specialty pharmacy wholesalers and hospital GPO procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA tightening of human factors engineering expectations for home care electronic dispensers constitutes a regulatory inflection that will consolidate competitive positions around validated device architectures.
For Market Incumbents: Compound clinical heritage advantage through backward integration into microporous polymer nozzle production, capturing margin currently flowing to Porex Corporation. Pursue sole-source adherence analytics bundling with Medicare Advantage plans to lock in three-year procurement cycles against emerging electronic platform competitors.
For New Entrants and Emerging Players: Anchor in pediatric dermatology dosing formats for corticosteroid creams, where formulation-device co-development partnerships with pharmaceutical firms remain underpenetrated for children ages 2-12. Target telehealth-integrated Bluetooth dispensers with dose-logging APIs as the most penetrable reimbursement-aligned segment.
For Investors and Strategic Acquirers: Capital is best deployed toward electronic delivery platform innovators with FDA 510(k) submission experience and existing specialty pharmacy distribution relationships. The signal to watch is EMA MDR Annex VIII reclassification queue times for wound care combination products, which will determine certification cycle duration and working capital intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Human Factors Validation Investment | Accelerates 510(k) clearance timelines for electronic home care dispensers under tightened guidance. |
| Backward Integration into Nozzle Manufacturing | Captures margin from Porex Corporation's premium polymer component supply position. |
| Telehealth Platform Partnership | Aligns Bluetooth-enabled dispensers with Medicare Advantage remote patient monitoring reimbursement codes. |
| Biologic-Compatible Cold-Chain Development | Addresses stability gaps for monoclonal antibody topicals in foam formulation architectures. |
| REACH-Compliant Aqueous System Migration | Replaces solvent-based propellants in European dermatology spray formats ahead of regulatory deadlines. |
Research Approach
A spread of perspectives from biomedical engineering directors, FDA regulatory affairs consultants, specialty pharmacy procurement managers, and GPO contracts administrators converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EMA MDR technical documentation, hospital procurement databases, and CMS Medicare Part D adherence metrics. Bottom-up unit volume modeling triangulated against top-down pharmaceutical manufacturer capacity disclosures.
Segmentation dimensions modeled include product type, delivery mode, end-user setting, and regional regulatory cluster across the analysis window. CAGRs derive from weighted least-squares fitting to historical shipment data and pharmaceutical pipeline stage-gate disclosures. Forecast inputs incorporate REACH propellant transition timelines and FDA human factors guidance revision schedules.
Decision-makers should treat outputs as directional under assumptions of stable FDA predicate device comparability standards; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Promotional Packaging Market
Packaging Solutions
FMCG Packaging Market
Packaging Solutions
Korea E-Commerce Packaging Market
Packaging Solutions
Shelf Stable Packaging Market
Packaging Solutions
Global Lithium Ion Battery Packaging Solutions Market
Packaging Solutions
Panel Level Packaging Market
Packaging Solutions
Global Packaging Market
Packaging Solutions
Portable UV Sanitizing Boxes Market
Packaging Solutions
Stretch Sleeves and Shrink Sleeves Market
Packaging Solutions
Cohesive Packaging Solutions Market
Packaging Solutions
Middle East and Africa Contract Packaging Market
Packaging Solutions
Contract Packaging Market
Packaging Solutions
North America Secondary Packaging Market
Packaging Solutions
United Kingdom Packaging Market
Packaging Solutions
Secondary Packaging Market
Packaging Solutions
Patisserie Packaging Market