
 Void Fill Packaging Systems Market | 2026-2036
Void Fill Packaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Void Fill Packaging Systems Market Analytics
EU Green Deal packaging waste targets is consolidating demand toward fiber-based and recyclable void fill alternatives. Sealed Air leverages its global manufacturing footprint to supply paper and inflatable systems across multiple continents. Ranpak anchors its position through dedicated kraft paper void fill technologies and automated dispensing equipment. Storopack competes with a broad portfolio spanning foam, paper, and air cushion formats for industrial and consumer fulfillment.
Void fill packaging systems are engineered protective structures—typically air cushions, foam inserts, paper crumple, or inflatable chambers—designed to immobilize products within shipping containers and absorb transit shock, with densities ranging from 0.5 to 2.5 pounds per cubic foot depending on material. These systems prevent dimensional weight penalties and damage claims in parcel logistics, serving as critical infrastructure for omnichannel distribution networks. Paper fill solutions lead in sustainability-sensitive supply chains where kraft fiber offers curbside recyclability, while air cushions dominate in high-volume e-commerce operations where material cost per unit shipped drives procurement decisions. Foam segments retain margin pools in electronics and pharmaceutical applications where anti-static properties and precise cavity molding justify premium positioning.
FDA regulations govern void fill materials in pharmaceutical and food contact applications, requiring substance migration testing and compliance with 21 CFR standards for indirect food additives. EPA guidelines on recycled content and waste reduction influence material selection for polyethylene and polypropylene formats in the US market. ECHA REACH restrictions on certain chemical additives in plastics are reshaping European formulation strategies, while ISO 18606 and related packaging recovery standards create certification thresholds for circular economy claims. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to invest in regional material conversion or consolidate supply around globally compliant substrate platforms.
Market Dynamics
E-commerce fulfillment networks are compressing damage tolerance thresholds while EU Green Deal packaging waste mandates force material transitions across supplier bases. This dual pressure is restructuring procurement criteria toward recyclable substrates and automated dispensing systems that reduce labor dependency in high-volume operations.
Growth Catalysts
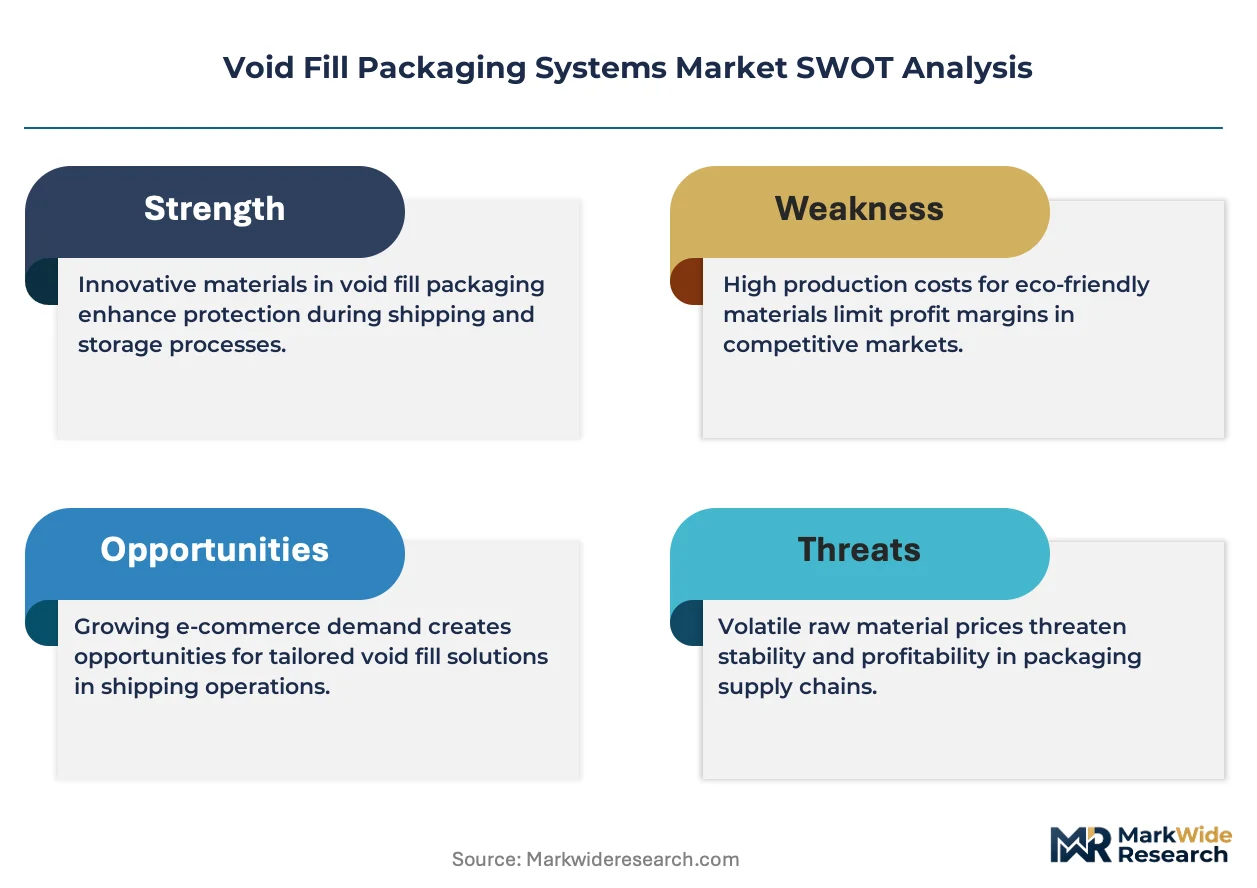
- EU Green Deal packaging directives:Mandatory recyclability targets are pulling demand toward fiber-based void fill formats and away from conventional polyethylene cushions across European distribution networks.
- Automotive export packaging:Germany's precision manufacturing clusters sustain elevated consumption of engineered foam and molded paper systems for high-value component protection.
- Automated dispensing integration:Robotics-enabled void fill stations are reducing per-unit labor costs in third-party logistics warehouses serving omnichannel retailers.
Market Restraints
- Resin price volatility:Polyethylene and polypropylene input costs fluctuate with crude oil indices, compressing margins for air cushion manufacturers dependent on fossil-derived films.
- Recycling infrastructure gaps:Curbside acceptance of laminated paper-foam hybrid formats remains inconsistent across municipal waste systems in the United States.
- Anti-static formulation constraints:ECHA REACH restrictions on certain chemical additives limit performance options for electronics-grade foam void fill in European markets.
Strategic Opportunities
- Pharmaceutical cold chain expansion:Temperature-sensitive biologics distribution is creating demand for insulated void fill systems combining thermal protection with dimensional stability.
- India e-commerce infrastructure buildout:Domestic fulfillment center construction is accelerating adoption of paper-based protective packaging as the country's logistics networks modernize.
- Extended producer responsibility frameworks:Emerging fee structures on non-recyclable packaging are incentivizing substrate conversion before mandates harden into law.
Industry Challenges
- Equipment retrofit complexity:Legacy void fill dispensing systems in established warehouses require substantial modification to handle kraft paper formats versus film-based alternatives.
- Certification timeline compression:FDA 21 CFR compliance for pharmaceutical-contact void fill materials demands extended migration testing cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Void Fill Packaging Systems Market |
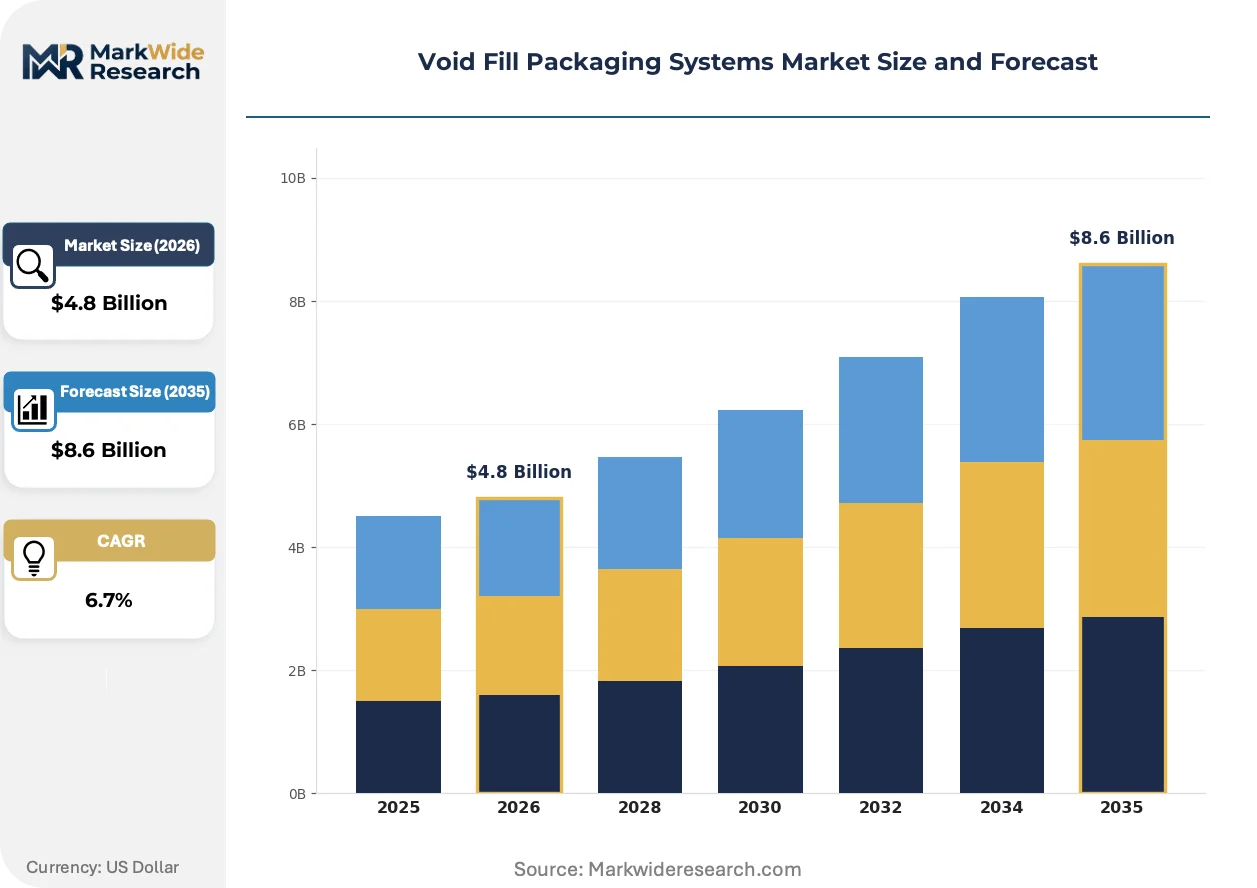
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Cushions, Foam, Paper Fill, Inflatable Packaging Application: Electronics, Pharmaceuticals, Food & Beverage, E-commerce Material: Polyethylene, Polypropylene, Kraft Paper, Biodegradable Options Distribution Channel: Online Retail, Retail Stores, Direct Sales, Wholesale |
| Companies Covered | Ranpak, Kite Packaging, Sealed Air, Automated Packaging Systems, Intertape Polymer Group, Pregis, FP International, Packsize, Storopack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Void Fill Packaging Systems Market Evolving Landscape
Material science advances and regulatory stringency are converging to reshape substrate selection and equipment design across protective packaging supply chains. Three developments are actively redirecting competitive positioning and procurement patterns.
On-demand paper void fill systems are expanding into high-velocity e-commerce operations previously dominated by pre-inflated air cushions. Third-party logistics providers in the United States are deploying compact kraft paper dispensers that convert flat stock into three-dimensional crumple at point of pack. This substrate transition is expanding into fulfillment networks where damage claim reduction and curbside recyclability now outweigh material cost per unit in vendor scorecards.
EU Green Deal packaging waste targets are mandating design-for-recyclability principles that eliminate multi-material laminates. The European Chemicals Agency's evolving REACH restrictions on persistent organic pollutants are further constraining additive options in plastic void fill formulations. Electronics and pharmaceutical sectors in Germany and France are responding fastest, specifying mono-material paper or certified recyclable foam alternatives in supplier qualification requirements.
Shipper demand for dimensional weight optimization is compressing tolerance for over-packaging in parcel networks. Retailers are unbundling protective packaging specifications from carrier contracts and bringing void fill procurement in-house to control costs. This behavioral shift is most visible in North American direct-to-consumer apparel and consumer electronics verticals, where brands now specify minimum fill densities and maximum container void percentages to avoid carrier dimensional pricing penalties.
Void Fill Packaging Systems Market Segmentation
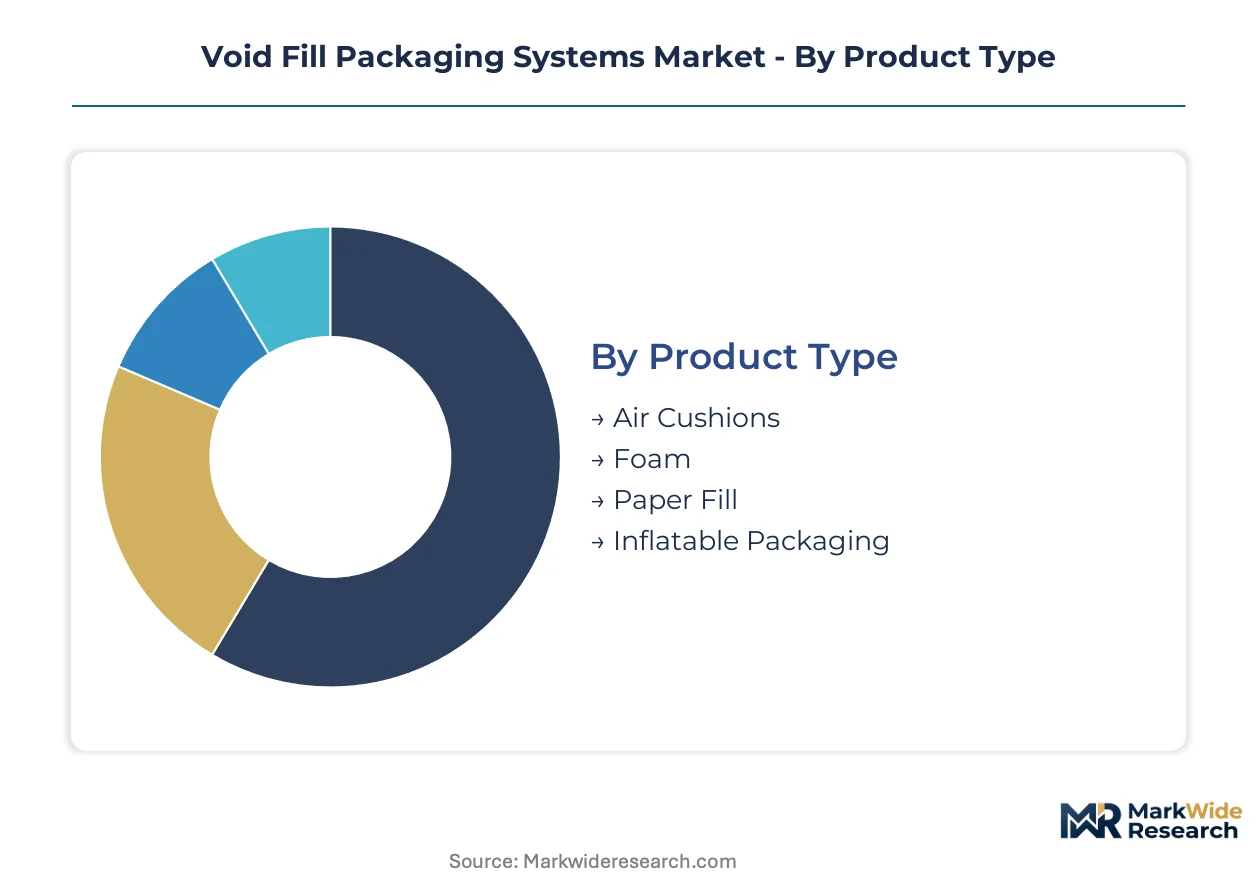
Void fill packaging procurement patterns diverge sharply between high-velocity e-commerce operations prioritizing unit economics and precision industries where damage tolerance approaches zero. Material selection, equipment compatibility, and end-use regulatory exposure create distinct competitive arenas within each segment dimension.
Product Type:
Air cushions dominate shipment volumes while foam commands premium positioning in damage-sensitive applications.
- Air Cushions:Pre-inflated or on-demand polyethylene film chambers provide lightweight dimensional stability at densities below one pound per cubic foot. E-commerce fulfillment centers in Germany and the United States deploy high-speed dispensers to minimize labor per parcel in operations exceeding 50,000 units daily.
- Foam:Expanded polystyrene and polyurethane formulations offer precise cavity molding and anti-static properties for electronics and pharmaceutical cold chain protection. Automotive component suppliers in Stuttgart and Wolfsburg specify engineered foam systems for export shipments of precision-machined parts.
- Paper Fill:Crumpled kraft fiber systems deliver curbside recyclability without film contamination.
- Inflatable Packaging:Chambered film structures inflate at pack stations to reduce inbound freight volume.
Mature deployment sits with foam in industrial export packaging. Newer deployment is concentrated in paper fill systems responding to EU Green Deal recyclability mandates.
Application:
Regulatory exposure and damage claim thresholds segment procurement behavior across end-use verticals.
- Electronics:Anti-static foam and air cushion hybrids protect semiconductor components and consumer devices from electrostatic discharge and transit shock. Original equipment manufacturers in Taiwan and South Korea specify ISO 18606-compliant recyclable formats for outbound logistics.
- E-commerce:Omnichannel retailers optimize for dimensional weight minimization and curbside recyclability in direct-to-consumer fulfillment. Third-party logistics providers in the United States are retrofitting pack stations with on-demand paper dispensers to reduce film dependency.
- Pharmaceuticals:FDA 21 CFR compliance requirements govern material selection for secondary packaging in drug distribution.
- Food & Beverage:Indirect food contact regulations limit substrate options for edible product protection.
Procurement sophistication peaks in pharmaceuticals where migration testing extends qualification timelines. E-commerce represents the steepest expansion trajectory as fulfillment center construction accelerates across India and Southeast Asia.
Material:
Fossil-derived films retain cost advantage while fiber and bio-based alternatives capture sustainability-premium positioning.
- Polyethylene:Low-density and linear low-density films dominate air cushion manufacturing due to seal integrity and puncture resistance. Resin price volatility tied to crude oil indices compresses margins for manufacturers without long-term supply contracts.
- Kraft Paper:Unbleached virgin and recycled fiber grades offer mechanical cushioning through crumple geometry rather than cellular structure. European distributors are consolidating procurement around FSC-certified sources to satisfy EU Green Deal due diligence requirements.
- Polypropylene:Higher melting point and stiffness suit molded foam applications and temperature-resistant formats.
- Biodegradable Options:Starch-based and mycelium-derived experimental substrates target composting infrastructure markets.
Volume concentration remains with polyethylene in high-velocity operations. Kraft paper is gaining share fastest where extended producer responsibility fees penalize non-recyclable formats.
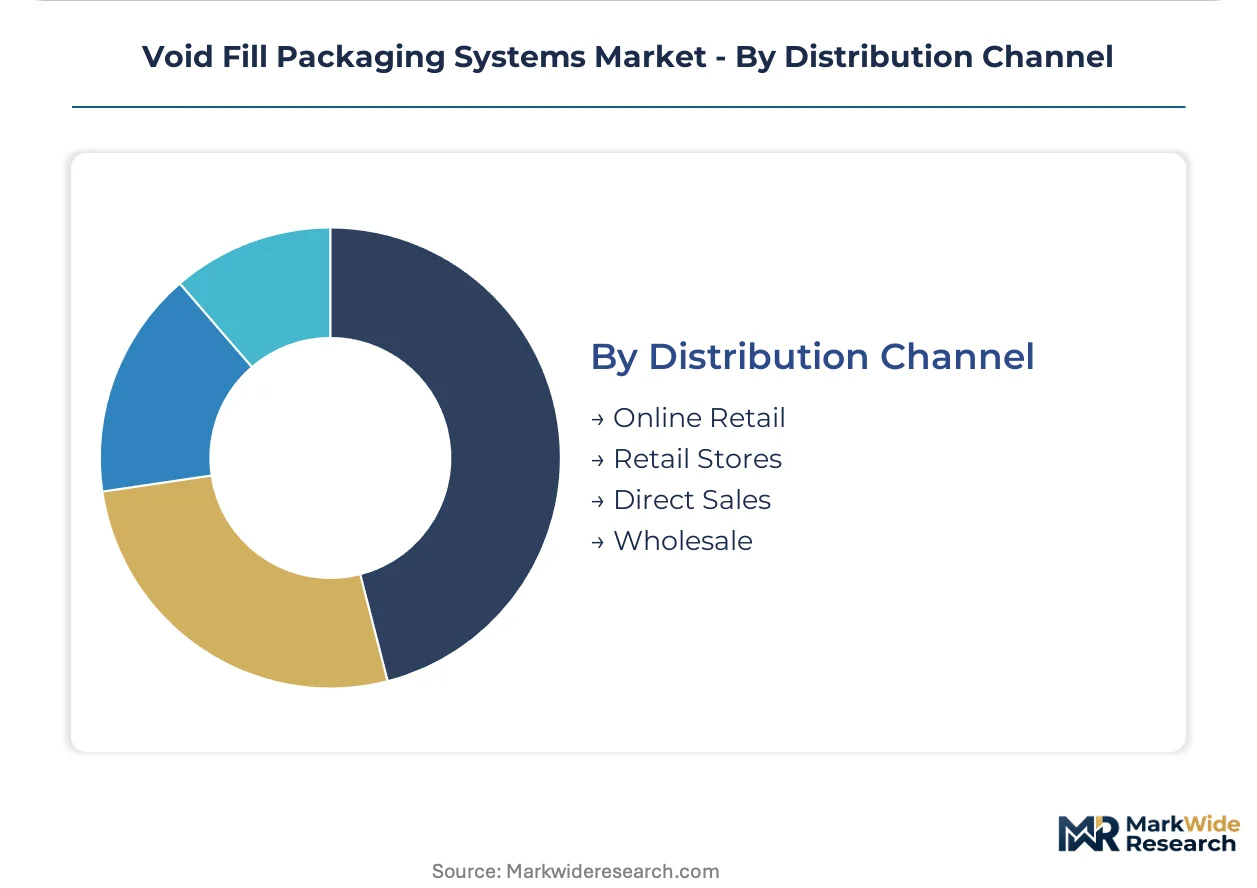
Distribution Channel:
Equipment bundling and technical service requirements shape channel selection for void fill system procurement.
- Direct Sales:Manufacturers deploy technical specialists to configure automated dispensing systems integrated with warehouse management software. Large automotive and electronics producers in Germany negotiate multi-year service contracts covering equipment, substrate supply, and preventive maintenance.
- Wholesale:Industrial distributors stock standard air cushion and foam formats for mid-volume shippers without dedicated packaging engineers. Regional distributors in the United States maintain inventory positions near major logistics hubs to enable rapid replenishment.
- Online Retail:Catalog and marketplace sales serve small e-commerce merchants with standardized product dimensions and low order variability.
- Retail Stores:Limited selection of consumer-scale protective packaging for small business and residential shipping.
Direct sales capture the most complex automated installations. Wholesale channels serve the broadest geographic spread of mid-market accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European void fill demand through its dense concentration of automotive precision manufacturing and export logistics infrastructure. The city's component suppliers consume engineered foam and molded paper systems at volumes that shape continental procurement patterns.
Germany
Automotive export packaging from Stuttgart and Wolfsburg sustains elevated consumption of engineered foam systems for precision-machined components. EU Green Deal packaging waste directives accelerate fiber-based transitions across Bavarian and North Rhine-Westphalia distribution networks. The KBA automotive regulator influences transport packaging standards that cascade into void fill specifications for cross-border component shipments.
United States
Third-party logistics providers in Chicago and Dallas-Fort Worth metro areas deploy high-speed air cushion dispensers for e-commerce volumes exceeding 50,000 parcels daily. EPA guidelines on recycled content influence polyethylene and polypropylene material selection across fulfillment networks. The Southeast logistics corridor spanning Georgia and Tennessee attracts automated void fill equipment investments from omnichannel retailers seeking dimensional weight optimization.
China
E-commerce fulfillment center construction in Yangtze River Delta and Pearl River Delta regions drives demand for lightweight protective packaging in domestic parcel networks. MIIT industrial standards govern packaging material specifications for electronics exports from Shenzhen and Dongguan manufacturing clusters. Shanghai-based distributors consolidate procurement around substrates compliant with dual carbon policy targets.
India
Domestic fulfillment infrastructure buildout in Mumbai and Bangalore accelerates adoption of paper-based protective packaging as logistics networks modernize. BIS certification requirements shape material qualification timelines for void fill suppliers entering the market. The Delhi-Mumbai Industrial Corridor attracts automated dispensing equipment deployments from third-party logistics operators serving apparel and consumer electronics verticals.
Japan
Electronics original equipment manufacturers in Kansai and Chubu regions specify ISO 18606-compliant recyclable void fill formats for outbound semiconductor logistics. METI circular economy guidelines incentivize substrate transitions away from multi-material laminates in Osaka and Nagoya distribution hubs. Precision component suppliers in Kyushu sustain demand for anti-static foam systems with stringent electrostatic discharge protection.
Void Fill Packaging Systems Market Competitive Landscape
The competitive structure tilts toward diversified material specialists with automated equipment integration capabilities. Consolidation pressure concentrates among suppliers capable of delivering both substrate and dispensing system bundles under unified service contracts. Three archetypes dominate: integrated material-equipment providers, pure-play substrate manufacturers, and regional automation specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers seek to secure fulfillment center retrofit contracts.
Among integrated material-equipment providers, Sealed Air, Ranpak, and Storopack occupy positions that exemplify the premium-tier archetype through global manufacturing footprints and automated dispensing portfolios. Sealed Air represents the diversified multinational structure with cross-continental supply capabilities. Ranpak anchors the fiber-based specialization vector through dedicated kraft paper technologies. Storopack sits within the broad-format portfolio tier spanning foam, paper, and air cushion alternatives. These three entities collectively illustrate how competitive positioning stratifies around material science depth versus equipment integration breadth.
| Leading Market Players |
|---|
| Ranpak |
| Kite Packaging |
| Sealed Air |
| Automated Packaging Systems |
| Intertape Polymer Group |
| Pregis |
| FP International |
| Packsize |
| Storopack |
| Others |
Value Network & Pricing Analysis
Automated equipment engineering talent concentrated in Stuttgart and Wolfsburg feeds labor-cost differentials that widen pricing-tier spreads between premium integrated system bundles and commodity substrate-only supply.
Pricing Analysis
Throughput-based pricing anchors contracts to parcels-per-hour guarantees rather than material volume, with Sealed Air and Ranpak bundling dispenser uptime commitments into premium tiers. Price differentiation separates FDA 21 CFR-certified pharmaceutical formats from standard e-commerce grades, with customization for anti-static foam commanding further premiums. Cost compression in polyethylene air cushions is intensifying because resin volatility erodes manufacturer margins without long-term offtake contracts. Third-party logistics providers show highest price sensitivity, while pharmaceutical cold chain buyers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive and electronics buyer demand through multi-year service contracts covering equipment, substrate, and preventive maintenance. Manufacturing concentrates in Germany, the United States, and China, with kraft paper sourcing anchored in FSC-certified Nordic and North American pulp networks. Raw material dependencies rest on low-density polyethylene resin, unbleached kraft fiber, and specialized anti-static additives. Single-source vulnerability sits with precision foam molders serving Stuttgart automotive clusters. Distribution runs through manufacturer-direct technical sales for automated installations and industrial distributors for mid-volume replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing captive control over automated dispensing equipment manufacturing to lock in substrate-of-choice bundling and service contract renewals.
For Market Incumbents: Cement fiber-based format leadership by acquiring regional kraft paper converters ahead of EU Green Deal packaging waste mandate deadlines. Expand automated equipment service footprints in India and Southeast Asia to preempt emerging local competitors. Backward integration into FSC-certified pulp supply secures raw material cost stability against Nordic fiber price volatility. For New Entrants and Emerging Players: EU Green Deal packaging directives in Germany and France open a window for mono-material paper void fill specialists to capture share from polyethylene-dependent incumbents. Target mid-tier e-commerce fulfillment centers in India where paper-based protective packaging penetration remains below automated air cushion deployment. Lead with on-demand paper dispenser leasing models that convert capital expenditure to operational expenditure for logistics operators. For Investors and Strategic Acquirers: Re-rating potential sits with automated equipment-integrated substrate providers given extended producer responsibility framework rollouts across European markets. Long-term viability favors specialists with dual material-equipment capabilities rather than pure-play substrate manufacturers. Watch for BIS certification completion timelines in India as an inflection indicator for market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | FSC-certified fiber sourcing secures cost stability for EU Green Deal compliance. |
| Automated Dispenser Platform Launch | On-demand paper systems capture e-commerce retrofit demand from legacy film infrastructure. |
| Pharmaceutical Cold Chain Certification | FDA 21 CFR compliance opens insulated void fill opportunities in biologics distribution. |
| Regional Manufacturing Scale-Up | India fulfillment center construction accelerates paper-based protective packaging adoption. |
| Extended Producer Responsibility Partnership | Pre-mandate substrate conversion agreements position suppliers ahead of fee structures. |
Research Methodology
Document review covered customs and trade databases, SEC filings from protective packaging manufacturers, EU regulatory directive texts, and automotive export packaging specifications, complemented by interviews with fulfillment center operations directors, automated packaging equipment engineers, pharmaceutical supply chain managers, and kraft paper procurement leads. Secondary validation drew from EPA recycled content guidelines, ECHA REACH restriction updates, and ISO 18606 certification records. Bottom-up triangulation of dispenser deployment counts and substrate consumption volumes was cross-checked against top-down market sizing from trade association aggregates.
Segment-level outputs across material type, application vertical, equipment integration depth, and regional regulatory cluster were generated through the projection horizon. CAGRs were derived from elasticity modeling of e-commerce parcel growth against packaging intensity per shipment. Industry-specific inputs included automotive export volume forecasts from Stuttgart and Wolfsburg manufacturing clusters, and e-commerce fulfillment center construction pipelines across India and Southeast Asia.
The model assumes a particular technology adoption path for on-demand paper dispensing systems; alternative pathways favoring continued polyethylene air cushion dominance would alter the outlook for fiber-based substrate demand. Forecasts reflect assumptions regarding EU Green Deal implementation timelines and BIS certification streamlining in India. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Cohesive Packaging Solutions Market
Packaging Solutions
Package Drop Box Market
Packaging Solutions
Supplements and Nutrition Packaging Market
Packaging Solutions
Transport Packaging Market
Packaging Solutions
CBD Product Packaging Market
Packaging Solutions
Contract Packaging and Fulfillment Service Market
Packaging Solutions
Sterilized Packaging Market
Packaging Solutions
Global Coding and Marking Solutions Market
Packaging Solutions
Europe Contract Packaging Market
Packaging Solutions
Anti-Counterfeit Clothing Packaging Market
Packaging Solutions
Packaging Solutions Market
Packaging Solutions
Consumer Packaging Market
Packaging Solutions
Patisserie Packaging Market
Packaging Solutions
North America Child Resistant Packaging Market
Packaging Solutions
Panel Level Packaging Market
Packaging Solutions
Contract Packaging Market