
 Contract Packaging and Fulfillment Service Market | 2026-2036
Contract Packaging and Fulfillment Service Market Size, Share, and Industry Trends Forecast 2026-2036
Contract Packaging and Fulfillment Service Market Outlook
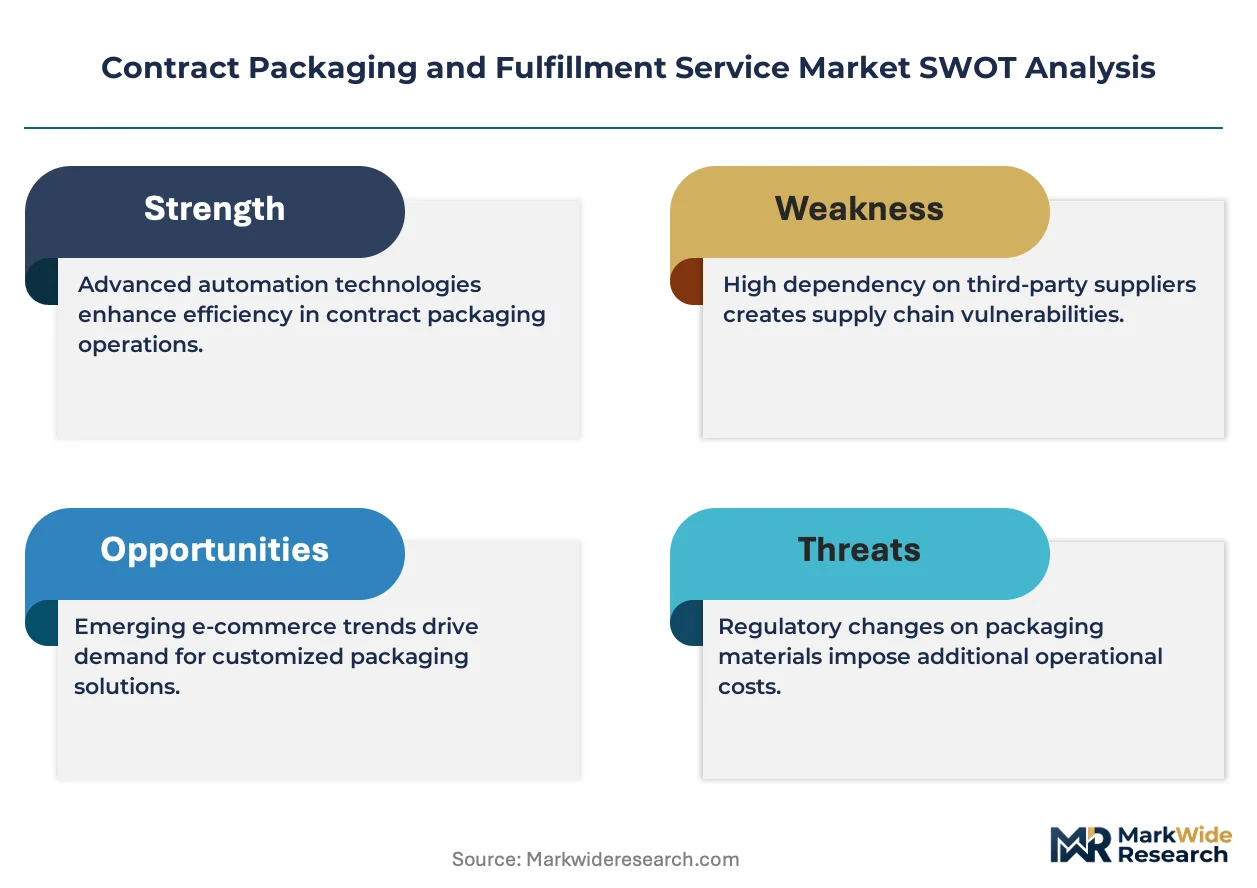
Packaging technician availability across North America and Western Europe is redrawing where contract operations expand versus stall. WestRock Company leverages its integrated paperboard and converting infrastructure to control large-format retail packaging programs for consumer brands. Sonoco Products Company anchors its position through engineered rigid containers and temperature-assured solutions that serve pharmaceutical cold chains. Sharp Packaging Services specializes in regulatory-compliant pharmaceutical packaging, including serialization and anti-counterfeiting integrations that FDA mandates require.
Contract packaging and fulfillment services encompass the outsourced physical preparation, containment, protection, and distribution of finished goods, typically operating under cGMP or ISO 9001 quality systems with lot-tracking capabilities down to unit level. These services span primary packaging (direct product contact such as blister forming and pouch filling) through secondary operations (carton assembly, labeling, case packing) to final distribution, serving manufacturers that lack internal capacity or seek variable-cost structures. Blister packaging and carton sealing dominate pharmaceutical and electronics segments where product integrity and tamper evidence carry compliance weight. E-commerce fulfillment represents the fastest-expanding delivery model as direct-to-consumer order profiles demand single-unit pick, pack, and ship capabilities with same-day or next-day service levels.
FDA serialization mandates under the Drug Supply Chain Security Act shape pharmaceutical contract packaging demand by requiring interoperable track-and-trace systems that many manufacturers outsource to specialized providers. OSHA workplace safety standards and EPA hazardous material handling regulations further constrain facility design and operational protocols across food, cosmetics, and chemical packaging sites. Stakeholders must evaluate whether provider investments in automated blister lines and warehouse management systems align with evolving DSCSA enforcement timelines and state-level e-commerce tax collection obligations.
Market Dynamics
Pharmaceutical serialization mandates under DSCSA are forcing manufacturers to outsource track-and-trace infrastructure, compressing decision timelines for contract packaging partnerships and redrawing competitive boundaries around regulatory compliance capabilities.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Serialization requirements for unit-level traceability drive pharmaceutical manufacturers toward specialized third-party providers with validated infrastructure.
- E-commerce fulfillment velocity:Direct-to-consumer order profiles demand same-day processing capabilities that strain in-house distribution networks.
- Cold chain expansion:Temperature-assured packaging for biologics and cell therapies creates specialized demand in pharmaceutical clusters across Massachusetts and North Carolina.
Market Restraints
- Qualified technician scarcity:cGMP-certified packaging operators command wage premiums that compress provider margins in competitive labor markets.
- Automated line capex concentration:Robotic blister packaging and carton sealing systems require capital deployment that favors scaled operators over mid-tier facilities.
- Resin and substrate volatility:Paperboard and polymer input costs fluctuate with pulp and petrochemical indices, complicating fixed-price contract structures.
Strategic Opportunities
- Cell and gene therapy packaging:Cryogenic labeling and ultra-low temperature logistics represent unmet white space with limited qualified provider capacity.
- State-level cannabis compliance:Track-and-trace mandates for adult-use markets create parallel demand for serialization infrastructure outside pharmaceutical channels.
- Return logistics integration:Reverse supply chain capabilities for medical device refurbishment and pharmaceutical returns remain underdeveloped among contract providers.
Industry Challenges
- Validation timeline compression:FDA inspection backlogs and site approval delays extend onboarding cycles for new manufacturing partnerships.
- Warehouse management system integration:Legacy ERP platforms at client sites create data interoperability friction with provider-side serialization databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contract Packaging and Fulfillment Service Market |
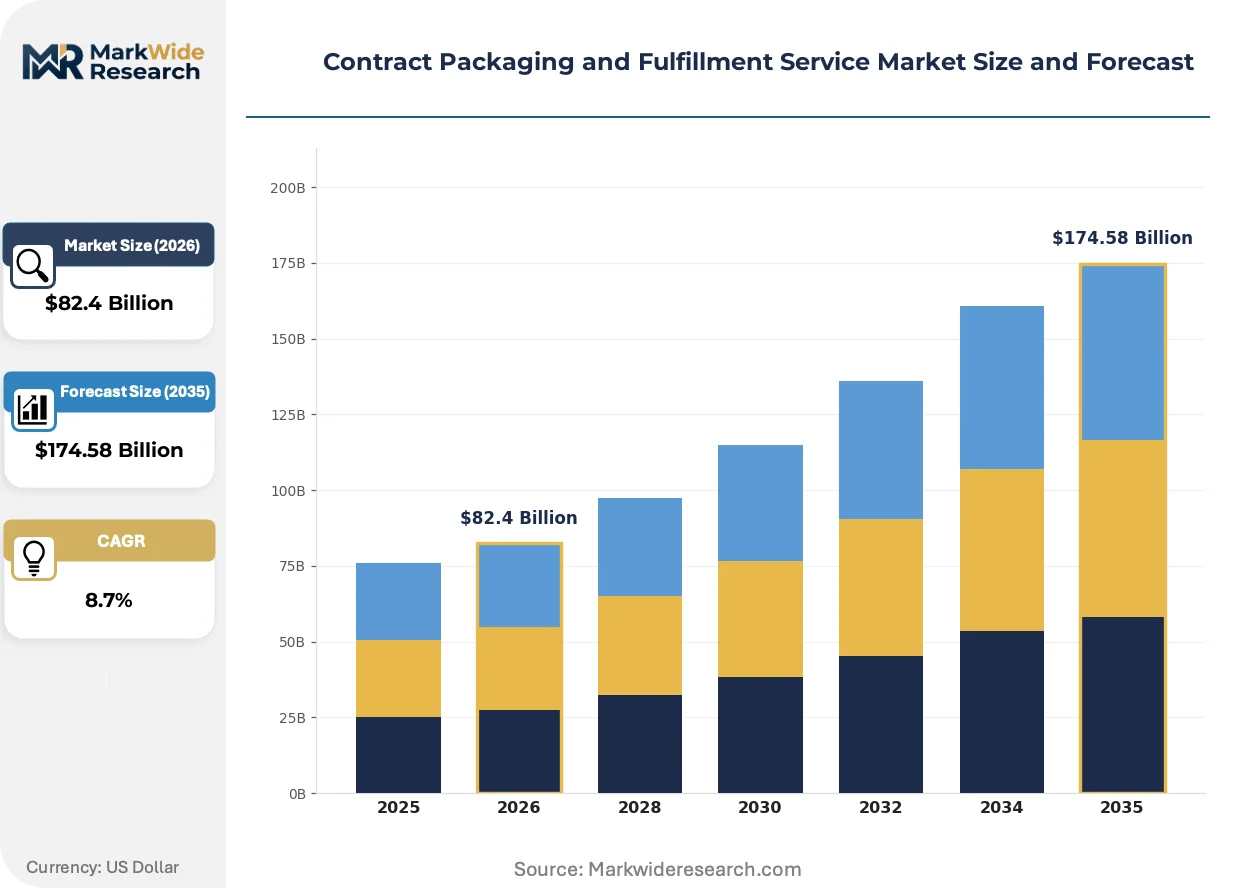
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $174.58 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Blister Packaging, Shrink Wrapping, Carton Sealing, Labeling End User: Pharmaceutical, Food & Beverages, Consumer Electronics, Cosmetics Packaging Type: Flexible Packaging, Rigid Containers, Glass Bottles, Pouches Delivery Model: Direct Shipping, Third-Party Logistics, In-House Distribution, E-commerce Fulfillment |
| Companies Covered | Aaron Thomas Company, ActionPak Inc., Assemblies Unlimited, PAC Worldwide Corp., AmeriPac LLC, WestRock Company, Sonoco Products Company, Econo-Pak, Sharp Packaging Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contract Packaging and Fulfillment Service Market Strategic Shifts
Automation architectures and regulatory data systems are converging to redefine operational benchmarks across pharmaceutical and consumer packaged goods channels.
Robotic palletizing and autonomous mobile robots are displacing manual material handling in high-velocity e-commerce fulfillment centers. Third-party logistics operators deploying these systems achieve throughput rates that manual configurations cannot match. The technology is displacing conventional warehouse labor models and compressing facility footprint requirements.
EMA's evolving guidance on serialized medicinal products for human use is extending track-and-trace obligations across European distribution networks. Pharmaceutical contract packagers serving EU markets must implement interoperable data exchange protocols that mirror DSCSA architecture. Small-molecule generics manufacturers in Germany and Italy face compressed implementation timelines for aggregation capabilities.
Subscription-based replenishment models for chronic disease therapies are fragmenting order profiles into high-frequency, low-unit shipments. Direct-to-patient pharmacy services bypass traditional wholesale distribution, demanding pick-and-pack precision at unit-of-use scale. This pattern concentrates operational investment in Pennsylvania and Tennessee distribution corridors serving Medicare-eligible populations.
Contract Packaging and Fulfillment Service Market Segmentation
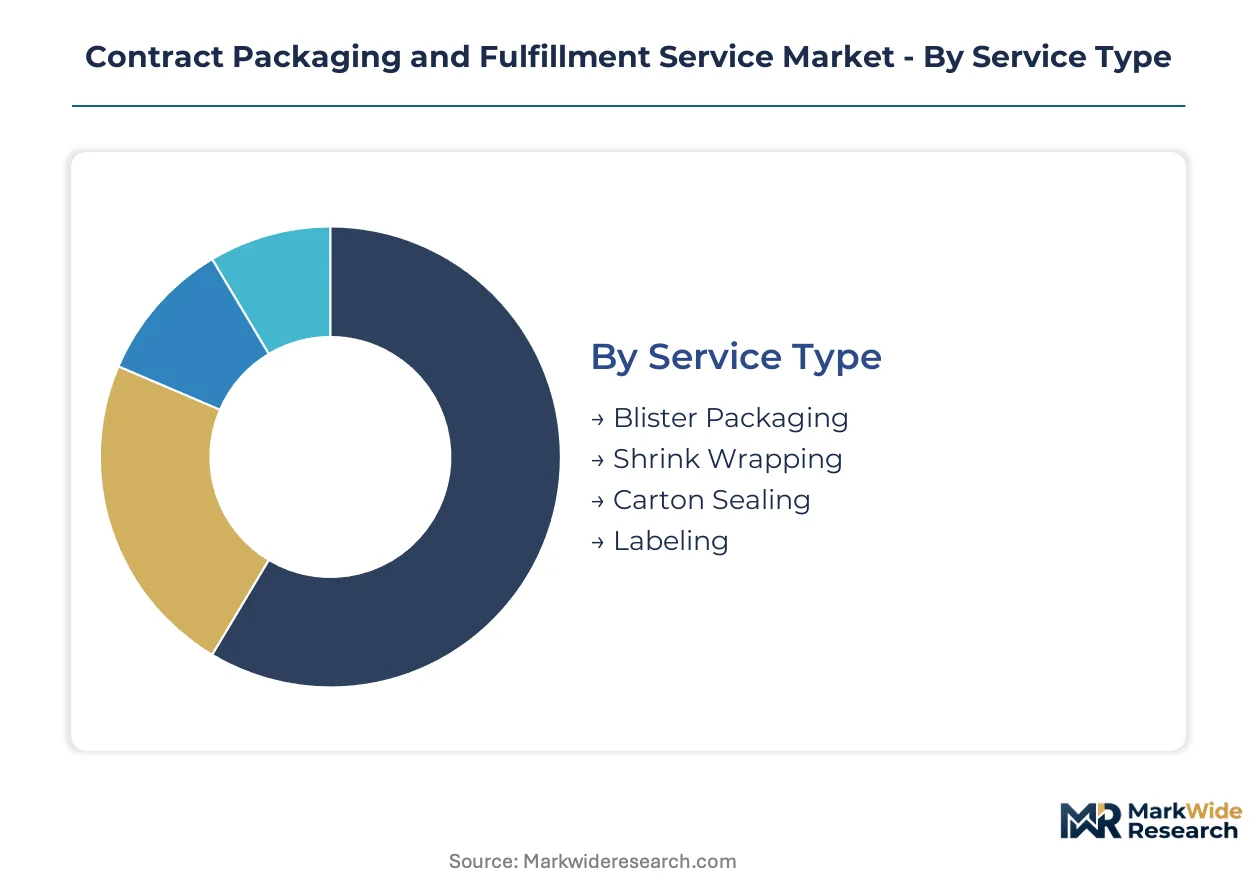
Service configuration across the contract packaging and fulfillment service market channels operational capability into distinct revenue streams. Each segment carries specific capital requirements, regulatory burdens, and margin profiles that shape provider specialization strategies.
Service Type:
Channel flow varies sharply by service complexity, with high-validity operations commanding pharmaceutical partnerships while commodity services feed retail replenishment networks.
- Blister Packaging:Thermoformed cavities sealed with lidding foil protect unit-dose pharmaceuticals from moisture and tampering. Demand concentrates in New Jersey and Pennsylvania corridors serving FDA-regulated oral solid dose manufacturers facing DSCSA serialization deadlines. Cold-form aluminum variants command premium positioning for moisture-sensitive biologics.
- Carton Sealing:Automated case erecting and tape application systems process high-velocity consumer goods throughput. Massachusetts and North Carolina facilities serve pharmaceutical secondary packaging where lot-code verification integrates with warehouse management systems. Robotic line integration compresses labor exposure in 24-hour fulfillment cycles.
- Shrink Wrapping:Polyolefin film heat tunnels bundle multi-unit retail configurations for club store and mass merchant channels.
- Labeling:Pressure-sensitive and sleeve applications apply regulatory content, barcodes, and brand graphics across primary and secondary packaging tiers.
By volume, carton sealing leads. By growth pace, blister packaging is ahead.
End User:
Cost tier stratification separates validated pharmaceutical services from standard-margin consumer applications, with certification requirements determining facility investment thresholds.
- Pharmaceutical:cGMP-compliant operations handle serialization, stability testing, and temperature-assured distribution for prescription and over-the-counter products. FDA inspection backlogs in Maryland and Puerto Rico extend onboarding timelines for new manufacturing partnerships. Cell therapy cryopreservation packaging represents emerging white space with limited qualified capacity.
- Consumer Electronics:Anti-static materials and foam-in-place protection secure high-value devices through e-commerce final mile. California and Texas distribution clusters serve direct-to-consumer order profiles demanding same-day processing capabilities. Subscription replenishment models fragment shipment sizes toward unit-of-use scale.
- Food & Beverages:Modified atmosphere packaging and allergen segregation protocols serve retail and foodservice channels.
- Cosmetics:Decorative finishing and kit assembly support brand differentiation in premium and mass-market tiers.
Pharmaceutical commands the highest margins. Consumer electronics is expanding most quickly.
Packaging Type:
Application requirements dictate material selection, with barrier properties and structural integrity driving specification decisions across temperature-sensitive and shelf-stable product categories.
- Flexible Packaging:Multi-layer films and stand-up pouches reduce material weight and cube utilization versus rigid alternatives. Illinois and Wisconsin converting infrastructure supplies rollstock to contract packagers serving snack food and personal care brands. High-barrier metallized variants penetrate pharmaceutical sachet applications.
- Rigid Containers:Injection-molded and thermoformed plastics provide dimensional stability for liquid and semi-solid products. Ohio and Indiana manufacturing clusters produce HDPE and PET containers for pharmaceutical and nutritional supplement contract filling. Child-resistant closure integration requires specialized line equipment.
- Glass Bottles:Amber and flint glass offers chemical inertness for parenteral and oral liquid pharmaceuticals.
- Pouches:Spouted and fitmented formats support on-the-go consumption in food and personal care segments.
Flexible formats dominate shipment count. Rigid containers carry the steepest expansion trajectory in pharmaceutical applications.
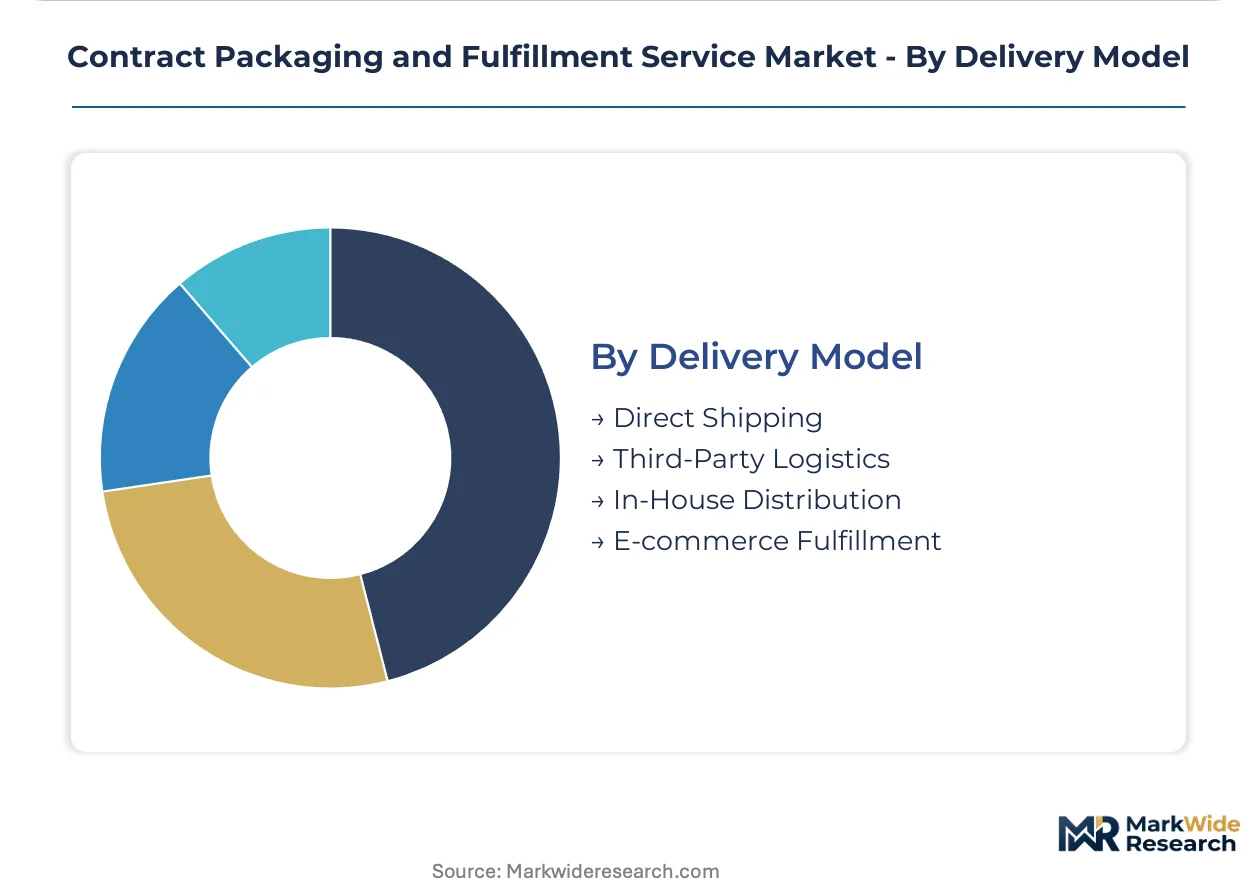
Delivery Model:
Customer type fragmentation separates enterprise manufacturers seeking variable-cost structures from emerging brands requiring turnkey fulfillment infrastructure.
- E-commerce Fulfillment:Single-unit pick, pack, and ship operations integrate with marketplace and direct-to-consumer platforms. Tennessee and Pennsylvania distribution corridors serve Medicare-eligible populations through direct-to-patient pharmacy services. Warehouse management system interoperability with client ERP platforms creates implementation friction.
- Third-Party Logistics:Consolidated transportation and inventory positioning reduce working capital requirements for mid-market manufacturers. Georgia and Florida hubs leverage port proximity for import distribution and export consolidation. Value-added packaging services differentiate commodity warehousing offerings.
- Direct Shipping:Manufacturer-controlled distribution maintains brand experience and customer data ownership.
- In-House Distribution:Captive logistics operations persist among high-volume manufacturers with predictable demand patterns.
Third-party logistics handles the greatest freight tonnage. E-commerce fulfillment is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA serialization mandates under DSCSA anchor North American contract packaging demand, while EMA track-and-trace obligations reshape European provider capabilities across multiple jurisdictions.
United States
Pharmaceutical manufacturers facing DSCSA deadlines drive outsourcing to specialized providers with validated serialization infrastructure. FDA inspection backlogs in Maryland and Puerto Rico extend onboarding timelines for new manufacturing partnerships. New Jersey and Pennsylvania corridor facilities serve oral solid dose producers requiring unit-level traceability systems.
Germany
EMA aggregation requirements for small-molecule generics compress implementation timelines for domestic manufacturers. The country's national pharmaceutical regulator enforces serialized medicinal product standards aligned with EU-wide traceability architecture. Bavaria and North Rhine-Westphalia host contract packaging clusters serving continental distribution networks.
China
NMPA drug traceability mandates for vaccine and injectable products expand serialization infrastructure requirements. The national medical products administration implements electronic drug monitoring codes across pharmaceutical supply chains. Yangtze River Delta converting facilities supply flexible packaging substrates to regional contract service providers.
India
CDSCO export-oriented manufacturing drives demand for EU and US-compliant packaging validation. The central drugs standard control organization harmonizes good manufacturing practice standards with international regulatory frameworks. Gujarat and Maharashtra pharmaceutical clusters outsource secondary packaging to manage serialization compliance for regulated markets.
Switzerland
Swissmedic precision requirements for biologics and specialty pharmaceuticals sustain premium-tier contract service demand. The national regulatory authority mandates batch release testing integration within packaging workflows. Basel-region facilities leverage proximity to major pharmaceutical headquarters for just-in-time manufacturing support.
Contract Packaging and Fulfillment Service Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with consolidated paperboard and rigid container manufacturers commanding pharmaceutical partnerships while mid-scale operators compete on e-commerce velocity. The market structure rewards capital-intensive automation investments that compress turnaround times for direct-to-consumer fulfillment. Three archetypes dominate: integrated packaging converters with captive substrate supply, temperature-assured logistics specialists serving cold chains, and regulatory compliance boutiques focused on serialization infrastructure. Competitive moves concentrate on automated line deployment and geographic expansion into pharmaceutical manufacturing clusters.
Among North American integrated providers, WestRock Company and Sonoco Products Company exemplify scale-driven archetypes, while Sharp Packaging Services occupies a position within the regulatory specialization tier. These entities represent contrasting strategic positions—substrate-integrated infrastructure versus compliance-centric service models—without implying specific market share or operational metrics.
| Leading Market Players |
|---|
| Aaron Thomas Company |
| ActionPak Inc. |
| Assemblies Unlimited |
| PAC Worldwide Corp. |
| AmeriPac LLC |
| WestRock Company |
| Sonoco Products Company |
| Econo-Pak |
| Sharp Packaging Services |
| Others |
Value Chain & Pricing Dynamics
FDA cGMP certification requirements gate entry into pharmaceutical contract packaging tiers while simultaneously enabling price premiums that separate validated operators from commodity providers. This dual function concentrates pricing power among facilities that have absorbed the capital burden of serialization infrastructure and inspection-readiness, leaving standard-margin consumer packaging exposed to input cost volatility.
Pricing Analysis
Massachusetts and North Carolina command 15-25% price premiums over Midwest consumer-packaging corridors due to cold-chain infrastructure density and proximity to biologics manufacturing clusters. Contract structures stratify across FDA-validated pharmaceutical tiers, ISO-certified food-grade mid tiers, and unvalidated commodity consumer tiers, with certification level and volume scale as primary differentiation drivers. Cost compression in the commodity tier intensifies as resin and paperboard indices fluctuate, while pharmaceutical buyers show lowest price sensitivity due to compliance risk exposure.
Supply Chain Analysis
Inventory buffers for serialized packaging components stretch lead times to 8-12 weeks versus 3-4 weeks for standard consumer formats, compressing working capital for mid-tier operators. Raw material supply draws from Ohio and Indiana rigid container manufacturing, Illinois and Wisconsin flexible film converting, and Yangtze River Delta specialty substrate imports. Single-source vulnerability concentrates in cold-form aluminum lidding foil for moisture-sensitive pharmaceuticals. Distribution runs through Tennessee and Pennsylvania e-commerce corridors for direct-to-patient fulfillment, with Georgia and Florida hubs handling import-export consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validated serialization capability and temperature-assured infrastructure are becoming scarce assets that determine which providers capture pharmaceutical outsourcing volume versus competing on thinning consumer margins. The widening gap between compliance-capable and commodity operators is restructuring partnership selection criteria across manufacturer procurement functions.
For Market Incumbents: Shield market position by accelerating automated blister line deployment in New Jersey and Pennsylvania corridors before DSCSA enforcement timelines harden, while securing backward integration into paperboard converting to offset resin volatility exposure. cGMP-certified technician retention programs represent the critical defensive lever against wage-premium compression. For New Entrants and Emerging Players: CDSCO export-validation fast-tracks open access to EU and US-compliant pharmaceutical outsourcing demand from Gujarat and Maharashtra manufacturing clusters. Cell therapy cryopreservation packaging and state-level cannabis track-and-trace compliance represent the most penetrable white spaces, with subscription-based direct-to-patient pharmacy services offering the clearest go-to-market angle. For Investors and Strategic Acquirers: DSCSA aggregation deadline reshapes the acquisition landscape toward providers with demonstrated FDA inspection history and interoperable warehouse management systems. Five-to-ten year viability favors temperature-assured logistics specialists over commodity e-commerce velocity plays, with site approval backlog duration as the signal to watch for capacity-constraint inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Blister Line Deployment | Robotic packaging systems compress labor exposure and align with DSCSA serialization timelines. |
| Cold Chain Infrastructure Expansion | Cryogenic labeling capabilities capture cell therapy packaging demand in Massachusetts and North Carolina. |
| Backward Integration into Converting | In-house paperboard supply insulates margin from pulp index volatility for retail packaging programs. |
| Warehouse Management System Interoperability | ERP integration with client serialization databases reduces onboarding friction for pharmaceutical partnerships. |
| Regulatory Certification Fast-Tracking | CDSCO and FDA dual-validation opens export-oriented manufacturing demand from India. |
Study Parameters
A standing panel of pharmaceutical packaging directors, cGMP compliance officers, third-party logistics procurement leads, and contract manufacturing executives provided ongoing calibration against operational realities. Primary fieldwork combined structured interviews with facility site assessments across New Jersey, Pennsylvania, Massachusetts, and North Carolina corridors. Secondary validation drew from FDA inspection databases, EMA serialized medicinal product guidance, DSCSA implementation timelines, and customs records for packaging substrate trade flows. Bottom-up service-type demand modeling triangulated against top-down pharmaceutical outsourcing expenditure estimates.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. The analytical framework modeled segmentation by service complexity tier, end-use regulatory cluster, packaging material format, and delivery model velocity. CAGRs were derived from fitted growth curves incorporating pharmaceutical serialization mandate phase-ins, e-commerce fulfillment penetration rates, and cold-chain infrastructure investment cycles. Industry-specific inputs included DSCSA enforcement timeline assumptions and biologics pipeline growth trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained FDA inspection backlog conditions and stable resin-paperboard price correlations; material deviation would warrant model refresh. Specific risk factors include accelerated DSCSA deadline shifts, tariff restructuring on Chinese substrate imports, and qualified technician wage spiral in competitive labor markets. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Contract Packaging Market
Packaging Solutions
United States Contract Packaging Market
Packaging Solutions
Hermetic Packaging Market
Packaging Solutions
Temperature Controlled Packaging Solutions Market
Packaging Solutions
Vacuum Skin Packaging Market
Packaging Solutions
Saudi Arabia Packaging Market
Packaging Solutions
Decoys and Dispensers Market
Packaging Solutions
Consumer Packaging Market
Packaging Solutions
Advanced Packaging Market
Packaging Solutions
Europe Contract Packaging Market
Packaging Solutions
Global Coding and Marking Solutions Market
Packaging Solutions
Anti-Counterfeit Clothing Packaging Market
Packaging Solutions
North America Secondary Packaging Market
Packaging Solutions
United Kingdom Packaging Market
Packaging Solutions
Secondary Packaging Market
Packaging Solutions
Stretch Sleeves and Shrink Sleeves Market