
 South Korea Smart Home Market | 2026-2036
South Korea Smart Home Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Smart Home Market Insights
Property developers are reorganizing the demand structure for smart home systems in South Korea, shifting volume away from individual retail buyers toward bulk procurement for new apartment complexes. Samsung Electronics Co., Ltd. dominates the appliance layer with refrigerators, air conditioners, and washing machines that communicate through its SmartThings platform. LG Electronics Inc. differentiates through AI-driven energy optimization across its ThinQ-enabled product range.
A smart home comprises interconnected devices, sensors, and control systems that automate residential functions through wireless protocols and centralized management interfaces. These installations typically operate on Wi-Fi, Zigbee, or Z-Wave networks with latency thresholds below 100 milliseconds for real-time security and climate responsiveness. Smart lighting and smart thermostats command the largest installed base among product categories, while home security applications generate the highest margin pools due to recurring monitoring subscriptions. The hospitality sector represents the fastest-growing end user segment as hotel chains retrofit properties with integrated guest room automation.
MFDS and KTL certification requirements shape device interoperability standards, while the Korea Communications Commission enforces spectrum allocation for IoT protocols. The Personal Information Protection Act imposes strict data localization rules on voice-activated platforms, compelling vendors to process biometric and behavioral data within domestic cloud infrastructure. Stakeholders must weigh the trade-off between open ecosystem interoperability and closed-platform data control as regulatory scrutiny intensifies.
Market Dynamics
KT Corporation's broadband infrastructure bundling is compressing standalone device margins while forcing appliance manufacturers toward platform-level integration. This infrastructure leverage is reorganizing competitive positioning around connectivity ownership rather than hardware differentiation.
Growth Catalysts
- Apartment Complex Bulk Procurement:Property developers in Seoul and Gyeonggi Province now specify smart home infrastructure as standard in new construction, creating guaranteed installation pipelines that bypass retail channel volatility.
- MFDS Certification Harmonization:Streamlined device interoperability standards reduce technical friction for multi-vendor deployments, accelerating complex system rollouts in residential towers.
- AI-Enabled Energy Optimization:Machine learning algorithms embedded in climate and lighting systems deliver measurable utility cost reductions, driving replacement cycles in existing housing stock.
Market Restraints
- Semiconductor Input Volatility:Memory chip and sensor component pricing fluctuations compress hardware margins for device manufacturers dependent on imported silicon supply.
- Cloud Infrastructure Concentration:Domestic data localization requirements under the Personal Information Protection Act limit vendor choice for voice processing backend services.
- Zigbee-Z-Wave Protocol Fragmentation:Incompatible wireless standards across legacy installations force expensive gateway hardware or complete system replacement.
Strategic Opportunities
- Busan-Ulsan Corridor Expansion:Secondary metropolitan construction booms outside the Seoul capital region present underpenetrated demand for integrated smart building systems.
- Hospitality Retrofit Segment:Hotel chains in Jeju and coastal tourism zones are accelerating guest room automation deployments to compete on service differentiation.
- Matter Protocol Convergence:Cross-platform interoperability standardization enables ecosystem-agnostic device positioning, reducing platform lock-in barriers for new entrants.
Industry Challenges
- Embedded Systems Firmware Talent Scarcity:Shortage of engineers proficient in real-time operating systems for sub-100-millisecond latency device control limits product development velocity.
- KTL Certification Timeline Compression:Extended testing protocols for RF emissions and electromagnetic compatibility delay product launches and compress revenue recognition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Smart Home Market |
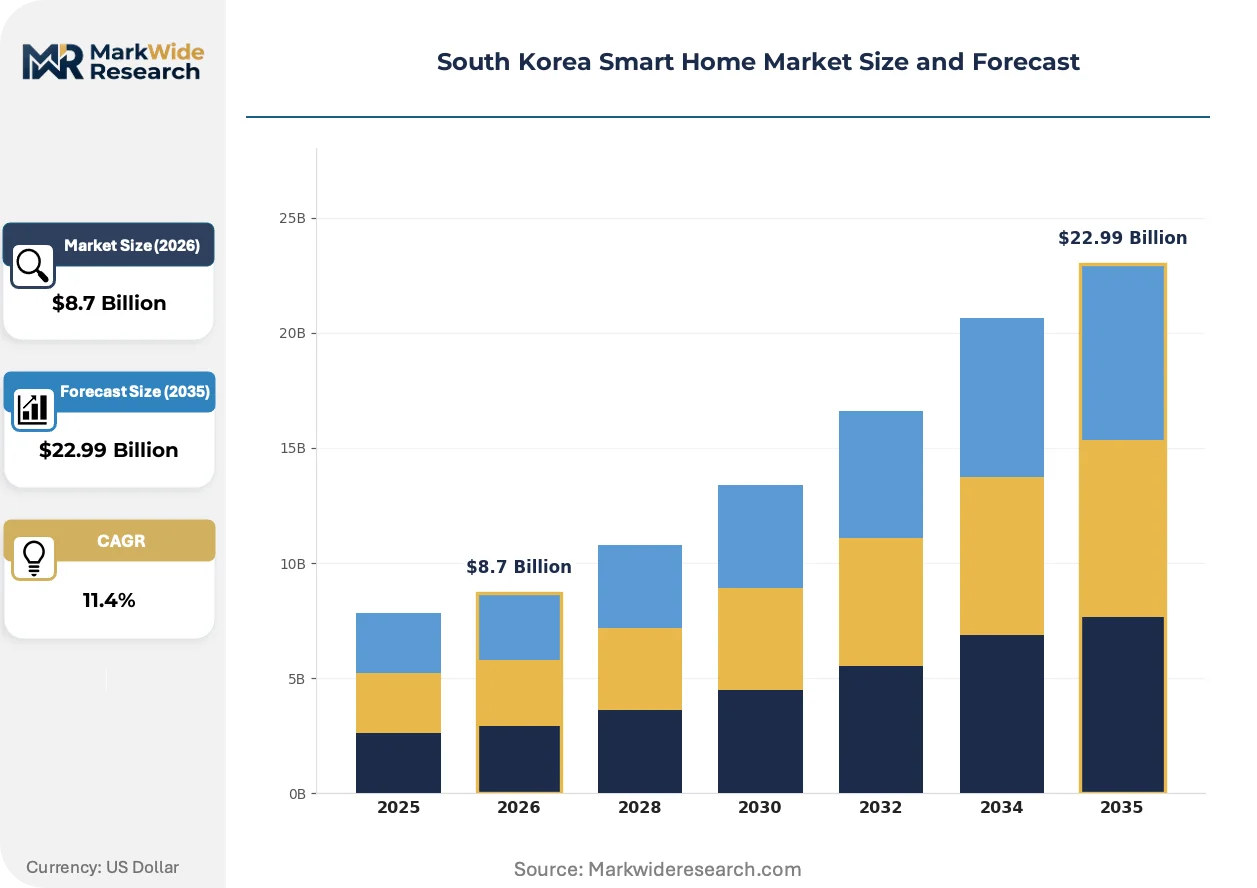
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Speakers, Smart Lighting, Smart Thermostats, Smart Locks End User: Residential Users, Property Developers, Hospitality Sector, Senior Living Technology: Wi-Fi, Bluetooth, Zigbee, Z-Wave Application: Home Security, Energy Management, Home Automation, Entertainment |
| Companies Covered | Samsung Electronics Co., Ltd., LG Electronics Inc., SK Telecom Co., Ltd., LG Uplus Corp., KT Corporation, Signify N.V., Coway, Winia, Hancom MDS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Smart Home Market Trends and Innovations
Edge computing architectures are displacing cloud-dependent processing in South Korean smart home deployments. This shift responds to data sovereignty pressures while enabling faster device response times for security-critical applications.
Matter-over-Thread protocol stacks are displacing proprietary Zigbee implementations in new device introductions. Major appliance manufacturers are adopting this unified connectivity standard for 2024-2025 product generations. The technology is displacing fragmented gateway hardware requirements, enabling direct smartphone-to-device commissioning without ecosystem-specific hubs.
The Korea Communications Commission's spectrum reallocation for sub-GHz IoT protocols is mandating device firmware updates across installed bases. Industrial consequence includes accelerated obsolescence of 2.4 GHz-only hardware in security and climate categories. Multi-dwelling unit installations in Incheon and Suwon are experiencing the highest retrofit pressure as property managers face compliance deadlines.
Builder-direct specification contracts are consolidating procurement authority away from retail channels. Large construction conglomerates now negotiate multi-year supply agreements with appliance vendors, bypassing traditional electronics distribution. This concentration is most visible in Songdo International Business District and other planned urban developments where single-source smart home packages are bundled into unit sales.
South Korea Smart Home Market Segmentation
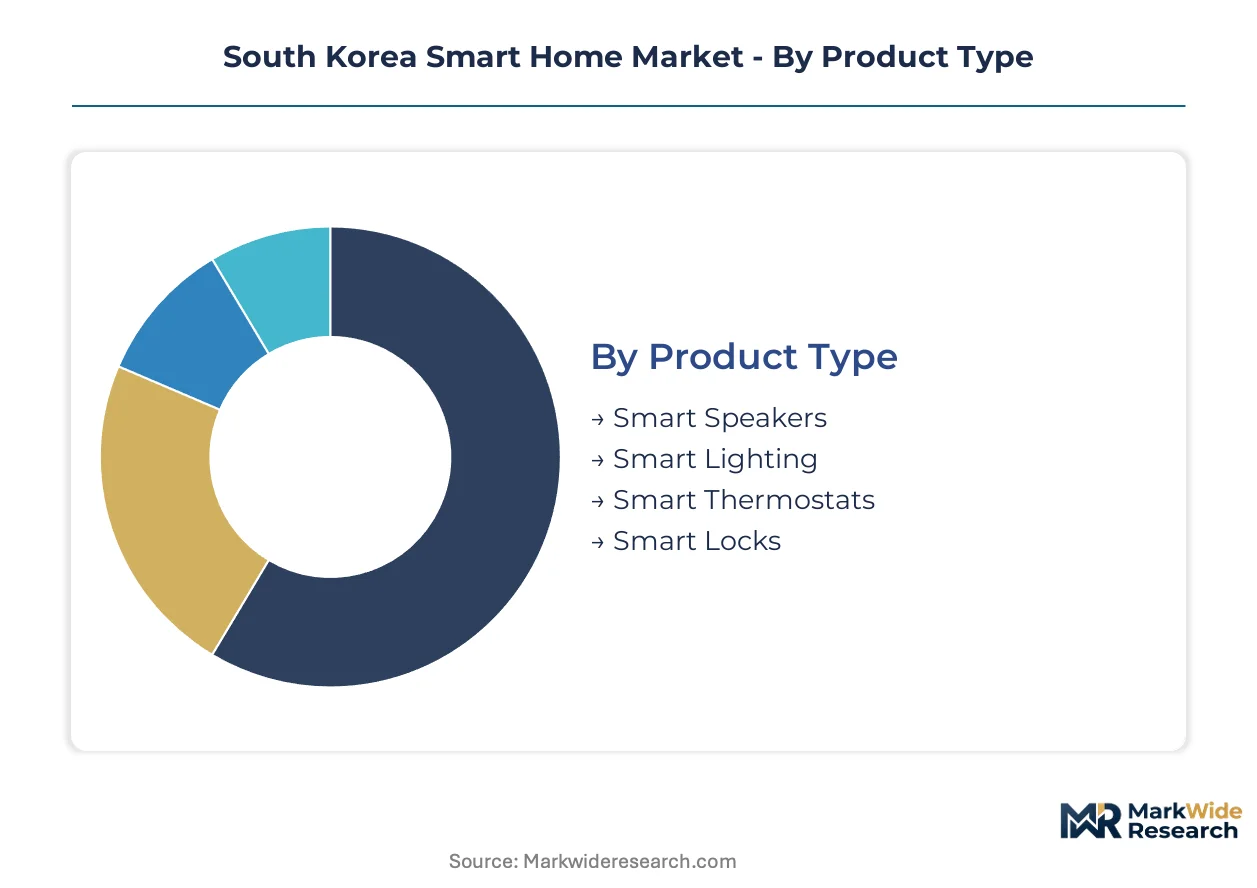
Segmentation in the South Korean smart home market reveals how regulatory mandates and construction practices reshape demand concentration across product categories. Distinct technology protocols and end-user procurement patterns create divergent margin structures that vendors must navigate.
Product Type:
Smart thermostats face the strongest substitution pressure from integrated HVAC systems with native connectivity, compressing standalone device opportunities.
- Smart Speakers:Voice-activated control hubs process natural language commands through domestic cloud infrastructure per Personal Information Protection Act requirements. Demand concentrates in Seoul apartment complexes where KT Corporation bundles these with broadband subscriptions, though privacy regulations limit foreign platform penetration.
- Smart Lighting:LED fixtures with embedded wireless controllers enable programmable color temperature and occupancy-based dimming. Property developers in Gyeonggi Province specify these as standard in new construction, driving bulk procurement volumes that bypass retail markup structures.
- Smart Thermostats:Climate control devices with machine learning algorithms optimize energy consumption patterns. Samsung Electronics and LG Electronics integrate these functions directly into air conditioning units, eroding standalone thermostat margins.
- Smart Locks:Biometric and keypad entry systems with remote access logging address MFDS security certification requirements. Hospitality chains in Jeju retrofit properties with these devices to differentiate guest experience.
Smart lighting anchors the volume base while smart locks gain share at the steepest rate.
End User:
Cost tier stratification separates premium integrated deployments from economy retrofit installations across South Korean demand segments.
- Residential Users:Individual homeowners purchase devices through electronics retail channels or direct-to-consumer platforms. Adoption concentrates among high-rise apartment dwellers in Busan seeking energy cost reductions through automated climate control.
- Property Developers:Construction conglomerates negotiate multi-year supply agreements for pre-installed smart home infrastructure. Seoul and Gyeonggi Province new builds specify complete system packages that eliminate consumer choice at point of sale.
- Hospitality Sector:Hotel chains deploy guest room automation for service differentiation and operational efficiency. Coastal tourism zones in Gangwon Province represent the most active retrofit geography.
- Senior Living:Assisted care facilities integrate fall detection and emergency response connectivity into residential units. Korea Communications Commission spectrum allocation for medical IoT devices supports this segment's specialized protocol requirements.
Property developers command the largest revenue pool while hospitality applications expand most quickly.
Technology:
Protocol maturity determines which wireless standards face obsolescence pressure from next-generation unified connectivity specifications.
- Wi-Fi:High-bandwidth protocol supports video streaming and firmware updates across device categories. Ubiquitous router penetration in South Korean households enables zero-additional-hardware deployment for bandwidth-intensive applications.
- Zigbee:Mesh networking standard with low power consumption dominates lighting and sensor deployments. Korea Communications Commission sub-GHz spectrum reallocation mandates firmware updates that accelerate hardware replacement cycles.
- Bluetooth:Short-range protocol enables direct smartphone commissioning without intermediary hubs. Matter-over-Thread convergence threatens Bluetooth's position in new device introductions.
- Z-Wave:Proprietary sub-GHz mesh technology with strong security specifications. Fragmentation against Zigbee forces expensive gateway hardware or complete system replacement in multi-dwelling retrofits.
Wi-Fi sustains the broadest installed base while Matter-compatible protocols capture the steepest share gains.
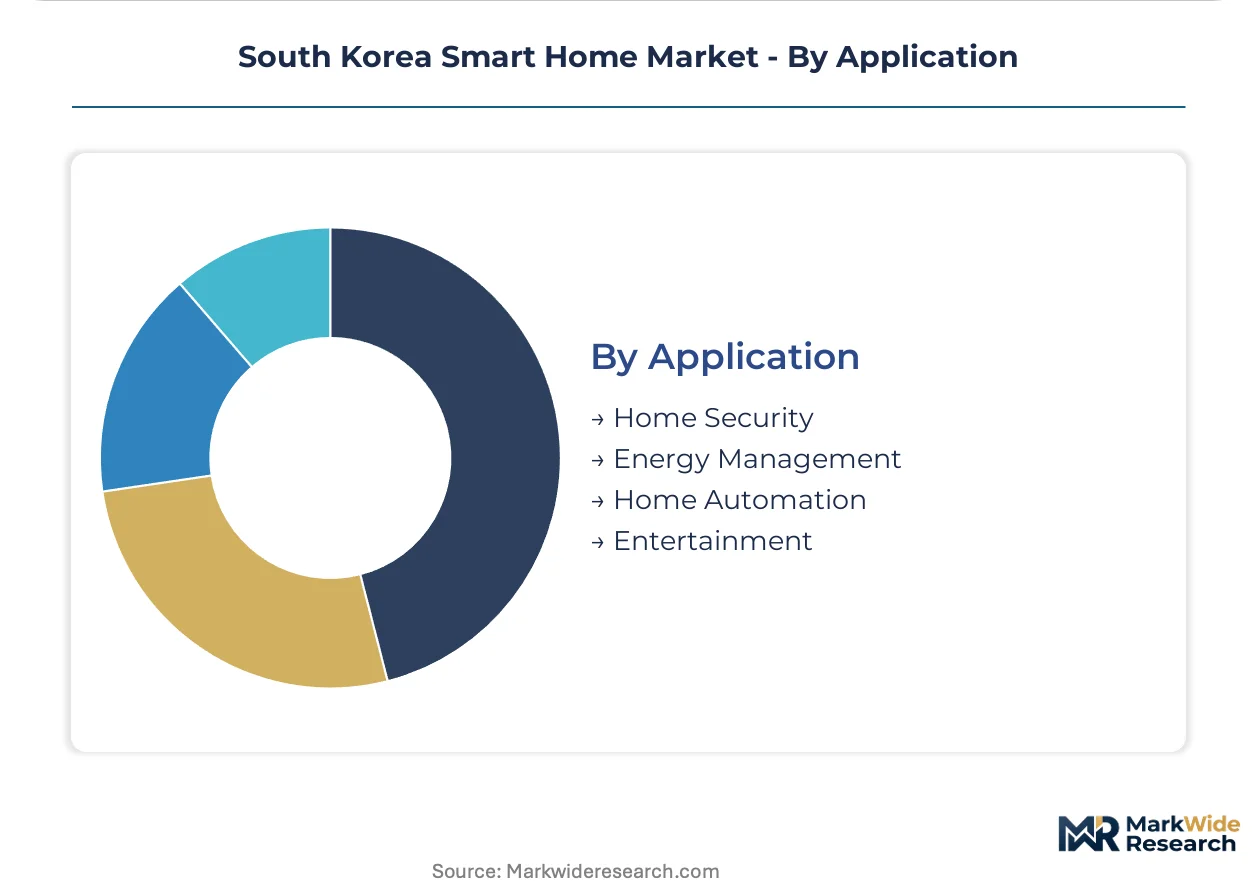
Application:
Margin concentration varies sharply across functional use cases, with recurring revenue models outperforming one-time hardware sales.
- Home Security:Integrated camera, sensor, and monitoring systems generate subscription-based recurring revenue. MFDS certification requirements for biometric data handling create compliance barriers that favor established domestic vendors.
- Energy Management:Climate and lighting optimization systems deliver measurable utility cost reductions. AI-enabled platforms from SK Telecom and KT Corporation leverage broadband infrastructure for real-time consumption analytics.
- Home Automation:Centralized control of multiple device categories through unified interfaces. Samsung SmartThings and LG ThinQ platforms compete for ecosystem lock-in through appliance integration.
- Entertainment:Audio-visual system integration with voice control and content synchronization. Streaming service bundling drives hardware attachment in premium residential segments.
Home security commands the highest margin pool while energy management climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The KTX high-speed rail network connects Seoul to Busan in under three hours, compressing logistics timelines for smart home component distribution across the peninsula. This infrastructure backbone underwrites South Korea's concentrated market geography.
Seoul Capital Area
Property developers in Seoul and Gyeonggi Province specify smart home infrastructure as standard in new apartment complexes, creating guaranteed installation pipelines. MFDS certification requirements for biometric data handling shape device interoperability standards in this corridor. Songdo International Business District exemplifies single-source smart home packages bundled into unit sales.
Busan-Ulsan Corridor
Secondary metropolitan construction booms outside the capital region present underpenetrated demand for integrated smart building systems. The Korea Communications Commission enforces spectrum allocation for IoT protocols affecting deployments here. Hotel chains along the southeastern coast accelerate guest room automation to compete on service differentiation.
Daegu-Gyeongbuk
Industrial electronics manufacturing clusters support component supply chains for device assembly. KTL testing protocols for RF emissions and electromagnetic compatibility create certification bottlenecks for products sourced from this region. Smart factory retrofits in this manufacturing belt drive adjacent demand for industrial IoT expertise transferable to residential applications.
Daejeon-Sejong
Government administrative relocation to Sejong City concentrates procurement authority for public housing smart home specifications. The Personal Information Protection Act imposes strict data localization rules affecting voice-activated platform deployments here. Research institutes in Daejeon feed firmware engineering talent into the embedded systems pipeline.
Gwangju-Honam
Agricultural automation expertise in this southwestern region transfers to rural smart home retrofit applications. Senior living facilities integrate fall detection and emergency response connectivity into residential units here. Coastal tourism zones in adjacent Jeju drive hospitality sector retrofit demand for guest room automation.
South Korea Smart Home Market Competitive Landscape
Listed leaders compete with private specialists across platform integration and infrastructure ownership dimensions. The market structure concentrates around three domestic conglomerates with broadband, appliance, and mobile ecosystem assets, while foreign specialists occupy niche lighting and air quality segments. Strategic archetypes include infrastructure-leveraged platform operators, appliance-anchored ecosystem builders, and component-focused device specialists. Competitive moves center on builder-direct specification contracts and Matter protocol convergence to reduce interoperability friction.
Within the infrastructure-leveraged tier, KT Corporation and SK Telecom Co., Ltd. exemplify connectivity ownership strategies that compress standalone device margins. Samsung Electronics Co., Ltd. anchors the appliance-integrated ecosystem archetype through its SmartThings platform dominance. These three listed entities occupy positions that reshape competitive dynamics around broadband bundling and mobile platform integration rather than hardware differentiation alone.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| LG Electronics Inc. |
| SK Telecom Co., Ltd. |
| LG Uplus Corp. |
| KT Corporation |
| Signify N.V. |
| Coway |
| Winia |
| Hancom MDS |
| Others |
Pricing and Supply Chain Analysis
MFDS certification requirements for biometric data handling gate both supplier qualification and price differentiation simultaneously, forcing device vendors to absorb compliance costs or segment offerings across certification tiers. Property developers in Seoul negotiate bulk procurement contracts that compress margins for appliance manufacturers while creating volume-discount structures unavailable to retail channels.
Pricing Analysis
Volume-discount tiering structures dominate procurement between construction conglomerates and appliance vendors, with three-tier pricing separating premium integrated systems from standard modular packages and economy retrofit kits. Price differentiation hinges on KTL certification grade and after-sales service bundling, with full-service maintenance contracts commanding substantial premiums over hardware-only transactions. Pricing pressure stems from KT Corporation's broadband bundling strategy, which forces standalone device vendors toward razor-thin margins. Individual homeowners in Busan exhibit the highest price sensitivity, while hospitality chains in Jeju prioritize service differentiation over unit cost.
Supply Chain Analysis
Inventory lead times for memory chips and RF modules have elongated as semiconductor fabrication capacity concentrates in Taiwan, South Korea, and China. Smart home device assembly draws from Taiwanese sensor foundries, Chinese LED component suppliers, and domestic Korean packaging facilities. Single-source vulnerability in Zigbee chipset supply creates exposure to Korea Communications Commission spectrum reallocation mandates. Distribution runs through builder-direct specification contracts that bypass traditional electronics retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as Matter protocol convergence disrupts platform lock-in, creating entry points for ecosystem-agnostic specialists. Property developer procurement consolidation simultaneously generates volume concentration and niche openings for retrofit specialists serving existing housing stock.
For Market Incumbents: Secure builder-direct specification contracts in Songdo International Business District and other planned urban developments to lock out emerging competitors. Deepen backward integration into edge computing chipsets to reduce exposure to semiconductor input volatility. Invest in KTL certification pipeline acceleration to compress time-to-revenue for new product introductions.
For New Entrants and Emerging Players: Anchor in the Busan-Ulsan corridor's underpenetrated secondary metropolitan construction market, where incumbent platform bundling remains less entrenched. Target hospitality retrofit segments in Gangwon Province coastal tourism zones with guest room automation solutions. Pursue direct-to-property-manager sales models that bypass construction conglomerate procurement gatekeepers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across Matter-compatible device manufacturing as unified protocol stacks reduce gateway hardware requirements. Long-term viability favors acquisition targets with embedded systems firmware engineering capabilities and established KTL certification relationships. Monitor Korea Communications Commission sub-GHz spectrum implementation timelines as the critical inflection signal for hardware replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Cross-platform interoperability reduces ecosystem lock-in barriers for new device entrants. |
| Builder-Direct Supply Agreement | Multi-year contracts with Seoul construction conglomerates guarantee installation pipeline volumes. |
| Edge Computing Architecture Migration | Domestic data processing satisfies Personal Information Protection Act localization requirements. |
| Hospitality Retrofit Partnership | Jeju hotel chain deployments create recurring service revenue and reference installations. |
| Firmware Engineering Talent Acquisition | Real-time operating systems expertise addresses critical embedded systems capability scarcity. |
Research Methodology
A spread of perspectives from smart home platform engineers, property development procurement directors, KTL certification specialists, and hospitality technology managers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through Korea Communications Commission spectrum allocation filings, MFDS device registration databases, construction industry permit records, and SEC disclosures from listed appliance manufacturers. Bottom-up unit installation estimates triangulated against top-down broadband subscription bundling data.
Segmentation dimensions modeled include product category, end-user archetype, wireless protocol technology, and functional application across the projection horizon. CAGRs were derived from installation run-rate analysis and replacement cycle assumptions. Forecast inputs incorporated apartment complex construction pipelines from Seoul and Gyeonggi Province, plus Matter protocol adoption curves from major appliance manufacturer product roadmaps.
Material uncertainties — semiconductor supply disruptions, regulatory timeline shifts, and protocol standardization delays — sit outside the modeled envelope. Forecasts reflect documented assumptions about certification harmonization and construction activity continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
ISO Cylinder Market
Others
Advanced Combat Helmet Market
Others
AI in Precision Medicine Market
Others
Convertible Shipper Display Market
Others
Global Pumpkin Candles Market
Others
Air Separation Module Kit Market
Others
France Smart Home Market
Others
Smart-Connected Power Plug Socket Market
Others
US Cat Food Market
Others
Smartphone Gimbal Market
Others
Asia Pacific Foodservice Paper Packaging Market
Others
Cloud Broadcasting Solutions Market
Others
Underwater Communication System Market
Others
Wearable Solar Devices Market
Others
Canada 3D Printing Construction Market
Others
Thermal Energy Flow Metering Solutions Market