
 Uzbekistan Renewable Energy Market | 2026-2036
Uzbekistan Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Uzbekistan Renewable Energy Market Analytics
Utility-scale battery storage integration with photovoltaic arrays is fragmenting the traditional project development model in Uzbekistan. ACWA Power anchors the gigawatt-scale solar pipeline through its independent power producer concessions in the Navoi region. Masdar competes on technology leadership in hybrid solar-wind configurations, while Voltalia SA leverages its development platform to secure long-term power purchase agreements with state utility Uzbekenergo.
Uzbekistan renewable energy encompasses electricity generation systems harnessing solar irradiance, wind kinetic energy, biomass combustion, and hydropower gravitational potential, with photovoltaic modules typically rated at 540-600 Wp per panel and wind turbines sited at 80-120 meter hub heights to capture Central Asian wind regimes. Solar technology dominates current capacity additions due to declining module costs and the country's 1,800-2,000 kWh/m² annual irradiance. Hydropower retains structural importance through Soviet-era infrastructure on the Syr Darya and Amu Darya river basins, though large-scale project development now shifts toward pumped-storage augmentation for grid flexibility.
The Ministry of Energy implements renewable energy auctions under presidential decree PP-4249, while the State Inspectorate for Ecological and Technical Safety enforces environmental impact standards for utility-scale installations. Grid codes issued by Uzbekistan's national transmission operator mandate frequency response capabilities that shape inverter procurement specifications and project engineering. Stakeholders must monitor auction price floors and local content requirements as these mechanisms determine developer margins and technology sourcing strategies.
Market Dynamics
Presidential decree PP-4249 is restructuring Uzbekistan's renewable energy procurement through competitive auctions, displacing bilateral negotiations with transparent price discovery mechanisms that compress developer margins while accelerating capacity deployment timelines.
Growth Catalysts
- Feed-in tariff reforms:Presidential decree mechanisms guarantee long-term revenue stability for independent power producers, reducing financing costs for utility-scale photovoltaic installations.
- Mining sector offtake expansion:Industrial consumers in metallurgy and mineral processing are contracting directly with renewable developers to hedge against grid electricity price volatility.
- Land-irradiance convergence:Samarqand and Bukhara regions combine 1,800-2,000 kWh/m² annual solar irradiance with flat, arid terrain suitable for gigawatt-scale array deployment.
Market Restraints
- Polysilicon supply concentration:Module cost volatility tracks Chinese polysilicon production curtailments, exposing Uzbek projects to input price swings without domestic manufacturing buffers.
- Grid integration capacity:Soviet-era transmission infrastructure on the 220-500 kV backbone limits instantaneous renewable absorption, forcing curtailment during peak generation periods.
- Local content thresholds:Auction rules mandate domestic labor and equipment sourcing that outpaces Uzbekistan's nascent solar supply chain development, inflating project execution risk.
Strategic Opportunities
- Pumped-storage augmentation:Hydropower facilities on the Syr Darya and Amu Darya river basins offer retrofit potential for diurnal storage, pairing with photovoltaic generation to deliver firm capacity.
- Hybrid configuration adoption:Wind-solar co-location at 80-120 meter hub heights captures complementary generation profiles, optimizing transmission utilization across Central Asian wind regimes.
- Utility-scale battery integration:Lithium-ion storage systems are securing long-term power purchase agreement premiums by providing frequency response capabilities mandated in national grid codes.
Industry Challenges
- Inverter engineering specialization:Grid code requirements for frequency response and reactive power control demand scarce power electronics expertise, constraining equipment procurement timelines.
- Environmental compliance timelines:State Inspectorate for Ecological and Technical Safety permitting processes for utility-scale installations extend development cycles, compressing construction windows before tariff deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uzbekistan Renewable Energy Market |
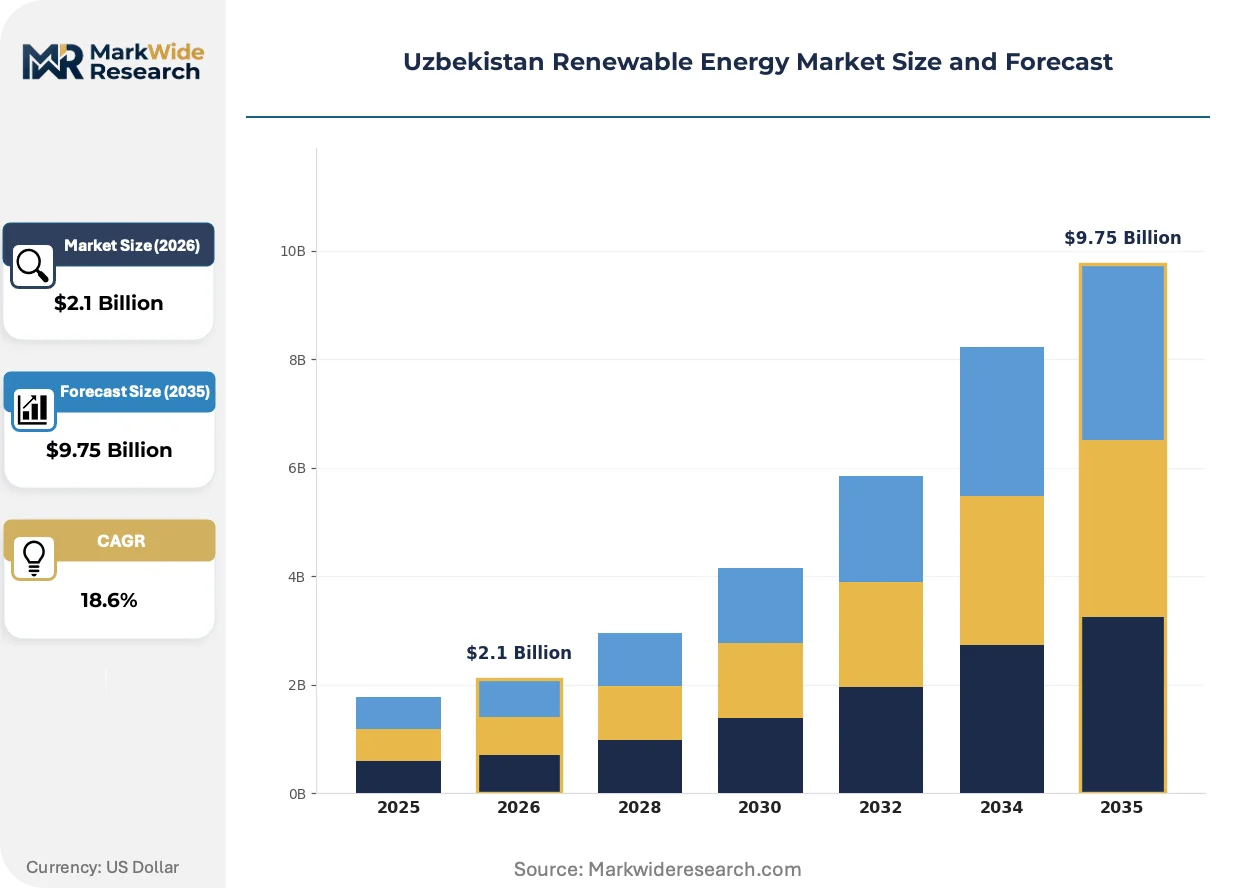
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $9.75 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Biomass, Hydropower End User: Residential, Commercial, Industrial, Utilities Application: Electricity Generation, Heating, Water Supply, Grid Support Capacity: Small Scale, Medium Scale, Large Scale, Utility Scale |
| Companies Covered | Voltalia SA, SkyPower Ltd, Masdar, Sinohydro Corporation, RusHydro, JSC Uzbekgidroenergo, Total Eren SA, WorleyParsons Limited, ACWA Power, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uzbekistan Renewable Energy Market Evolving Landscape
Technology convergence and procurement model evolution are compressing traditional development timelines in Uzbekistan's renewable sector, with digitalization and hybrid architectures displacing single-technology project structures.
Bifacial photovoltaic modules rated at 540-600 Wp are collapsing the levelized cost threshold for utility-scale deployment in Uzbekistan. Mining and metallurgy offtakers are specifying bifacial configurations in direct power purchase agreements to maximize energy yield per hectare. This technology shift is collapsing the economic viability margin between imported electricity and on-site renewable generation for energy-intensive industries.
Presidential decree PP-4249 auction frameworks are mandating price floors that expose developers to competitive bidding dynamics previously absent from Uzbek energy procurement. The Ministry of Energy's quarterly auction schedule compresses development timelines and forces technology standardization to meet bid deadlines. Independent power producers are responding by pre-positioning engineering resources and securing conditional financing before auction participation.
Long-term contracting is displacing merchant exposure as the dominant offtake structure for Uzbek renewable projects. State utility Uzbekenergo is fragmenting its procurement across 15-25 year power purchase agreements rather than assuming balance sheet risk for generation assets. This behavioral shift is most visible in the Navoi region, where ACWA Power and Masdar have secured multi-decade contracts that transfer operational risk to private developers while guaranteeing capacity payments.
Uzbekistan Renewable Energy Market Segmentation
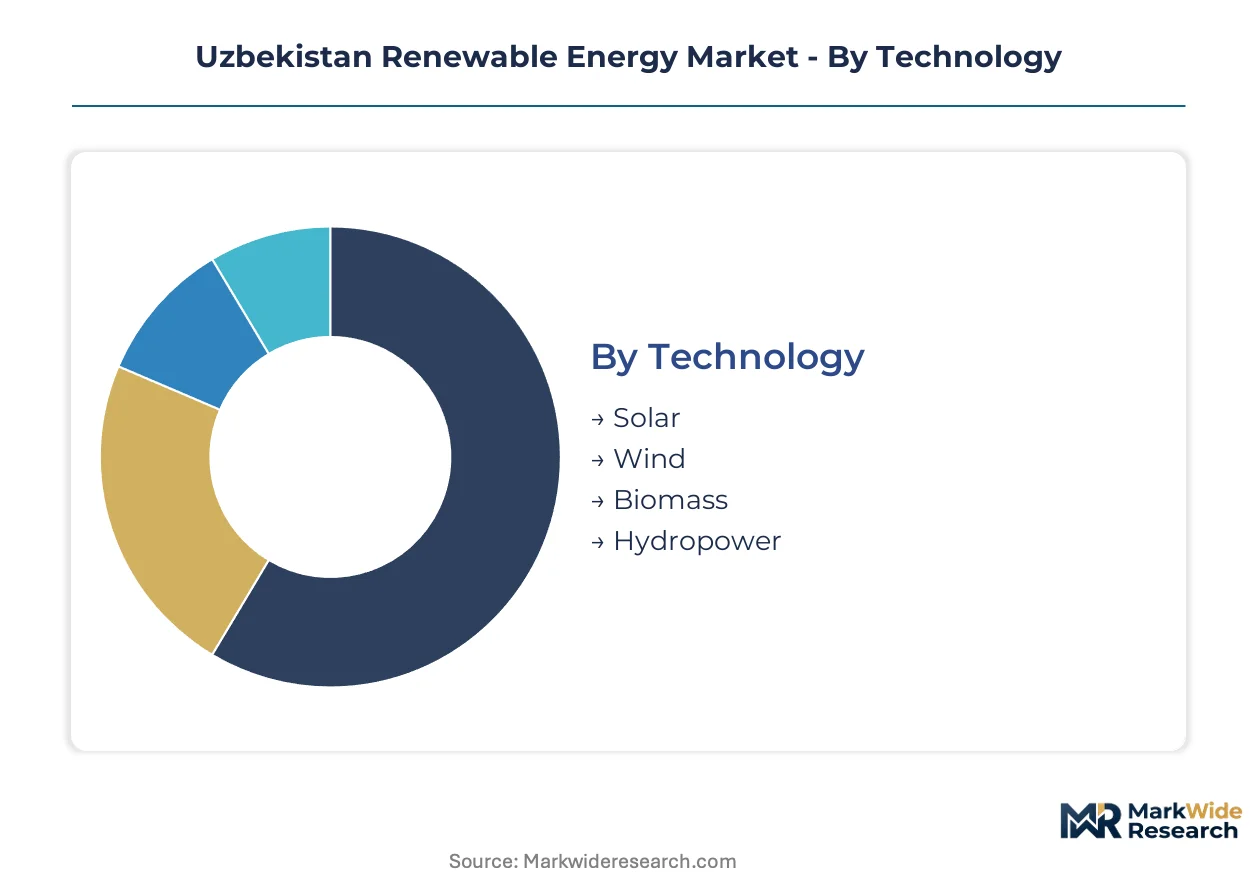
Technology selection determines project economics and grid integration requirements across Uzbekistan's renewable procurement landscape. End-use diversification and capacity tiering shape developer strategies under auction frameworks mandated by presidential decree PP-4249.
Technology:
Use-case spectrum spans distributed residential installations to gigawatt-scale independent power producer concessions across irradiance-rich regions.
- Solar:Photovoltaic modules rated at 540-600 Wp dominate current capacity additions, with bifacial configurations maximizing yield per hectare in Samarqand and Bukhara where annual irradiance reaches 1,800-2,000 kWh/m². Mining and metallurgy offtakers specify solar arrays in direct power purchase agreements to hedge grid price volatility.
- Wind:Turbines sited at 80-120 meter hub heights capture Central Asian wind regimes, with hybrid wind-solar configurations optimizing transmission utilization through complementary generation profiles. Navoi region developments anchor the pipeline through ACWA Power concessions.
- Biomass:Agricultural residue combustion systems serve distributed heating applications in rural provinces with limited grid connectivity, though feedstock logistics constrain scale.
- Hydropower:Soviet-era infrastructure on the Syr Darya and Amu Darya river basins retains structural importance, with pumped-storage retrofit potential pairing with photovoltaic generation for grid flexibility.
Established volume favors solar; emerging adoption favors wind-solar hybrid configurations.
End User:
Customer archetypes range from price-sensitive households to energy-intensive industrial complexes with balance sheet capacity for long-term contracting.
- Residential:Distributed rooftop installations under net metering frameworks serve urban households in Tashkent and regional capitals, constrained by financing access and grid connection queues.
- Commercial:Retail and office buildings deploy mid-scale arrays to offset consumption, though tariff structures limit export economics.
- Industrial:Mining and metallurgy sectors contract directly with developers for utility-scale offtake, specifying firm capacity requirements and technology configurations in 15-25 year power purchase agreements.
- Utilities:State utility Uzbekenergo fragments procurement across competitive auctions, transferring operational risk to independent power producers while guaranteeing capacity payments under decree PP-4249 frameworks.
Industrial offtake commands developer attention; utility procurement sets price benchmarks.
Application:
Functional deployment spans electrons, thermal energy, water infrastructure, and grid stability services with diverging technical specifications.
- Electricity Generation:Utility-scale photovoltaic and wind installations feed the 220-500 kV transmission backbone, with frequency response capabilities mandated in national grid codes shaping inverter procurement.
- Heating:Biomass combustion and solar thermal systems serve district heating networks in colder provinces, though seasonal demand mismatches with solar generation complicate integration.
- Water Supply:Solar-powered pumping infrastructure supports irrigation and potable water distribution in arid regions, reducing diesel dependence for remote communities.
- Grid Support:Lithium-ion battery systems and pumped-storage hydropower provide frequency regulation and peak shaving, securing power purchase agreement premiums through ancillary service revenues.
Electricity generation absorbs capital deployment; grid support applications gain policy priority.
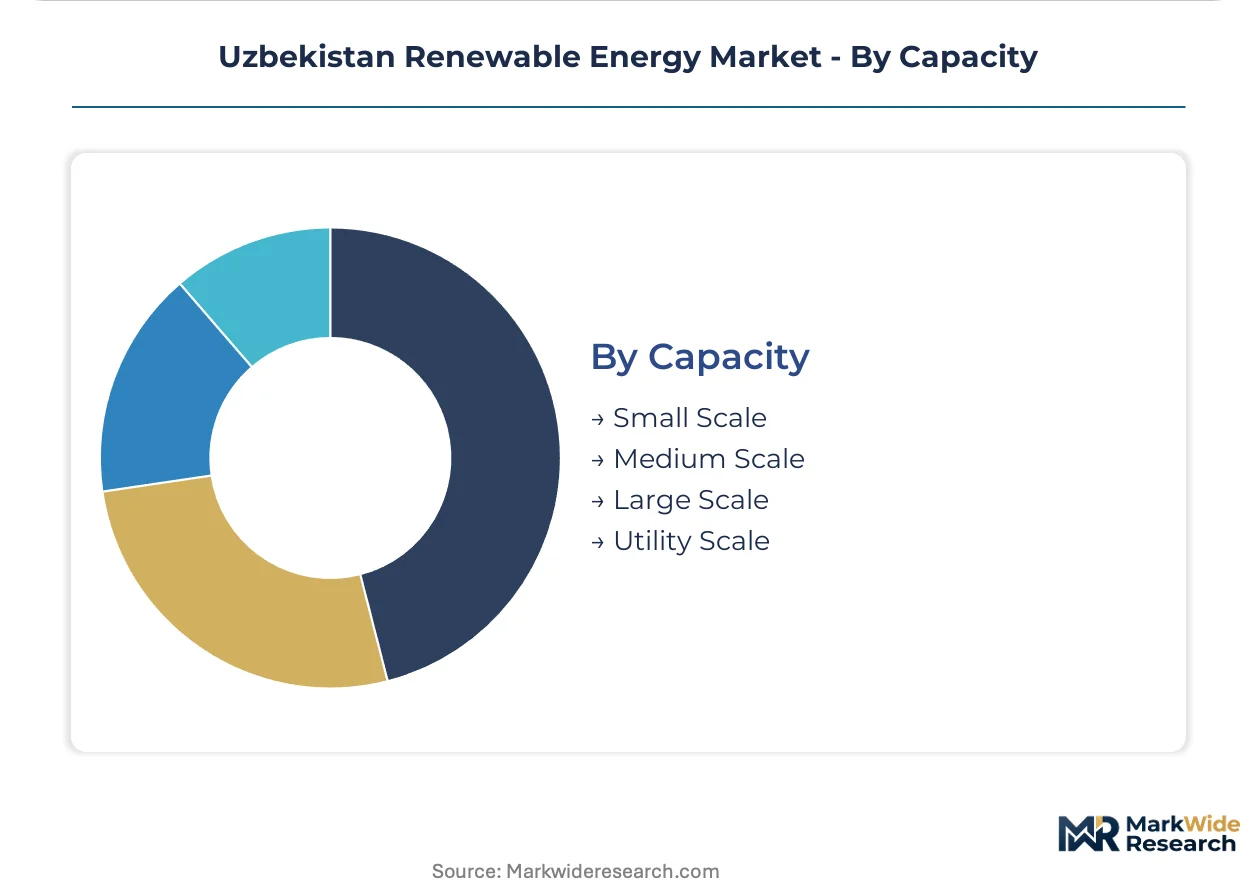
Capacity:
Scale tiers align with financing structures, permitting pathways, and grid connection voltage levels under Ministry of Energy oversight.
- Small Scale:Sub-megawatt rooftop and mini-grid installations serve residential and rural commercial loads, navigating distributed generation regulations and local content requirements.
- Medium Scale:Commercial and industrial arrays between 1-20 MW leverage bilateral power purchase agreements, though transmission access constraints limit site selection.
- Large Scale:20-100 MW projects compete in quarterly auctions with standardized documentation requirements, compressing development timelines and forcing pre-positioned engineering resources.
- Utility Scale:Gigawatt-scale concessions in Navoi, Samarqand, and Bukhara regions anchor national capacity targets, with ACWA Power and Masdar securing multi-decade contracts through international competitive bidding.
Utility-scale projects concentrate investment flows; small-scale deployment expands geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Uzbekistan exports renewable energy project development expertise and equipment procurement services to neighboring Central Asian republics and South Asian markets. Trade corridors link Tashkent-based engineering firms with demand centers in Kazakhstan, Kyrgyzstan, and Afghanistan. Cross-border transmission planning increasingly coordinates with these geographies to balance seasonal generation profiles.
Navoi Region
Industrial mining complexes anchor electricity demand growth in this central zone. Presidential decree PP-4249 auction frameworks prioritize Navoi for gigawatt-scale solar concessions due to land availability and existing 500 kV transmission access. ACWA Power operates multiple independent power producer facilities here, feeding the Navoi Mining and Metallurgy Combinat's energy-intensive operations.
Samarqand Region
1,800-2,000 kWh/m² annual irradiance drives photovoltaic deployment concentration across this historic corridor. The Ministry of Energy directs quarterly auction capacity allocations toward Samarqand to diversify generation geography beyond Navoi. Bifacial module arrays at 540-600 Wp ratings dominate project configurations, with land-leasing agreements negotiated through regional administration channels.
Bukhara Region
Flat desert terrain and superior solar resource quality position Bukhara as the secondary utility-scale development hub. State utility Uzbekenergo channels power purchase agreement procurement toward this area to reduce transmission congestion on the Tashkent-Navoi corridor. Hybrid wind-solar configurations at 80-120 meter hub heights capture complementary generation profiles across the Kyzylkum Desert fringe.
Tashkent Region
Capital-city load centers concentrate commercial and industrial offtake demand for distributed renewable generation. Net metering frameworks administered by the national transmission operator enable rooftop photovoltaic installations for corporate headquarters and logistics facilities. Grid code frequency response mandates shape inverter procurement specifications for projects connecting to the 220 kV urban substation network.
Karakalpakstan Autonomous Republic
Aral Sea basin hydropower infrastructure on the Amu Darya river system retains structural importance for grid flexibility services. Pumped-storage retrofit potential at Soviet-era facilities pairs with photovoltaic generation to deliver firm capacity during evening peak demand periods. Environmental permitting through the State Inspectorate for Ecological and Technical Safety governs any capacity augmentation projects in this sensitive watershed.
Uzbekistan Renewable Energy Market Competitive Landscape
Channel-controlling players compete with product-specialist players for procurement relationships with state utility Uzbekenergo and direct industrial offtakers. The competitive structure fragments across three tiers: international independent power producers holding multi-decade concessions, regional engineering contractors executing construction phases, and technology-agnostic developers bidding Ministry of Energy auctions. Strategic archetypes include auction-prepositioned developers securing conditional financing before bid submission, vertically integrated utilities leveraging balance sheet capacity, and hybrid technology specialists optimizing wind-solar co-location. Dominant competitive moves center on long-term power purchase agreement tenor extension and local content partnership formation to satisfy decree PP-4249 requirements.
Within the international independent power producer tier, ACWA Power and Masdar exemplify auction-winning archetypes through their Navoi region concessions. Voltalia SA occupies a position representing the European development platform model, securing offtake contracts through bilateral negotiation rather than pure auction competition. These three anchors demonstrate divergent geographic origins and concession structures while sharing dependency on Uzbekenergo payment guarantees.
| Leading Market Players |
|---|
| Voltalia SA |
| SkyPower Ltd |
| Masdar |
| Sinohydro Corporation |
| RusHydro |
| JSC Uzbekgidroenergo |
| Total Eren SA |
| WorleyParsons Limited |
| ACWA Power |
| Others |
Value Network & Pricing Analysis
Chinese polysilicon production curtailments determine both the spread between premium and standard module tiers and the geographic concentration of Uzbekistan's solar supply chain. Developers bidding under presidential decree PP-4249 face compressed margins when feedstock volatility transmits through crystalline silicon wafer pricing.
Pricing Analysis
Bifacial photovoltaic modules at 540-600 Wp ratings command premium positioning over monofacial alternatives due to energy yield advantages in Samarqand's irradiance conditions. Price differentiation rests on module efficiency grade and inverter frequency response certification tier. Pricing pressure stems from auction price floors mandated by the Ministry of Energy that force competitive bidding below prior bilateral negotiation levels. Industrial offtakers in mining and metallurgy show lowest price sensitivity due to grid price volatility hedging requirements, while residential rooftop segments face financing constraints that amplify sensitivity.
Supply Chain Analysis
Polysilicon feedstock draws primarily from China, with secondary sourcing from Germany and Malaysia for premium-grade material. Uzbekistan's project pipeline rests on imported crystalline silicon wafers, lithium-ion battery cells, and power electronics components. Single-source vulnerability concentrates in Chinese module assembly capacity, exposing developments to tariff exposure or export restriction events. Distribution runs through Tashkent-based engineering procurement contractors who coordinate international logistics with regional construction execution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Uzbekenergo's procurement fragmentation across multiple independent power producers signals buyer power consolidation that restructures developer margins. State utility payment guarantees now anchor project finance, shifting negotiation leverage toward the offtaker.
For Market Incumbents: Harden auction participation capabilities by pre-positioning conditional financing and engineering resources before Ministry of Energy bid deadlines. ACWA Power and Masdar demonstrate defensive positioning through multi-decade power purchase agreement tenors that lock in capacity payments. Counter emerging entrant pressure by deepening local content partnerships to satisfy decree PP-4249 domestic sourcing thresholds. For New Entrants and Emerging Players: Build out development platforms targeting medium-scale commercial and industrial segments between 1-20 MW that escape utility auction competition. The Karakalpakstan Autonomous Republic offers penetrable white space for pumped-storage retrofit projects pairing with photovoltaic generation. Secure bilateral offtake relationships with metallurgy sector energy managers before engaging auction frameworks. For Investors and Strategic Acquirers: The market sits at an infrastructure buildout phase that favors engineering-procurement-construction contractors with conditional financing capabilities. Long-term viability across the projection horizon rests on developer ability to navigate local content requirements and grid code compliance timelines. Watch auction participation rates as the inflection indicator for competitive intensity and margin compression trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Structuring | Long-term contracting with Uzbekenergo transfers operational risk while securing capacity payment guarantees. |
| Hybrid Technology Configuration | Wind-solar co-location at 80-120 meter hub heights optimizes transmission utilization across Central Asian regimes. |
| Local Content Partnership Formation | Domestic labor and equipment sourcing satisfies decree PP-4249 requirements that determine auction eligibility. |
| Grid Code Compliance Investment | Frequency response capabilities mandated by the national transmission operator shape inverter procurement specifications. |
| Pumped-Storage Retrofit Development | Soviet-era hydropower facilities on the Amu Darya offer diurnal storage pairing with photovoltaic generation. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility planning officers, independent power producer project developers, EPC contractors, and grid operators at Uzbekenergo. Secondary validation drew from presidential decree PP-4249 documentation, Ministry of Energy auction records, State Inspectorate for Ecological and Technical Safety permitting databases, and IEA Central Asia energy outlooks. Bottom-up project pipeline aggregation was triangulated against top-down capacity target assessments.
Calibration against historical auction outcomes and installed capacity trajectories anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include technology type, end-user archetype, application function, and capacity tier aligned with voltage connection levels. CAGRs were derived from regression analysis of auction price trends and capacity deployment schedules, with inputs from polysilicon cost curves and transmission infrastructure expansion timelines.
Stress conditions across feedstock price volatility, local content requirement stringency, and grid integration capacity constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about decree PP-4249 continuity and Uzbekenergo payment guarantee reliability. Cross-checking against IEA renewable investment flow benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar Traffic Light Market
Renewable Energy
Switzerland Renewable Energy Market
Renewable Energy
Renewable Energy Certificate Market
Renewable Energy
Renewable Heating Market
Renewable Energy
Global BIPV Glass Market
Renewable Energy
Wind Turbine Crane Market
Renewable Energy
South Africa Solar Photovoltaic (PV) Market
Renewable Energy
Green Renewable Energy Market
Renewable Energy
Solar Ceiling Fans Market
Renewable Energy
Solar Watch Market
Renewable Energy
China Wind Power Market
Renewable Energy
Italy Renewable Energy Market
Renewable Energy
Hydrokinetic Converters Market
Renewable Energy
Solar Boat Market
Renewable Energy
Zimbabwe Renewable Energy Market
Renewable Energy
Portugal Renewable Energy Market