
 Renewable Heating Market | 2026-2036
Renewable Heating Market Size, Share, and Industry Trends Forecast 2026-2036
Renewable Heating Market Intelligence
The direct-to-installer sales channel for heat pumps and solar thermal systems is reconfiguring the traditional wholesale distribution model. Johnson Controls leverages its extensive service network to secure commercial building contracts. Siemens Energy focuses on large-scale district heating projects, integrating geothermal and biomass sources. The Danfoss Group specializes in high-efficiency components, supplying critical parts to a wide range of system integrators.
Renewable heating encompasses technologies that generate thermal energy from non-fossil fuel sources like solar radiation, geothermal gradients, or biomass. These systems operate by capturing ambient energy, such as air-source heat pumps achieving a coefficient of performance (COP) above 3.0, or by combusting organic matter. Heat pumps, particularly air-source systems, lead the market in new installations for the residential end-user segment. In contrast, biomass boilers and geothermal systems find stronger application in industrial process heating and large-scale district heating projects.
Regulatory mandates are a primary catalyst, with the EU's F-Gas Regulation phasing out high-GWP refrigerants and the US Inflation Reduction Act (IRA) providing consumer tax credits. In China, the government's dual carbon goals are driving the expansion of geothermal district heating networks. System manufacturers must now navigate diverging regional component standards and incentive structures to maintain market access.
Market Dynamics
The renewable heating market's trajectory is defined by a fundamental tension between aggressive decarbonization mandates and the physical constraints of supply chains and skilled labor. Policy frameworks are accelerating the phase-out of fossil fuel systems, creating demand that outstrips current installation capacity.
Growth Catalysts
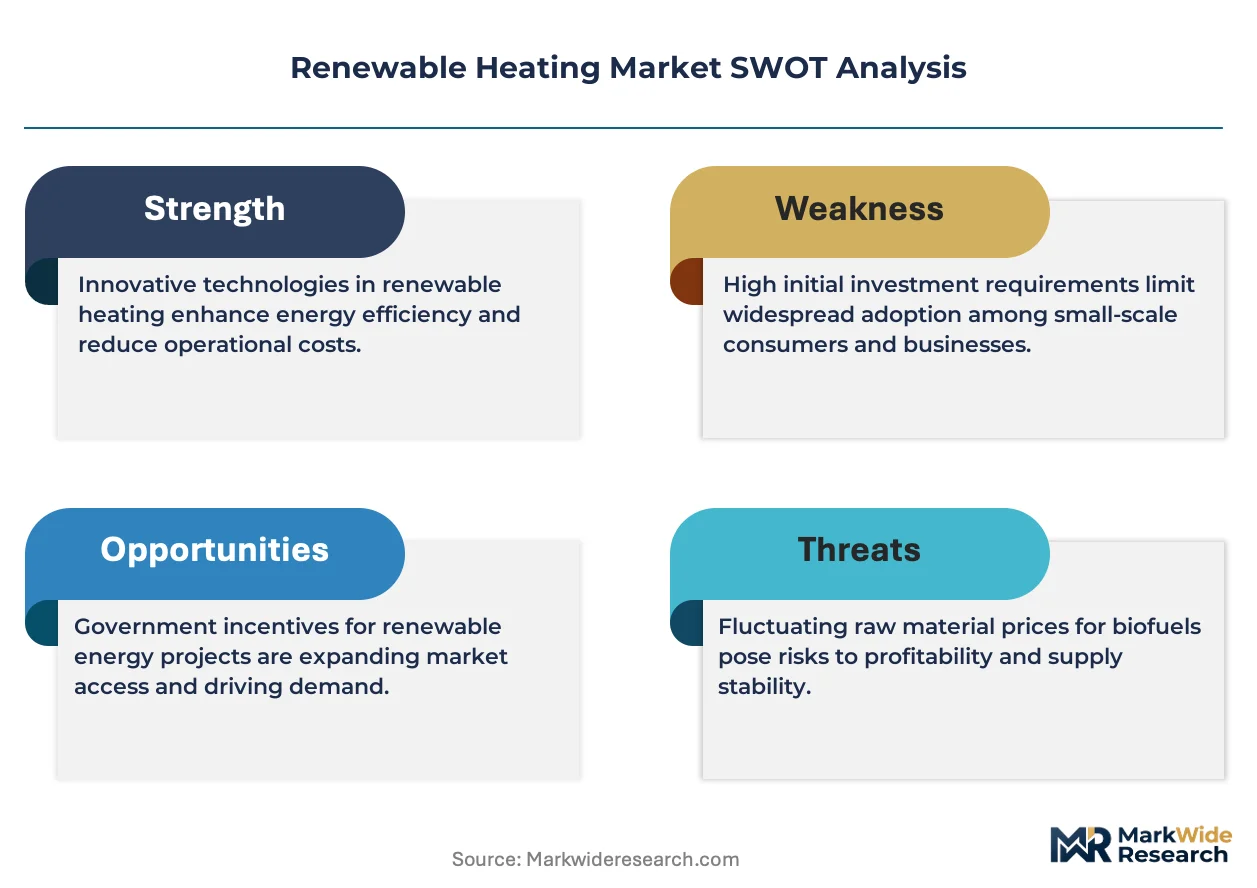
- National Phase-Out Mandates:Government policies, such as Germany's Building Energy Act which restricts new fossil fuel boiler installations, create compulsory replacement cycles and a predictable demand floor for renewable heating systems like heat pumps.
- Residential Retrofit Demand:A significant portion of market activity is concentrated in retrofitting existing residential buildings, particularly in developed economies with aging housing stock and strong consumer incentives for energy efficiency upgrades.
- Technology Efficiency Gains:Continuous improvements in heat pump technology, leading to systems with a coefficient of performance (COP) consistently above 3.0, strengthen the economic and environmental case for adoption over conventional heating.
Market Restraints
- High Upfront Capital Costs:The initial investment for geothermal and large-scale biomass systems remains a significant barrier for many residential and commercial end-users, despite lower long-term operational expenses compared to fossil fuel alternatives.
- Refrigerant Supply and Regulation:Heat pump manufacturing depends on specific refrigerants, the supply and cost of which are increasingly impacted by environmental regulations like the EU's F-Gas Regulation, creating component sourcing uncertainty.
- Technical Intermittency:Solar thermal systems exhibit performance variability dependent on weather and daylight, necessitating costly and complex backup heating or thermal energy storage solutions to ensure consistent supply.
Strategic Opportunities
- District Heating Expansion:China's "dual carbon" goals are driving substantial investment in new and expanded geothermal district heating networks, representing a major opportunity for large-scale system integrators and component suppliers.
- Heating-as-a-Service Models:The development of subscription-based service models allows customers to pay a recurring fee for thermal comfort, removing the barrier of high upfront equipment costs and shifting the market towards long-term service contracts.
- Smart Grid Integration:Connecting renewable heating systems, particularly heat pumps, to smart grids enables participation in demand-response programs, offering new revenue streams for owners and enhancing grid stability for utility operators.
Industry Challenges
- Skilled Labor Scarcity:A critical shortage of certified technicians and installers with expertise in designing, installing, and servicing modern heat pump and geothermal systems constrains the market's ability to meet policy-driven installation targets.
- Retrofit Integration Complexity:Upgrading older buildings with renewable heating technologies often requires extensive and costly modifications to a building's existing electrical, plumbing, and insulation infrastructure, complicating project timelines and budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renewable Heating Market |
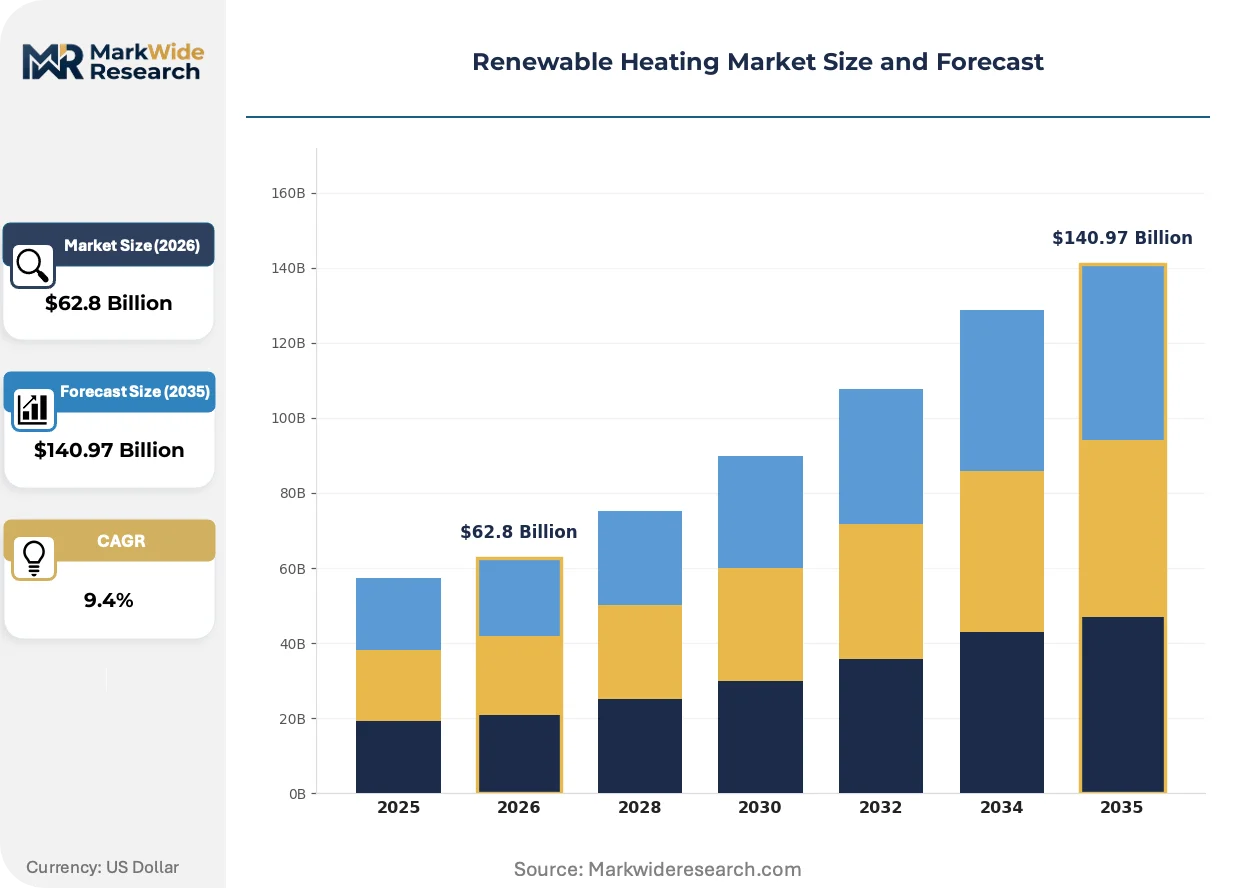
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $140.97 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Pumps, Solar Thermal, Biomass Boilers, Geothermal Systems End User: Residential, Commercial, Industrial, Government Technology: Hydronic Systems, Air-source Systems, Ground-source Systems, Radiant Heating Application: Space Heating, Water Heating, Process Heating, District Heating |
| Companies Covered | Siemens Energy, Johnson Controls, Panasonic Holdings Corporation, GEA Group Aktiengesellschaft, Mitsubishi Electric Corporation, ENGIE, Vattenfall AB, The Danfoss Group, Fortum Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renewable Heating Market Strategic Shifts & Innovations
System intelligence and component specialization are fundamentally altering the competitive landscape. The market is shifting from the sale of standalone hardware towards the delivery of integrated, data-optimized thermal energy solutions that prioritize efficiency and grid interactivity.
Digital twin technology for district heating networks provides a virtual replica of the physical infrastructure. Municipal utilities and large commercial operators are adopting this approach to optimize performance across complex thermal grids. This technology is virtualizing network management, enabling predictive maintenance and dynamic load balancing without disruptive physical interventions.
The EU's F-Gas Regulation is progressively phasing down the use of high Global Warming Potential (GWP) refrigerants in heat pumps. This mandate is forcing an industry-wide pivot towards R&D in natural refrigerants like propane (R290) and carbon dioxide (R744). Heat pump manufacturers are redesigning entire product lines to comply, impacting component choices and system architecture across the residential sector.
Installers are increasingly bypassing traditional multi-step wholesale distribution to procure equipment directly from manufacturers. This disintermediation pressures conventional HVAC distributors, who now face competition from manufacturers building their own direct logistics and training platforms. This procurement pattern is most visible in mature European markets like Germany, where policy deadlines are accelerating installation rates.
Renewable Heating Market Segmentation
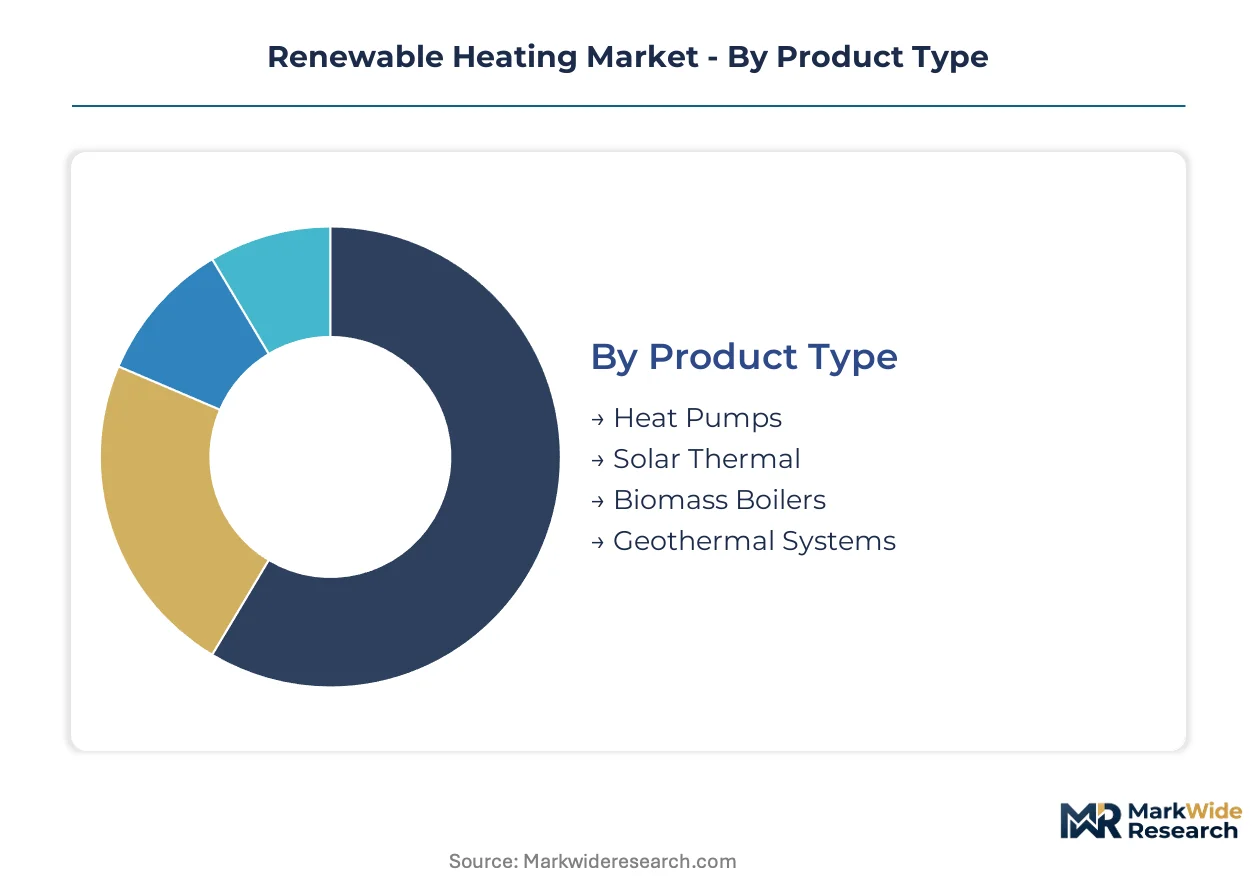
The renewable heating market's segmentation reveals distinct demand patterns and technological preferences across various applications. Understanding these divisions helps stakeholders align product development and service delivery with specific end-user needs and regulatory incentives. This granular view highlights where investment and innovation are most concentrated.
Product Type:
The after-sales service intensity for renewable heating products varies significantly, influencing installation complexity and long-term maintenance contracts across different system types.
- Heat Pumps:These systems leverage electricity to transfer heat from a source (air, ground, or water) to a building, achieving coefficients of performance (COP) above 3.0. Demand concentrates in the residential sector across Europe, driven by national phase-out mandates for fossil fuel boilers.
- Solar Thermal:These systems capture solar radiation to heat water or a heat-transfer fluid, primarily for domestic hot water and space heating. Performance variability due to weather necessitates backup systems, impacting adoption in regions with inconsistent sunlight.
- Biomass Boilers:These units combust organic matter like wood pellets or chips to generate heat, suitable for both residential and industrial applications. Industrial process heating in Germany utilizes biomass boilers for consistent high-temperature requirements.
- Geothermal Systems:These systems extract heat from the earth's stable underground temperatures using a ground loop, providing highly efficient heating and cooling. Large-scale district heating projects in China are expanding geothermal networks, supported by government dual carbon goals.
By volume, Heat Pumps lead new installations. By growth pace, Geothermal Systems are expanding most quickly.
End User:
Customer type dictates the scale and financial models for renewable heating deployment, ranging from individual household retrofits to extensive industrial process upgrades.
- Residential:This segment includes single-family homes and multi-unit dwellings, primarily requiring space heating and domestic hot water. Retrofitting existing residential buildings in developed economies drives significant market activity due to aging housing stock.
- Commercial:This segment covers offices, retail spaces, and public buildings, often demanding larger capacity systems for climate control. Johnson Controls secures commercial building contracts by leveraging its extensive service network and integrated solutions.
- Industrial:This segment encompasses manufacturing facilities and processing plants that require high-temperature heat for various processes. Biomass boilers and geothermal systems find stronger application here for energy-intensive operations.
- Government:This segment includes municipal buildings, schools, and public infrastructure projects, often driven by public sector decarbonization targets. China's government initiatives are expanding geothermal district heating networks for urban areas.
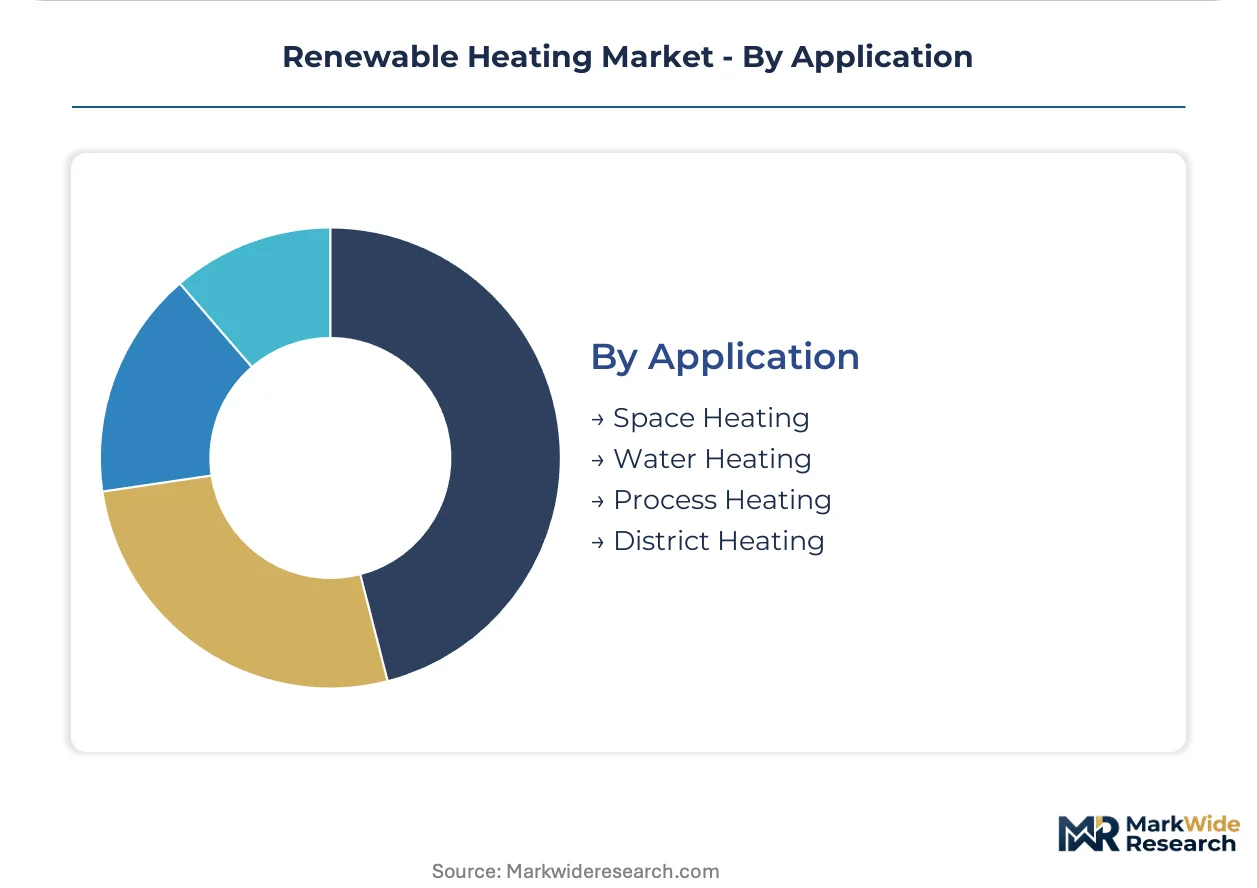
The Residential segment generates the largest share of demand. The Industrial segment shows the highest average project value.
Technology:
The maturity level of renewable heating technologies impacts their widespread adoption, with established solutions seeing broad deployment and newer innovations gaining traction in specific niches.
- Hydronic Systems:These systems circulate heated water through pipes to radiators, underfloor heating, or fan coils, providing efficient heat distribution. They are a common component integrated with various heat sources like boilers and heat pumps.
- Air-source Systems:These heat pumps extract heat from ambient air, even at low temperatures, making them versatile for many climates. They lead the market in new installations for the residential end-user segment due to ease of installation.
- Ground-source Systems:These heat pumps utilize the stable temperatures of the earth, offering high efficiency and consistent performance regardless of air temperature. Their installation requires significant upfront excavation for ground loops.
- Radiant Heating:This technology delivers heat directly to occupants and surfaces through infrared radiation, often via underfloor or ceiling panels. It provides comfortable, even heating with lower operating temperatures than forced-air systems.
Air-source Systems represent the most widely adopted technology. Ground-source Systems offer superior efficiency in colder climates.
Application:
The specific application of renewable heating systems determines the required temperature output, system scale, and integration complexity within existing infrastructure.
- Space Heating:This application focuses on maintaining comfortable indoor temperatures in residential, commercial, and industrial buildings. Heat pumps are particularly well-suited for space heating due to their energy efficiency.
- Water Heating:This application provides hot water for domestic use, commercial facilities, and industrial processes. Solar thermal systems are a traditional choice for water heating, especially in sunnier regions.
- Process Heating:This application involves generating high-temperature heat for industrial manufacturing and chemical processes. Large-scale biomass boilers and geothermal systems are essential for these energy-intensive operations.
- District Heating:This application distributes heat from a central source to multiple buildings through an insulated pipe network. Siemens Energy focuses on large-scale district heating projects, integrating diverse renewable sources.
Space Heating accounts for the largest share of renewable heating installations. District Heating projects are expanding rapidly in urban areas.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global renewable heating market benefits from extensive energy grid interconnectivity, facilitating cross-border technology adoption and resource sharing. This infrastructure supports widespread deployment of efficient heating solutions. Policy incentives across major economies accelerate this transition.
Germany
National phase-out mandates for fossil fuel systems and strong residential retrofit demand drive the German market. Germany's Building Energy Act restricts new fossil fuel boiler installations, creating compulsory replacement cycles. Bavaria's advanced manufacturing hubs actively produce heat pump systems for domestic and export markets.
United States
Consumer tax credits for energy efficiency upgrades and a focus on decarbonization stimulate demand in the United States. The US Inflation Reduction Act (IRA) provides significant financial incentives for renewable heating installations. California's progressive energy policies encourage adoption of heat pumps in urban centers and new constructions.
China
Large-scale district heating projects and industrial process heating applications represent significant demand in China. The government's dual carbon goals drive substantial investment in geothermal district heating networks. The Yangtze River Delta region is expanding its clean heating infrastructure for urban areas.
Japan
Energy security concerns and a preference for high-efficiency systems shape the Japanese renewable heating market. METI's (Ministry of Economy, Trade and Industry) initiatives promote the adoption of advanced heat pump technologies. Tokyo's commercial sector is actively investing in integrated thermal solutions for large buildings.
Sweden
An established district heating infrastructure and high biomass utilization rates characterize the Swedish market. Strong national decarbonization targets support the continued expansion of renewable heating sources. Stockholm's utility companies integrate diverse geothermal and biomass sources into their city-wide heating grids.
Renewable Heating Market Key Industry Players
On the supply side, the industry is transitioning from a fragmented landscape of traditional HVAC manufacturers to a more consolidated structure driven by specialized renewable heating providers. Strategic archetypes include large diversified industrial conglomerates, niche component innovators, and specialized system integrators. Dominant competitive moves involve strategic partnerships for market access and portfolio diversification into integrated energy solutions.
Within the integrated solutions provider archetype, Siemens Energy and Johnson Controls exemplify companies leveraging extensive service networks for commercial and large-scale projects. The Danfoss Group, a component specialist, focuses on supplying critical high-efficiency parts to a wide range of system integrators. These entities anchor distinct segments of the renewable heating value chain.
| Leading Market Players |
|---|
| Siemens Energy |
| Johnson Controls |
| Panasonic Holdings Corporation |
| GEA Group Aktiengesellschaft |
| Mitsubishi Electric Corporation |
| ENGIE |
| Vattenfall AB |
| The Danfoss Group |
| Fortum Corporation |
| Others |
Cost & Logistics Intelligence
Bavaria's advanced manufacturing hubs, specializing in heat pump production, exert significant influence on European pricing power for these systems, reflecting their capacity and technological leadership. This concentration impacts the cost structure for downstream installers and end-users.
Pricing Analysis
Volume-based pricing models differentiate between residential installers purchasing single units and commercial integrators securing bulk orders for heat pumps. Price differentiation arises from customization levels for district heating projects and the inclusion of comprehensive after-sales service packages. Pricing softness reflects intense competition in the residential air-source heat pump segment, driven by rapid technology adoption. The residential end-user segment exhibits the highest price sensitivity, while industrial clients prioritize long-term operational savings over upfront costs.
Supply Chain Analysis
Refrigerant production, particularly for low-GWP alternatives like R290, forms a critical upstream bottleneck, with China and the United States emerging as key supply geographies. Heat pump manufacturing relies heavily on specialized compressors and electronic controls, primarily sourced from Japan and Germany. Single-source vulnerability for advanced componentry poses a structural risk across the value chain. Equipment distribution runs through a reconfiguring channel, with direct-to-installer models gaining traction in mature European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The renewable heating market stands as a high-growth disruption, driven by aggressive decarbonization mandates like the EU Green Deal and the US Inflation Reduction Act.
For Market Incumbents: Build a data-driven service moat by integrating smart grid solutions and predictive maintenance platforms for commercial installations. Invest in R&D for natural refrigerants to mitigate F-Gas Regulation compliance risks and secure future component supply. Leverage existing service networks to offer Heating-as-a-Service models, countering the threat of high upfront capital costs for end-users.
For New Entrants and Emerging Players: Southeast Asia's nascent renewable heating markets present significant underpenetration for air-source heat pump installations in residential new builds. Target retrofitting opportunities in regions with aging housing stock and strong consumer incentives for energy efficiency upgrades. A go-to-market angle focused on simplified installation processes and bundled financing options can accelerate adoption.
For Investors and Strategic Acquirers: Long-term, this sits as a sustainable infrastructure play because national decarbonization targets create predictable demand floors for decades. Focus on acquiring specialized component manufacturers or regional system integrators with strong direct-to-installer channels. The signal to watch is the acceleration of skilled labor training programs, indicating reduced installation bottlenecks.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Direct-to-Installer Channels | This move optimizes logistics and reduces costs for heat pump manufacturers in Germany. |
| Invest in Natural Refrigerant R&D | This addresses EU F-Gas Regulation compliance and secures long-term component supply for heat pumps. |
| Develop Heating-as-a-Service Models | This removes high upfront capital cost barriers for residential and commercial end-users. |
| Integrate Smart Grid Capabilities | This enables demand-response participation, offering new revenue streams for system owners. |
| Acquire Specialized Component Manufacturers | This deepens supply chain control and mitigates component sourcing uncertainty for integrators. |
Research Approach
The analysis maps distinct renewable heating sub-sectors, each validated through extensive interviews with system integrators, component manufacturers, and utility planning officers. This approach combines primary insights from R&D directors, procurement specialists, and installation technicians with secondary data. Bottom-up and top-down triangulation ensures robust market sizing.
Assumptions regarding regulatory stability and raw material availability were held constant across the analysis window, while technology efficiency gains were varied. The analytical framework modeled segmentation dimensions including product type, end-user, technology, application, and regional policy frameworks. Compound Annual Growth Rates were derived from historical data and projected forward based on identified growth catalysts and market restraints, integrating inputs like refrigerant cost fluctuations.
Practitioners should monitor shifts in refrigerant regulations and skilled labor availability for early signals of market recalibration. Forecasts reflect a comprehensive set of assumptions, acknowledging potential impacts from macroeconomic volatility or unforeseen technological breakthroughs. Cross-checking against national energy agency reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Mexico Renewable Energy Market
Renewable Energy
Green Energy Lighting Market
Renewable Energy
Philippines Renewable Energy Market
Renewable Energy
Solar Tree Market
Renewable Energy
Renewable Energy in South America Market
Renewable Energy
China Wind Power Market
Renewable Energy
Malaysia Renewable Energy Market
Renewable Energy
Japan Renewable Energy Market
Renewable Energy
Republic of Ireland Renewable Energy Market
Renewable Energy
Solar District Heating Market
Renewable Energy
Renewable Energy Certificate Market
Renewable Energy
Global Green Energy Market
Renewable Energy
Solar Lighting System Market
Renewable Energy
Africa Solar E-Bike Market
Renewable Energy
Solar Floating Pool Lights Market
Renewable Energy
Tunisia Renewable Energy Market