
 Portugal Renewable Energy Market | 2026-2036
Portugal Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Portugal Renewable Energy Market Analytics
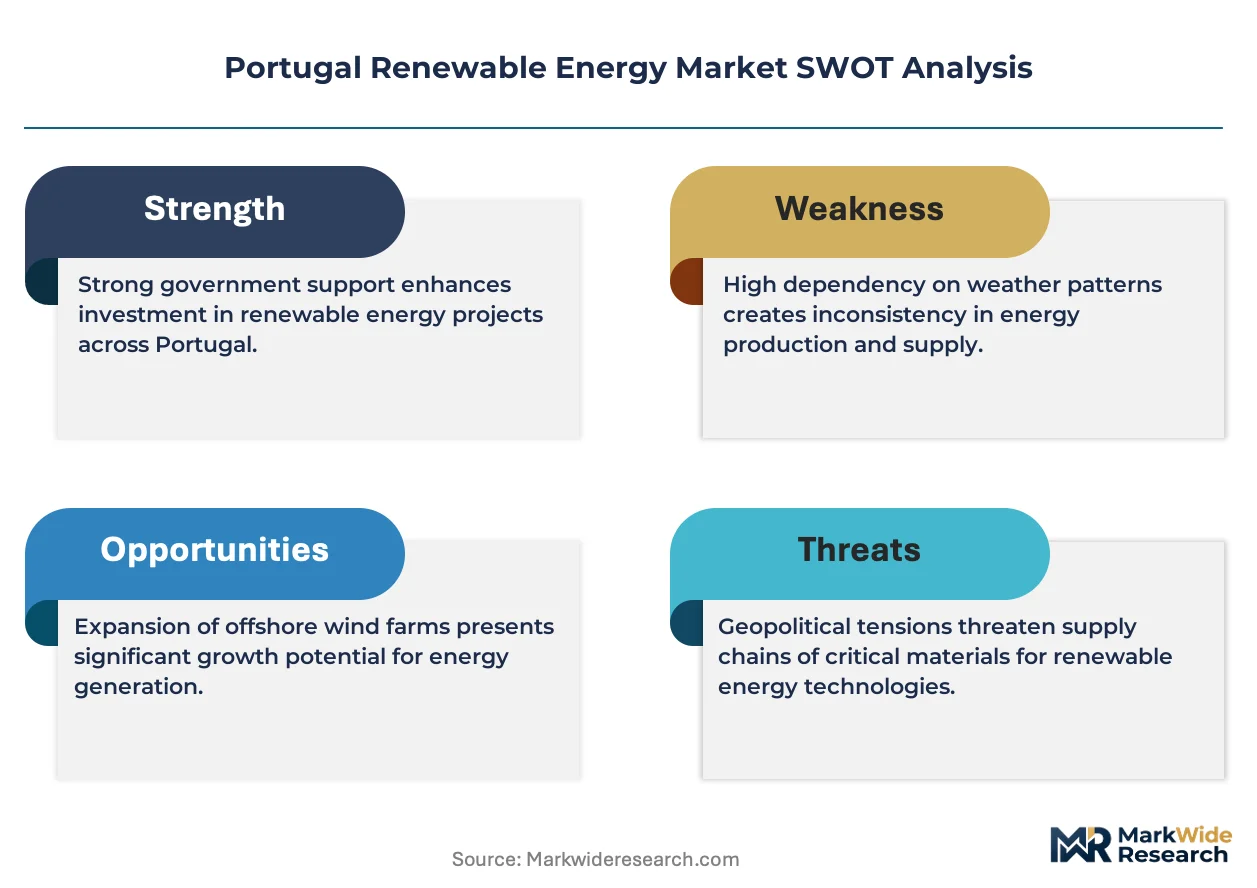
A capital-intensity divergence between offshore wind developers and distributed solar installers is reorganizing competitive hierarchy in Portugal's renewable sector. EDP Renováveis leverages its early-mover floating wind concessions to anchor project pipelines in deep-water zones. Iberdrola competes through integrated development capabilities spanning onshore wind and grid-scale solar. Galp Energia differentiates by repurposing downstream fuel retail infrastructure into EV charging and green hydrogen offtake nodes.
Portugal renewable energy encompasses electricity generation systems that harness solar irradiance, Atlantic wind regimes, biomass residues, and river hydrology to produce low-carbon power for grid injection or behind-the-meter consumption. Photovoltaic arrays typically deploy monocrystalline silicon modules with capacity factors of 15-18% in southern districts, while floating offshore wind platforms target 50+ meter water depths west of Viana do Castelo. Solar technology currently dominates installed capacity additions, though wind retains superior capacity factors and grid stability value. Industrial applications command the largest share of new offtake agreements as energy-intensive manufacturers seek fixed-price renewable supply to hedge volatile wholesale electricity markets. Utility-scale deployment channels absorb the majority of capital deployment, driven by auction mechanisms and bilateral power purchase contracts with grid operators.
Portugal's energy regulator ERSE administers feed-in tariff transitions and market premium auctions that determine project revenue certainty, while the Environmental Agency APA enforces biodiversity impact assessments for coastal wind developments. EU Green Deal alignment through the Recovery and Resilience Plan channels structural funds toward green hydrogen valleys and grid reinforcement. Stakeholders must monitor auction design evolution and cross-border interconnector capacity expansion to assess offtake risk and capture rate trajectories.
Market Dynamics
Floating offshore wind technology maturation is redirecting capital toward deeper Atlantic waters off Portugal's central and northern coasts, reorganizing competitive positioning between deep-water developers and distributed solar installers.
Growth Catalysts
- EU Green Deal alignment:The Recovery and Resilience Plan channels structural funds toward green hydrogen valleys and grid reinforcement, accelerating utility-scale project development.
- Industrial power procurement:Energy-intensive manufacturers in the Leiria-Aveiro corridor are executing bilateral power purchase contracts to hedge volatile wholesale electricity markets.
- Floating platform technology:Prototype deployments west of Viana do Castelo are validating 50+ meter water depth viability, unlocking previously inaccessible wind resources.
Market Restraints
- Grid interconnection bottlenecks:Transmission capacity constraints between generation clusters and demand centers limit project offtake certainty.
- Supply chain concentration:Floating platform component fabrication concentrates in specialized North Atlantic shipyards, creating procurement lead time risk.
- Biological impact assessment requirements:APA enforcement of biodiversity protocols for coastal wind developments extends permitting timelines.
Strategic Opportunities
- Green hydrogen valleys:Alentejo and Sines industrial zones offer offtake aggregation for electrolyzer-scale renewable power contracts.
- Port infrastructure repurposing:Aveiro and Figueira da Foz terminals are converting to floating wind assembly and maintenance hubs.
- Behind-the-meter solar:Commercial and industrial rooftops in Lisbon and Porto metropolitan areas remain underpenetrated relative to irradiance potential.
Industry Challenges
- Floating platform engineering expertise:Mooring system design and dynamic cable installation capabilities face acute talent scarcity.
- Cross-border interconnector coordination:Iberian electricity market coupling requires synchronized regulatory approvals across Portuguese and Spanish grid operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portugal Renewable Energy Market |
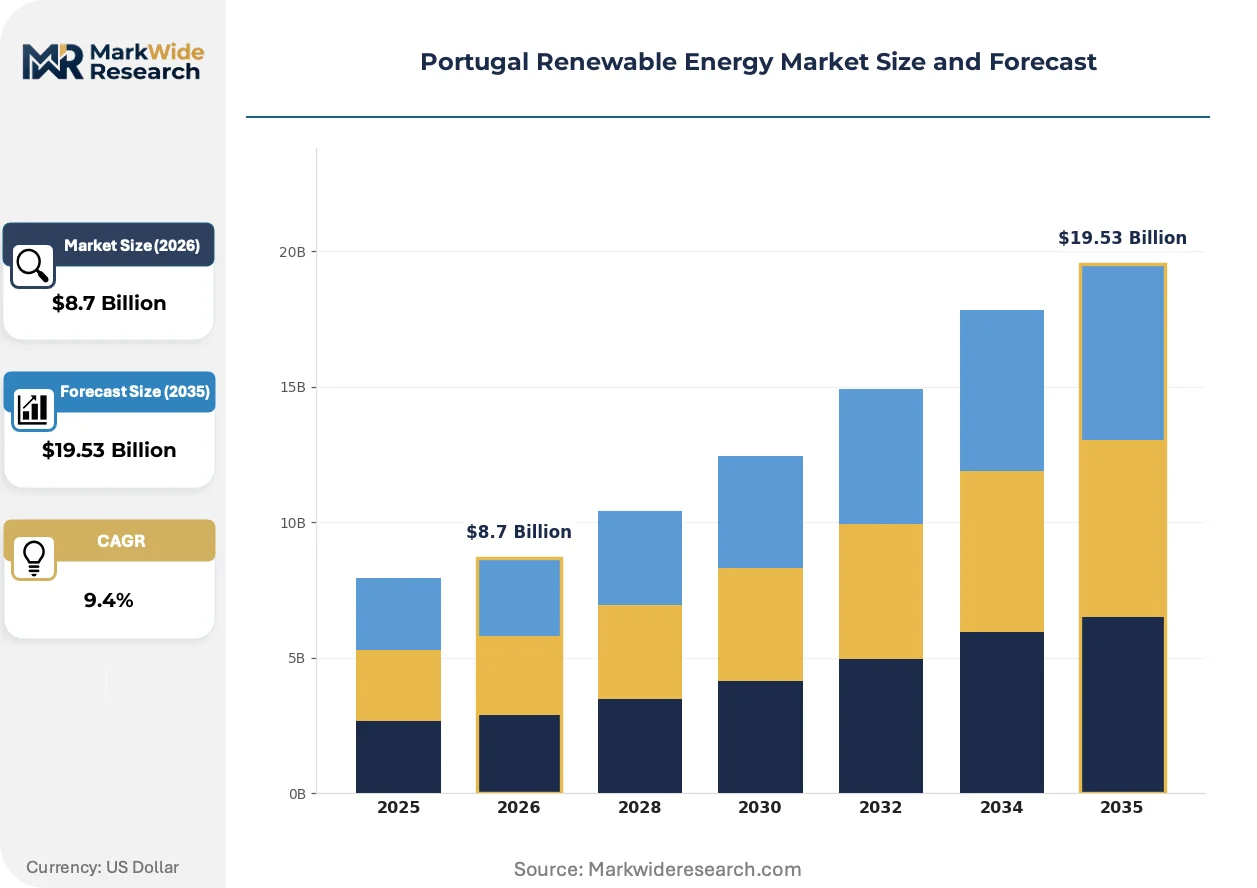
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Biomass, Hydropower Application: Residential, Commercial, Industrial, Utilities End User: Government, Corporations, Households, NGOs Distribution Channel: Direct Sales, Distributors, Online, Retail |
| Companies Covered | Acciona Energía, Aquila Clean Energy, Energias de Portugal (EDP Renováveis), Brookfield Renewable Partners, TotalEnergies (Total Eren), Iberdrola, Galp Energia, GE Vernova, Finerge, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portugal Renewable Energy Market Evolving Landscape
Technology convergence between floating offshore platforms and green hydrogen production is restructuring Portugal's renewable value chain, with capital allocation shifting from standalone generation assets to integrated energy systems.
Floating offshore wind platforms are decomposing the traditional fixed-bottom project model by enabling turbine deployment in 50+ meter water depths west of Viana do Castelo. EDP Renováveis and early-mover developers are securing concession blocks previously inaccessible to conventional monopile foundations. This technology is decomposing the geographic constraints that historically concentrated Atlantic wind development in shallow coastal strips, expanding addressable seabed area by an order of magnitude.
Portugal's National Energy and Climate Plan mandates auction-based market premiums replacing legacy feed-in tariffs, forcing developers to bid against wholesale price forecasts. ERSE-administered competitive tenders compress developer margins while accelerating capacity deployment timelines. Industrial offtakers in the ceramics, pulp, and chemicals sectors are responding by consolidating procurement into multi-year power purchase agreements to lock in price visibility.
Aggregated corporate procurement is displacing traditional utility-centric contracting as the dominant offtake mechanism for new renewable capacity. Large industrial consumers in the central coast manufacturing belt are forming buyer consortia to negotiate directly with project developers, bypassing incumbent retail suppliers. This pattern concentrates most visibly in the Leiria-Aveiro corridor, where grid interconnection capacity and port logistics infrastructure converge.
Portugal Renewable Energy Market Segmentation
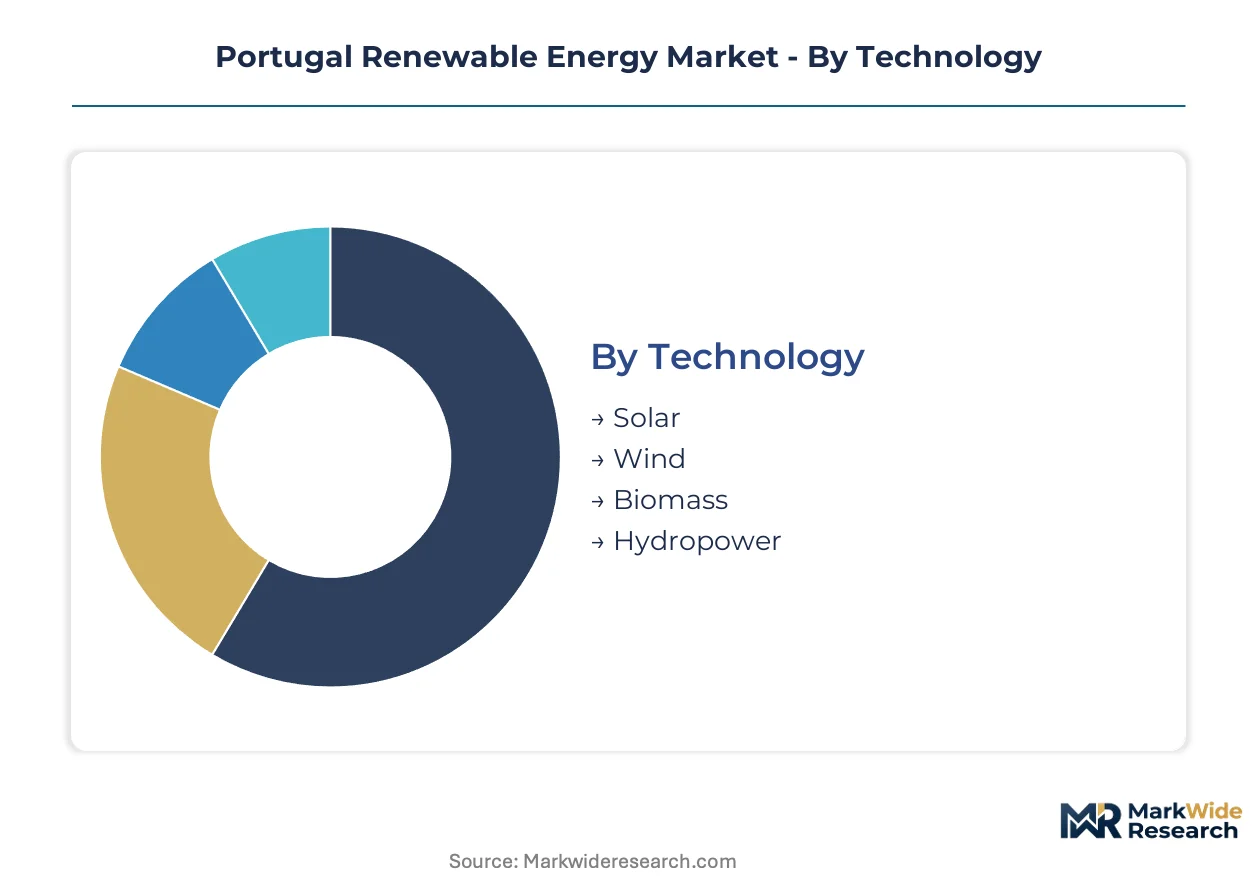
Technology substitution pressures are intensifying across Portugal's renewable mix as floating offshore wind disrupts established onshore wind economics and distributed solar challenges centralized generation models. Understanding segment boundaries reveals where capital reallocation and competitive repositioning concentrate.
Technology:
Wind and solar segments face the most acute substitution pressure as floating platforms displace fixed-bottom economics and photovoltaic costs undercut alternative clean sources.
- Solar:Monocrystalline silicon arrays dominate capacity additions with 15-18% capacity factors in Alentejo and Algarve districts. Industrial rooftops in Lisbon-Porto corridors and utility-scale auctions in southern regions concentrate procurement activity as developers exploit irradiance premiums and simplified permitting relative to coastal wind.
- Wind:Onshore installations retain grid stability advantages through superior capacity factors, while floating offshore prototypes west of Viana do Castelo validate 50+ meter depth viability. ERSE auction mechanisms favor wind where transmission infrastructure exists, though biological impact assessments extend APA permitting timelines.
- Biomass:Agricultural residue combustion and biogas recovery serve district heating networks in rural interior districts where grid extension costs outweigh renewable alternatives.
- Hydropower:Mature run-of-river installations provide baseload flexibility, with limited greenfield expansion constrained by environmental licensing and reservoir availability.
Solar retains volume leadership in annual capacity additions; floating offshore wind holds the steepest expansion curve as deep-water concessions unlock.
Application:
Cost tier stratification separates premium-priced behind-the-meter installations from auction-driven utility-scale deployments competing on wholesale market integration.
- Industrial:Energy-intensive ceramics, pulp, and chemicals manufacturers in Leiria-Aveiro belt execute bilateral power purchase agreements to hedge volatile wholesale markets. Corporate procurement consortia bypass incumbent retail suppliers, aggregating demand into direct developer negotiations.
- Utilities:Grid-scale projects absorb majority capital deployment through ERSE-administered competitive tenders and market premium auctions replacing legacy feed-in tariffs. Recovery and Resilience Plan structural funds accelerate transmission reinforcement and interconnector expansion.
- Commercial:Lisbon and Porto metropolitan rooftops remain underpenetrated relative to irradiance potential, with tenant-landlord split incentives constraining deployment velocity.
- Residential:Net metering schemes and building-integrated photovoltaics drive distributed adoption, though upfront capital requirements limit penetration in lower-income districts.
Utilities command installed capacity dominance; industrial applications are climbing fastest as procurement aggregation restructures offtake contracting.
End User:
Customer type fragmentation concentrates purchasing power among price-sensitive volume buyers while households face capital access barriers.
- Corporations:Large industrial consumers consolidate renewable procurement into multi-year contracts, leveraging creditworthiness to secure developer financing and lock in price visibility against wholesale volatility.
- Government:Public sector tenders for municipal buildings and infrastructure electrification align with National Energy and Climate Plan targets, though procurement cycles lag private sector velocity.
- Households:Distributed solar adoption concentrates in higher-income metropolitan districts where financing availability and roof ownership coincide.
- NGOs:Community energy cooperatives aggregate residential demand in rural municipalities, accessing collective self-consumption frameworks under recent regulatory reforms.
Corporations anchor contract volume; government procurement is expanding most quickly as EU fund absorption accelerates.
Distribution Channel:
Supply concentration in specialized fabrication and engineering services shapes channel economics, with direct relationships dominating capital-intensive segments.
- Direct Sales:Utility-scale and industrial offtake contracts route through developer-direct negotiations, bypassing intermediaries where project finance complexity requires bilateral structuring.
- Distributors:Equipment wholesalers serve commercial and residential installers with module inverters and balance-of-system components, consolidating procurement for fragmented downstream channels.
- Retail:Building materials and electrical supply chains offer standardized residential kits, though technical advisory gaps constrain customer conversion.
- Online:Digital platforms facilitate equipment comparison and financing aggregation for small-scale commercial and prosumer segments, with limited penetration in utility-scale contracting.
Direct sales dominate transaction value; online channels are gaining share fastest in residential equipment procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portugal's renewable energy trade balance tilts toward equipment imports, with floating platform components and photovoltaic modules sourced from specialized North Atlantic and Asian fabrication centers. Domestic project development concentrates capital deployment along the central coast, where port infrastructure and grid interconnection create competitive clustering. Regional differentiation follows seabed depth gradients, irradiance patterns, and industrial demand density.
Norte Region
Deep-water wind concessions west of Viana do Castelo anchor floating platform deployment, with 50+ meter depths unlocking previously inaccessible Atlantic resources. APA biodiversity assessments govern coastal permitting timelines, while Porto metropolitan demand drives grid reinforcement investments. The port of Leixões converts to floating wind assembly logistics, consolidating mooring system staging and dynamic cable handling.
Centro Region
Industrial ceramics and pulp manufacturers in the Leiria-Aveiro corridor execute bilateral power purchase agreements to hedge wholesale price volatility. ERSE-administered competitive tenders compress developer margins while accelerating capacity deployment. Aveiro port infrastructure repurposes for floating wind maintenance hubs, converging grid interconnection with maritime logistics.
Lisbon Metropolitan Area
Behind-the-meter solar penetration lags irradiance potential across commercial and industrial rooftops, constrained by tenant-landlord split incentives. Net metering schemes and building-integrated photovoltaics drive distributed adoption in higher-income districts. The capital's public sector tenders for municipal electrification align with National Energy and Climate Plan targets.
Alentejo
Utility-scale solar auctions concentrate in southern districts where 15-18% capacity factors and simplified permitting attract capital allocation. Green hydrogen valley development in Sines industrial zones offers electrolyzer-scale renewable offtake aggregation. Agricultural residue combustion serves district heating networks in rural interior municipalities.
Algarve
Monocrystalline silicon arrays exploit superior southern irradiance, with tourism sector electrification driving commercial rooftop deployment. Grid extension costs in dispersed coastal settlements favor distributed generation over centralized alternatives. Community energy cooperatives aggregate residential demand under collective self-consumption frameworks.
Portugal Renewable Energy Market Competitive Landscape
Concentration sits with integrated utility-scale developers holding concession portfolios and grid access rights. Early-mover floating wind specialists compete against distributed solar installers for capital allocation, with technology choice determining project finance structures. Two archetypes dominate: deep-water platform developers leveraging proprietary seabed data, and integrated energy groups bundling generation with hydrogen offtake. Competitive moves center on concession block accumulation and port infrastructure control.
Among Iberian integrated energy groups, EDP Renováveis and Iberdrola occupy positions spanning onshore wind, grid-scale solar, and emerging floating offshore platforms. Galp Energia represents the downstream repurposing archetype, converting fuel retail infrastructure into EV charging and green hydrogen nodes. Acciona Energía anchors the European specialist developer tier, competing through construction capabilities and operational asset management. These firms exemplify how geographic concession access and offtake contract structuring determine competitive hierarchy.
| Leading Market Players |
|---|
| Acciona Energía |
| Aquila Clean Energy |
| Energias de Portugal (EDP Renováveis) |
| Brookfield Renewable Partners |
| TotalEnergies (Total Eren) |
| Iberdrola |
| Galp Energia |
| GE Vernova |
| Finerge |
| Others |
Value Network & Pricing Analysis
ERSE-administered auction mechanisms gate both developer qualification and revenue certainty, compressing margins for late entrants while rewarding early-movers with secured offtake premiums. This regulatory architecture simultaneously shapes supply chain partner selection and price differentiation across project finance structures.
Pricing Analysis
Industrial OEM buyers anchor contract pricing through multi-year power purchase agreements that lock in fixed rates against wholesale volatility. Auction-based market premiums replace legacy feed-in tariffs, forcing developers to bid on wholesale price forecasts and compressing returns. Price differentiation rests on grid access priority and concession block location, with deep-water floating wind commanding financing premiums over distributed solar. Margins are tightening due to ERSE competitive tender intensity, while utilities prove least price-sensitive given balance sheet capacity to absorb regulatory risk.
Supply Chain Analysis
Port congestion at Leixões and container availability on Asia-Europe trade lanes elevate inbound logistics costs for photovoltaic module delivery. Component fabrication concentrates in China, South Korea, and specialized North Atlantic shipyards for floating platform assembly. Raw material dependencies span polysilicon ingots, high-grade steel for mooring systems, and dynamic submarine cables. Single-source vulnerability in floating platform engineering creates procurement lead time exposure. Distribution runs through direct developer-EPC relationships for utility-scale deployment, with equipment wholesalers serving fragmented commercial and residential channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acute talent scarcity in floating platform mooring design and dynamic cable installation constrains project execution velocity, filtering capital toward developers with captive engineering capabilities or established shipyard partnerships.
For Market Incumbents: Secure concession block accumulation in 50+ meter depth zones west of Viana do Castelo before APA permitting timelines extend further. Anchor grid interconnection rights at Aveiro and Figueira da Foz terminals to control floating wind assembly logistics. Backward integration into mooring system fabrication mitigates North Atlantic shipyard concentration risk. For New Entrants and Emerging Players: Differentiate on behind-the-meter solar deployment in Lisbon and Porto metropolitan corridors where tenant-landlord coordination failures have suppressed penetration. Target commercial rooftop aggregation through energy-as-a-service financing models that eliminate upfront capital barriers. Partner with municipal governments on public building electrification tenders aligned with National Energy and Climate Plan absorption targets. For Investors and Strategic Acquirers: EU Recovery and Resilience Plan fund disbursement milestones reshape the acquisition landscape by accelerating green hydrogen valley development timelines. Long-term viability centers on developers with integrated electrolyzer offtake positioning in Sines and Alentejo industrial zones. Target acquisition archetypes: floating wind specialists with proprietary seabed data portfolios. Monitor cross-border interconnector capacity expansion announcements as inflection indicators for Iberian electricity market coupling completion.| Strategic Initiative | Industry Significance |
|---|---|
| Floating Wind Concession Accumulation | Deep-water block control west of Viana do Castelo unlocks previously inaccessible Atlantic wind resources. |
| Port Infrastructure Repurposing | Aveiro terminal conversion to assembly hubs consolidates mooring staging and maintenance logistics. |
| Green Hydrogen Valley Integration | Sines electrolyzer-scale offtake aggregation secures long-term renewable power contract visibility. |
| Behind-the-Meter Solar Financing | Energy-as-a-service models bypass tenant-landlord split incentives in Lisbon-Porto metropolitan corridors. |
| Cross-Border Interconnector Coordination | Synchronized Portuguese-Spanish grid operator approvals enable Iberian electricity market coupling completion. |
Research Methodology
Cross-validation between developer pipeline disclosures and ERSE auction outcome records anchors the qualitative findings. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators combined with secondary validation against EDP Renováveis regulatory filings, IEA renewable energy reports, and APA environmental licensing databases. Bottom-up project capacity aggregation triangulates against top-down macroeconomic demand modeling.
Sensitivity analysis across auction price floor assumptions and interconnector capacity expansion timelines tests forecast robustness. Segmentation dimensions span technology type, application tier, end-user category, and distribution channel structure across the projection horizon. CAGRs derive from installed capacity buildout trajectories and offtake contract pricing evolution. Forecast inputs incorporate floating platform cost learning curves and green hydrogen electrolyzer scale-up economics.
The analysis sits within stated boundaries; outcomes outside sustained EU structural fund disbursement and APA permitting timeline stability would require recalibration. Forecasts reflect assumptions regarding technology maturation rates and cross-border regulatory synchronization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar Tree Market
Renewable Energy
Solar Floating Pool Lights Market
Renewable Energy
South Africa Wind Energy Market
Renewable Energy
North America Solar Tracker Market
Renewable Energy
Tunisia Renewable Energy Market
Renewable Energy
China Solar Photovoltaic Market
Renewable Energy
Ethiopia Renewable Energy Market
Renewable Energy
Philippines Renewable Energy Market
Renewable Energy
Biomethane Certificate Trading Platform Market
Renewable Energy
Solar Watch Market
Renewable Energy
East Africa Renewable Energy Market
Renewable Energy
Malaysia Renewable Energy Market
Renewable Energy
Solar Drying System Market
Renewable Energy
Wind Turbine Automation Market
Renewable Energy
Wind and Solar Hybrid Monitoring Systems Market
Renewable Energy
Ocean Energy Market